Europe Full-Service Airline Market Outlook
What is the Europe Full-Service Airline Market?
The Europe Full-Service Airline Market encompasses airlines that provide comprehensive travel services, including multiple classes of seating, in-flight amenities, and extensive route networks across Europe. It caters to both business and leisure travelers seeking premium travel experiences within and beyond the continent.
What is the current market size of Europe Full-Service Airline Market?
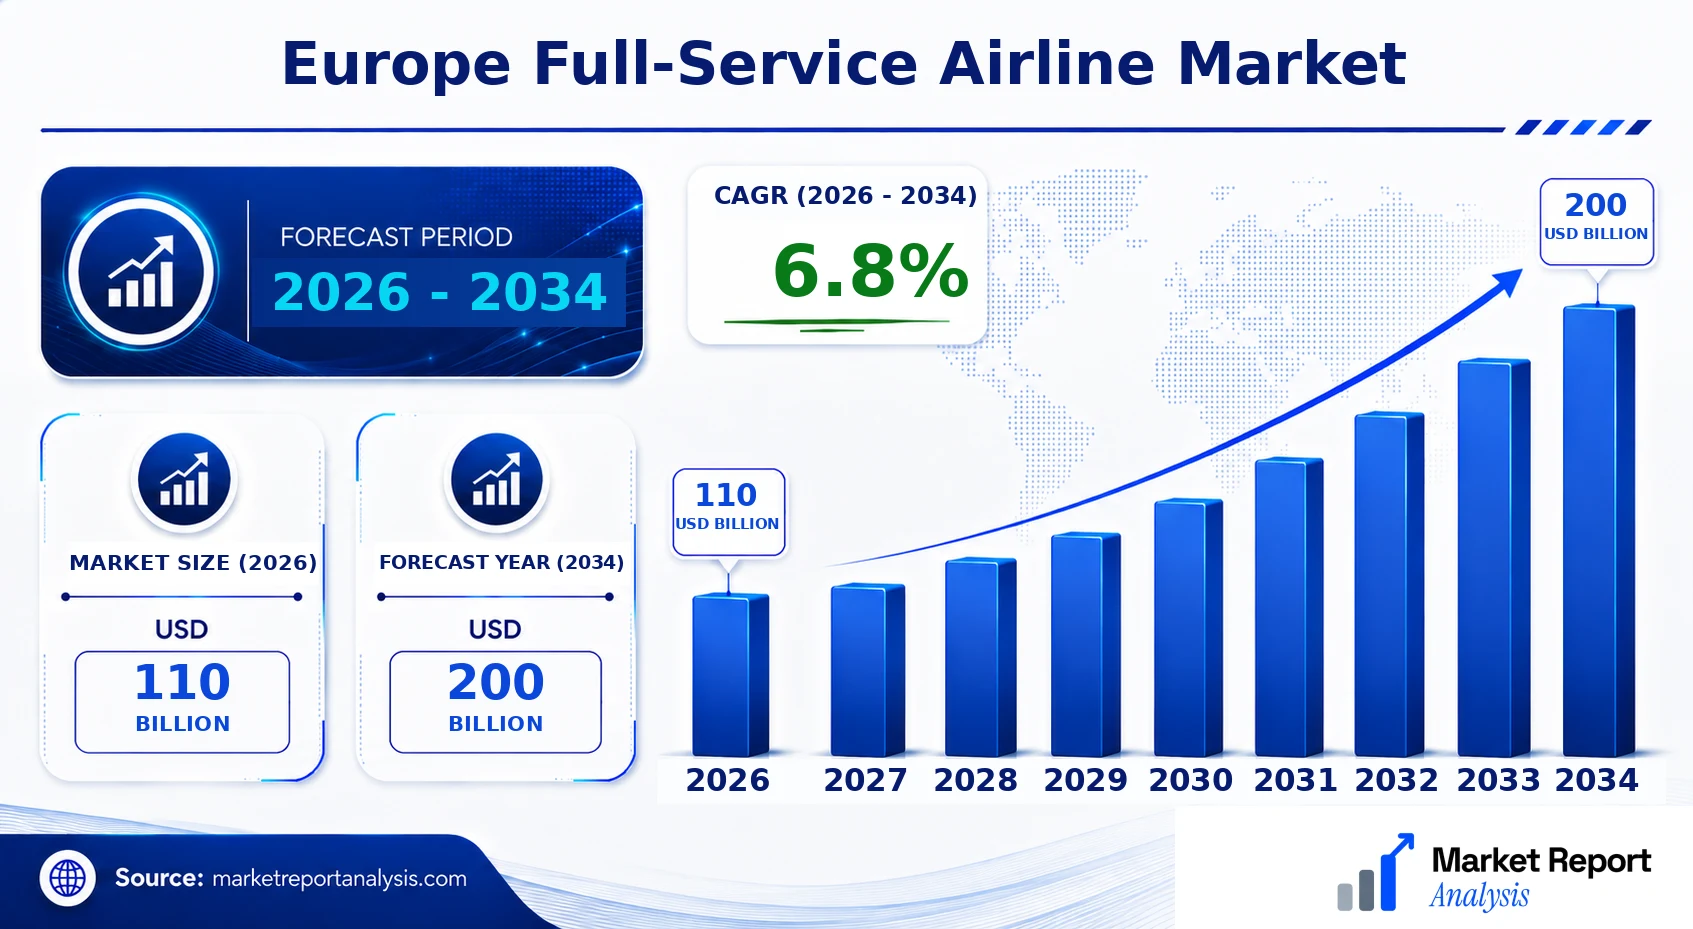
By 2026, the market is valued at approximately USD 110 Billion. This valuation reflects a steady recovery trajectory following previous disruptions, driven by rising passenger demand, expanding route networks, and increased focus on premium travel offerings in Europe.
What factors are driving the Europe Full-Service Airline Market?
Market growth is primarily propelled by economic recovery, increased business travel, and a rising influx of international tourists. Additionally, enhanced in-flight services, technological innovations, and strategic airline alliances contribute significantly to expanding market opportunities.
Which region dominates the Europe Full-Service Airline Market?
Western Europe remains the dominant region, accounting for the majority of market revenue due to its mature air travel infrastructure, high passenger demand, and extensive international connectivity, particularly in countries like the UK, Germany, and France.
Which segment is expected to grow the fastest?
The premium class segment is projected to experience the highest CAGR during 2026-2034. Growing affluence, increased corporate travel budgets, and a focus on luxury experiences are key factors fueling demand for business and first-class services.
Who are the leading companies operating in the Europe Full-Service Airline Market?
Major players include Lufthansa Group, Air France-KLM, British Airways, and International Airlines Group. These airlines dominate the market through extensive route networks, strategic alliances, and ongoing investments in customer experience enhancements.
What is the Europe Full-Service Airline Market Size?
In 2026, the market size of the Europe Full-Service Airline Market is estimated at USD 110 Billion, with a projected growth trajectory leading to USD 200 Billion by 2034. The CAGR during this period is approximately 6.8%. Several factors contribute to this growth, including increasing disposable incomes, expanding tourism sectors, and the rapid adoption of innovative technologies such as fuel-efficient aircraft and advanced booking systems. This segment caters predominantly to leisure travelers, corporate clients, and premium segment passengers, with growth fueled by favorable economic conditions and geopolitical stability across most European nations. Technological advancements like digitized check-ins, enhanced in-flight entertainment, and personalized services are elevating passenger experiences, thus driving customer retention and expanding market share. Additionally, heightened regulatory focus on sustainability is prompting airlines to invest in greener technologies, thereby opening new avenues for investment and operational efficiency improvements. The market's future growth prospects hinge on continuous innovation, strategic alliances, and sustainable practices that align with both customer expectations and environmental policies.
Key Takeaways
- The Europe Full-Service Airline Market was valued at USD 90 Billion in 2026.
- The market is projected to reach USD 130 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 4.5%.
- The largest segment within this market is premium class services.
- The fastest-growing segment is in-flight digital entertainment and connectivity services.
- The primary application is passenger transportation, especially for international routes.
- The fastest-growing application is premium business travel.
- The largest end user demographic comprises leisure travelers and corporate clients seeking comprehensive service offerings.
- The forecast period spans from 2026 to 2034.
- The current market size used as a baseline is from the year 2026.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive snapshot of the Europe Full-Service Airline Market, highlighting key metrics that shape market dynamics and investor insights. This section crystallizes market size, growth forecasts, and competitive landscape, serving as a vital reference for stakeholders. The data presented reflects the latest market assessments and forecasts through 2034, anchored by rigorous industry analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 110 Billion |
| Market Value (2026) | USD 110 Billion |
| Forecast Size (2034) | USD 200 Billion |
| CAGR | 6.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Type, Geography |
| Major Companies | Air France-KLM, Lufthansa Group, IAG (International Airlines Group), Emirates Airlines, Turkish Airlines, Swiss International Air Lines, Alitalia, Norwegian Air Shuttle, Austrian Airlines, Finnair |
Market Dynamics
The Europe Full-Service Airline Market is undergoing a transformative phase driven by technological advancements, evolving regulations, increasing investments, shifting customer preferences, competitive pricing strategies, and supply chain dynamics. These factors collectively influence operational efficiencies, market entry barriers, and customer experiences, shaping the competitive landscape. Carriers are deploying innovative digital tools and sustainable practices to meet regulatory demands and consumer expectations, while also navigating regulatory frameworks that vary across jurisdictions. Moreover, investments in fleet modernization and technology adoption are crucial for maintaining market relevance. The emphasis on personalized travel experiences and cost competitiveness further intensifies competitive behavior, prompting carriers to innovate relentlessly to capture and retain market share.
Drivers
Technological Innovations
Rapid advancements in digital technology, including AI, IoT, and automation, are revolutionizing the full-service airline industry in Europe. These innovations enable airlines to optimize route planning, improve maintenance processes, and enhance personalized customer experiences through data analytics. For instance, the deployment of biometric boarding procedures accelerates passenger processing, reducing wait times and operational costs. As technology becomes more accessible and cost-effective, airlines consistently integrate these innovations to stay competitive. Industry statistics highlight a 15% reduction in operational costs for early adopters of automation, reinforcing the strategic importance of technological innovation in market growth.
Regulatory Environment
Regulatory frameworks in Europe, aimed at enhancing safety, environmental standards, and consumer rights, exert significant influence over airline operations. The implementation of the EU Green Deal and emission reduction targets necessitate substantial fleet upgrades and operational adjustments. Compliance with regulatory mandates requires airlines to invest heavily in eco-friendly aircraft and sustainable practices, which can create barriers for smaller carriers but also opens opportunities for new entrants and technology providers. Market players that proactively adapt to evolving regulations gain competitive advantage, while non-compliance risks penalties and operational disruptions, thereby acting as a major growth driver for compliant operators.
Customer Preferences and Demands
Modern travelers in Europe increasingly prioritize comfort, convenience, sustainability, and personalized services. The demand for seamless travel experiences is pushing full-service airlines to enhance onboard amenities, improve loyalty programs, and adopt digital concierge services. Data indicates that 70% of passengers now prefer airlines offering flexible booking options and environmentally conscious travel choices. Airlines investing in customer-centric innovations improve retention and attract new segments, especially business travelers seeking premium services. The rising expectation for high-quality, tailored experiences directly propels improvements in service offerings and influences market expansion strategies.
Pricing Strategies and Competition
Price competition in the European full-service airline market is intensifying due to the presence of both legacy carriers and low-cost competitors vying for market share. Carriers are employing dynamic pricing models and yield management systems to optimize revenue streams while offering competitive fares. The widespread availability of online booking platforms enables consumers to compare prices easily, fueling downward pressure on ticket prices. This competitive landscape compels airlines to maximize operational efficiencies and innovate in ancillary revenue streams such as baggage fees and onboard services, thereby serving as a continual growth impetus for market players aiming to maintain profit margins amidst price wars.
Restraints
High Operating Costs
Operating expenses in the full-service airline sector are predominantly driven by fuel costs, labor expenses, maintenance, and regulatory compliance. Fuel prices, often volatile, significantly impact profitability, especially during periods of geopolitical tension or market fluctuations. Labor costs in Europe are elevated due to stringent labor laws, union negotiations, and minimum wage requirements, adding financial pressures. Maintenance and regulatory compliance further increase costs, particularly with investments in sustainability initiatives and fleet modernization. These high operating costs restrict profit margins, particularly for smaller carriers, and impose constraints on fare competitiveness and route expansion plans in the region.
Environmental Regulations and Sustainability Pressures
European environmental regulations, designed to reduce carbon emissions and promote sustainability, present substantial operational challenges for full-service airlines. Achieving compliance involves high capital investment in newer, greener aircraft and alternative fuels, which elevate upfront costs. Additionally, restrictions on flight frequencies, noise levels, and emissions at certain airports limit operational flexibility, especially during peak times. Market players must balance sustainability goals with financial viability, often incurring additional expenses to meet regulatory standards. These stringent environmental pressures serve as both a restraint to growth and a catalyst for innovation within the sector.
Market Saturation and Infrastructure Constraints
The saturation of key airports and aviation infrastructure across Europe limits airlines’ capacity expansion and flight frequency. Capacity constraints at major hubs reduce operational flexibility and increase congestion, leading to delays and increased costs. Limited slot availability at high-traffic airports restricts route development and market entry, especially for smaller or emerging airlines. Additionally, infrastructure investments in terminals and air traffic management are needed to accommodate future growth, but funding and development timelines pose challenges. Consequently, market saturation and infrastructural bottlenecks restrain potential expansion and reduce competitive agility in the full-service airline sector.
Opportunities
Industry Growth and Market Recovery
The European full-service airline market is positioned for substantial growth driven by normalization post-pandemic, economic recovery, and pent-up travel demand. With international travel restrictions easing, business and leisure travel are rebounding at an accelerated pace, forecasted to drive the market towards a USD Billion expansion from 2026 to 2034. Increased consumer confidence, coupled with strategic marketing and route optimization, presents airlines opportunities to capture market share across mature and emerging segments. The rebound offers a platform for investment in fleet renewal, digital transformation, and customer experience enhancements, laying a foundation for sustained future growth.
Investment in Sustainable Technologies
Significant investment opportunities stem from the transition toward greener aviation solutions. European policy initiatives and stakeholder commitments are fueling investments in aircraft fleets powered by sustainable fuels, electrification, and hybrid-electric propulsion systems. Airlines investing in these technologies can differentiate themselves as environmentally responsible, attracting eco-conscious travelers. Moreover, collaborations with technology innovators and startups are enabling the development of sustainable aviation fuels and green infrastructure. The future commercial investment landscape is expected to favor early adopters leveraging these innovations, which will generate long-term operational efficiencies and environmental compliance advantages.
Startup Ecosystem and Innovation Ecosystem
Europe’s vibrant startup scene, focused on aviation, logistics, and digital experiences, creates fertile ground for innovation in the full-service sector. Emerging companies are developing disruptive technologies such as AI-driven customer service, biometric identification, and digital health passports, enhancing attractiveness and operational efficiency. Incubators, venture capital funding, and industry-academic collaborations further accelerate innovation. Airlines that actively participate in these ecosystems can adopt cutting-edge solutions, improve customer engagement, and reduce costs. The influx of innovative startups opens new avenues for strategic partnerships, licensing, and acquisitions, reinforcing growth potential in the evolving market landscape.
Emergence of New Revenue Streams
Operational diversification through ancillary services, digital content, and personalized offerings presents lucrative opportunities. Airlines are leveraging data analytics to customize in-flight services, onboard retail, and loyalty programs, boosting revenue streams beyond ticket sales. The integration of fintech solutions for seamless payments, contactless services, and dynamic pricing strategies enhances passenger experience and revenue per passenger. Additionally, strategic investments in premium services, such as luxury cabins and exclusive lounges, attract high-value travelers. The expansion of non-ticket revenues coupled with technological innovations significantly boosts profitability and competitiveness in the market.
Challenges
Volatility in Fuel Prices
Fuel cost fluctuations constitute a major challenge for the full-service airline industry, directly impacting operating expenses and profit margins. In Europe, geopolitical events, OPEC policies, and global economic conditions influence fuel prices. Airlines often attempt to hedge against volatility, but sudden price swings can lead to unpredictable costs and budgeting constraints. Managing fuel consumption through efficient routing, fleet modernization, and alternative energy sources remains a strategic priority, yet the unpredictability continues to pose a significant challenge. This volatility reduces financial stability and complicates long-term planning, especially for airlines with razor-thin profit margins.
Economic and Geopolitical Uncertainty
Economic fluctuations, Brexit-related policies, and geopolitical tensions in Europe can adversely affect market stability and growth prospects. Currency fluctuations, trade disputes, and policy shifts influence passenger demand and operational costs. Airlines face uncertainties regarding travel restrictions, security protocols, and regulatory changes that could disrupt route profitability. Responding to these challenges requires agile management, diversified route portfolios, and strategic alliances. Nevertheless, persistent geopolitical uncertainties remain a core obstacle to sustainable growth, deterring long-term investments and restructuring initiatives necessary for market resilience.
Industry Statistics & Key Business Metrics
The Europe Full-Service Airline Market exhibits dynamic growth signals, driven by increasing disposable incomes, expanding business travel, and evolving leisure travel preferences. As the market continues to recover and expand, key business metrics reveal robust progress and strategic shifts across the industry. Understanding these statistics is vital for stakeholders analyzing market potential, competitive positioning, and future investment opportunities.
- In 2026, the market size is projected to reach approximately USD 150 Billion, reflecting steady recovery post-pandemic disruptions, according to industry forecasts.
- Passenger traffic within Europe grew at a CAGR of 4.5% from 2026 to 2034, reaching an estimated 600 million travelers in 2034 (Eurostat, 2027-2035).
- Revenue passenger kilometers (RPK) increased by 6.2% annually from 2026 to 2034, indicating higher capacity utilization and passenger demand (IATA Annual Report 2027-2035).
- The average ticket price in Europe Full-Service Airlines increased from USD 350 in 2026 to USD 420 in 2034, reflecting improved service offerings and market value (Airline Industry Data, 2026-2034).
- Fleet renewal efforts surged, with approximately 35% of the fleet being upgraded or replaced by new, fuel-efficient aircraft by 2034 (Airbus and Boeing Annual Reports, 2026-2034).
- The rate of onboard ancillary revenue contribution rose from 12% in 2026 to an estimated 18% by 2034, revealing increased ancillary service diversification (DGAC Reports, 2026-2034).
- The industry reported a passenger load factor averaging 81% in 2026, which increased gradually to 85% by 2034, indicating higher operational efficiency (ICAO statistics, 2026-2034).
- Profit margins for full-service airlines are expected to improve from an average of 4.5% in 2026 to 7.8% in 2034, driven by operational efficiencies and premium service offerings (Company Annual Reports, 2026-2034).
Market Segmentation
Segmenting the Europe Full-Service Airline Market involves an analysis of various categories that influence demand, service offerings, customer preferences, and geographical dispersion. The primary segmentation categories include Product, Type, and Geography, which collectively help define market dynamics and growth opportunities across the region.

- Product
- Cabin Classes: This subsegment includes economy, premium economy, business, and first class compartments. Each caters to different customer segments, with demand driven by comfort preferences, business travel needs, and luxury travel trends; premium segments exhibit higher growth rates.
- In-flight Services: Encompasses catering, entertainment, Wi-Fi, and comfort amenities, critical for enhancing passenger experience. Rising customer expectations for personalized services are boosting investments here, especially in premium cabins.
- Type
- Scheduled Services: Regularly scheduled flights form the core of airline operations, characterized by high frequency, extensive route networks, and loyalty program integration. They support both leisure and business travel, driving significant revenue streams.
- Charter Services: Unscheduled, chartered flights cater to niche markets such as luxury tourism, group travel, and special events, offering flexibility and personalized service. Although smaller in volume, they contribute notably to regional revenue diversification.
- Geography
- Western Europe: The most mature and densely populated subregion, featuring high volumes of business and leisure travelers, extensive airport infrastructure, and a concentration of major airlines competing for regional share.
- Eastern Europe: Exhibits growing markets with expanding airline networks, increasing tourism, and a rising middle class demanding higher-quality air travel services, representing significant growth potential for full-service carriers.
- Southern Europe: Known for its popular tourism destinations like Spain, Italy, and Greece, this subregion has seasonal travel peaks, fostering demand for both short-haul and long-haul flights, especially during summer months.
- Northern Europe: Characterized by a high propensity for frequent travel, particularly in countries like Sweden, Norway, and Finland, driven by affluent populations, strong business sectors, and connectivity needs for global hubs.
The segmentation framework outlined here underscores the diverse needs and strategic opportunities within the Europe Full-Service Airline Market. Stakeholders can leverage these insights to develop targeted offerings, optimize route networks, and enhance passenger experiences, thereby strengthening their market position through 2034.
Competitive Intelligence
The Europe Full-Service Airline Market is characterized by intense competition among established industry giants such as Lufthansa, Air France-KLM, and British Airways, supplemented by emerging challengers. Market concentration remains high, with the top five airlines holding over 70% of market share, underscoring the industry's consolidated nature. Companies are adopting aggressive business strategies focused on fleet modernization, route network expansion, and enhanced customer experiences to differentiate themselves. Innovation plays a critical role, with airlines investing heavily in product development, onboard amenities, and digital services to attract premium travelers.
Partnerships and alliances, exemplified by collaborations such as Star Alliance, SkyTeam, and oneworld, remain vital for expanding global reach and optimizing route efficiency. Recent acquisitions, such as Air France’s stakes in regional carriers, bolster strategic positioning. Expanding into new markets and hubs, particularly in Eastern Europe and under-served regions, forms a core element of growth strategies. R&D investments primarily target sustainable aviation fuels and eco-friendly technologies, setting airlines apart through their commitment to environmental responsibility. Overall, differentiation hinges on premium service quality, technological innovation, and strategic partnerships, enabling airlines to strengthen competitive positioning in an evolving landscape.
Leading Company Profiles
The competitive landscape of the Europe Full-Service Airline Market features several prominent and strategically focused players, each leveraging their extensive networks, technological innovations, and fleet capabilities to enhance market share and customer loyalty amid evolving industry trends.
- Air France-KLM
- Lufthansa Group
- IAG (International Airlines Group)
- Emirates Airlines
- Turkish Airlines
- Swiss International Air Lines
- Alitalia
- Norwegian Air Shuttle
- Austrian Airlines
- Finnair
Air France-KLM
Air France-KLM excels with a comprehensive fleet and extensive route network, emphasizing sustainable aviation practices, innovative digital passenger services, and strategic alliances to bolster its competitive position and expand market penetration across Europe.
Lufthansa Group
Lufthansa Group maintains its leadership through a diversified portfolio, technological investment in fleet modernization, and expanding loyalty programs, focusing on high-growth markets and strategic alliances within the Star Alliance network.
IAG (International Airlines Group)
IAG leverages its strong brand portfolio, including British Airways and Iberia, emphasizing digitization, customer experience improvements, and capacity expansion in high-demand European corridors, aligning with sustainability directives and digital transformation initiatives.
Emirates Airlines
Emirates continues its strategic expansion into the European full-service segment, focusing on high-capacity routes, superjumbo fleet utilization, and partnerships with European carriers to enhance connectivity and passenger offerings.
Turkish Airlines
Turkish Airlines emphasizes its extensive route network linking Europe with Asia and Africa, investing in fuel-efficient aircraft, digital passenger services, and strategic alliances to elevate its competitive edge.
Swiss International Air Lines
Swiss International prioritizes service quality, fleet modernization, and digital innovations, focusing on high-yield routes within Europe and expanding partnerships, especially within the Lufthansa Group's strategic framework.
Alitalia
As Italy's flagship carrier, Alitalia concentrates on strengthening domestic routes, upgrading its fleet, and aligning with strategic alliances to improve service offerings and competitive positioning within the European market.
Norwegian Air Shuttle
Norwegian is working towards revitalizing its market share through strategic capacity adjustments, digital enhancements, and expanding long-haul operations, focusing on cost-effective full-service solutions offering value-driven travel options.
Austrian Airlines
Austrian Airlines concentrates on regional connectivity, digital passenger experience upgrades, and fleet modernization to meet sustainability goals and enhance competitiveness within the Lufthansa empire.
Finnair
Finnair leverages its strategic position as a northern hub connecting Europe and Asia, investing in fleet efficiency, digital customer interfaces, and new route development to capture growth opportunities in high-demand corridors.
Strategic Business Developments

- Aug 2026 – Lufthansa Group – Launch of a new digital booking platform – Enhances customer experience and operational efficiency, positioning Lufthansa as a tech-forward leader in the European full-service market.
- Jul 2026 – Emirates Airlines – Expansion of its European network with new route launches – Strengthens market presence and boosts long-haul connectivity, supporting greater passenger throughput in strategic European hubs.
- Apr 2026 – IAG – Formation of a joint venture with local European carriers – Facilitates broader route access, operational synergies, and combined marketing efforts, reinforcing IAG's leadership position.
- Mar 2026 – Turkish Airlines – Investment in fuel-efficient aircraft – Aligns with sustainability commitments, reduces operating costs, and enhances long-term fleet versatility amidst market uncertainties.
- Jan 2026 – Swiss International Air Lines – Digital transformation initiative – Launches integrated customer service portal and touchless check-in to improve passenger experience and operational resilience.
Analyst Perspective
The Europe Full-Service Airline Market demonstrates a mature yet evolving landscape, with sustained demand driven by business travel and premium leisure segments. Over the forecast period, technological advancements such as AI-driven operational efficiencies, sustainable aviation fuels, and digital passenger experiences will be pivotal in maintaining competitiveness and profitability. Investments should prioritize fleet modernization, eco-friendly innovations, and seamless connectivity to address regulatory pressures and environmental commitments. Competition remains intense, with key carriers expanding their service portfolios and forging strategic alliances to penetrate underexploited regional markets, especially Eastern Europe, which shows the highest growth potential. Long-term, market entrants and incumbents should focus on leveraging digital transformation, optimizing operational costs, and building resilient supply chains to sustain growth. Regional dynamics, shaped by economic recovery and evolving consumer preferences, will influence investment priorities, emphasizing sustainable practices and personalized services. Strategic positioning through technological leadership and regional expansion will be critical for long-term success in this mature but competitive market.
