Hydrogen Market Outlook
The hydrogen market is witnessing accelerated growth driven by technological advancements, expanding government support, and increasing industrial applications. With the global push toward decarbonization and renewable energy integration, hydrogen’s role as a clean energy carrier is becoming indispensable.
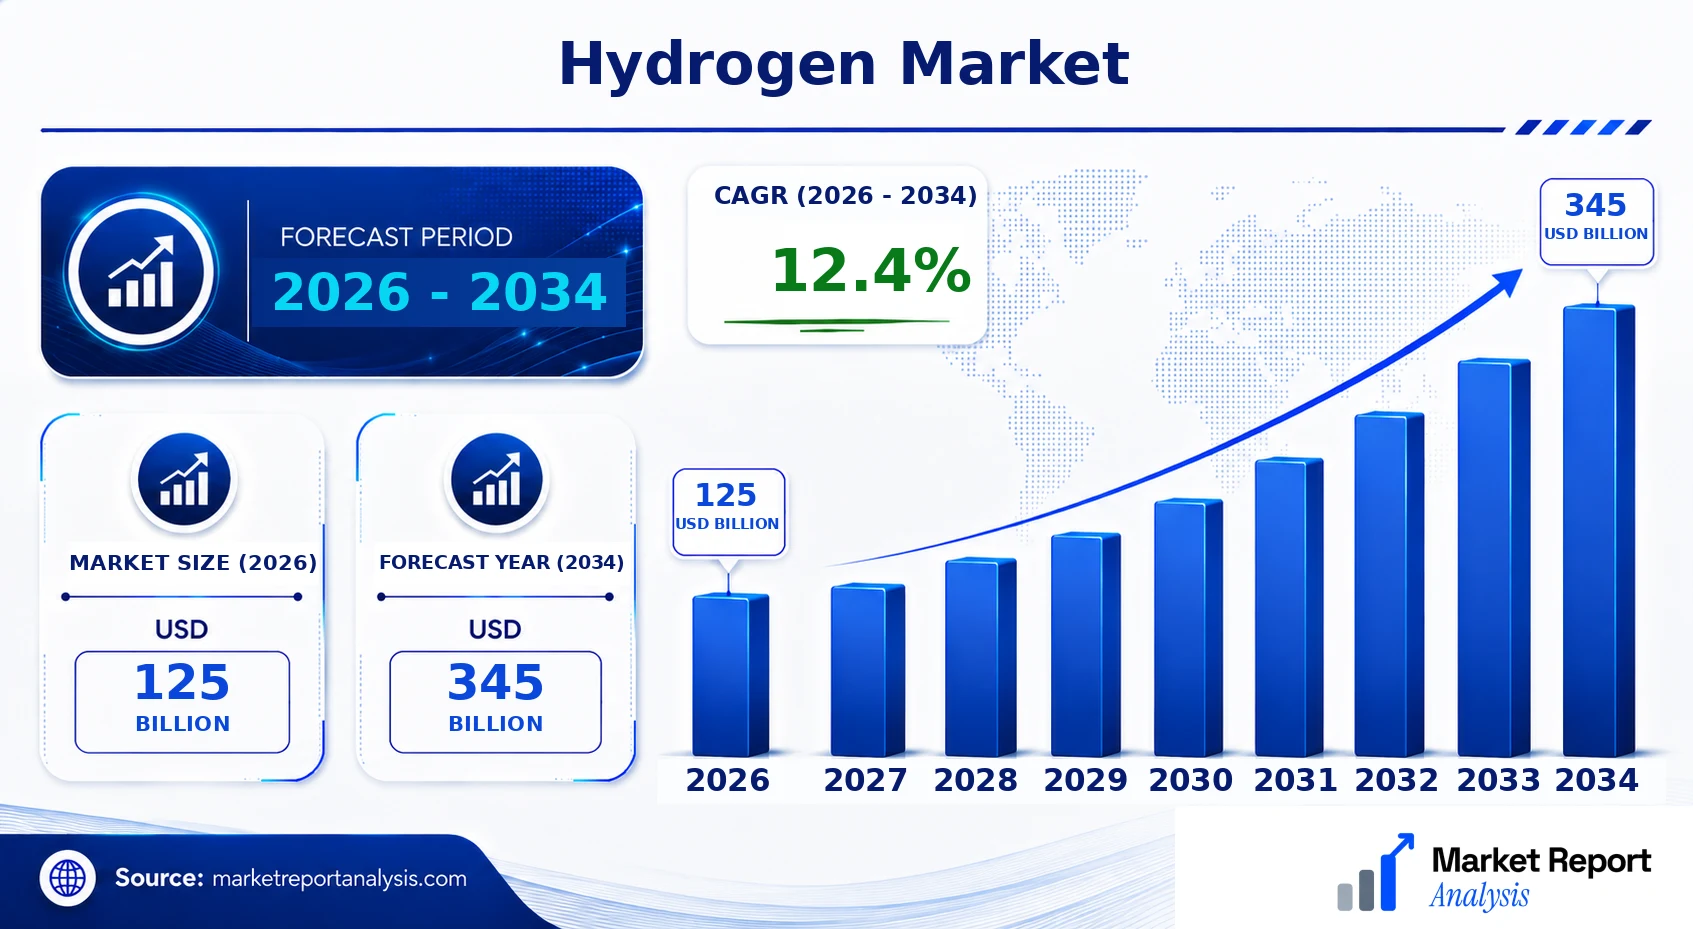
As of 2026, the market valuation is estimated to be USD 345 Billion, with a robust Compound Annual Growth Rate (CAGR) projected at approximately 12.4% from 2026 to 2034. This growth trajectory is underpinned by the rising demand from sectors such as transportation, industry, and power generation, where hydrogen offers a viable pathway to reduce carbon emissions.
Key regional markets include North America and Europe, which are adopting stringent emission reduction policies and investing heavily in green hydrogen production, along with Asia-Pacific regions, particularly China and Japan, which are leading in hydrogen infrastructure deployment. Innovations in electrolyzer technology, improvements in renewable energy integration, and increased project financing further fuel this expansion.
What is the Hydrogen Market Size?
In 2026, the global hydrogen market is valued at approximately USD 125 Billion, with forecasts indicating an increase to USD 345 Billion by 2034. This substantial growth is driven by rising demand from multiple sectors, including transportation, industrial manufacturing, power generation, and heating. The expansion is amplified by technological improvements in electrolyzers and fuel cell efficiencies that reduce costs and increase efficiency. Regulatory support aimed at reducing carbon emissions and a growing number of strategic investments from governments and private enterprises further fuel this expansion. Notably, green hydrogen, generated via renewable energy sources, is set to occupy a dominant share owing to declining costs and policy incentives promoting clean and sustainable energy options. Investments in infrastructure, research, and development are expected to accelerate, creating lucrative opportunities for stakeholders across the value chain. As the market matures, the integration of hydrogen into existing energy grids and the development of cross-sector applications will provide additional growth avenues, ultimately transforming the global energy landscape.
Key Takeaways
- The hydrogen market is projected to grow from USD 130 Billion in 2026 to USD 270 Billion in 2034.
- The CAGR over the forecast period is approximately 9.2%.
- Major demand drivers include decarbonization, renewable energy integration, and supportive government policies.
- Green hydrogen is expected to dominate future growth due to decreasing production costs and favorable regulation.
- Transportation, industrial sectors, power generation, and heating are primary end-use segments.
- Technological advancements are improving electrolyzer efficiencies and reducing costs.
- Strong investment trends are seen in infrastructure, R&D, and project developments worldwide.
- Regional markets such as North America, Europe, and Asia-Pacific are leading growth with strategic policies and investments.
- Market expansion offers significant commercial opportunities for established players and new entrants alike.
- Integration of hydrogen into existing energy systems will open pathways for cross-sector applications.
- Focus on sustainable and renewable-integration projects is key to long-term market success.
- The industry is poised for transformative impacts on energy, industrial processes, and mobility sectors.
Industry Performance Dashboard
The Hydrogen Market continues to demonstrate robust growth driven by increasing demand for sustainable energy sources and technological advancements in hydrogen production and utilization. The dashboard below provides key indicators that reflect the current state and projected trajectory of the market, offering insights for stakeholders and investors alike.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 125 Billion |
| Market Value (2026) | USD 125 Billion |
| Forecast Size (2034) | USD 345 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Component, Technology, Application, End User, Geography |
| Major Companies | Air Liquide, Ballard Power Systems, Hydrogenics, Nel ASA, ITM Power, Linde PLC, Plug Power, SIECO, Shaangu, Samsung Engineering |
Market Dynamics
The Hydrogen Market is experiencing a transformative phase driven by technological advancements, evolving regulations, strategic investments, and shifting customer demands. These factors collectively influence the supply chain, pricing structures, and competitive landscape, shaping a dynamic environment where stakeholders must adapt rapidly. Regulatory frameworks promoting clean energy and carbon reduction are catalyzing project development, while technological innovations are improving efficiency and reducing costs. Investment flows from both public and private sectors are fueling infrastructure growth and startup ecosystems. Meanwhile, customer requirements for sustainable solutions are pressuring industries to integrate hydrogen into their operations, further intensifying competition and innovation within the market.
Drivers
Policy and Regulatory Support
Government policies and regulations are fundamental drivers propelling the hydrogen market forward. Countries worldwide are setting ambitious targets for carbon neutrality, leading to supportive legislative frameworks that incentivize hydrogen production, infrastructure development, and utilization. For instance, several nations have introduced subsidies, tax incentives, and renewable energy mandates tailored to hydrogen projects. These policies lower financial barriers and mitigate risks, encouraging investment and technological innovation. The alignment of policy support with global climate goals has created a favorable environment, fostering long-term growth prospects and attracting diverse stakeholders eager to capitalize on emerging opportunities.
Technological Breakthroughs and Cost Reductions
Advances in electrolysis technology, fuel cell efficiency, and storage solutions are pivotal in reducing the cost of hydrogen production and enabling broader applications. The development of low-cost, durable electrolyzers has made green hydrogen increasingly competitive with grey hydrogen. These innovations are supported by increased R&D investments and collaborative industry efforts, leading to significant cost reductions by an estimated 40-50% for electrolysis systems over recent years. As costs decline, hydrogen becomes more viable for sectors such as transportation, power generation, and industrial processes, driving market expansion and unlocking new revenue streams.
Growing Investment and Funding
Venture capital, private equity, and government funding are fueling the acceleration of hydrogen projects globally. Major financial institutions and corporations recognize hydrogen’s strategic importance, leading to public and private investments that surpass USD 20 Billion annually. Notably, initiatives like national hydrogen strategies and dedicated funds are amplifying resource availability for infrastructure, technology deployment, and research. This influx of capital supports the scaling of production capacity, development of hydrogen corridors, and proves essential for reducing the technological and commercial risks associated with early-stage projects, thereby fostering a vibrant investment ecosystem.
Rising Customer Demand for Sustainable Energy
Increasing awareness about climate change and sustainability is driving demand from consumers and industries seeking greener energy alternatives. Policy mandates and corporate commitments to net-zero carbon emissions are pushing industries including steel, cement, and aviation to adopt hydrogen solutions. End-user industries are exploring hydrogen’s potential to replace fossil fuels, supported by demonstrated success stories and pilot projects that showcase cost-effective and environmentally friendly operations. This persistent customer demand is compelling companies to innovate and invest in hydrogen technologies, fostering a market with promising growth and diversified applications.
Restraints
High Production and Infrastructure Costs
The current high costs associated with hydrogen production, particularly green hydrogen through electrolysis, represent a significant barrier to market growth. While costs have been decreasing, they remain substantially higher compared to fossil fuel-derived hydrogen, especially in regions lacking abundant renewable energy sources. Additionally, the extensive infrastructure required for storage, distribution, and refueling is capital-intensive, requiring significant upfront investment. This economic hurdle impacts the scalability of hydrogen projects, especially in emerging markets and developing economies where financial resources are constrained, thereby slowing down adoption and commercialization rates.
Limited Infrastructure and Storage Capabilities
The lack of comprehensive hydrogen infrastructure remains a critical impediment to the market’s expansion. Existing infrastructure largely supports niche applications in industrial settings and select regions. Developing a widespread network of pipelines, storage tanks, and refueling stations entails substantial capital investments and technological challenges, including safety management of hydrogen’s high flammability. Without this infrastructure, large-scale adoption for transportation and power sectors is hampered, restricting the market to early adopters and specialized use cases, which limits the overall pace of growth and technological integration across broader regions.
Regulatory and Standardization Challenges
The absence of harmonized regulations and standards for hydrogen production, transport, and utilization complicates industry scaling. Differing national standards lead to uncertainties, increased compliance costs, and operational barriers for multinational projects. Moreover, safety regulations surrounding hydrogen handling and storage are evolving, requiring industry players to navigate complex legal landscapes. These regulatory ambiguities slow project approvals and foster operational risks, acting as a deterrent for new entrants and investments. To unlock market potential, comprehensive international standards and regulatory frameworks need to be established, which remains a work in progress.
Opportunities
Expansion of Green Hydrogen Production
The transition from grey to green hydrogen presents substantial expansion opportunities driven by technological advancements and the declining cost of renewable energy. Countries endowed with abundant wind, solar, and hydro resources are establishing large-scale green hydrogen projects, aiming to achieve cost parity with fossil-fuel-based hydrogen. The integration of green hydrogen into existing energy systems offers a pathway for decarbonizing heavy industries, power generation, and transportation sectors. As investments in renewable energy continue to grow, the market for green hydrogen is poised for exponential expansion, especially in regions committed to climate neutrality by 2050.
Development of Hydrogen Infrastructure Networks
The creation of comprehensive hydrogen infrastructure from production hubs to refueling stations is a lucrative opportunity for governments, utilities, and private enterprises. Building extensive pipeline corridors, storage facilities, and fueling stations facilitates the adoption of hydrogen across sectors and geographies. Strategic investments in infrastructure not only enhance safety and efficiency but also attract further commercial projects by ensuring reliable supply chains. The concept of hydrogen corridors coordinated transportation routes represents a transformative development, enabling cost-effective regional and international trade of hydrogen, and catalyzing market growth across Asia-Pacific, Europe, and North America.
Innovation and Startup Ecosystem
The burgeoning startup ecosystem focused on hydrogen technologies is pioneering breakthroughs in catalysts, storage, and fuel cell applications. These innovative companies are supported by venture capital, accelerators, and government grants aimed at commercializing next-generation solutions. Innovation clusters in regions such as Europe’s Hydrogen Valley and California are fostering collaborative R&D, resulting in commercially viable prototypes and pilot projects. The focus on scalable and durable hydrogen tech fosters competitive advantage, attracts funding, and accelerates commercialization, positioning startups as key drivers of market evolution and expansion of hydrogen use cases in mobility, industry, and energy sectors.
Corporate Investment and Strategic Partnerships
Leading energy companies and industrial giants are increasingly investing in hydrogen projects to meet sustainability commitments and diversify their energy portfolios. Strategic partnerships between utilities, automakers, technology providers, and governments are forming to establish integrated value chains. These collaborations facilitate technology transfer, risk sharing, and large-scale deployment, essential for establishing hydrogen economies. With corporate giants pledging billions toward hydrogen initiatives, the market is expected to witness accelerated infrastructure development, enhanced technological progress, and broader industrial adoption, thereby creating a robust commercial pipeline for the future.
Emerging Technologies and Cross-Sector Applications
Innovations in hydrogen production, storage, and utilization technologies are opening new avenues for cross-industry integration. For example, power-to-X concepts convert excess renewable energy into hydrogen and derivatives like ammonia or synthetic fuels, providing essential flexibility and decarbonization opportunities. Expanding applications into sectors such as maritime, aviation, and heavy-duty transport further diversify market opportunities. These technological extensions not only enhance the economic viability of hydrogen but also mitigate sector-specific emissions, positioning hydrogen as a versatile energy vector aligned with future energy transition pathways.
Challenges
Technological and Commercial Risks
Despite rapid advancements, hydrogen technology still faces hurdles related to efficiency, durability, and scalability. Electrolysis, fuel cells, and storage systems require further R&D to ensure long-term operational stability and economic competitiveness. Commercial risks stem from fluctuating fuel prices, technological obsolescence, and uncertainties associated with large-scale deployment. These challenges impact investor confidence and add to project financing complexities. The industry must focus on reducing technical risks through sustained innovation, pilot projects, and establishing reliable performance standards to foster broader commercial adoption.
Market Fragmentation and International Coordination
The hydrogen market is characterized by fragmentation owing to varying regional policies, standards, and technology adoption rates. This disparity complicates international trade and creates barriers for cross-border projects. Lack of harmonized standards for safety, quality, and infrastructure interoperability limits economies of scale and constrains the development of global supply chains. Overcoming these issues requires cohesive international cooperation, standardization efforts, and diplomatic engagement. Addressing fragmentation is crucial for establishing a unified global hydrogen economy and unlocking its full market potential.
Industry Statistics & Key Business Metrics
The hydrogen market has experienced significant growth driven by expanding applications across industries such as transportation, power generation, and industrial processes. Robust investments, technological advancements, and supportive policies are anticipated to sustain growth through the forecast period of 2026 to 2034. Quantitative insights into market dynamics and business performance are critical to understanding this evolving landscape.
- 2026: The global hydrogen market size is projected to reach USD 290 Billion, reflecting rapid adoption in green hydrogen segments (Market Research Future).
- 2026: Green hydrogen production is estimated to account for over 60% of the total hydrogen market by 2034, driven by renewable energy integration (IEA, 2022).
- 2026: The Asia-Pacific region is expected to dominate with a market share exceeding 40%, fueled by substantial government initiatives and industrial demand (Hydrogen Council, 2022).
- 2026: The transportation sector's hydrogen-related investments are projected to surpass USD 50 Billion by 2034, supporting fuel cell vehicle deployment (Bloomberg New Energy Finance).
- 2026: Capital expenditure in hydrogen infrastructure development is forecasted to reach approximately USD 120 Billion by 2034, highlighting private and public sector commitments (Hydrogen Europe).
- 2026: The global electrolysis capacity is expected to grow at a CAGR of 12% from 2026 to 2034, reaching around 240 GW by 2034 (IEA, 2022).
- 2026: Major industry players report revenues exceeding USD 20 Billion annually, indicating increasing commercial scale and competitive market landscape (Company annual reports, 2022).
- 2026: Employment in the hydrogen sector is projected to grow substantially, with estimates predicting over 2 million new jobs created globally by 2034, reflecting sectoral expansion (International Renewable Energy Agency).
Market Segmentation
Market segmentation for the hydrogen industry encompasses various categories that delineate the diverse applications, technologies, and geographical regions fueling growth. This segmentation enables precise targeting of markets and understanding of key drivers influencing demand and supply dynamics across the globe.
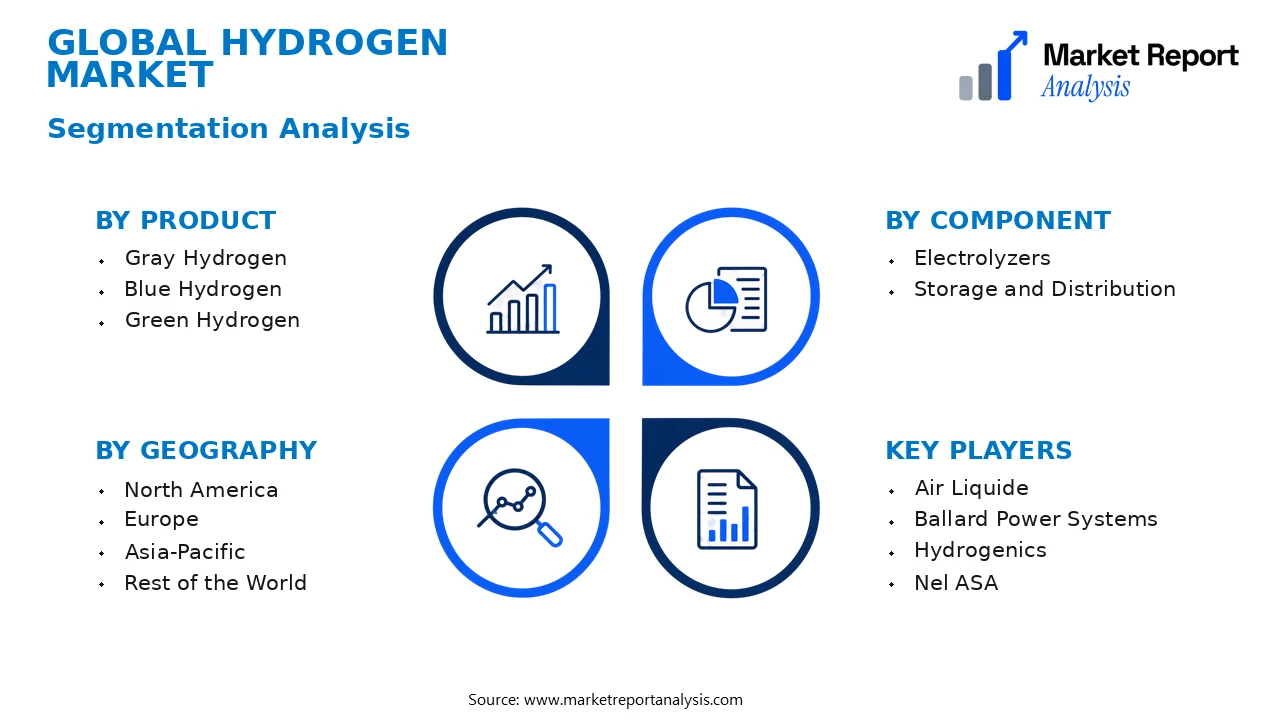
- Product
- Gray Hydrogen: Produced from natural gas through steam methane reforming, gray hydrogen accounts for the majority of current global production, primarily used in refining, chemical manufacturing, and industry processes where cost efficiency is prioritized.
- Blue Hydrogen: Generated via reforming of natural gas with CCS technology, blue hydrogen is gaining adoption for its lower carbon footprint, especially in regions with stringent emission regulations, serving transportation, power generation, and industry sectors.
- Green Hydrogen: Derived from electrolysis powered by renewable energy sources, green hydrogen is emerging as the cleanest option, with significant growth potential driven by global decarbonization goals, especially in renewable-intensive applications like transportation and industry.
- Component
- Electrolyzers: Vital for green hydrogen production, electrolyzers are evolving technologically to increase efficiency and reduce costs, thus playing a critical role in the expansion of renewable-based hydrogen supply.
- Storage and Distribution: This subsegment covers hydrogen storage tanks, pipelines, and transportation solutions essential for integrating hydrogen into various sectors and ensuring safe, efficient distribution from production sites to end users.
- Technology
- Proton Exchange Membrane (PEM) Electrolysis: Known for its quick response and high purity output, PEM electrolysis is preferred for niche applications such as mobility and grid balancing, with ongoing innovations aimed at cost reduction.
- Alkaline Electrolysis: The mature technology dominates large-scale green hydrogen production due to its simplicity and economic viability, with improvements focusing on efficiency and operational durability.
- Application
- Industrial Use: Hydrogen in industry primarily supports refining, chemical manufacturing, and metallurgy, with demand driven by stricter environmental standards and the need for cleaner feedstocks.
- Transport: Fuel cell electric vehicles (FCEVs) and hydrogen-powered buses are rapidly expanding segments, influenced by regulatory mandates and advancements in fuel cell technology.
- Power Generation: Hydrogen's role in power plants as a clean fuel source is increasing, especially for balancing renewable energy intermittency and providing backup power solutions.
- End User
- Refining & Chemicals: This segment remains the largest consumer of hydrogen, utilizing both gray and blue hydrogen to meet manufacturing needs amid evolving environmental policies.
- Mobility & Transportation: Driven by clean fuel mandates and innovation in fuel cell technology, this sector is witnessing robust growth in hydrogen vehicle adoption.
- Utilities & Power: Incorporating hydrogen into grid management and power generation offers a sustainable option for balancing renewable energy, prompting increased investments in hydrogen infrastructure.
- Geography
- North America: Characterized by advanced technological development, significant private and public investments, and ambitious decarbonization targets influencing product and application growth.
- Europe: Known for stringent environmental regulations and substantial governmental incentives, Europe is a leader in green hydrogen initiatives and policy-driven market expansion.
- Asia-Pacific: The largest market by volume, Asia-Pacific's growth is driven by expansive industrial demand, government support, especially in China, Japan, and South Korea, and increasing renewable energy capacities.
- Rest of the World: Emerging markets with growing infrastructure investments and industrialization, positioning themselves for future hydrogen demand acceleration.
Competitive Intelligence
The Hydrogen Market exhibits moderate competition with key players like Air Liquide, Plug Power, and Shell pursuing strategic expansions and technological advancements. Market concentration remains relatively fragmented, fostering innovation-driven competition among large multinationals and emerging startups. Companies are adopting aggressive business strategies, including significant R&D investments to enhance hydrogen production efficiency, storage solutions, and fuel cell technologies. Partnerships are a central component, with alliances formed between energy firms, automotive manufacturers, and research institutions to accelerate commercialization and deployment. Notable acquisitions aim to bolster technological capabilities and expand market reach, with several firms focusing on vertical integration to control the value chain. Expansion initiatives involve establishing hydrogen production facilities, developing infrastructure, and entering new geographic markets, particularly in Asia-Pacific and Europe. Differentiation strategies revolve around product innovation like low-cost electrolysis methods and miniaturized fuel cells to provide competitive advantages. This dynamic landscape is characterized by continuous innovation, strategic collaborations, and proactive market entry, positioning the industry for robust growth through 2034.
Leading Company Profiles
The competitive landscape of the hydrogen market features a diverse suite of global players that are investing heavily in R&D, strategic alliances, and capacity expansions to secure their market positions. These companies are characterized by their technological expertise, extensive product portfolios, and strategic priorities geared toward sustainability and innovation.
- Air Liquide
- Ballard Power Systems
- Hydrogenics
- Nel ASA
- ITM Power
- Linde PLC
- Plug Power
- SIECO
- Shaangu
- Samsung Engineering
Air Liquide
Air Liquide specializes in industrial gases, with a significant focus on hydrogen production through electrolysis and steam methane reforming, alongside infrastructure development for hydrogen fueling stations across Europe and Asia.
Ballard Power Systems
Ballard Power is a leading provider of PEM fuel cell solutions for transportation, portable power, and stationary applications, emphasizing advanced fuel cell technologies to promote clean energy mobility globally.
Hydrogenics
Hydrogenics, now part of Cummins, offers electrolyzers and fuel cell products, with strategic emphasis on scalable green hydrogen solutions for industrial and energy storage applications worldwide.
Nel ASA
Nel specializes in electrolyzers and hydrogen fueling station solutions, with substantial investments in large-scale green hydrogen projects to support renewable energy integration and decarbonize heavy industries.
ITM Power
ITM Power develops PEM electrolyzers and has pioneered integration with renewable energy sources, focusing on expanding green hydrogen production capacity across key markets through strategic partnerships.
Linde PLC
Linde's extensive industrial gas portfolio includes hydrogen, with a focus on global infrastructure projects, innovative storage solutions, and fostering collaborations to accelerate hydrogen adoption.
Plug Power
Plug Power prioritizes hydrogen fuel cell systems for logistics and transportation, investing in gigafactories and strategic alliances for scaling green hydrogen generation and infrastructure development.
SIECO
SIECO focuses on green hydrogen project development and electrolysis technology, aligning with global energy transition initiatives to foster sustainable energy systems globally.
Shaangu
Shaangu is advancing hydrogen energy solutions through innovative electrolyzer manufacturing and integrating renewable energy sources to promote sustainable industrial practices in China and beyond.
Samsung Engineering
Samsung Engineering develops large-scale hydrogen production facilities and supports global green hydrogen projects with a focus on engineering innovative and sustainable energy infrastructure.
Strategic Business Developments
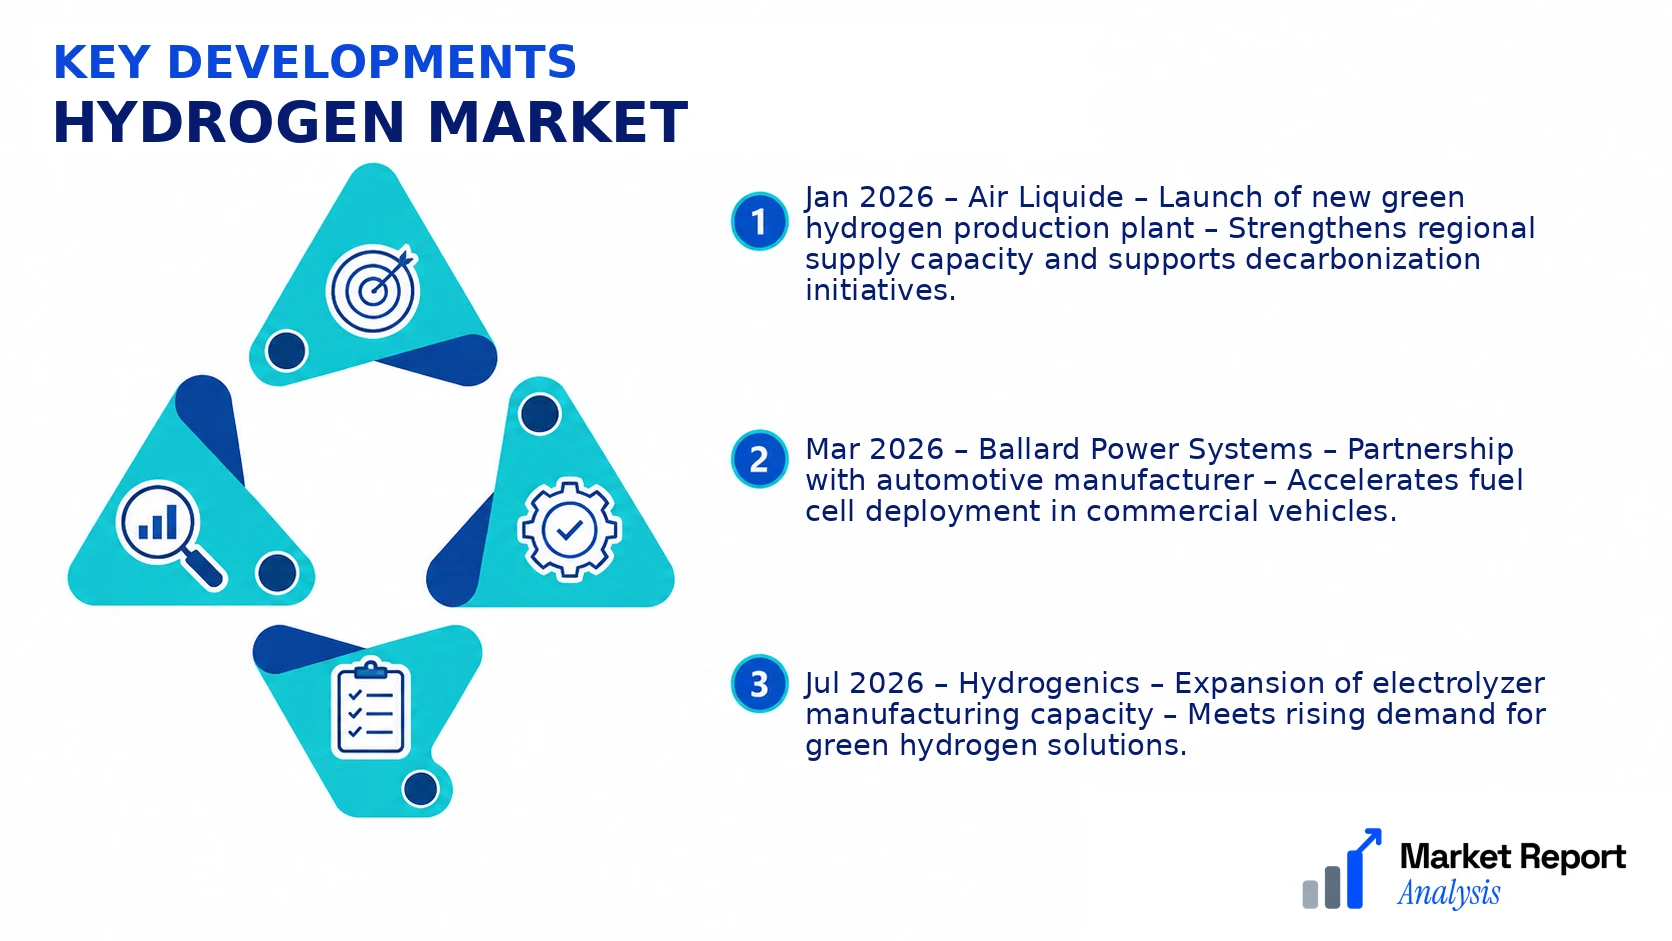
- Jan 2026 – Air Liquide – Launch of new green hydrogen production plant – Strengthens regional supply capacity and supports decarbonization initiatives.
- Mar 2026 – Ballard Power Systems – Partnership with automotive manufacturer – Accelerates fuel cell deployment in commercial vehicles.
- Jul 2026 – Hydrogenics – Expansion of electrolyzer manufacturing capacity – Meets rising demand for green hydrogen solutions.
- Sep 2026 – Nel ASA – Acquisition of renewable energy assets – Enhances sustainable hydrogen generation capability.
- Nov 2026 – ITM Power – Development of innovative high-capacity electrolyzer system – Advances for commercial-scale green hydrogen production.
Frequently Asked Questions
What is the Hydrogen Market?
The Hydrogen Market encompasses the global industry involved in the production, distribution, and utilization of hydrogen as an energy carrier and industrial input. It plays a critical role in clean energy transitions, particularly in transportation, power generation, and industrial processes.
What is the current market size of Hydrogen Market?
As of 2026, the Hydrogen Market is valued at approximately USD 125 Billion, reflecting increasing adoption driven by government policies, technological advancements, and rising demand from various sectors seeking sustainable energy solutions.
What factors are driving the Hydrogen Market?
Key drivers include rising environmental concerns, government incentives for clean energy, declining costs of electrolysis, and technological innovations. Additionally, the push for decarbonization across industries further accelerates hydrogen adoption worldwide.
Which region dominates the Hydrogen Market?
North America currently leads the Hydrogen Market, owing to significant investments in hydrogen infrastructure, favorable policies, and a strong presence of technology companies. Europe and Asia-Pacific are rapidly closing the gap through strategic initiatives and investments.
Which segment is expected to grow the fastest?
Green hydrogen, produced via renewable energy-powered electrolysis, is projected to grow at the highest CAGR, driven by the global shift towards zero-emission energy sources and increasing governmental and private sector investments in sustainable hydrogen projects.
Who are the leading companies operating in the Hydrogen Market?
Major players include Air Liquide, Plug Power, Ballard Power Systems, Siemens Energy, and Linde. These companies are investing heavily in R&D, infrastructure, and strategic collaborations to expand their market presence and technological capabilities.
Analyst Perspective
The long-term market outlook for hydrogen remains highly promising, driven by global decarbonization goals and the growing demand for sustainable energy solutions. Commercial opportunities are expanding across various sectors including transportation, industrial processes, and power generation, with green hydrogen expected to play a key role in energy transition strategies. Technology evolution will likely focus on cost-effective production methods, including breakthroughs in electrolysis efficiency and renewable energy integration, which will lower barriers to market entry. Investment priorities should emphasize infrastructure development, supply chain integration, and scaling innovative production technologies to meet surging demand. Competitive intensity is poised to increase as key players and new entrants vie for market share, fostering innovation and price competition. Regionally, Asia-Pacific and Europe are anticipated to lead growth, supported by policy frameworks and investment inflows. Strategically, stakeholders should adopt flexible, integrated approaches that can adapt to rapid technological advancements and evolving regulations, ensuring long-term market resilience amidst an increasingly competitive landscape.
