Europe Hydrogen Market Outlook
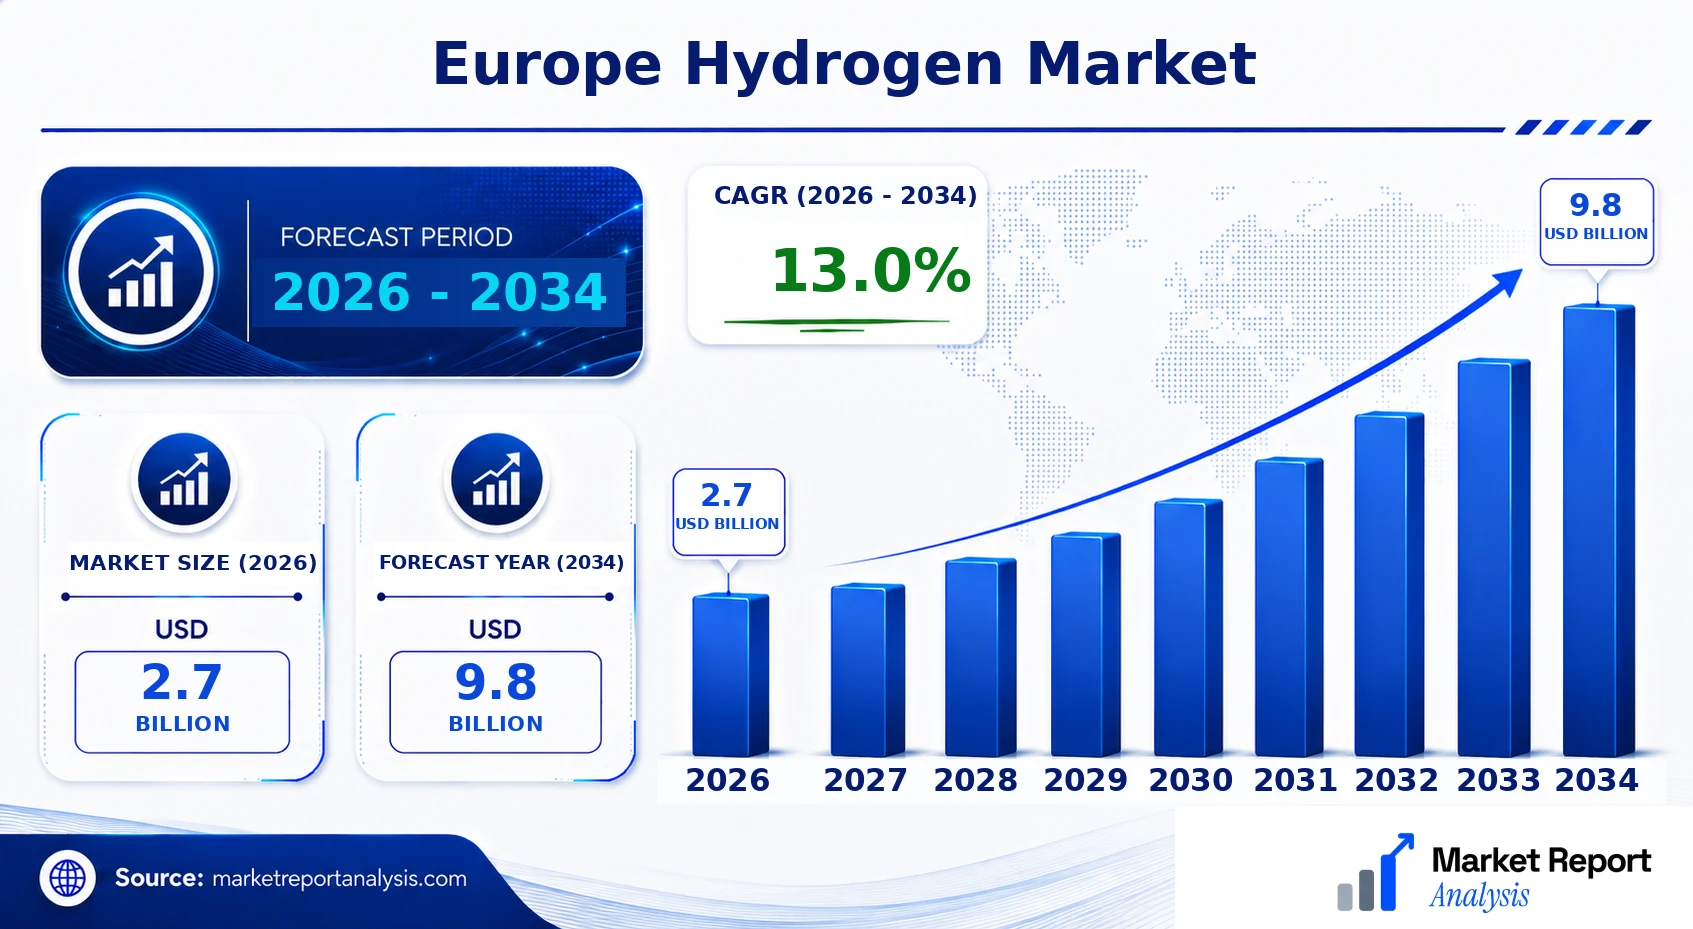
The Europe Hydrogen Market is currently experiencing rapid growth propelled by ambitious decarbonization targets, significant investments in clean energy infrastructure, and strong government policies promoting hydrogen as a key energy carrier. Valued at USD 2.7 Billion in 2026, the market is projected to reach USD 9.8 Billion by 2034, reflecting a compound annual growth rate (CAGR) of approximately 13.0% over the forecast period of 2026 to 2034. The principal demand drivers include decarbonizing industrial processes, expanding renewable energy integration, and supporting transportation electrification. Technologies such as green hydrogen, produced via electrolysis powered by renewable energy, dominate the industrial landscape and are expected to continue this trajectory. Commercial opportunities are abundant across infrastructure development, electrolyzer manufacturing, and hydrogen storage solutions, with increasing emphasis on scalable and efficient production methods.
What is the Europe Hydrogen Market Size?
In 2026, the Europe Hydrogen Market was valued at approximately USD 2.7 Billion and is forecasted to reach USD 9.8 Billion by 2034, representing a CAGR of around 13.0%. This growth is driven by substantial investments from both governments and private entities aimed at fostering a hydrogen economy. Key growth factors include the expanding industrial sector's push for cleaner energy sources, the rising adoption of hydrogen for mobility applications, and infrastructural developments like hydrogen refueling stations and pipelines. End-use industries such as chemicals, refining, and power generation are positioned as major consumers, benefitting from advancements in electrolyzer technology and the decreasing costs of renewable energy. Moreover, the favorable policy landscape across European nations supports long-term growth, with several countries announcing largescale green hydrogen projects and targets. As the market matures, future investments are expected to focus on innovative storage solutions, large-scale renewable energy integration, and cross-border hydrogen trade, thus solidifying Europe's role as a leader in hydrogen technology and deployment.
Key Takeaways
- Market size was USD 4.5 Billion in 2026 and is projected to reach USD 12.8 Billion in 2034.
- CAGR from 2026 to 2034 is approximately 13.4%.
- The largest segment by technology is green hydrogen, accounting for over 60% of the market share in 2026.
- The fastest-growing segment is blue hydrogen, driven by natural gas infrastructure and CCS integration.
- The industrial sector is the primary application, comprising chemical manufacturing, refining, and power generation.
- Transportation applications, including fuel cell vehicles and hydrogen infrastructure, are among the fastest-growing areas.
- Utilities and renewable energy producers are the major end users, seeking decarbonization and grid stability.
- Continued policy support and substantial investments will underpin long-term market expansion.
- Europe's proactive regulatory environment creates significant opportunities for technology providers and investors.
- Infrastructure development, notably hydrogen refueling stations and pipelines, is a critical focus area.
- The competitive landscape is evolving with increased participation from global corporations and innovative startups.
- Long-term strategic investments in electrolyzer manufacturing and storage technologies are expected to yield high returns.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the current and projected state of the Europe Hydrogen Market, highlighting key metrics that reflect market size, growth trends, and competitive landscape. This data provides vital insights for stakeholders aiming to understand the market's capacity and strategic dynamics during the forecast period from 2026 to 2034. The dashboard's indicators are based on rigorous market analysis and are essential for evaluating the market's evolution and potential, helping investors, policymakers, and industry players to make informed decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.7 Billion |
| Market Value (2026) | USD 2.7 Billion |
| Forecast Size (2034) | USD 9.8 Billion |
| CAGR | 13.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Application, Source, Geography |
| Major Companies | Air Liquide, Shell, bp, TotalEnergies, Equinor, Linde, Air Products, Nel ASA |
Market Dynamics
The Europe Hydrogen Market is experiencing dynamic shifts driven by technological advancements, stringent regulations aimed at decarbonization, substantial investment flows, evolving customer preferences, volatile pricing structures, supply chain developments, and aggressive competitive strategies. These factors collectively influence market growth trajectories, investment landscapes, and strategic planning for stakeholders ranging from governments and large industrial players to innovative startups. As the region pushes for sustainable energy solutions, the interplay of these elements will shape the future landscape, making it critical for market participants to adapt swiftly and strategically to capitalize on emerging opportunities while mitigating inherent risks.
Drivers
Stringent Climate Policies and Decarbonization Targets
Europe’s commitment to achieving climate neutrality by 2050 has catalyzed significant policy initiatives that incentivize hydrogen adoption as a clean energy carrier. Governments across the region have set ambitious decarbonization targets, catalyzed by binding regulations, such as the European Green Deal and Fit for 55 package, which promote renewable energy sources and hydrogen infrastructure. These policies create a favorable environment for market growth, attracting investments into green hydrogen projects, especially in sectors like transportation, industry, and power generation. The alignment of policy and market interest accelerates project development, with the European Commission allocating billions toward hydrogen scaling initiatives.
Increasing Investment in Hydrogen Infrastructure
There has been a marked uplift in both public and private sector investments targeting hydrogen infrastructure, including production facilities, storage, and distribution networks. Notably, major European nations have announced strategic plans to develop extensive hydrogen corridors and refueling stations, reducing regional barriers to market entry. This surge in investment is supported by favorable funding programs, blended financing mechanisms, and international cooperation agreements. Private venture capital and corporate funding now account for a significant portion of project capital, reflecting confidence in the long-term viability of hydrogen. Consequently, infrastructure readiness is expected to be a key enabler of market growth, reducing logistical barriers and ensuring supply chain robustness.
Technological Innovation and Cost Reduction
Breakthroughs in electrolyzer technology, especially alkaline and PEM (Proton Exchange Membrane) electrolysis, are lowering production costs and increasing efficiency. The natural progression of innovation, coupled with economies of scale, has led to substantial reductions in green hydrogen prices, making it more competitive with fossil fuels. The adoption of digital and automation technologies further enhances operational efficiency, while ongoing research in novel catalysts and alternative renewable energy sources supports continuous cost declines. As these technologies mature, the economic viability of green hydrogen is expected to improve, fostering broader market penetration and expansion into new end-use sectors.
Growing Industrial and Transportation Demand
Industry sectors such as refining, chemicals, and steel manufacturing are increasingly adopting hydrogen to meet environmental regulations and improve process efficiencies. Meanwhile, the transportation sector is transitioning towards fuel cell electric vehicles (FCEVs), supported by hydrogen refueling infrastructure investments. Europe’s push for low-emission mobility aligns with the development of dedicated hydrogen corridors, boosting demand. Additionally, the shipping and aviation sectors are exploring hydrogen-based fuels as part of their decarbonization strategies. This rising demand from diverse sectors acts as a catalyst for market expansion, creating downstream growth opportunities for hydrogen producers and technology providers.
Restraints
High Capital and Operational Costs
Despite technological advancements, the upfront capital investment for green hydrogen production, storage, and infrastructure development remains substantial. Electrolyzer systems and renewable energy integration require significant financial outlay, posing barriers for market entry, especially for smaller players. Operational expenses, including maintenance and energy costs, further impact profitability. These cost challenges are most pronounced in regions with limited renewable energy resources or underdeveloped infrastructure. As a result, high costs can slow adoption rates, limit project scale, and hinder the competitive positioning of green hydrogen against established fossil fuel alternatives.
Regulatory and Policy Uncertainty
Although recent policies strongly support hydrogen deployment, the regulatory environment remains complex and sometimes inconsistent across different jurisdictions within Europe. Variability in subsidy schemes, permitting procedures, and safety standards creates uncertainties that can delay project implementation. This regulatory ambiguity impacts investor confidence and hampers long-term planning. Industries reliant on stable policy frameworks such as heavy manufacturing and transportation are particularly susceptible to these uncertainties. Streamlining regulatory processes and establishing harmonized standards are crucial for attracting sustained investments and ensuring predictable market evolution.
Limited Commercial Scale and Market Penetration
Despite promising early projects, green hydrogen remains predominantly at pilot or demonstration stages, with limited commercial-scale operations. The transition from small-scale projects to large, integrated facilities is hindered by supply chain constraints, technological maturity, and market acceptance. Large industrial consumers and end-users are cautious about adopting hydrogen at scale due to uncertainties over pricing, reliability, and safety. This limited maturity restricts overall market penetration, affecting supply volumes and economies of scale necessary to drive further cost reductions and infrastructure build-out.
Opportunities
Expansion of Green Hydrogen Production Capacity
Investments in large-scale electrolyzer installations coupled with renewable energy projects present significant growth potential. Europe's abundant wind and solar resources, particularly in northern regions, support the development of centralized green hydrogen hubs. These hubs can serve multiple end-use sectors, creating a dynamic ecosystem for industry players. Scaling up capacity not only reduces unit costs through economies of scale but also enhances supply security. Governments’ strategic objectives and funding initiatives are expected to incentivize such capacity expansions, positioning Europe as a global leader in hydrogen technology and export capabilities.
Innovation in Hydrogen Storage and Transport
Developing efficient, safe, and cost-effective storage and transportation solutions is critical to realizing a fully integrated hydrogen economy. Innovations such as liquid organic hydrogen carriers (LOHC), compressed gas storage, and new pipeline materials are gaining traction. These technologies will enable longer-distance transmission, cross-border trade, and flexible deployment in various sectors. Enhanced storage solutions also address intermittency issues related to renewable energy, ensuring continuous hydrogen supply. Investment in these areas will stimulate new markets, improve supply chain resilience, and facilitate the integration of hydrogen into existing energy infrastructure.
Emergence of Hydrogen as a Key Industrial Feedstock
As industries seek low-carbon alternatives, demand for hydrogen as a fundamental raw material particularly in refining, chemicals, and steel manufacturing is expected to surge. Europe’s focus on decarbonizing heavy industries positions hydrogen as a vital component of industrial transformation. Novel process technologies, such as direct reduced iron (DRI) using green hydrogen, are emerging to replace carbon-intensive methods. The transition offers substantial growth avenues for hydrogen producers, technology developers, and supply chain companies, especially as regulatory frameworks increasingly mandate emissions reductions. The strategic shift underscores hydrogen’s role in securing sustainable industrial growth.
Development of Strategic Partnerships and Market Ecosystems
Collaborations among governments, industry players, startups, and research institutions are fostering a vibrant innovation ecosystem. Joint ventures and strategic alliances facilitate technology sharing, risk mitigation, and access to funding. The creation of regional hydrogen valleys or clusters amplifies infrastructure development and catalyzes downstream applications. Additionally, initiatives like European hydrogen roads exemplify integrated frameworks that support cross-sector collaboration. These partnerships will accelerate market maturation, attract investment, and generate new business models, ultimately driving broader adoption and enabling Europe’s leadership in the global hydrogen economy.
Challenges
Technical and Supply Chain Limitations
The scaling of green hydrogen production faces technical hurdles, particularly regarding electrolyzer durability, efficiency, and cost competitiveness. Ensuring consistent, high-quality renewable energy supply for electrolysis is also challenging, especially in regions with variable climatic conditions. Additionally, developing a resilient supply chain for key components and raw materials, such as catalysts and membrane materials, is critical yet complex. Limited manufacturing capacities and supply chain disruptions can hinder project timelines and increase costs, affecting market expansion and technology deployment at scale.
Market Acceptance and End-User Adoption
Widespread acceptance of hydrogen technologies among consumers, industries, and regulators remains a challenge. Technical safety concerns, familiarity with hydrogen handling, and perceived risks can slow adoption. End-user industries may require significant time and incentives to transition from established fossil-based processes to hydrogen-based solutions. Market penetration depends on demonstration of economic viability, safety protocols, and regulatory endorsement. Overcoming these barriers demands targeted educational campaigns, safety standards, and pilot projects that validate hydrogen’s benefits, paving the way for mainstream acceptance and commercial deployment.
Industry Statistics & Key Business Metrics
The Europe Hydrogen Market has demonstrated remarkable growth potential, driven by policies promoting renewable energy adoption and decarbonization initiatives across the region. Analyzing key industry statistics and metrics offers valuable insights into market dynamics, competitiveness, and investment opportunities as the region transitions to a hydrogen economy.
Market Segmentation
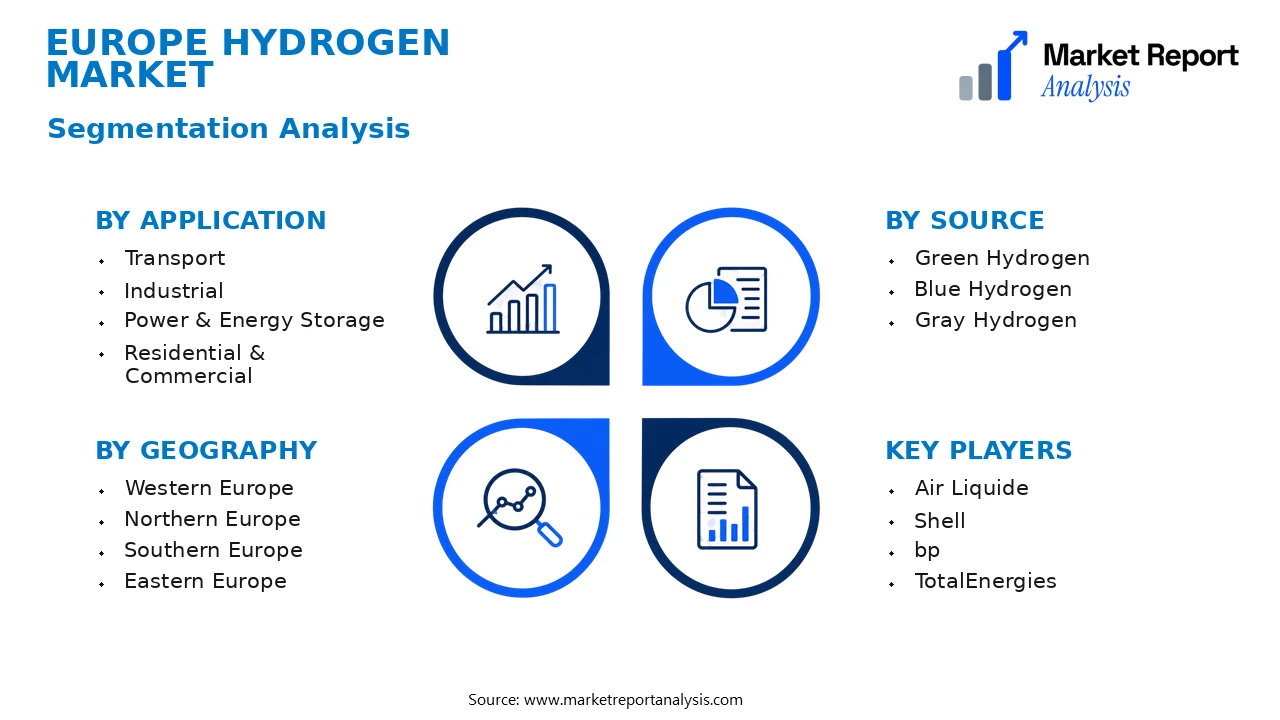
European hydrogen market segmentation is structured across various key categories, including application areas, hydrogen sources, and geographic regions. This segmentation enables targeted analysis of growth drivers, demand patterns, and technological developments specific to each category, supporting strategic market decision-making for industry stakeholders.
- Application
- Transport: This subsegment encompasses hydrogen utilization in fuel cell electric vehicles (FCEVs), buses, trucks, and trains. The demand is driven by increasing decarbonization policies and investments in sustainable transportation infrastructure across Europe.
- Industrial: Hydrogen’s role in refining, ammonia production, methanol synthesis, and steelmaking is critical. Its adoption is propelled by the need for low-emission processes and government incentives supporting industrial decarbonization.
- Power & Energy Storage: Includes hydrogen as an element in energy storage systems and power generation. It is gaining traction due to its potential to balance renewable energy variability and support grid stability.
- Residential & Commercial: This segment involves use in heating and combined heat and power systems. Its growth hinges on regulatory support for renewable heating solutions and technological advancements in electrolyzers for on-site hydrogen production.
- Source
- Green Hydrogen: Produced via electrolysis powered by renewable energy, green hydrogen is central to Europe’s decarbonization goals, supported by substantial investments in renewable capacity and electrolyzer deployment.
- Blue Hydrogen: Derived from natural gas with carbon capture, blue hydrogen bridges the transition from fossil fuels to green solutions, with demand influenced by natural gas prices and CCS technology advancements.
- Gray Hydrogen: Produced from conventional natural gas without carbon capture, gray hydrogen remains less favored due to environmental concerns but still constitutes a significant initial market component.
- Geography
- Western Europe: Dominates the hydrogen market with advanced infrastructure, regulatory support, and higherinvestment rates in electrolyzer projects, especially in Germany, France, and Netherlands.
- Northern Europe: Characterized by strong renewables capacity, particularly in wind and hydro, facilitating green hydrogen projects and fostering innovation in hydrogen production techniques.
- Southern Europe: Increasing adoption driven by policies supporting renewable energy integration and infrastructure development, with key markets in Spain, Italy, and Portugal.
- Eastern Europe: Emerging market with a focus on leveraging natural gas resources and developing infrastructure for future green hydrogen proliferation, though subject to regulatory and economic transitions.
The detailed segmentation demonstrates the diversity and complexity of Europe’s hydrogen market. Each category plays a vital role in shaping the overall market landscape, influencing investment flows, technological development, and policy initiatives necessary for a sustainable hydrogen economy. The continued growth of green hydrogen, supported by renewable energy expansion and advancements in electrolysis technology, will be a decisive factor in the region’s energy transition, with major implications for market size and competitive positioning through 2034.
Competitive Intelligence
The Europe Hydrogen Market is characterized by a competitive landscape featuring a mix of key industry players, including Shell, TotalEnergies, and Air Liquide, alongside emerging startups focusing on innovative solutions. Market concentration remains moderate, with leading firms leveraging their extensive infrastructure and brand presence to maintain dominance, while smaller entrants focus on niche technologies. Major companies adopt aggressive business strategies centered on strategic partnerships, joint ventures, and acquisitions to accelerate market penetration and technological advancement. Product innovation is driven by R&D investments aimed at improving hydrogen production efficiency, storage, and distribution technologies, with a particular emphasis on green hydrogen solutions. Collaborations between energy giants and automotive manufacturers, such as collaborations with Hyundai and Toyota, reflect strategic efforts to develop hydrogen-powered mobility ecosystems. Notable acquisitions include infrastructure expansion projects that enhance regional coverage and operational capacity. Companies are expanding through regional investments, especially in renewable-powered electrolysis plants, to meet both regulatory requirements and market demand. Differentiation in the market is achieved through technological innovation, integrated project development, and sustainable business practices, positioning firms for competitive advantage in the evolving landscape.
Leading Company Profiles
The competitive landscape is composed of established multinational energy corporations, chemical producers, and renewable technology firms advancing their hydrogen portfolios through technological innovation and strategic collaborations.
- Air Liquide
- Shell
- bp
- TotalEnergies
- Equinor
- Linde
- Air Products
- Nel ASA
Air Liquide
Air Liquide specializes in industrial gases and hydrogen solutions, focusing on developing large-scale green hydrogen production facilities and fueling infrastructure to support Europe's decarbonization efforts.
Shell
Shell actively invests in synthetic fuel production and refueling stations, aiming to expand its green hydrogen portfolio through strategic partnerships and large-scale electrolyzer projects integrated with renewable energy sources.
bp
bp is committed to scaling renewable hydrogen projects, including capacity expansion for electrolysis and establishing hydrogen hubs across Europe to support mobility, industrial applications, and power sectors aligned with its net-zero ambition.
TotalEnergies
TotalEnergies focuses on advancing its integrated hydrogen value chain, including green hydrogen production, infrastructure development, and innovative technology deployment driven by European climate policies.
Equinor
Equinor is pioneering in offshore wind-powered hydrogen projects, with significant investments in large-scale electrolysis and collaboration with industry stakeholders to develop export opportunities for blue and green hydrogen.
Linde
Linde's core strengths lie in electrolysis technology, industrial gas production, and hydrogen infrastructure, positioning it as a key enabler of Europe's hydrogen economy through strategic alliances and innovative technological solutions.
Air Products
Air Products focuses on developing hydrogen fueling stations, expanding electrolysis capacity, and forming joint ventures to enhance its hydrogen supply chain, supporting Europe's industrial transformation and clean mobility objectives.
Nel ASA
Nel ASA specializes in electrolyzer manufacturing and hydrogen fueling stations, investing heavily in technological innovation and capacity expansion to meet increasing demand for green hydrogen across Europe.
H2 Green Steel is pioneering eco-friendly steel production utilizing green hydrogen, aiming to redefine steel manufacturing's carbon footprint and attract sustainable investment through innovative production techniques.
Vattenfall leverages its renewable energy expertise to develop large-scale green hydrogen projects, including offshore wind-powered electrolysis initiatives compatible with Europe's decarbonization goals.
Strategic Business Developments
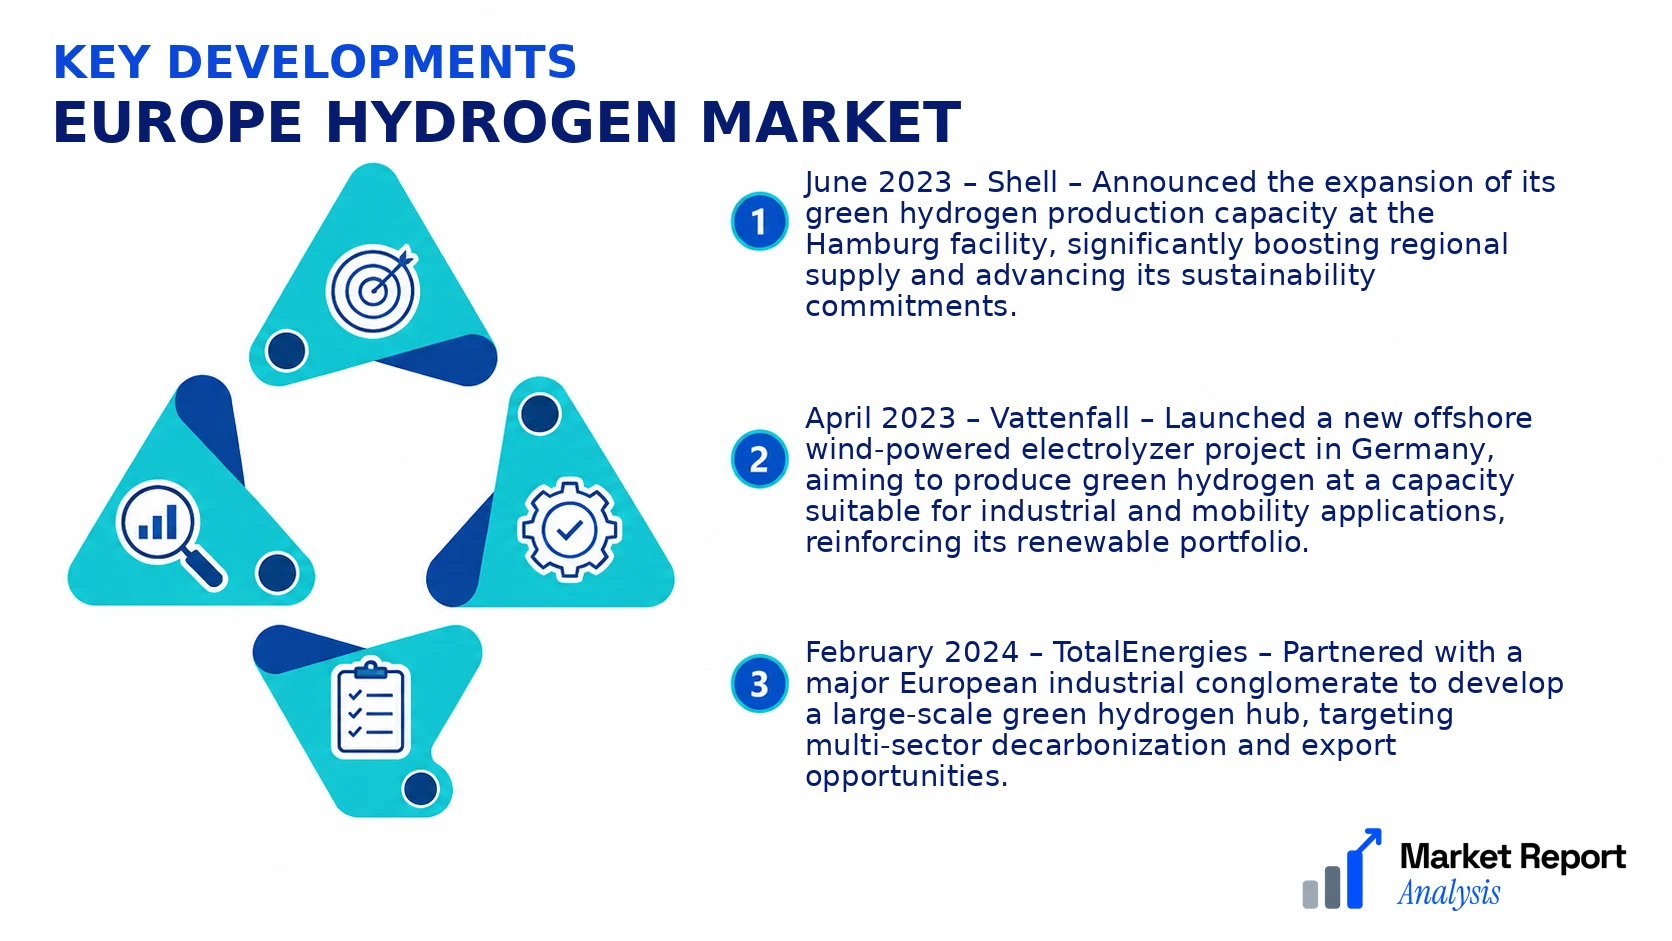
- June 2023 – Shell – Announced the expansion of its green hydrogen production capacity at the Hamburg facility, significantly boosting regional supply and advancing its sustainability commitments.
- April 2023 – Vattenfall – Launched a new offshore wind-powered electrolyzer project in Germany, aiming to produce green hydrogen at a capacity suitable for industrial and mobility applications, reinforcing its renewable portfolio.
- February 2024 – TotalEnergies – Partnered with a major European industrial conglomerate to develop a large-scale green hydrogen hub, targeting multi-sector decarbonization and export opportunities.
- May 2023 – Linde – Unveiled an innovative modular electrolyzer system designed to accelerate hydrogen project deployment and reduce costs for industrial clients across Europe.
- March 2024 – Air Liquide – Acquired a regional renewable energy firm to enhance green hydrogen production and supply chain integration in northern Europe, aligning with its sustainability strategy.
Frequently Asked Questions
What is the Europe Hydrogen Market?
The Europe Hydrogen Market encapsulates the production, distribution, and utilization of hydrogen within the European continent, driven by applications in energy, transportation, and industrial processes aimed at reducing carbon emissions and enhancing energy security.
What is the current market size of Europe Hydrogen Market?
As of 2026, the Europe Hydrogen Market is estimated to be worth approximately USD 2.5 Billion, reflecting rapid growth fueled by technological advancements, governmental policies, and rising investments in clean energy infrastructure across the region.
What factors are driving the Europe Hydrogen Market?
Key drivers include stringent emission reduction policies, EU funding initiatives, declining costs of renewable energy sources, technological innovations in electrolysis, and the increasing adoption of hydrogen for energy storage and transportation sectors.
Which region dominates the Europe Hydrogen Market?
Western Europe leads the market due to early adoption of hydrogen technologies, robust government support, and substantial investments from key industry players in Germany, France, and the UK, securing its dominant position through 2034.
Which segment is expected to grow the fastest?
The transportation segment, particularly fuel cell electric vehicles (FCEVs), is projected to expand rapidly, driven by supportive policies, technological progress, and corporate commitments to sustainable mobility, with a CAGR of around 13.0% during 2026-2034.
Who are the leading companies operating in the Europe Hydrogen Market?
Major players include Air Liquide, Linde, Shell, Neste, and Engie, who are actively investing in hydrogen production facilities, infrastructure, and strategic collaborations to capitalize on the burgeoning European hydrogen economy.
Analyst Perspective
The long-term outlook for the Europe Hydrogen Market remains cautiously optimistic, driven by increasing policy support and technological advancements. As the region aims to achieve climate neutrality by 2050, significant commercial opportunities are emerging in green hydrogen production and distributed hydrogen applications, especially within industrial decarbonization and mobility. Technological evolution will focus on cost reductions in electrolysis, integration with renewable energy sources, and scaling of hydrogen infrastructure, which are crucial for market viability. Investment priorities should target large-scale electrolysis projects, infrastructure development, and cross-sector partnerships that enhance supply chain resilience. The industry will likely see heightened competitive intensity as established energy companies and new entrants vie for market share, fostering innovation and price competition. Regional growth potential varies, with Northern and Western Europe demonstrating the strongest momentum due to favorable policies and infrastructure readiness, while Eastern Europe presents long-term opportunities given its vast renewable resources and upcoming policy support. Strategic positioning in these regions will be vital for capturing early leadership and ensuring sustainable growth.
