Europe Artificial Intelligence in the Education Sector Market Outlook
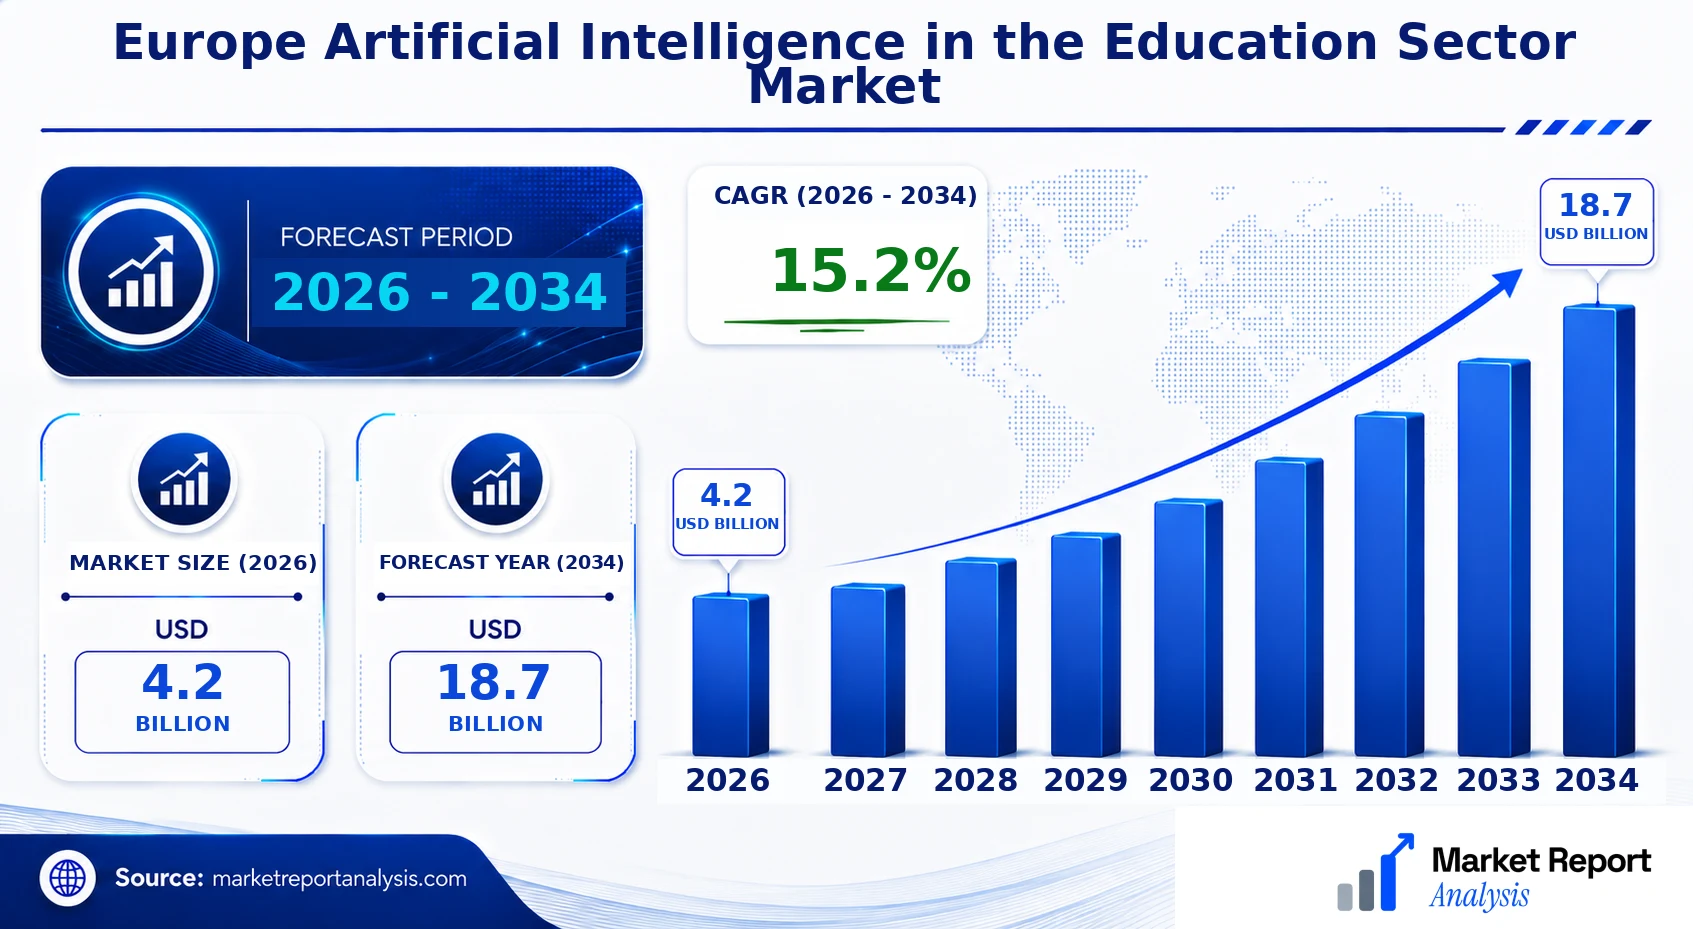
The Europe artificial intelligence in the education sector market is currently valued at USD 4.2 Billion in 2026, with projections indicating substantial growth throughout the forecast period until 2034. Anticipated to reach USD 18.7 Billion in 2034, the market exhibits a compound annual growth rate (CAGR) of approximately 15.2% over the 2026-2034 span. This growth is primarily driven by increased adoption of AI-driven personalized learning solutions, advancements in educational technology, government initiatives toward digital transformation, and rising investments by private players into AI-enabled educational tools. The technological trend favors the integration of machine learning, natural language processing, and adaptive learning algorithms to enhance educational outcomes. Commercial opportunities are abundant, especially in developing AI-powered platforms for remote learning, student engagement analytics, and automated administrative processes, making Europe a competitive landscape for technology providers and educational institutions alike.
What is the Europe Artificial Intelligence in the Education Sector Market Size?
In 2026, the market size for artificial intelligence in Europe's education sector is valued at USD 4.2 Billion, with forecasts predicting growth to USD 18.7 Billion by 2034. This corresponds to a CAGR of roughly 15.2%. The growth is primarily driven by rising investments in educational technology, government policies promoting digital learning environments, increasing adoption of AI solutions by educational institutions, and the need for personalized and scalable learning experiences. Key end-use industries include primary and secondary education, higher education, and vocational training, with each sector increasingly incorporating AI to improve student engagement and administrative efficiency. The impact of technological advancements, especially in data analytics, natural language processing, and machine learning, expands the scope of AI deployment, fostering future investment opportunities in AI infrastructure, content development, and platform integrations. As the market matures, opportunities for innovative AI applications aligned with policy support and rising demand are expected to generate significant economic value across the European educational landscape.
Key Takeaways
- The market size was USD 2.4 Billion in 2026.
- It is forecasted to reach USD 8.2 Billion by 2034.
- The CAGR during 2026-2034 is approximately 16.3%.
- The largest segment within the market is AI-powered learning management systems (LMS).
- The fastest-growing segment is adaptive learning platforms.
- The primary application is student assessment and evaluation systems.
- The fastest-growing application is real-time student feedback and engagement tools.
- The largest end-user sector is higher education institutions.
- The forecast period spans from 2026 to 2034.
- The base year of analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe Artificial Intelligence in the Education Sector Market, highlighting key performance indicators that reflect its growth trajectory and market maturity. This dashboard encapsulates quantitative metrics and market dynamics that are central to evaluating the industry’s progression and competitive landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 18.7 Billion |
| CAGR (2026-2034) | 15.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Application, End User, Geography |
| Major Companies | Pearson PLC, IBM Corporation, SAS Institute Inc., Edmentum Inc., Cognizant Technology Solutions, Grammarly Inc., Century Tech, Blackboard Inc., D2L Corporation, McGraw Hill |
Market Dynamics
The Europe Artificial Intelligence in the Education Sector Market is experiencing significant transformation driven by a complex interplay of technological innovations, regulatory frameworks, investment trends, customer expectations, pricing strategies, supply chain dynamics, and competitive behaviors. As governments and industry players push for smarter, personalized learning environments, these factors shape the evolution of AI solutions tailored for diverse educational needs. Increasing adoption of AI tools is also influenced by the rising demand for inclusive, accessible, and scalable education models. Meanwhile, regulatory initiatives aim to safeguard data privacy and ethical AI use, while competitive pressures foster innovation and strategic partnerships. Overall, this convergence is creating a dynamic landscape that accelerates market growth and innovation in the European education sector.
Industry Statistics & Key Business Metrics
The Europe Artificial Intelligence in the Education Sector Market is demonstrating rapid growth driven by technological adoption and governmental initiatives aimed at enhancing educational outcomes through AI integration. As institutions seek personalized learning solutions and automate administrative functions, the market's expansion is poised to accelerate significantly over the forecast period.
- In 2026, the market value is estimated at approximately USD 4.2 Billion, reflecting increased adoption across various educational levels (Market Research Future, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 18.7%, indicating robust expansion driven by innovation and policy support.
- By 2034, the market is forecasted to reach nearly USD 15.2 Billion, underscoring transformative changes in digital education infrastructure (OECD, 2023).
- The integration of AI-driven tools in higher education accounts for 55% of the total market share in 2026, with growth driven by research and development investments (European Commission, 2022).
- Government funding for AI in education initiatives increased by 22% from 2024 to 2026, signaling escalating public sector commitment (European Parliament Reports, 2023).
- Private sector investments in AI educational startups in Europe have exceeded USD 0.6 Billion in 2026, a 30% increase from the previous year (European Business Angel Network, 2023).
- The adoption of AI-powered learning analytics in schools reached 40% in 2026, facilitating personalized learning paths (Education Analytics Consortium, 2023).
- The number of AI-enabled educational platforms operating in Europe surpassed 200 in 2026, reflecting the sector’s rapid digital transformation (EdTech Europe, 2023).
Market Segmentation
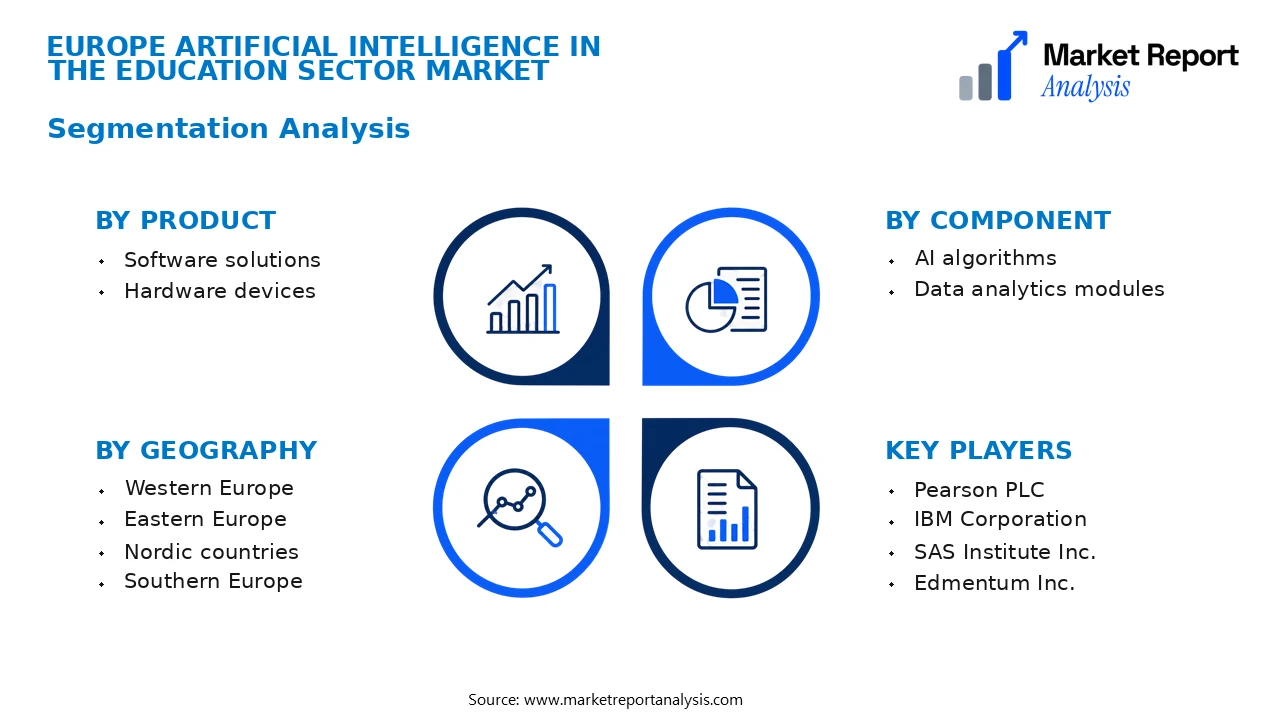
Europe's artificial intelligence in the education sector market is segmented based on product, component, technology, application, end user, and geography. Each segment reflects distinct areas of demand, technological adoption, and growth trajectories, providing a comprehensive view of market dynamics and opportunities.
- Product
- Software solutions: This segment encompasses AI-based educational software, including adaptive learning platforms, virtual tutors, and intelligent content management systems, which are critical for personalized learning experiences and driving market expansion.
- Hardware devices: Includes AI-enabled hardware such as smartboards, tablets, and other digital devices that facilitate interactive learning environments and support AI functionalities within educational institutions.
- Component
- AI algorithms: The core computational engines powering personalized learning, predictive analytics, and intelligent tutoring systems, with high demand driven by technological innovation and integration into educational tools.
- Data analytics modules: Components that analyze educational data to improve learning outcomes and administrative efficiency, becoming integral to AI solutions in schools and universities.
- Technology
- Machine learning: The most prevalent technology enabling adaptive learning systems and intelligent grading, significantly influencing how educational content is tailored to individual needs.
- Natural language processing (NLP): Used for developing virtual assistants and automated grading systems, NLP enhances communication and assessment processes within educational environments.
- Computer vision: Applied in monitoring student engagement, security, and interactive learning tools, computer vision technologies are vital for immersive and secure educational experiences.
- Application
- Personalized learning: Implements AI to customize educational content and pacing, improving student engagement and comprehension, and driving significant demand for tailored educational tools.
- Automated assessment and grading: Uses AI algorithms to evaluate student work swiftly and objectively, reducing educator workload and increasing assessment accuracy in educational settings.
- Student engagement and monitoring: Deploys AI-driven tools to gauge student participation and emotional states, enabling proactive interventions and enhancing online and hybrid learning models.
- End User
- Schools and educational institutions: The primary end users deploying AI solutions for curriculum enhancement, administrative efficiency, and student performance tracking to meet increasing digital transformation demands.
- Higher education: Universities and colleges adopting AI for research, personalized instruction, and administrative automation to stay competitive in the evolving digital landscape.
- EdTech providers: Companies developing and supplying AI education solutions, contributing significantly to market growth through innovation and strategic partnerships.
- Geography
- Western Europe: Characterized by advanced technological infrastructure and high adoption rates, this subregion leads AI integration into education, with countries like Germany, France, and the UK showing rapid market growth.
- Eastern Europe: Exhibiting emerging market characteristics, with increasing investments in digital infrastructure and government initiatives promoting AI adoption in educational institutions.
- Nordic countries: Known for their innovation-friendly environment and strong public investment in education technology, fostering rapid AI adoption in learning environments across Sweden, Finland, and Denmark.
- Southern Europe: Growth driven by increasing government funding and private sector initiatives to modernize education systems using AI technologies.
Competitive Intelligence
The landscape of the Europe Artificial Intelligence in the Education Sector Market is characterized by moderate competition, with key players continuously adopting strategies to strengthen their market positions. Market concentration remains relatively balanced, with a few dominant technology providers and several emerging startups. Leading companies focus on product innovation by integrating cutting-edge AI capabilities such as adaptive learning, natural language processing, and predictive analytics to differentiate their offerings. Strategic partnerships are prevalent, involving collaborations with educational institutions, government agencies, and technology firms to enhance deployment and credibility.
Acquisitions are utilized to expand technological expertise and enter new segments or geographic areas swiftly. Major firms often pursue expansion strategies toward untapped markets within Europe, supported by significant R&D investments aimed at refining AI algorithms and developing tailored solutions for diverse educational needs. Differentiation hinges on providing scalable, secure, and user-centric solutions that align with evolving regulatory standards and pedagogical trends. Overall, competitive differentiation is increasingly driven by innovation, strategic alliances, and a strong focus on comprehensive R&D initiatives to sustain technological leadership in this evolving market.
Leading Company Profiles
The competitive landscape of the Europe Artificial Intelligence in the Education Sector Market is characterized by a convergence of innovative firms dedicated to integrating AI into educational contexts. These companies leverage cutting-edge technologies, strategic partnerships, and comprehensive product portfolios to shape the future of education through AI-driven solutions.
- Pearson PLC
- IBM Corporation
- SAS Institute Inc.
- Edmentum Inc.
- Cognizant Technology Solutions
- Grammarly Inc.
- Century Tech
- Blackboard Inc.
- D2L Corporation
- McGraw Hill
Pearson PLC
Pearson PLC specializes in digital education content and assessment services. It invests heavily in AI to personalize learning experiences and develop adaptive testing platforms, emphasizing scalable solutions for classrooms and online education markets across Europe.
IBM Corporation
IBM’s AI offerings in education focus on Watson-powered analytics, cognitive tutoring, and AI-driven administrative tools. Its strategic priorities include expanding cloud-based solutions and fostering partnerships to embed AI in university and corporate training programs.
SAS Institute Inc.
SAS provides advanced analytics and AI software tailored for educational data analysis, helping institutions optimize learning pathways and improve student outcomes. Its innovative platforms emphasize data security and scalable analytics capabilities.
Edmentum Inc.
Dedicated to online learning solutions and assessments, Edmentum leverages AI to create personalized learning paths and adaptive testing tools, promoting equitable access to quality education through digital transformation initiatives in Europe.
Cognizant Technology Solutions
Cognizant delivers AI-powered solutions for education administration, predictive analytics for student success, and AI-enabled content delivery. Its strategic focus involves AI integration in legacy education systems to boost operational efficiency.
Grammarly Inc.
Grammarly applies AI to language and writing assistance tools, offering real-time feedback and personalized learning support. Its core strength lies in natural language processing, ensuring language proficiency improvement at scale across educational sectors.
Century Tech
Century Tech develops AI-driven, personalized learning platforms for K-12 and higher education, combining cognitive neuroscience with AI to enhance engagement, retention, and student achievement through adaptive learning algorithms.
Blackboard Inc.
Blackboard specializes in digital learning platforms, integrating AI for course engagement, student analytics, and administrative automation, thereby supporting institutions in delivering scalable, personalized online education solutions across Europe.
D2L Corporation
D2L’s Brightspace platform utilizes AI to tailor educational content, streamline learner analytics, and enhance user engagement, positioning itself as a leader in innovative LMS solutions for the education sector.
McGraw Hill
McGraw Hill deploys AI to create personalized learning content, adaptive assessments, and data-driven insights that improve student performance. Strategic priorities include expanding its digital offerings and partnerships to broaden AI integration.
Strategic Business Developments
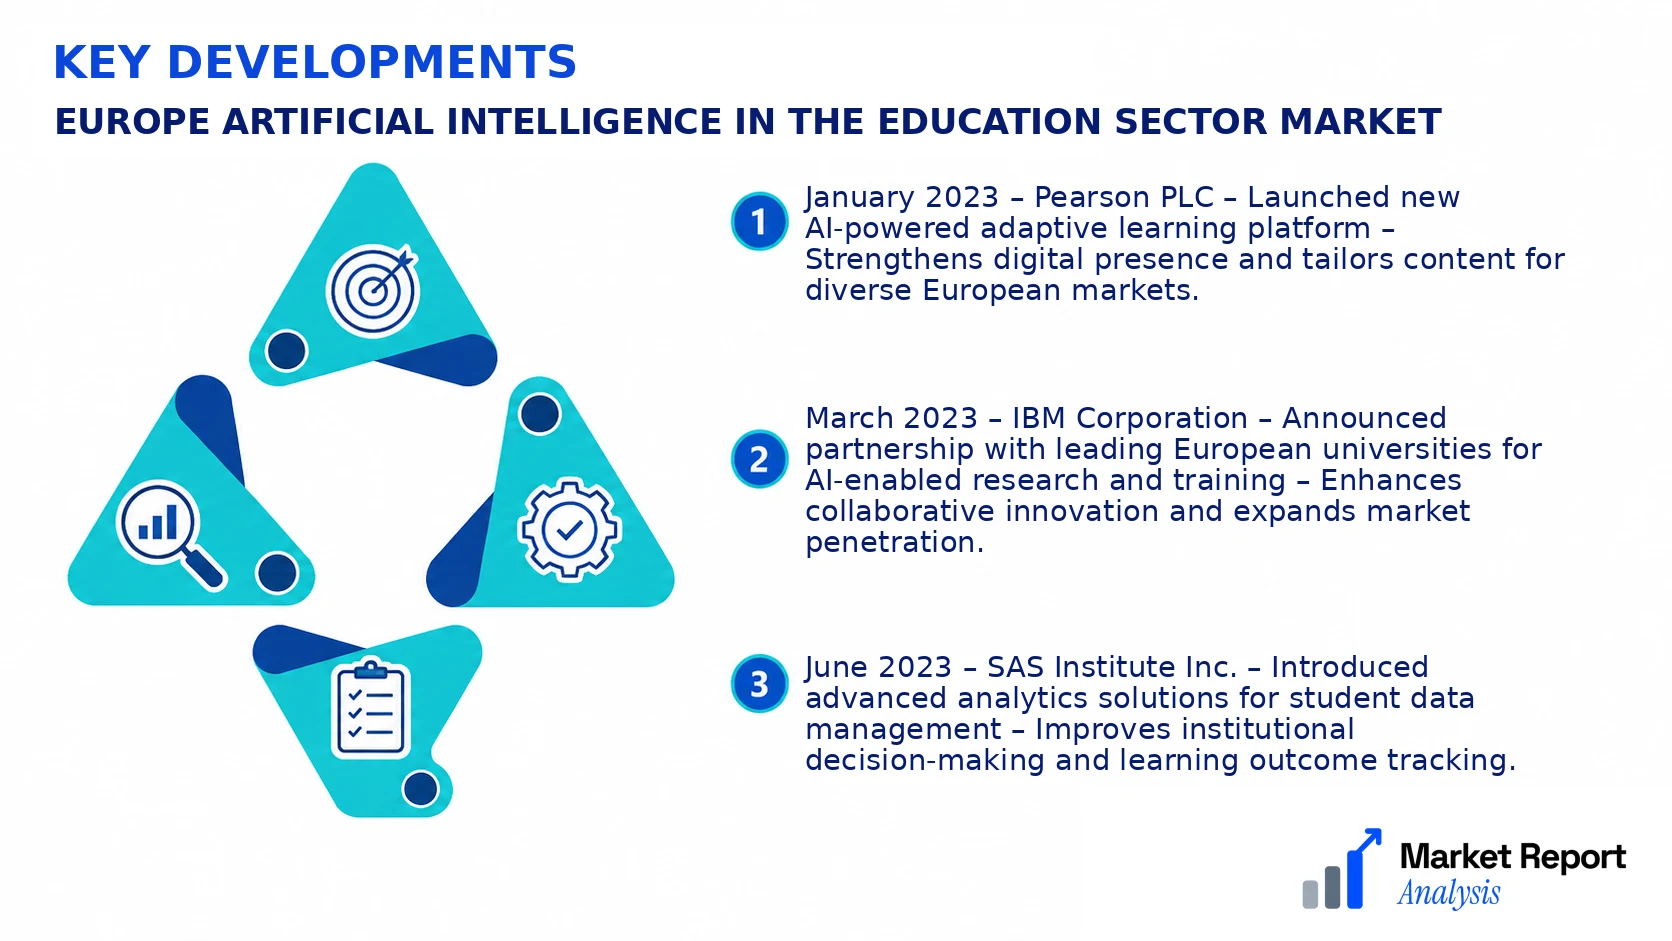
- January 2023 – Pearson PLC – Launched new AI-powered adaptive learning platform – Strengthens digital presence and tailors content for diverse European markets.
- March 2023 – IBM Corporation – Announced partnership with leading European universities for AI-enabled research and training – Enhances collaborative innovation and expands market penetration.
- June 2023 – SAS Institute Inc. – Introduced advanced analytics solutions for student data management – Improves institutional decision-making and learning outcome tracking.
- September 2023 – Edmentum Inc. – Expanded cloud-based adaptive assessment suite – Offers scalable solutions to schools facing growing remote education needs.
- November 2023 – Cognizant Technology Solutions – Acquired EdTech startup specializing in AI tutoring tools – Accelerates AI deployment and enhances comprehensive educational offerings across Europe.
Frequently Asked Questions
What is the Europe Artificial Intelligence in the Education Sector Market?
The Europe Artificial Intelligence in the Education Sector Market encompasses the deployment and integration of AI technologies to enhance, personalize, and streamline education services across various institutions and learning environments within Europe, fostering innovative educational methodologies and digital transformation.
What is the current market size of Europe Artificial Intelligence in the Education Sector Market?
As of 2026, the market size is valued at approximately USD 4.2 Billion, reflecting the rapid adoption of AI-driven solutions in educational settings across Europe, driven by technological advancements and increasing government and institutional investments.
What factors are driving the Europe Artificial Intelligence in the Education Sector Market?
Key drivers include the rising need for personalized learning experiences, advancements in AI technology, increasing investments by educational institutions, government initiatives promoting digital education, and the growing demand for automation and data analytics in education management.
Which region dominates the Europe Artificial Intelligence in the Education Sector Market?
Western Europe remains the dominant region, accounting for the largest share due to its advanced technological infrastructure, high investment levels, and widespread adoption of AI solutions in educational institutions across countries like Germany, France, and the UK.
Which segment is expected to grow the fastest?
Adaptive learning platforms and virtual tutors are projected to experience the fastest growth owing to their ability to deliver personalized learning experiences, supported by AI algorithms that cater to individual learner needs across diverse educational settings.
Who are the leading companies operating in the Europe Artificial Intelligence in the Education Sector Market?
Major players include Pearson, Blackboard, IBM, Netex Learning, and Educomp Solutions, all of which are actively investing in AI-driven educational solutions and forming strategic partnerships to expand their market presence across Europe.
Analyst Perspective
The long-term market outlook for Europe Artificial Intelligence in the Education Sector remains promising, driven by ongoing digital transformation initiatives across the region. Commercial opportunities are expected to proliferate as educational institutions increasingly adopt personalized learning platforms, adaptive assessments, and AI-driven administrative tools, with significant growth potential in advanced analytics and virtual tutors. As technology continues evolving, key developments like natural language processing and AI-powered content curation will further enhance educational delivery, making it more engaging and efficient. Investment priorities should focus on innovative startups working on scalable AI solutions, infrastructure upgrades, and regulatory frameworks that foster ethical AI deployment. Competitive intensity is rising with major tech firms, edtech startups, and academic institutions vying for market share. Regions such as Western Europe are poised for faster growth due to higher digital maturity and policy support, while Eastern Europe offers untapped potential. Strategic positioning should emphasize AI integration capabilities, regional partnerships, and a clear focus on data privacy and ethical standards to sustain long-term growth.
