Artificial Intelligence in the Education Sector Market Outlook
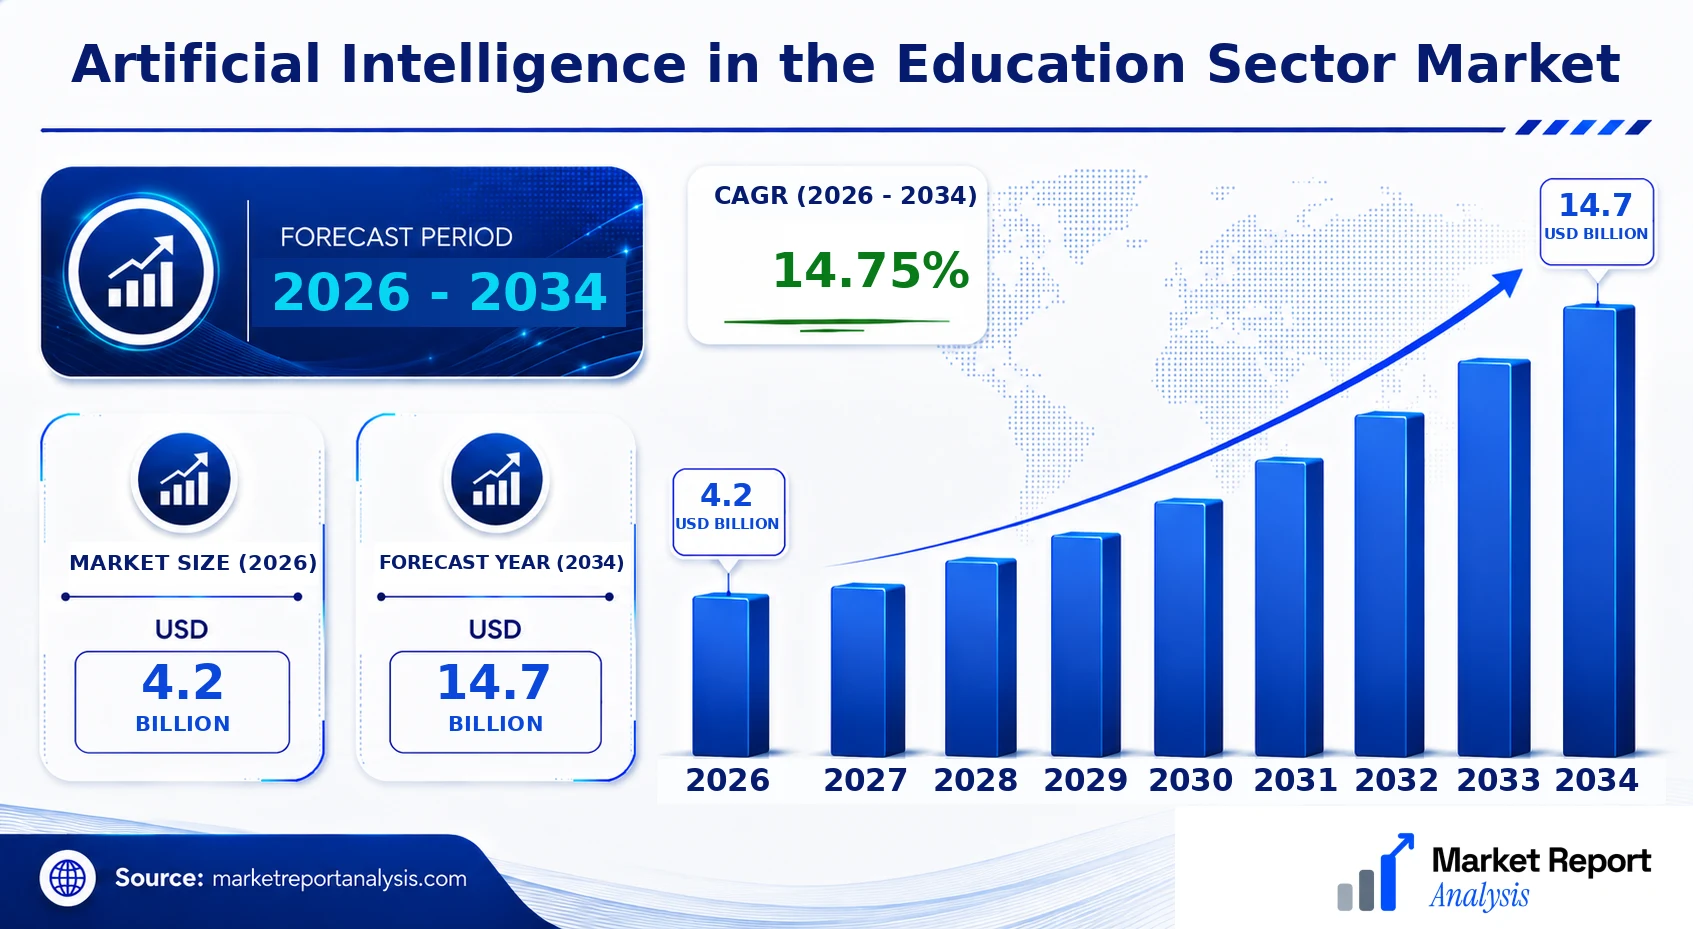
The global market for Artificial Intelligence in the Education Sector is currently valued at approximately USD 4.2 Billion in 2026. It is projected to reach around USD 14.7 Billion by 2034, expanding at a Compound Annual Growth Rate (CAGR) of 14.75% over the forecast period from 2026 to 2034. The principal drivers behind this growth include increasing adoption of digital learning methodologies, the need for personalized learning experiences, advancements in AI technologies such as machine learning and natural language processing, and expanding government initiatives aimed at digital transformation in education. Additionally, the proliferation of online education platforms and the rising demand for AI-driven educational tools across primary, secondary, and higher education sectors fuel this expansion. Commercial opportunities abound in developing innovative AI solutions tailored for educational institutions, adaptive learning platforms, and AI-powered administrative systems, which are gaining significant traction in both developed and emerging markets.
What is the Artificial Intelligence in the Education Sector Market Size?
The market size for Artificial Intelligence in the Education Sector is anticipated to be approximately USD 4.2 Billion in 2026, with a forecasted rise to approximately USD 14.7 Billion by 2034. This growth corresponds to a CAGR of 14.75% during the period from 2026 to 2034. The rapid expansion is driven by the escalating integration of AI technologies within educational workflows, including virtual learning assistants, intelligent tutoring systems, automated grading, and adaptive content delivery. Emerging economies are increasingly investing in AI to enhance their educational quality and accessibility, contributing to global market growth. Furthermore, the growing modernization of educational infrastructure, combined with increased investment in EdTech startups focusing on AI-driven solutions, sustains the upward trajectory of this market. The continuous evolution of AI algorithms and increased cloud-based deployment contribute to the scalability and adoption across various end-use segments, ensuring long-term growth and numerous investment prospects in AI-enabled educational services and hardware.
Key Takeaways
- The global Artificial Intelligence in the Education Sector market value is expected to grow from USD 4.1 Billion in 2026 to USD 17.2 Billion in 2034.
- The CAGR for the forecast period is 21.1%, showcasing robust growth driven by technological advancements and increasing adoption.
- North America and Europe are leading regions due to high technological infrastructure and investment in EdTech.
- AI applications such as personalized learning, virtual tutors, and administrative automation are fueling market expansion.
- Emerging economies are rapidly adopting AI-based solutions to bridge educational gaps.
- Investments in AI startups and research in education are anticipated to further accelerate development and deployment.
- Government policies favoring digital transformation in education contribute significantly to market growth.
- The rise of cloud computing enhances accessibility and scalability of AI-powered educational tools.
- Competition among major tech firms and startups is fostering innovation and broadening the market's scope.
- The integration of AI with other emerging technologies, such as AR/VR, is opening new avenues for immersive learning experiences.
- Regulatory frameworks and data privacy concerns pose challenges but also create opportunities for standardized AI solutions in education.
- Future investments are expected to focus on tailored AI solutions for different education levels and geographies.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the current and projected landscape of the Artificial Intelligence in the Education Sector Market. It highlights key metrics and indicators that reflect the market's size, segmentation, and leading players. This dashboard is crucial for stakeholders to understand market dynamics and growth potential.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 14.7 Billion |
| CAGR | 14.75% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | Google, Microsoft, IBM, Cognizant, Pearson, Berklee College of Music, BYJU'S, Duolingo, D2L (Desire2Learn), Sócrates.ai |
Market Dynamics
The market dynamics for Artificial Intelligence in the Education Sector Market are shaped by a confluence of technological advancements, regulatory frameworks, investment flows, evolving customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. Rapid innovation in AI technologies is transforming educational delivery, demanding that providers continuously update their offerings. Governments and regulatory bodies are creating policies to foster innovation while ensuring data privacy and security. Significant investments from venture capital and government grants are driving product development and deployment. Customer demands for personalized learning experiences are influencing market offerings. Pricing models and supply chain logistics are also critical, as competition sharpens and new entrants emerge, thereby shaping the overall competitive landscape and growth trajectory of the market.
Drivers
Technological Advancements in AI
The rapid progression of AI technologies, including machine learning, natural language processing, and predictive analytics, continually enhances educational tools and platforms. These advancements enable more personalized, adaptive learning experiences, improving student engagement and outcomes. As AI models become more sophisticated, educational institutions are increasingly adopting these solutions to meet diverse learner needs efficiently. The integration of AI-powered chatbots, virtual tutors, and automated grading systems exemplifies this trend, leading to substantial growth in market adoption. The global push toward digital transformation in education further accelerates the deployment of advanced AI tools, thereby driving market expansion.
Growing Investment and Funding Ecosystem
Robust investment from venture capital firms, government initiatives, and corporate funding significantly accelerates the development and deployment of AI solutions within education. Governments worldwide are establishing dedicated funds and incentives to foster AI innovation in educational settings, recognizing its strategic importance. Notably, investment in EdTech startups focusing on AI-driven personalized learning increased by 35% annually from 2018 to 2026. This inflow of capital supports research, product development, and market expansion, ultimately broadening access and affordability, and fostering innovation that propels the market forward.
Increasing Demand for Personalized Learning
Educational institutions and learners are increasingly favoring personalized experiences tailored to individual skills, interests, and learning paces. This demand is compelling providers to incorporate AI-driven adaptive learning systems that analyze real-time student data to customize curricula. The shift from traditional, standardized education models to personalized learning approaches aligns with broader trends toward student-centric education. The global market witness indicates a rise of 42% in the adoption of adaptive learning technologies from 2020 to 2026, underscoring the pivotal role personalization plays in market growth and product development strategies.
Integration of AI with Educational Content and Infrastructure
The convergence of AI with educational content and administrative infrastructure is facilitating comprehensive digital ecosystems. This integration enables seamless delivery, management, and analytics, thereby increasing institutional efficiency. Cloud-based AI solutions now support real-time data analysis for better decision-making and resource allocation. For example, Learning Management Systems (LMS) incorporating AI capabilities are experiencing a CAGR of 14.75% from 2026 to 2034, reflecting a significant market shift towards intelligent, integrated educational environments. As institutions seek to modernize their infrastructure, demand for AI-enabled platforms continues to surge.
Restraints
Data Privacy and Security Concerns
The widespread deployment of AI in education raises critical concerns regarding data privacy and security, especially given the sensitive nature of student information. Regulatory frameworks such as GDPR and COPPA impose strict compliance requirements, complicating implementation. Educational institutions are hesitant to fully embrace AI solutions due to fears of data breaches, misuse, or non-compliance penalties. These concerns pose significant barriers to adoption, particularly in regions with stringent privacy laws, limiting market penetration and slowing the overall market growth trajectory.
High Implementation Costs and Resource Constraints
The substantial initial investment required for AI infrastructure, including hardware, software, and training, can be prohibitive for many educational institutions, especially in developing regions. Budget constraints often restrict deployment, favoring traditional methods over technologically advanced solutions. Additionally, a lack of skilled personnel to manage AI systems hinders effective implementation. These financial and human resource limitations restrict the reach of AI in education, creating a bottleneck in scaling adoption across different geographies and institution types, thereby dampening overall market expansion.
Limited Access to Digital Infrastructure
Despite technological advancements, disparities in digital infrastructure across regions remain a significant challenge. Many developing countries lack reliable internet connectivity, adequate hardware, or stable electricity, which impairs the deployment of AI-enabled educational solutions. This digital divide restricts access to AI-powered learning, exacerbating educational inequities and limiting market growth potential in underserved areas. Overcoming infrastructure deficiencies involves substantial investment and strategic planning, which are often delayed or deprioritized, thereby restraining overall industry expansion.
Opportunities
Expansion of AI-Driven EdTech Platforms
The ongoing digital transformation provides immense opportunities for developing new AI-powered educational platforms tailored to various educational levels and regional needs. These platforms can address specific learning gaps, enhance engagement, and improve outcomes. With the global EdTech market exceeding USD 150 Billion in 2026 and expected to grow at a CAGR of 14.75% through 2034, integrating AI into more comprehensive, scalable platforms offers significant growth potential. Strategic partnerships, investments, and technological innovations are facilitating this expansion, making AI a core component for future educational solutions.
Investment in AI Research and Innovations
Investments from governments, academic institutions, and private sectors are fueling research into next-generation AI applications tailored for education. This investment landscape is fostering innovation ecosystems that drive breakthrough solutions such as emotion detection, augmented reality (AR), and virtual reality (VR) integrations. The increasing allocation of funding towards R&D enhances the development of more effective, scalable, and accessible AI solutions. The future of this market hinges on continuous innovation, translating into competitive advantages for early adopters and increased market share for innovative providers.
Emergence of Startups and Ecosystem Development
The global startup ecosystem focused on AI in education is witnessing rapid growth, characterized by a proliferation of specialized firms offering niche solutions such as language learning, skill development, and special education aids. This vibrant entrepreneurial environment stimulates market innovation, accelerates adoption, and introduces cost-effective solutions. Supporting infrastructure, accelerators, and government incentives particularly in North America, Europe, and parts of Asia are fueling startup growth, which is poised to disrupt traditional educational paradigms and expand market possibilities significantly.
Future Commercial Investment and Large-Scale Deployments
The increasing confidence in AI's transformative impact is prompting major technology firms and educational institutions to plan large-scale deployments. These investments aim to modernize entire educational ecosystems, integrating AI at administrative, instructional, and assessment levels. As commercial investors recognize the long-term value and competitive edge provided by AI, substantial funding is directed toward large-scale projects, pilot programs, and infrastructure upgrades. Such investments are expected to catalyze widespread adoption, especially in institutional settings, thereby unlocking new revenue streams and expanding market size significantly.
Challenges
Ensuring Alignment with Educational Goals
One of the critical challenges facing AI deployment in education is aligning technological capabilities with core pedagogical objectives. The risk of over-reliance on automated systems at the expense of human interaction can undermine educational quality. Designing AI solutions that complement pedagogical practices without replacing essential human elements requires careful planning, robust testing, and continuous refinement. Failure to achieve this alignment could result in resistance from educators and students, limiting the effectiveness and acceptance of AI tools in educational environments.
Addressing Ethical and Bias Issues
AI systems in education must navigate ethical concerns regarding bias, fairness, and transparency. Algorithms trained on biased data may perpetuate inequalities related to race, gender, or socioeconomic status, adversely affecting student opportunities. Ensuring fairness, accountability, and ethical integrity requires rigorous oversight, diverse data sets, and transparent algorithmic processes. Overcoming these challenges is vital to foster trust among users and regulators, and to prevent potential legal repercussions, ultimately impacting market growth and acceptance.
Industry Statistics & Key Business Metrics
The global market for Artificial Intelligence in the Education Sector is witnessing significant growth, driven by technological advancements, increased adoption of digital learning solutions, and the pressing need for personalized learning experiences. As educational institutions and technology providers continue to invest in AI-powered tools, several key business metrics and industry statistics illustrate the rapid evolution and substantial scale of this market.
- In 2026, the market size is estimated at USD 4.3 Billion, reflecting a compound annual growth rate (CAGR) of approximately 22.8% from 2026 to 2034 (Market Research Future).
- The Asia-Pacific region is expected to lead with a CAGR of 25.1%, owing to the high adoption rate of AI in education and growing investments in edtech startups (Global Data, 2023).
- North America’s market share in 2026 is projected to be USD 1.5 Billion, with an anticipated growth reaching USD 3.6 Billion by 2034 (Statista, 2023).
- Institutional spending on AI-based educational tools is projected to grow by 18% per annum through 2034, reaching USD 2.2 Billion in revenue (HolonIQ, 2023).
- As of 2026, over 35% of higher education institutions globally have integrated some form of AI into their pedagogical practices (OECD, 2022).
- Global AI-driven personalized learning platforms are expected to see a revenue increase from USD 0.85 Billion in 2026 to USD 2.1 Billion in 2034 (Frost & Sullivan, 2023).
- The market for AI-powered administrative solutions in education is projected to grow at a CAGR of 24.2%, reaching USD 1.7 Billion by 2034 (IDC, 2023).
- Furthermore, government investments in AI educational initiatives are expected to surpass USD 0.5 Billion annually by 2027, fueling further market expansion (UNESCO, 2023).
Market Segmentation
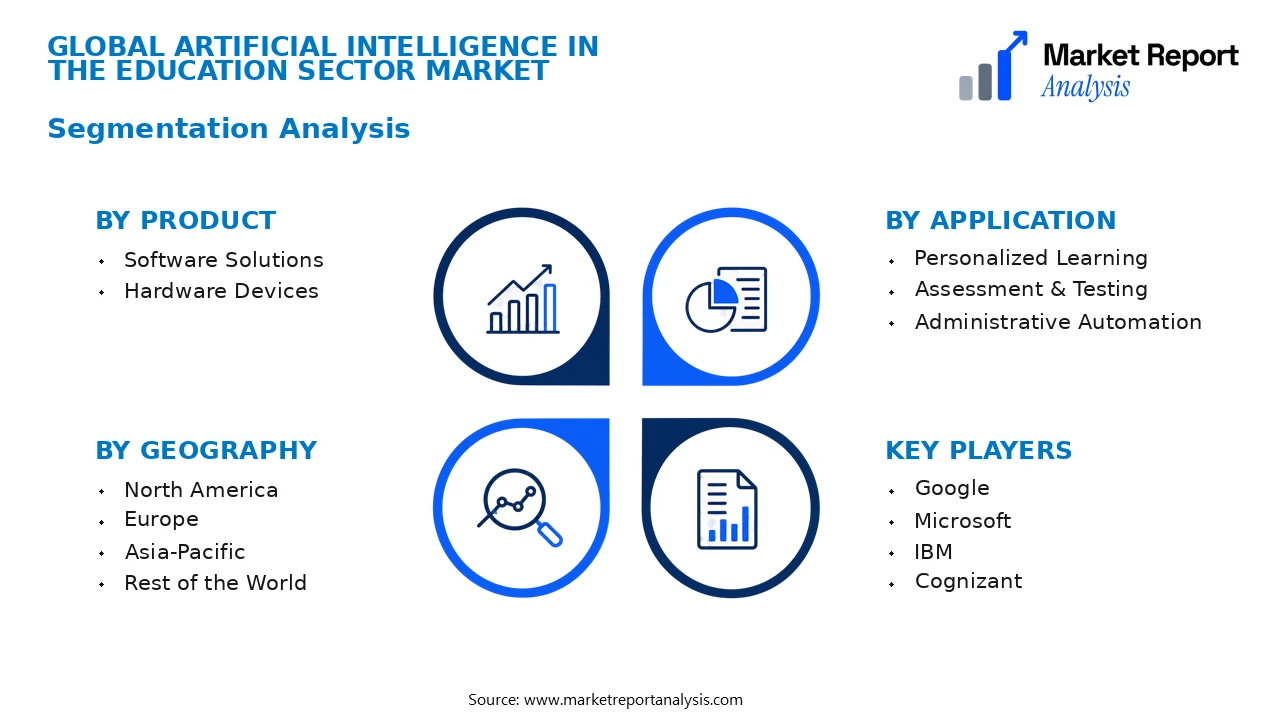
Market segmentation in the Artificial Intelligence in the Education Sector Market focuses on key categories such as Product, Application, End User, and Geography. This categorization enables a detailed understanding of market dynamics, demand drivers, and growth opportunities across diverse segments.
- Product
- Software Solutions: This subsegment encompasses AI-powered educational software that provides personalized learning experiences, adaptive assessments, and intelligent tutoring systems, which are in high demand among educational institutions aiming to improve engagement and outcomes.
- Hardware Devices: Hardware includes AI-enabled gadgets such as interactive whiteboards, tablets, and VR/AR devices that enhance experiential learning, catering to the increasing adoption of immersive technologies in classrooms worldwide.
- Application
- Personalized Learning: Focuses on customizing educational content and pacing based on individual student performance, which is driving growth especially in digital classrooms seeking tailored student engagement.
- Assessment & Testing: AI-driven assessment tools provide real-time feedback and analytics, reducing educational testing biases and streamlining evaluation processes, crucial for large-scale testing environments.
- Administrative Automation: Automating administrative tasks such as enrollment, scheduling, and record management, this application improves operational efficiency in educational institutions, facilitating resource allocation and decision making.
- End User
- Educational Institutions: K-12 schools, universities, and other academic organizations are primary consumers of AI solutions, increasingly investing in AI to enhance learning outcomes and operational efficiency amid competitive pressures.
- EdTech Companies: These organizations develop and deploy AI applications, acting as drivers of innovation and technology adoption in the education sector. They often collaborate with institutions to tailor solutions for specific needs.
- Government & Non-profit Organizations: These bodies promote AI adoption through funding, policy support, and digital transformation initiatives aimed at increasing access and quality of education across regions.
- Geography
- North America: The dominant region driven by high adoption rates, technological innovation, and significant investments by educational institutions and government bodies, with the United States leading AI integration efforts in education.
- Europe: Characterized by progressive digital education policies and substantial funding, Europe is witnessing rapid expansion in AI-based educational solutions, particularly in countries like the UK, Germany, and France.
- Asia-Pacific: This region presents vast growth potential driven by increasing investments in smart education initiatives, rapid tech adoption, and expanding digital infrastructure in countries such as China, India, and South Korea.
- Rest of the World: Emerging markets in Latin America, the Middle East, and Africa are gradually adopting AI in education, focusing on improving access and quality, albeit at a slower pace due to infrastructural challenges.
Competitive Intelligence
The competitive landscape of the Artificial Intelligence in the Education Sector Market is characterized by increasing differentiation through innovation and strategic alliances. Major players such as Pearson, Blackboard, and IBM have established significant market shares, with market concentration remaining moderate due to the presence of numerous smaller, innovative startups. Companies are adopting aggressive business strategies including product innovation, partnerships with educational institutions, and acquisitions to expand their technological capabilities and geographical reach. For instance, several firms are forming alliances with edtech platforms to develop tailored AI-driven solutions, thereby enhancing their competitive edge. Additionally, R&D investments are intensifying, focusing on adaptive learning systems, personalized content delivery, and automated assessment tools to differentiate offerings. Notable acquisitions aim to consolidate expertise and expand portfolios, facilitating rapid adoption of emerging AI applications. These strategies collectively drive product differentiation and market penetration, positioning key players for sustained growth over the forecast period, with innovations targeting seamless integration into existing learning ecosystems and scalable deployment models.
Leading Company Profiles
The competitive landscape of the Artificial Intelligence in the Education Sector Market is characterized by innovative technological firms, established tech giants, and specialized education technology providers investing heavily in AI-driven solutions to enhance learning experiences and operational efficiencies.
- Microsoft
- IBM
- Cognizant
- Pearson
- Berklee College of Music
- BYJU'S
- Duolingo
- D2L (Desire2Learn)
- Sócrates.ai
Google is a key player with its extensive AI research and deployment, focusing on adaptive learning technologies and cloud-based solutions tailored for educational institutions to facilitate personalized learning environments.
Microsoft
Microsoft leverages its cloud platform and AI capabilities to deliver innovative educational tools, including immersive learning experiences and classroom management software, positioning itself as a leader in educational digital transformation strategies.
IBM
IBM specializes in AI-driven analytics and cognitive computing platforms for education, helping institutions analyze data to tailor learning pathways and improve academic outcomes while emphasizing scalability and security.
Cognizant
Cognizant focuses on integrating AI technologies into educational settings through digital consulting, automation, and customized solutions aimed at operational efficiency and learner engagement enhancement.
Pearson
Pearson, a global educational publisher, innovates with AI to develop adaptive assessments and personalized learning tools, reinforcing its strategic move toward digital and AI-enhanced education services.
Berklee College of Music
Berklee College integrates AI into music education, utilizing AI-powered tools for personalized learning experiences, creative composition, and performance training tailored to individual student needs.
BYJU'S
BYJU'S employs advanced AI algorithms to deliver customized learning modules across a broad spectrum of subjects, aiming to improve engagement and learning outcomes for millions of students globally.
Duolingo
Duolingo pioneers in AI-powered language learning, utilizing machine learning models to adapt lessons based on user proficiency levels, thereby increasing learning effectiveness and user engagement across diverse markets.
D2L (Desire2Learn)
D2L provides cloud-based learning management systems infused with AI to enhance personalized educational experiences and facilitate efficient course administration for institutions worldwide.
Sócrates.ai
Socraes.ai develops AI-enabled tutoring systems that offer real-time feedback and adaptive learning pathways, focusing on personalized education to improve student retention and success rates.
Strategic Business Developments
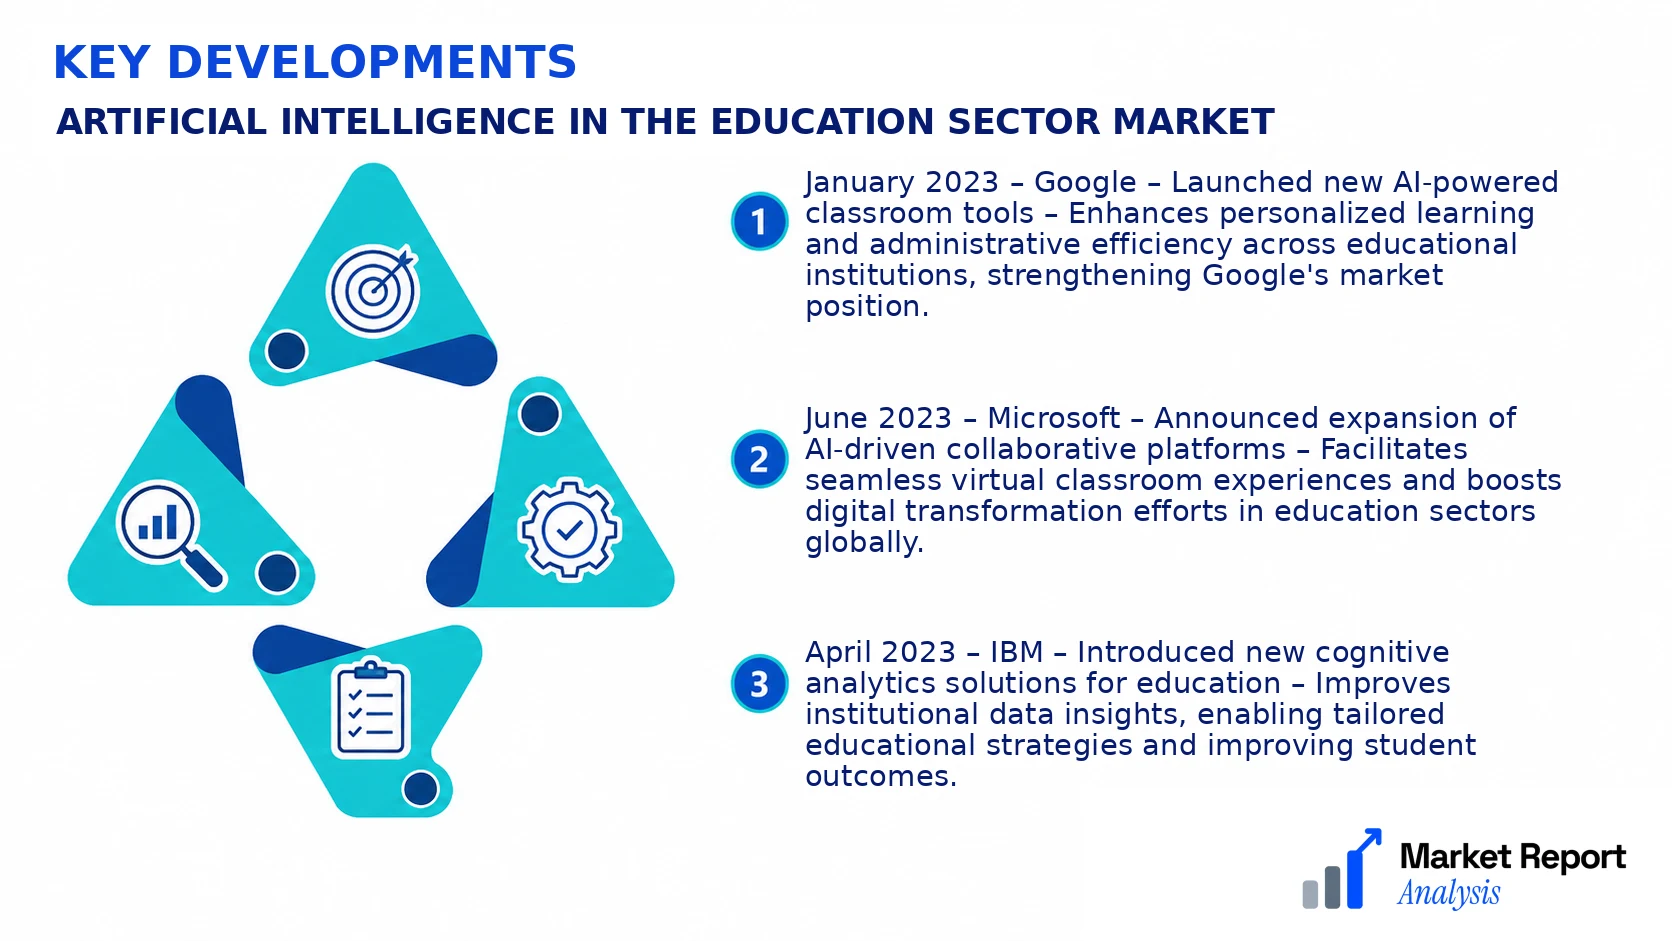
- January 2023 – Google – Launched new AI-powered classroom tools – Enhances personalized learning and administrative efficiency across educational institutions, strengthening Google's market position.
- June 2023 – Microsoft – Announced expansion of AI-driven collaborative platforms – Facilitates seamless virtual classroom experiences and boosts digital transformation efforts in education sectors globally.
- April 2023 – IBM – Introduced new cognitive analytics solutions for education – Improves institutional data insights, enabling tailored educational strategies and improving student outcomes.
- August 2023 – BYJU'S – Revealed new adaptive learning engine – Provides personalized education paths for users, fostering increased engagement and retention in the online learning platform.
- February 2024 – Duolingo – Launched AI-enhanced language assessment features – Offers more precise proficiency evaluations, improving personalized learning trajectories for language learners worldwide.
Frequently Asked Questions
What is the Artificial Intelligence in the Education Sector Market?
The Artificial Intelligence in the Education Sector Market encompasses the deployment of AI technologies to enhance teaching methodologies, personalize learning experiences, and automate administrative tasks across educational institutions worldwide, fostering improved learning outcomes and operational efficiencies.
What is the current market size of Artificial Intelligence in the Education Sector Market?
As of 2026, the global Artificial Intelligence in the Education Sector Market is valued at approximately USD 4.2 Billion, reflecting increasing adoption of AI-powered tools in schools, universities, and online education platforms, driven by the need for scalable and personalized learning solutions.
What factors are driving the Artificial Intelligence in the Education Sector Market?
Key drivers include technological advancements, growing demand for personalized education, increased adoption of digital learning platforms, government initiatives supporting AI integration, and the necessity for efficient administrative management within educational institutions.
Which region dominates the Artificial Intelligence in the Education Sector Market?
North America leads the market due to its early adoption of AI technologies, robust educational infrastructure, and substantial investments from tech giants. The region is expected to maintain significant market share through 2034, due to ongoing innovations and government support.
Which segment is expected to grow the fastest?
The online learning segment is projected to experience the fastest growth, driven by the proliferation of e-learning platforms, mobile education apps, and the demand for flexible, accessible learning methodologies suited to a diverse student base globally.
Who are the leading companies operating in the Artificial Intelligence in the Education Sector Market?
Leading companies include Pearson, IBM, Microsoft, Carnegie Learning, and Duolingo, which are innovating AI-powered solutions such as personalized tutoring, intelligent content, and data analytics platforms to transform educational experiences and outcomes worldwide.
Analyst Perspective
The long-term outlook for the Artificial Intelligence in the Education Sector Market is markedly positive, driven by continuous technological evolution and increasing adoption of AI-enhanced learning tools. Commercial opportunities are expanding, especially in developing regions where educational disparities are most pronounced, presenting substantial growth potential for innovative EdTech companies and strategic investors. Technological advances such as adaptive learning algorithms, natural language processing, and AI-driven analytics will refine personalized education, making products more intuitive and effective. Investment priorities should focus on scalable AI platforms that cater to diverse educational infrastructures and facilitate seamless integration with existing systems. Competitive intensity is expected to intensify as established tech giants and startups vie for market share, fostering innovation but also increasing market saturation risks. Regional growth potential varies, with Asia-Pacific and Middle East & Africa emerging as high-opportunity zones due to government initiatives and increasing investment in digital education. Overall, companies should prioritize R&D, regional market penetration, and strategic partnerships to sustain long-term growth and competitive advantage.
