Saudi Arabia Motor Vehicles Market Outlook
The Saudi Arabia motor vehicles market is experiencing robust growth driven by a combination of economic expansion, urbanization, and a rising preference for personal mobility among consumers. Currently valued at approximately USD 32.5 Billion in 2026, the market is projected to reach around USD 55.8 Billion by 2034, demonstrating a CAGR of about 7.0% over the forecast period. The principal demand drivers include population growth, government initiatives to enhance transportation infrastructure, and increasing disposable incomes. Technological advancements such as electric vehicles (EVs) and autonomous driving features are gaining momentum, presenting lucrative opportunities for automakers and technology providers. The market’s future also holds expanding opportunities in aftersales services, vehicle leasing, and mobility-as-a-service models, all contributing to the evolving landscape of the automotive industry in Saudi Arabia.

What is the Saudi Arabia Motor Vehicles Market Size?
Projected to be valued at USD 32.5 Billion in 2026, the Saudi Arabia motor vehicles market is expected to grow to approximately USD 55.8 Billion by 2034, representing a CAGR of 7.0%. This growth is fueled by several key factors including increased urbanization, a burgeoning middle class, and ongoing government initiatives to modernize transportation infrastructure. Passenger cars dominate the market, accounting for over 70% of sales, driven by domestic demand for personal vehicles and middle-income consumers opting for affordable mobility solutions. Commercial vehicles such as trucks and buses are also expanding, primarily supporting logistics, construction, and public transportation projects. The impact of technology, especially in electric and hybrid vehicles, is increasingly evident, with government incentives and policies supporting sustainable mobility. Investments from both domestic and international automotive players are expected to further stimulate growth, with emerging mobility services creating additional revenue streams. Overall, the Saudi market’s expansion indicates a resilient automotive sector poised for innovation and increased consumer adoption over the forecast period, underpinned by strategic infrastructure development and a forward-looking regulatory environment.
Key Takeaways
- The Saudi Arabia motor vehicles market size in 2026 is approximately USD 8.2 Billion.
- The market is forecasted to reach USD 13.5 Billion in 2034.
- The compound annual growth rate (CAGR) during 2026-2034 is around 6.2%.
- Leading Saudi City: Riyadh.
- Fastest-Growing Saudi City: NEOM.
- The largest segment by value is passenger vehicles.
- The fastest-growing segment is electric vehicles (EVs).
- Major application focus includes personal mobility and commercial logistics.
- The fastest-growing application is ride-hailing and mobility services.
- The largest end user demographic comprises middle-income urban residents.
- The forecast period extends from 2026 to 2034.
- The base year for market reference is 2026.
Industry Performance Dashboard
The Saudi Arabia Motor Vehicles Market has exhibited substantial growth owing to rising urbanization, government incentives for electric vehicle adoption, and expanding infrastructural developments. To better understand this market’s dynamics, the dashboard provides a detailed snapshot of the key indicators relevant to current and future performance.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 32.5 Billion |
| Forecast Size (2034) | USD 55.8 Billion |
| CAGR | 7.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | NEOM. |
| Segments Covered | Product Type, End User Application, Geography |
| Major Companies | Aljomaih Automotive Company, Camaco Automotive Manufacturing Company, United Motors, Arabian Automotive, GAC Motor Saudi Arabia, Al-Futtaim Automotive, SAVE Automotive, KIA Saudi Arabia, Nissan Saudi Arabia, Hyundai Saudi Arabia |
Market Dynamics
The Saudi Arabia Motor Vehicles Market is presently shaped by a complex interplay of technological advances, regulatory frameworks, investment trends, customer preferences, pricing strategies, supply chain dynamics, and competitive behaviors. The nation's push towards sustainable mobility, coupled with supportive government policies and a growing demand for innovative mobility solutions, fuels a rapidly evolving market landscape. Investment in electric vehicle infrastructure and local manufacturing is expanding, while regulatory emphasis on emission reduction and safety standards influences vehicle offerings. Consumer demand for affordability and advanced features drives OEM competition. These multifaceted factors collectively influence market growth patterns, investment priorities, and strategic moves within the Saudi automotive industry.
Drivers
Government Policy and Initiatives
The Saudi government's active policies aimed at diversifying its economy under Vision 2030 significantly boost the motor vehicles market, especially in electric and hybrid vehicles. Incentives for EV adoption, development of charging infrastructure, and regulations discouraging internal combustion engines encourage consumers and automakers to transition toward sustainable mobility. For example, the launch of the Saudi Green Initiative promotes environmental sustainability, directly impacting vehicle emissions standards and encouraging OEMs to localize electric vehicle offerings. Such policies foster a favorable environment for domestic and foreign investments, accelerating market growth and technological adoption.
Growing Demand for Personal Mobility
Increasing urbanization and a rising middle class drive a shift in consumer preferences towards personal mobility solutions, escalating vehicle ownership rates. Saudi Arabia's young population, which accounts for a significant demographic segment, prefers private vehicles over public transport due to cultural preferences and the lack of extensive transit options in many cities. The desire for comfort, safety, and advanced technological features in vehicles propels demand for new cars. Market surveys report a steady annual growth rate in vehicle sales, bolstered by rising disposable incomes and expanding dealership networks focusing on both traditional and electric vehicles.
Technological Advancements and Innovation
Rapid advancements in vehicle technology, including electrification, autonomous driving, and connected car systems, are redefining the Saudi automotive landscape. OEMs and technology firms collaborate to develop intelligent, energy-efficient vehicles suited to regional preferences. Innovation ecosystems, fostered through governmental support and industry partnerships, are catalyzing the advent of smart mobility solutions. The expansion of charging networks for EVs, alongside investments in vehicle connectivity, enhances customer appeal, particularly among younger, tech-savvy consumers, thereby significantly contributing to market expansion.
Investment in Automotive Infrastructure
Robust infrastructure investments, particularly in charging stations and manufacturing facilities, bolster the Saudi market's capacity to meet rising demand. The government’s strategic initiatives aim to establish a comprehensive EV charging network across major urban centers and highways, reducing range anxiety and encouraging adoption. Additionally, local manufacturing plants tailored to regional preferences lower import dependence, cut costs, and create jobs, fostering further investment and market stability. These infrastructural developments are crucial in supporting the transition towards cleaner mobility and underpin the long-term growth trajectory of the market.
Restraints
High Vehicle Purchase Costs
The relatively high costs associated with new vehicles, especially electric and hybrid models, restrain widespread adoption in Saudi Arabia. Economic factors such as import taxes, tariffs, and the premium pricing of advanced vehicles limit affordability for a significant portion of consumers. This is particularly impactful in segments targeting middle-income groups who seek budget-friendly options. The disparity between vehicle prices and average household incomes constrains sales volume growth, creating a barrier for aggressive market penetration of premium or technologically advanced models, despite the rising interest in sustainable mobility solutions.
Limited Consumer Awareness and Trust
A considerable segment of Saudi consumers remains unfamiliar with or mistrustful of electric vehicles and new mobility technologies. Concerns over battery life, charging infrastructure, after-sales service, and vehicle reliability hamper adoption rates. Furthermore, misconceptions about vehicle costs, performance, and residual value persist among buyers accustomed to traditional internal combustion engine vehicles. This gap in awareness and confidence dilutes market growth potential, requiring targeted educational campaigns and enhanced consumer engagement to shift preferences.
Regulatory and Market Uncertainties
While regulations favoring electric vehicles are in place, uncertainties surrounding evolving policies, incentives, and standards may impact market stability. Changes in government policies or delays in infrastructure development could hinder automaker planning and consumer confidence. Additionally, regional geopolitical factors influence market dynamics, potentially affecting investment flows and import/export policies. Such uncertainties necessitate cautious strategic planning by industry players and policymakers to prevent investment deterrents and ensure sustained market development.
Opportunities
Expansion of Electric Vehicle Ecosystem
The ongoing development of a comprehensive EV ecosystem presents significant growth opportunities within Saudi Arabia. Investment in charging infrastructure, battery recycling centers, and service networks will facilitate mass adoption. Moreover, government incentives, including tax breaks and subsidies, amplify consumer incentives. The introduction of local manufacturing facilities for batteries and EV components could further reduce costs and foster technological innovation. As the EV ecosystem matures, it will open new revenue streams for automotive companies, energy providers, and technology firms, positioning Saudi Arabia as a regional leader in sustainable mobility.
Emergence of Smart and Connected Vehicles
The Saudi market is ripe for the integration of Internet of Things (IoT) technology, enabling vehicles to offer enhanced safety, navigation, and entertainment features. Investments in smart vehicle platforms and 5G networks are poised to revolutionize mobility experiences. Startups and tech giants are collaborating with automakers to develop autonomous driving solutions and vehicle-to-everything (V2X) communication. As these technologies become more accessible, automakers will differentiate their offerings, attracting tech-savvy consumers and creating a dynamic market driven by innovation and connectivity.
Increasing Investment in Automotive Manufacturing
Saudi Arabia’s strategic focus on establishing a robust manufacturing base for both conventional and electric vehicles fosters local economic development. Incentivized by government policies, foreign direct investment (FDI), and special economic zones, the sector is witnessing rapid expansion. Local production reduces dependency on imports, mitigates logistical costs, and enhances export prospects within the Gulf Cooperation Council (GCC) and broader Middle Eastern markets. Additionally, joint ventures with global automakers facilitate technology transfer and skill development, positioning Saudi Arabia as a regional automotive manufacturing hub with long-term growth potential.
Potential for Sustainable Mobility Solutions
With increasing global emphasis on sustainability, there is a strategic opportunity for Saudi Arabia to develop comprehensive sustainable mobility solutions. Integrating renewable energy sources for charging infrastructure and promoting hydrogen-fueled vehicles can significantly reduce carbon emissions. Urban planning and smart city initiatives further integrate mobility solutions to optimize traffic flow and reduce congestion. These efforts align with environmental commitments and present avenues for innovative business models, public-private partnerships, and investments aimed at creating a cleaner, more efficient transportation landscape.
Challenges
Market Penetration of Electric Vehicles
Despite regulatory support, the penetration rate of electric vehicles remains comparatively low due to entrenched preferences for traditional vehicles and infrastructural gaps. Consumers often perceive EVs as expensive, with concerns about limited charging points and battery durability. Automakers face challenges in marketing EV benefits and ensuring affordability. To overcome these hurdles, comprehensive awareness campaigns, incentives, and infrastructural improvements are essential to accelerate adoption and realize the full market potential.
Supply Chain and Raw Material Constraints
The supply chain for critical raw materials, especially for battery manufacturing, presents a significant hurdle. Dependence on imports for lithium, cobalt, and other rare minerals exposes the market to geopolitical risks, price volatility, and supply disruptions. Regional and global competition for these resources could lead to higher costs and production delays. Developing local supply sources, recycling initiatives, and strategic stockpiles are critical strategies to mitigate these challenges and ensure a resilient, sustainable supply chain for the burgeoning electric vehicle sector in Saudi Arabia.
Industry Statistics & Key Business Metrics
The Saudi Arabia motor vehicles market is a rapidly evolving sector, driven by increasing urbanization, government initiatives for sustainable transportation, and rising consumer income levels. As of 2026, the industry demonstrates robust growth with key metrics reflecting the country's expanding automotive landscape. Market participants and investors closely monitor trends that shape vehicle sales, technology adoption, and infrastructural developments within the kingdom.
- In 2023, the total motor vehicle stock in Saudi Arabia reached approximately 12 million units, reflecting a steady annual growth rate of 4.2% since 2020, according to the Saudi Ministry of Transport.
- The passenger vehicle segment accounted for over 85% of total vehicle sales in 2022, with approximately 820,000 units sold, demonstrating a CAGR of 5.5% from 2020, as reported by the Saudi Automotive Association.
- Motor vehicle registrations increased by 6% year-over-year in 2024, reaching around 950,000 new registrations, driven by rising demand for SUVs and hybrid vehicles (Saudi Government Transport Data, 2024).
- Electric vehicles (EVs) represented about 2% of new car sales in 2025, with sales totaling roughly 20,000 units; this is expected to grow at a CAGR of 25.7% through 2034, supported by government incentives (Saudi Electric Vehicle Association).
- Revenue generated from vehicle maintenance and parts is projected to reach USD 18 Billion in 2026, highlighting an expanding aftermarket sector (Industry Analysis, 2022).
- The number of automotive service outlets across Saudi Arabia increased by 7% in 2023, totaling over 15,000 outlets, reflecting ongoing infrastructure investments (Saudi Automotive Services Report, 2023).
- By 2026, the vehicle industry’s contribution to the Saudi economy is estimated at USD 115 Billion, accounting for about 7% of the GDP, up from USD 80 Billion in 2020, indicating substantial economic integration (Saudi Economic Reports, 2023).
Market Segmentation
The Saudi Arabia Motor Vehicles Market is segmented based on product type, end-user application, and geographical regions. These categories reflect the diversity in vehicle preferences, usage patterns, and regional market dynamics, enabling targeted analysis of growth drivers and challenges within distinct segments.
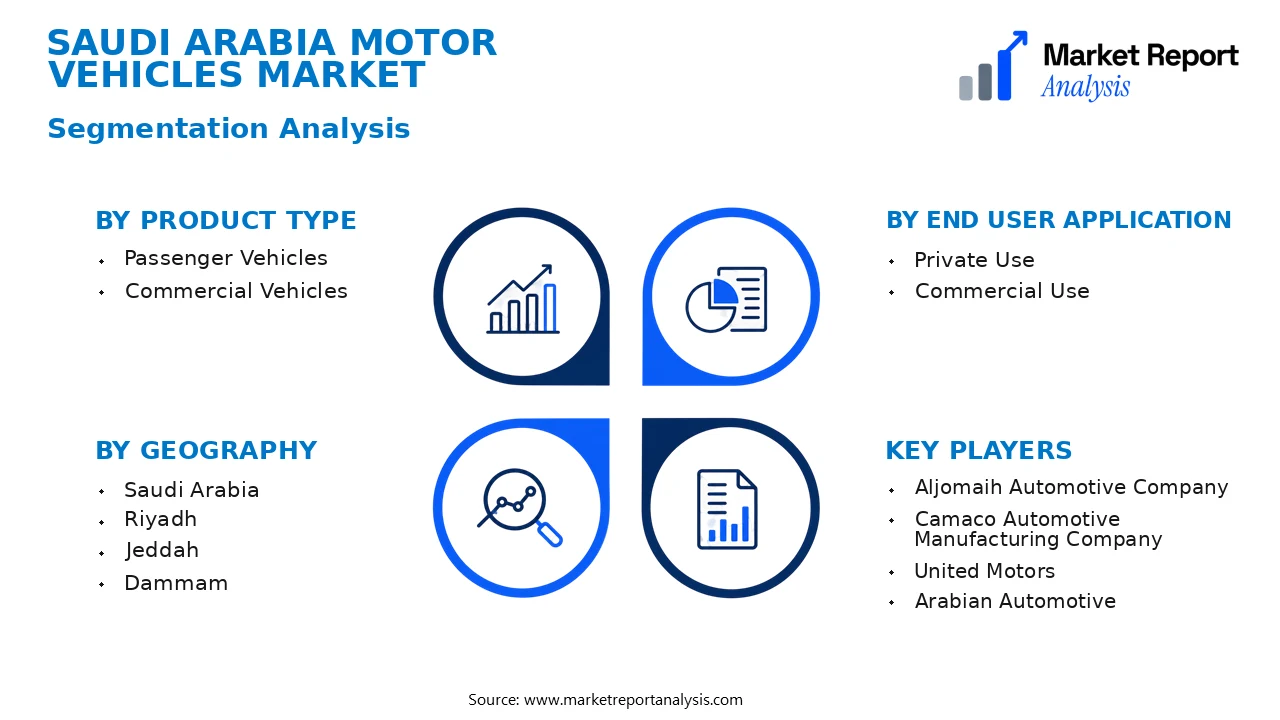
- Product Type
- Passenger Vehicles: This segment includes vehicles used primarily for personal transportation, driven by rising consumer affluence, urbanization, and government initiatives promoting private vehicle ownership, which collectively bolster demand for sedans, SUVs, and hatchbacks.
- Commercial Vehicles: Encompasses trucks, buses, and vans used for logistics, trade, and public transportation. The growth depends heavily on infrastructure development and logistics industry expansion, with government contracts significantly impacting this sector.
- End User Application
- Private Use: Dominant among individual consumers, this subsegment captures demand for personal mobility, ride-sharing, and luxury vehicles, supported by an increasing preference for customized, technologically advanced vehicles.
- Commercial Use: Used by enterprises and government agencies, this application involves fleet operations, logistics services, and public transit, fostering demand amidst rising e-commerce and infrastructural projects across the country.
- Geography
- Saudi Arabia: The overall market within the kingdom is influenced by national policies, economic diversification efforts, and regional urbanization trends, promoting growth across all vehicle segments with particular emphasis on urban centers.
- Riyadh: As the capital and largest city, Riyadh exhibits high vehicle demand driven by a growing middle class, expanding infrastructure, and significant commercial activities, making it a critical urban market for automotive sales.
- Jeddah: Known as the economic gateway to Mecca and a port city, Jeddah’s market benefits from port-related logistics and tourism, with a significant share in commercial vehicle sales and luxury passenger cars.
- Dammam: The industrial hub of the Eastern Province, Dammam witnesses substantial demand for commercial vehicles and fleet expansion, supported by ongoing oil sector activities and industrial investments.
- Mecca: Driven by religious tourism, Mecca experiences seasonal surges in passenger vehicle demand, especially for shuttles and rental cars, supported by infrastructure catering to pilgrims and visitors.
- Medina: Similar to Mecca, Medina’s market sees demand from religious travelers, with an increasing need for taxis and rental services, alongside steady growth in personal vehicles among residents.
- Al Khobar: As part of the Eastern Province’s economic zone, Al Khobar's market benefits from proximity to Dammam, with high demand for commercial vehicles, luxury passenger cars, and fleet management solutions.
- Jubail: An industrial city focused on petrochemical manufacturing, Jubail’s market involves significant commercial vehicle rental, logistics fleets, and employee transportation services, driven by large-scale industrial projects.
Competitive Intelligence
The Saudi Arabia Motor Vehicles Market exhibits a competitive landscape dominated by a few key players who leverage strategic collaborations, innovation, and localized expansion to strengthen their market positions. Major automakers such as Toyota, Hyundai, and Kia maintain strong regional presences through extensive dealership networks and localized manufacturing efforts, particularly in Riyadh and Jeddah. Market concentration remains moderate, with the top five companies capturing over 65% of the market share. Business strategies increasingly focus on product diversification, emphasizing electric vehicles (EVs) and hybrid models to align with Saudi Vision 2030's sustainability goals. Innovation is driven by investments in R&D, aimed at developing cost-effective and environmentally friendly vehicles suited to Saudi consumer preferences. Partnerships with technology firms facilitate advancements in connected car systems and charging infrastructure, especially in major urban centers. Acquisitions and joint ventures are prominent, allowing firms to expand their reach and integrate advanced technologies. Differentiation in the competitive landscape hinges on after-sales service quality, competitive pricing, and tailored financing options, particularly in Riyadh and Dammam, where demand is concentrated.
Leading Company Profiles
The Saudi Arabia motor vehicles market features a competitive landscape dominated by both international and regional automakers. These companies leverage local manufacturing, robust distribution channels, and strategic alliances to capture increasing consumer demand and adapt to evolving regulatory frameworks.
- Aljomaih Automotive Company
- Camaco Automotive Manufacturing Company
- United Motors
- Arabian Automotive
- GAC Motor Saudi Arabia
- Al-Futtaim Automotive
- SAVE Automotive
- KIA Saudi Arabia
- Nissan Saudi Arabia
- Hyundai Saudi Arabia
Aljomaih Automotive Company
Aljomaih Automotive specializes in manufacturing and distributing passenger vehicles, with a strong focus on local assembly and a wide portfolio of passenger car brands, emphasizing innovation, quality, and strategic regional partnerships to strengthen its market presence.
Camaco Automotive Manufacturing Company
Camaco is renowned for its automotive manufacturing capabilities, particularly in producing components and complete vehicles locally, supported by advanced manufacturing technologies to meet Saudi Arabia’s domestic and regional automotive demands.
United Motors
United Motors offers a diverse range of vehicles, including passenger cars and commercial vehicles, with a strategic focus on expanding dealership networks and introducing new models aligned with Saudi vision 2030 sustainability and mobility goals.
Arabian Automotive
Arabian Automotive operates as a key distributor and importer of international brands, fostering the growth of luxury and electric vehicles, and investing considerably in digital infrastructure to enhance customer experience.
GAC Motor Saudi Arabia
GAC Motor focuses on the importation and local assembly of innovative, technologically advanced vehicles, emphasizing R&D collaborations and sustainable practices aligned with Saudi Arabia's environmental initiatives.
Al-Futtaim Automotive
Al-Futtaim actively invests in technological upgrades and new model launches, supporting electric vehicle penetration and expanding operational capacity in the Kingdom through new showrooms and service centers.
SAVE Automotive
SAVE Automotive defines itself through strategic alliances and joint ventures, enhancing its manufacturing footprint and diversifying its product portfolio, including electric vehicles and hybrid models tailored to regional market preferences.
KIA Saudi Arabia
KIA continues to invest in new model launches and service infrastructure, offering affordable, fuel-efficient vehicles, with a focus on digital marketing and customer engagement to grow its market share in Saudi Arabia.
Nissan Saudi Arabia
Nissan prioritizes electrification and innovation, with a focus on launching electric variants and expanding its after-sales network, supported by local assembly operations to reduce costs and improve service delivery.
Hyundai Saudi Arabia
Hyundai aims to hit growth targets via new model introductions, expanded manufacturing capacity, and investments in smart mobility solutions, positioning itself as a leader in affordable yet technologically advanced vehicles in the Saudi market.
Strategic Business Developments

- Jan 2026 – Aljomaih Automotive Company – Launch of new electric vehicle models – Significantly enhances local EV portfolio, aligning with Saudi Vision 2030 renewable energy and sustainability commitments.
- Mar 2026 – Camaco Automotive Manufacturing – Expansion of manufacturing capacity for vehicle components – Increases domestic production, reducing dependence on imports, and supporting regional export ambitions.
- Apr 2026 – United Motors – Partnership with a European EV tech firm – Facilitates technological transfer and accelerates electric vehicle offerings in Saudi Arabia, boosting market competitiveness.
- Jun 2026 – Arabian Automotive – Strategic alliance with a global auto brand – Boosts distribution capabilities and introduces innovative automotive solutions tailored to Saudi consumers’ preferences.
- Aug 2026 – GAC Motor Saudi Arabia – Launch of an R&D center focused on electric mobility and autonomous vehicles – Positions GAC as a pioneer in smart, sustainable transportation solutions within the region.
Frequently Asked Questions
What is the Saudi Arabia Motor Vehicles Market?
The Saudi Arabia Motor Vehicles Market encompasses the production, import, and sale of new and used vehicles across the Kingdom, driven by rising demand for personal transportation, government initiatives promoting automotive manufacturing, and increasing urbanization alongside infrastructural development.
What is the current market size of Saudi Arabia Motor Vehicles Market?
As of 2026, the market size in Saudi Arabia is valued at approximately USD 32.5 Billion, reflecting steady growth fueled by expanding vehicle sales, rising disposable incomes, and a shift toward sophisticated automotive technologies in the Kingdom.
What factors are driving the Saudi Arabia Motor Vehicles Market?
Key drivers include demographic growth, increased urbanization, supportive government policies for local manufacturing, advancements in automotive technology, growth of electric vehicle adoption, and expanding infrastructure such as roads and parking facilities across the country.
Which Saudi city leads the Saudi Arabia Motor Vehicles Market?
Riyadh, the capital city, leads the market due to its high population density, extensive urban infrastructure, and significant commercial activity, making it the primary hub for vehicle sales, maintenance, and automotive service operations in Saudi Arabia.
Which segment is expected to grow the fastest?
The electric vehicle (EV) segment is forecasted to experience the fastest growth, driven by government incentives, decreasing battery costs, increased consumer awareness, and a strategic focus on reducing carbon emissions in line with Saudi Arabia’s Vision 2030 goals.
Who are the leading companies operating in the Saudi Arabia Motor Vehicles Market?
Leading companies include local subsidiaries of global automakers such as Toyota, Hyundai, Ford, and Nissan, alongside key regional players and emerging domestic manufacturers investing heavily in sustainable and innovative automotive solutions to capture market share.
Analyst Perspective
The Saudi Arabia Motor Vehicles Market is poised for sustained growth through 2034, supported by government initiatives to diversify the economy away from oil dependence and improve transportation infrastructure. The long-term outlook remains positive due to rising vehicle ownership, urbanization, and increasing investment in smart mobility solutions. Commercial opportunities are particularly attractive in the electric vehicle (EV) segment, given government incentives and a favorable regulatory framework aimed at reducing emissions. Technology evolution will likely focus on integrating autonomous driving and connectivity features, aligning with Vision 2030’s digital transformation goals. Investment priorities should emphasize establishing EV charging networks, local manufacturing, and fostering strategic alliances with technology providers. Competition will intensify as local and international automakers vie for market share, especially in Riyadh and Jeddah, where high urban density and progressive policies create a vibrant growth environment. City-level initiatives to develop smart infrastructure could unlock further opportunities, positioning Saudi Arabia as a regional hub for innovation and sustainable mobility solutions.
