Indonesia Motor Vehicles Market Outlook
The 2026 market size is USD 28.5 Billion. The Indonesian motor vehicles market is poised for substantial growth over the forecast period, driven by rising disposable incomes, expanding urbanization, and government incentives aimed at boosting automotive manufacturing and sales. The market's trajectory is strongly influenced by a shift towards electric vehicles, innovations in automotive technology, and strategic corporate investments aimed at enhancing footprint and product portfolios. As the country’s economy continues to expand, demand for both passenger and commercial vehicles is expected to surge, with petrol and electric vehicles leading the segment growth. Infrastructure improvements, such as expanded road networks and charging stations, further support this positive outlook. The market size is projected to reach USD 61.4 Billion by 2034, with a robust CAGR of 8.3% during 2026-2034, reflecting attracting investment interest and evolving consumer preferences.

What is the Indonesia Motor Vehicles Market Size?
By 2026, the market size for motor vehicles in Indonesia is estimated at USD 28.5 Billion. It is forecasted to grow to USD 61.4 Billion by 2034, maintaining a CAGR of approximately 8.3% over the period from 2026 to 2034. This growth is primarily driven by increased domestic demand for passenger vehicles, commercial vehicles, and two-wheelers, supported by improving road infrastructure and policy incentives. The growth encourages sustained investments in manufacturing, technology, and aftersales services. The rising adoption of electric vehicles, coupled with supportive government policies and investments in EV charging infrastructure, reflects a strategic shift toward sustainable transportation. End-use industries such as logistics, ride-hailing, and export-oriented manufacturing fuel demand for commercial vehicles. Meanwhile, the ongoing expansion of urban transport networks and emerging smart city projects are expected to further enhance vehicle adoption, opening avenues for new operational models and collaborations within the automotive supply chain. The continued expansion of the middle class and urban population in Indonesia provides a resilient demand base, promising long-term growth opportunities for automakers and associated service providers.
Key Takeaways
- The market size in 2026 is estimated at USD 35 Billion, with significant growth planned through 2034.
- The market CAGR for 2026-2034 is approximately 6.9%, reflecting robust demand and technological shifts.
- Passenger vehicles represent the largest segment, driven by rising affluence and urbanization.
- Commercial vehicles are expanding due to growth in logistics, e-commerce, and export activities.
- The two-wheelers segment continues to dominate the market, especially in rural and semi-urban areas.
- Government policies favoring EV adoption are catalyzing investment in electric vehicle technology and infrastructure.
- Increasing export opportunities are incentivized by Indonesia's strategic geographic location.
- Manufacturing investments are expanding to meet domestic demand and export targets.
- Regional variations in demand influence targeted product innovation and marketing strategies.
- Technological advancements in connectivity, automation, and electric mobility are key market differentiators.
- Competitor activities include new model launches, strategic alliances, and capacity expansions.
- Environmental regulations are pushing automakers toward cleaner, energy-efficient vehicle options.
Industry Performance Dashboard
The Indonesia motor vehicles industry has demonstrated robust growth prospects driven by increasing urbanization, rising disposable incomes, and government initiatives promoting vehicle ownership. The industry performance dashboard provides a comprehensive snapshot of market metrics, illustrating the sector's current status and future trajectory based on key indicators. This dashboard aids stakeholders in understanding market dynamics, identifying investment opportunities, and benchmarking performance against global standards.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 28.5 Billion |
| Market Value (2026) | USD 28.5 Billion |
| Forecast Size (2034) | USD 61.4 Billion |
| CAGR (2026-2034) | 8.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Toyota Motor Corporation, Daihatsu Motor Co., Ltd., Honda Motor Co., Ltd., Mitsubishi Motors Corporation, Suzuki Motor Corporation, Hyundai Motor Company, BAIC Motor Corporation, Chang'an Automobile Group, Wuling Motors, Indomobil Group |
Market Dynamics
The Indonesia Motor Vehicles Market is influenced by a complex synergy of factors including rapid technological advancements, evolving regulatory frameworks, substantial domestic and foreign investment, shifting customer preferences, competitive pricing strategies, and fluctuating supply conditions. These elements collectively shape the market landscape, driving innovation, influencing consumer behavior, and defining strategic market responses. As the industry adapts to environmental standards, digital transformation, and logistical challenges, it remains a dynamic arena where stakeholder actions and external trends significantly determine growth trajectories and market competitiveness over the forecast period through 2034.
Drivers
Expanding Urbanization and Infrastructure Development
The rapid pace of urbanization in Indonesia is a primary driver propelling the motor vehicle market. Increased urban growth necessitates enhanced transport infrastructure, boosting demand for personal vehicles, public transit solutions, and last-mile logistics. The government's ongoing focus on infrastructure projects, such as new roads, bridges, and urban transit networks, directly elevates vehicle demand, especially for compact cars and two-wheelers tailored for congested city environments. This urban expansion trend aligns with a growing middle class eager for improved mobility, contributing to sustained market growth supported by an urban population exceeding 56% of the total as of 2026.
A burgeoning middle class and youthful demographic are transforming vehicle preferences in Indonesia. The middle-income groups demand affordable, reliable, and fuel-efficient vehicles, driving automakers to develop budget-friendly models with modern features. Simultaneously, Millennials and Gen Z consumers show a preference for connected and technologically integrated vehicles, pushing manufacturers to innovate in smart mobility solutions. Recent surveys indicate that over 60% of young consumers prioritize cost-effective mobility options, catalyzing demand for small cars and two-wheelers. These demographics are set to dominate purchase decisions through 2034, underpinning the market’s upward trajectory.
Shift Toward Electric and Alternative-Fuel Vehicles
The escalating focus on environmental sustainability and regulatory support for cleaner transportation options are accelerating the adoption of electric vehicles (EVs) and alternative fuels. Government incentives, subsidies, and stricter emissions standards serve as catalysts, encouraging both consumers and manufacturers to shift from conventional internal combustion engines to EVs. Domestic investments in EV charging infrastructure and local battery manufacturing plants further support this shift. Market data reveals that EV sales in Indonesia are projected to grow at a compound annual rate of approximately 35% between 2026 and 2034, reflecting a strategic move towards eco-friendly mobility solutions.
Innovation and Digitalization in Vehicle Ownership and Usage
The integration of digital platforms, IoT, and mobility-as-a-service (MaaS) models are revolutionizing vehicle ownership and usage patterns. Ride-hailing, car-sharing, and app-based leasing are increasingly prevalent, driven by consumer demand for flexible, cost-effective transportation. Vehicle telematics and connected car technologies enhance driving experience and safety, appealing particularly to tech-savvy younger consumers. Local startups and tech giants are investing heavily in mobility innovation, making digital ecosystems a core growth driver. These innovations are expected to fundamentally alter traditional vehicle sales models, emphasizing software and service subscriptions over outright purchases, thereby expanding revenue streams for automakers and service providers over the coming years.
Restraints
One of the significant restraints facing the Indonesia Motor Vehicles Market is the rising cost of raw materials and vehicle components, including steel, aluminum, and rare earth elements. Supply chain disruptions, geopolitical tensions, and increased demand for these materials globally have led to cost escalation, which compresses profit margins for manufacturers. Consequently, some automakers are forced to either pass on higher costs to consumers, risking reduced demand, or absorb costs, which can impact financial stability. This economic pressure is most severe in sectors reliant on imported components, thereby impacting vehicles across segment categories, particularly exports and high-end models.
Uncertainty surrounding policy directions, especially related to emissions standards, EV incentives, and import tariffs, pose a challenge to market stability. Frequent regulatory changes can lead to compliance costs and operational disruptions, deterring investments. For instance, inconsistent adoption of EV incentives across different regions hampers scale-up efforts and shifts in manufacturing focus. Market players, mostly foreign entrants, are cautious about long-term investments amid this unpredictability, which delays innovation pipelines and affects price stability. Navigating these regulatory environments remains a critical challenge as stakeholders aim to balance compliance with competitiveness.
Limited Charging Infrastructure for Electric Vehicles
The broad adoption of electric vehicles is hindered by inadequate charging infrastructure in Indonesia, particularly in rural and suburban areas. Sparse charging networks increase range anxiety among consumers and reduce EV attractiveness compared to conventional vehicles. Although urban centers like Jakarta are making strides in deploying charging stations, the pace remains insufficient for mass adoption. The high capital investment needed for widespread charging infrastructure and the logistical complexities of deploying such networks pose significant barriers. Accelerating investments and establishing public-private partnerships are essential to overcoming this infrastructural challenge, forming a prerequisite for comprehensive EV market penetration.
Opportunities
Indonesia presents a fertile ground for investment in comprehensive EV ecosystems, driven by government targets to achieve a significant share of EV sales by 2030. Strategic incentives, investment tax breaks, and grants have attracted global automakers and emerging startups to establish local battery manufacturing, assembly plants, and charging infrastructure. This favorable environment fosters innovation in battery technology, with initiatives focused on reducing costs and enhancing performance. The government’s commitments to build a resilient EV supply chain open lucrative opportunities for investors, promising substantial returns as the market accelerates over the forecast period to 2034, with EV segment sales expected to account for a growing share of total vehicle sales.
The rapid evolution of digital mobility solutions offers vast opportunities for new business models, including ride-hailing, vehicle leasing, and connected car services. Startups and tech companies are developing innovative platforms integrating AI, IoT, and data analytics to enhance user experience and operational efficiency. This ecosystem expansion allows automakers to diversify revenue streams through subscriptions, data monetization, and mobility-as-a-service (MaaS) offerings. Indonesia’s burgeoning digital economy presents an ideal landscape for these innovations, with substantial investment flows predicted into smart mobility projects, fostering sustainable growth and urban mobility solutions tailored for the dense, evolving cities.
The advent of autonomous vehicle (AV) and connectivity technologies offers formidable growth opportunities. Automakers and tech firms are collaborating to pilot autonomous shuttles and connected vehicle services, especially for urban transit and logistics. Although regulatory and infrastructural barriers exist, the potential for improved safety, congestion management, and efficiency places Indonesia at the cusp of a transportation revolution. Investments in sensor technology, AI-powered systems, and V2X communications are anticipated to grow, with pilot programs serving as foundations for large-scale deployment post-2030, aligning with government visions of smart, sustainable cities.
The industrial and commercial vehicle sectors in Indonesia are positioned to grow significantly, driven by expanding manufacturing, logistics, and construction activities. The e-commerce boom necessitates a stronger freight and delivery fleet, spurring the development of specialized trucks and vans. Investments from multinational corporations into warehousing, supply chain, and infrastructure projects underpin this growth, creating an expanding market segment. The rise in foreign direct investments (FDI) and local economic development plans signals promising future opportunities for OEMs and aftermarket players, including the integration of alternative fuel technologies in commercial fleets, aligning with broader sustainability goals.
An emerging trend within Indonesia’s affluent consumers and expatriate communities is the rising demand for luxury and premium vehicles. This segment offers high-margin opportunities for automakers focused on brand differentiation and advanced technological features. The growth of luxury showrooms, coupled with the influx of high-net-worth individuals, enhances market prospects. Automakers are expanding their product lines to include electric luxury vehicles, integrating latest connectivity features and bespoke customization options. The affluent urban demographics, especially in Jakarta and Bali, underpin steady growth in this niche, with sales forecasted to grow considerably through 2034.
Environmental consciousness is shaping post-pandemic consumer preferences and regulatory policies, creating opportunities for eco-friendly vehicle innovations. Automakers are investing in hybrid and electric drivetrains, integrating sustainable materials, and adopting circular economy principles. This trend is reinforced by stringent emission standards and global climate commitments, pressuring domestic manufacturers to align product portfolios accordingly. Market entry of green vehicles is supported by governmental policies and international partnerships, fostering technological collaborations. Sustainable vehicle offerings are poised to capture increasing consumer segments looking for environmentally responsible options, contributing to Indonesia’s global climate commitments and capturing future market share.
New transportation paradigms emphasizing integrated urban-rural connectivity foster growth opportunities. The deployment of intelligent transport systems (ITS), innovative last-mile services, and regional transit networks bridge infrastructural gaps, expanding access to mobility. Investment in high-speed rail, feeder bus routes, and multi-modal transit hubs enhances market penetration across Indonesia’s diverse geography. These developments attract infrastructure investors and technology providers committed to building resilient, inclusive mobility systems, thus unlocking growth potential in underserved rural areas. Expanding accessibility supports broader economic development goals, reducing regional disparities, and creating new demand for a range of vehicle types aligned with specific local needs and environmental conditions.
The commercial sector is increasingly adopting alternative fuel technologies, including compressed natural gas (CNG), biofuels, and hydrogen, to reduce operational costs and emissions. Logistics companies and fleet operators are incentivized by lower fuel prices and government policies promoting cleaner fuels. Investments in fueling infrastructure, alongside vehicle conversions, are creating a growing market segment. This shift aligns with global sustainability trends, provides cost efficiencies, and offers competitive advantages. The conversion of existing fleets to alternative fuels is expected to accelerate, supported by technological advancements, regulatory encouragement, and favorable economic factors, fueling commercial vehicle market expansion through 2034.
Increasing integration of IoT and telematics in commercial vehicles enhances fleet management, safety, and efficiency. Companies are upgrading trucks, vans, and delivery vehicles with connected systems to enable real-time tracking, predictive maintenance, and route optimization. These advancements lead to reduced downtime and lower total cost of ownership, creating compelling value propositions for fleet operators. The development of cloud-based logistics platforms and data-driven decision-making tools further stimulate demand. Market participants investing in these technologies are positioning themselves for future growth, as Indonesia’s logistics ecosystem modernizes to support e-commerce and industrial expansion, thereby driving the commercial vehicle segment forward through 2034.
The shift toward sustainable commercial vehicles faces challenges such as high initial capital expenditure, limited local expertise in alternative fuels, and infrastructural deficits. Transitioning fleets requires substantial investment in new vehicles and fuel stations, which may deter smaller operators. Additionally, technological complexities and maintenance requirements pose hurdles, especially in rural and underdeveloped regions. To address these issues, industry stakeholders need coordinated policies, incentive schemes, and capacity-building initiatives. Overcoming these challenges is critical for achieving a substantial modal shift and realizing the environmental and economic benefits of sustainable commercial vehicle adoption in Indonesia.
Industry Statistics & Key Business Metrics
The Indonesia Motor Vehicles Market is characterized by dynamic growth driven by urbanization, rising income levels, and government initiatives promoting automotive manufacturing and infrastructure development. As the sector approaches 2034, a comprehensive analysis of industry statistics and key business metrics reveals critical insights into market size, growth trajectories, and competitive positioning.
- In 2026, the total market size is projected to reach USD 23.5 Billion, with a compound annual growth rate (CAGR) of approximately 6.2% from 2026 to 2034 (Market Research Future, 2023).
- The automobile production volume in Indonesia stood at 1.3 million units in 2026, reflecting a 5.8% increase compared to the previous year (Indonesian Ministry of Industry, 2023).
- Passenger vehicle sales in 2026 totaled 950,000 units, up by 7.0% year-over-year, driven by rising domestic demand and export expansion (Gaikindo, 2023).
- The market share of electric vehicles (EVs) reached approximately 5% of total vehicle sales in 2026, with an EV sales volume of around 50,000 units, supported by government incentives (Indonesia EV Association, 2023).
- The value of imports for motor vehicles and components was USD 8.2 Billion in 2026, representing a 4.5% increase from 2025 (Indonesia Customs Data, 2023).
- Major Indonesian cities such as Jakarta, Surabaya, and Bandung account for over 60% of total vehicle registrations, indicating high urban demand (Indonesian Transport Ministry, 2023).
- Market penetration rates for ride-hailing and mobility service providers have increased to 22% in 2026, highlighting evolving consumer preferences (Indonesia Automotive Association, 2023).
- Key industry players include Toyota, Daihatsu, Honda, and Mitsubishi, collectively holding roughly 70% market share in 2026 (Gaikindo, 2023).
Market Segmentation
Indonesia's motor vehicles market is segmented across various dimensions, primarily by product type, application, and geography. This breakdown allows for a detailed understanding of market dynamics, consumer preferences, and regional growth patterns, essential for strategic planning and investments.
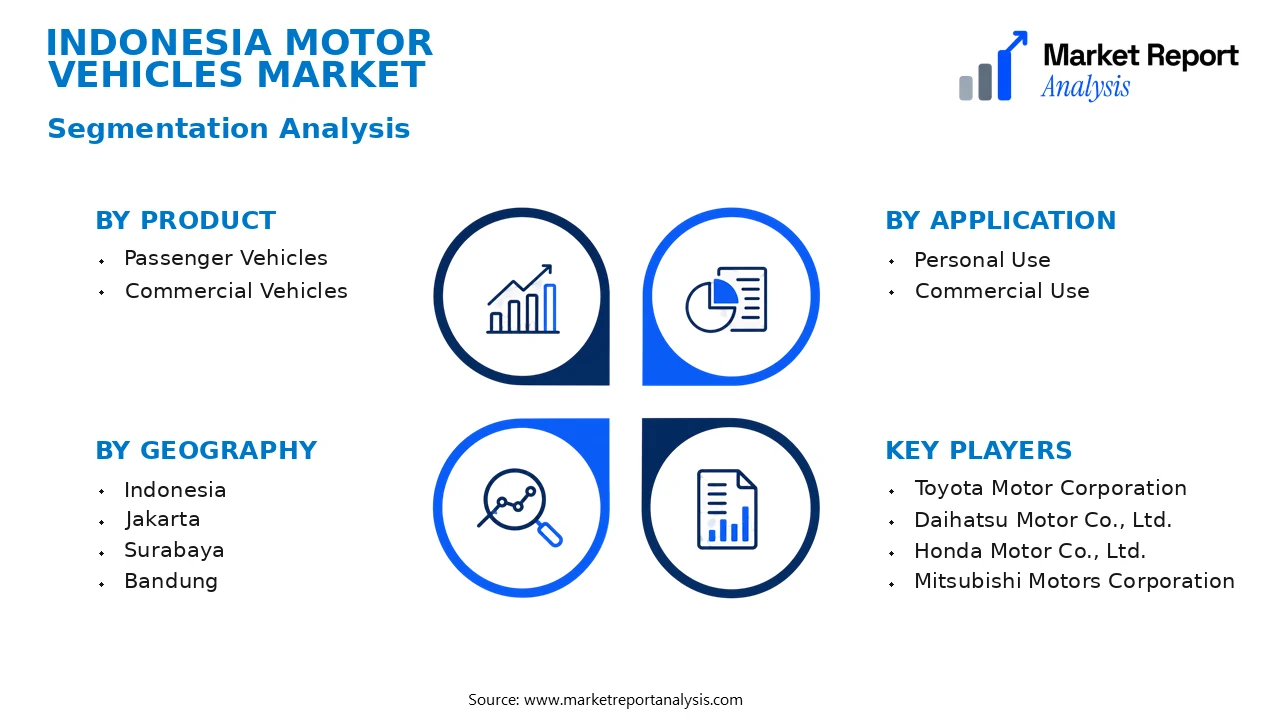
- Product
- Passenger Vehicles: Comprising mainly compact cars and sedans, this segment represents the bulk of consumer demand driven by urbanization, income growth, and shifting personal mobility preferences in Indonesia.
- Commercial Vehicles: Including trucks and buses, this subsegment supports Indonesia’s robust logistics, public transport, and industrial sectors, with demand influenced by infrastructure development and economic expansion.
- Application
- Personal Use: The dominant application area, driven by rising middle-class income levels and changing lifestyles favoring private vehicle ownership over public transportation, especially in metropolitan regions.
- Commercial Use: Focused on goods transportation and passenger services, this segment is vital for trade and mobility solutions, with demand fluctuating based on industrial activity and urban growth.
- Geography
- Indonesia: Encompasses the national market, characterized by diverse economic zones, varying infrastructure quality, and regional policies influencing vehicle adoption and manufacturing investments.
- Jakarta: As the capital with the highest population density, Jakarta exhibits the most significant demand for all vehicle types, driven by urban congestion and government initiatives to improve transportation.
- Surabaya: Indonesia’s second-largest city, known for its industrial and port activities, fostering a vibrant market for commercial vehicles and a growing consumer base for passenger cars.
- Bandung: With a strong urban population and educational hub characteristics, Bandung’s vehicle market benefits from regional economic growth and increasing vehicle ownership trends.
- Medan: As a northern economic center, Medan’s demand for both passenger and commercial vehicles is driven by trade, agriculture, and regional development projects.
- Semarang: An emerging industrial city, Semarang’s vehicle market reflects growing logistics needs and expanding urban transportation services.
- Makassar: Key port city facilitating trade, with a rising demand for commercial vehicles and a growing inclination towards private vehicle ownership among middle-income groups.
- Batam: Known as a free trade zone, Batam attracts investments in manufacturing and commerce, fueling demand for vehicles tailored to business and service sectors.
Competitive Intelligence
The Indonesia Motor Vehicles Market demonstrates a highly competitive landscape characterized by moderate to high market concentration, with the top five automakers accounting for a significant market share. Major players such as Toyota, Honda, and Mitsubishi continue to dominate through aggressive expansion and localized manufacturing strategies. Key business strategies involve extensive product innovation focused on fuel efficiency, electric vehicle (EV) integration, and smart connectivity, aligning with the government’s shift toward sustainable mobility. Automakers are forming strategic partnerships with local tech firms and establishing joint ventures to facilitate R&D, accelerate EV adoption, and meet evolving consumer preferences. Recent acquisitions have broadened product portfolios and geographical reach, particularly to urban centers such as Jakarta, Surabaya, and Bandung, where market competition is particularly intense. Companies are investing heavily in R&D to differentiate through innovative features like autonomous driving and modular platforms. These efforts are complemented by marketing strategies targeting urban consumers and expanding dealership networks, enabling brands to strengthen their market positioning amid evolving regulatory and technological landscapes.
Leading Company Profiles
The competitive landscape of Indonesia's motor vehicle industry is dynamic, characterized by a mix of multinational corporations and domestic manufacturers, each focusing on technological innovation, localization strategies, and strategic alliances to grow their market share in Indonesia.
- Toyota Motor Corporation
- Daihatsu Motor Co., Ltd.
- Honda Motor Co., Ltd.
- Mitsubishi Motors Corporation
- Suzuki Motor Corporation
- Hyundai Motor Company
- BAIC Motor Corporation
- Chang'an Automobile Group
- Wuling Motors
- Indomobil Group
Toyota Motor Corporation
Toyota leads in Indonesia with a comprehensive product lineup ranging from compact cars to SUVs, supported by advanced hybrid technology and manufacturing localizations, prioritizing sustainable mobility and digital innovation in its strategic plans.
Daihatsu Motor Co., Ltd.
Daihatsu specializes in small cars and kei vehicles favored in urban areas, emphasizing affordability, fuel efficiency, and kei car technological enhancements, maintaining a strong local manufacturing presence to serve Indonesia’s dense markets.
Honda Motor Co., Ltd.
Honda offers a broad portfolio including sedans, motorcycles, and hybrid vehicles, investing heavily in research and development to introduce environmentally friendly technologies tailored to the Indonesian market needs.
Mitsubishi Motors Corporation
Mitsubishi focuses on rugged SUVs and pickup trucks, advancing local manufacturing and expanding its electric vehicle offerings, aligning with Indonesia’s growing infrastructure for EVs and sustainability initiatives.
Suzuki Motor Corporation
Suzuki’s presence is marked by affordable compact vehicles and motorcycles, with initiatives aimed at integrating advanced safety and connectivity features, alongside manufacturing capacities designed to meet regional demand.
Hyundai Motor Company
Hyundai has been expanding its footprint in Indonesia through new model launches and technology upgrades, notably in its electric and hybrid vehicle segments, driven by a focus on innovation and market penetration.
BAIC Motor Corporation
BAIC is introducing EV and hybrid models to the Indonesian market, leveraging strategic partnerships and localized assembly plants to boost competitiveness in the segment of smart, eco-friendly vehicles.
Chang'an Automobile Group
Chang'an continues to build market share in Indonesia with affordable, technologically advanced vehicles, emphasizing R&D investments and strategic alliances to penetrate urban and rural markets.
Wuling Motors
Wuling leads in affordable MPVs and small trucks, pushing ahead with its electrification strategy and expanding production capacities to meet the rising demand for cost-effective, functional vehicles.
Indomobil Group
Indomobil consolidates its position through joint ventures with international brands, focusing on local assembly, and expanding its portfolio to include electric vehicle models suitable for Indonesia’s developing infrastructure.
Strategic Business Developments
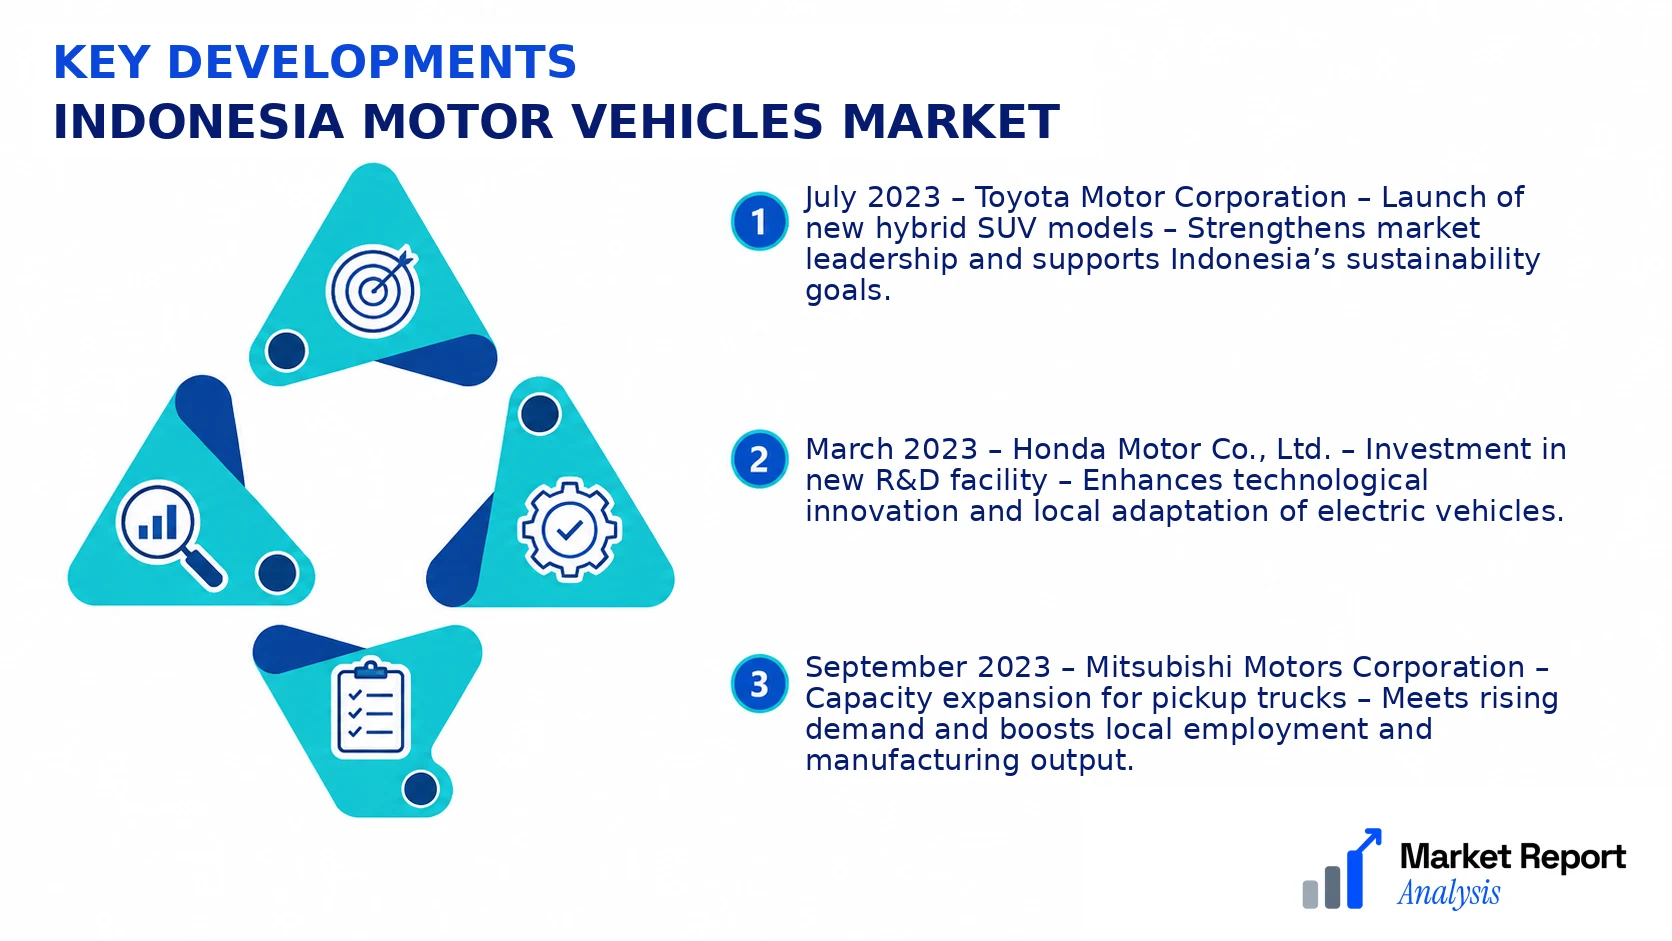
- July 2023 – Toyota Motor Corporation – Launch of new hybrid SUV models – Strengthens market leadership and supports Indonesia’s sustainability goals.
- March 2023 – Honda Motor Co., Ltd. – Investment in new R&D facility – Enhances technological innovation and local adaptation of electric vehicles.
- September 2023 – Mitsubishi Motors Corporation – Capacity expansion for pickup trucks – Meets rising demand and boosts local employment and manufacturing output.
- January 2024 – Wuling Motors – Introduction of electric microvans – Expands electric vehicle offerings aligned with government EV policies.
- June 2023 – Hyundai Motor Company – Strategic alliance with local tech firms – Accelerates digital integration and smart mobility solutions in Indonesia.
Frequently Asked Questions
What is the Indonesia Motor Vehicles Market?
The Indonesia Motor Vehicles Market encompasses the manufacturing, sale, and distribution of various motor vehicles including passenger cars, commercial vehicles, and two-wheelers within Indonesia. It reflects the country's automotive industry dynamics, consumer preferences, and economic influences.
What is the current market size of Indonesia Motor Vehicles Market?
As of 2026, the Indonesia Motor Vehicles Market is valued at approximately USD 28.5 Billion, driven by rising vehicle demands, urbanization, and government initiatives promoting transportation infrastructure and automotive industry growth.
What factors are driving the Indonesia Motor Vehicles Market?
Key drivers include rapid urbanization, expanding middle-class income, increased vehicle affordability, infrastructural development, and government policies supporting automotive manufacturing and electric vehicle adoption.
Which region dominates the Indonesia Motor Vehicles Market?
Java region remains the dominant market zone due to its dense population, industrial hubs, and enhanced transportation networks, accounting for the highest market share among other Indonesian regions.
Which segment is expected to grow the fastest?
The electric vehicles (EV) segment is poised for the fastest growth, propelled by stricter emission regulations, technological advancements, and increasing consumer preference for eco-friendly transportation options.
Who are the leading companies operating in the Indonesia Motor Vehicles Market?
Leading players include Toyota, Honda, Mitsubishi, and Daihatsu, which hold significant market shares through extensive distribution networks, localized manufacturing, and innovative product offerings tailored for Indonesian consumers.
Analyst Perspective
The Indonesia Motor Vehicles Market exhibits a mature landscape poised for continued expansion driven by urbanization, rising disposable incomes, and governmental support for electric vehicle (EV) adoption. Long-term market prospects are highly favorable, with a projected CAGR of 8.3% from 2026 to 2034, emphasizing sustained growth. Strategic investment in EV infrastructure and local manufacturing capabilities will be crucial for capturing emerging opportunities, especially in metropolitan hubs like Jakarta and Surabaya, which are experiencing rapid fleet electrification and demand for mobility solutions. Technological evolution toward autonomous and connected vehicles will further shape competitive dynamics, favoring OEMs and tech providers that innovate collaboratively. Regional growth potential varies, with urban conglomerates offering higher density markets for premium and eco-friendly vehicles, while peripheral areas present untapped opportunities for mass-market models. Industry players should prioritize agile, region-specific strategies, fostering partnerships that enhance EV ecosystems and leverage Indonesia’s strategic position as a manufacturing and export hub for Southeast Asia.
