Europe Motor Vehicles Market Outlook
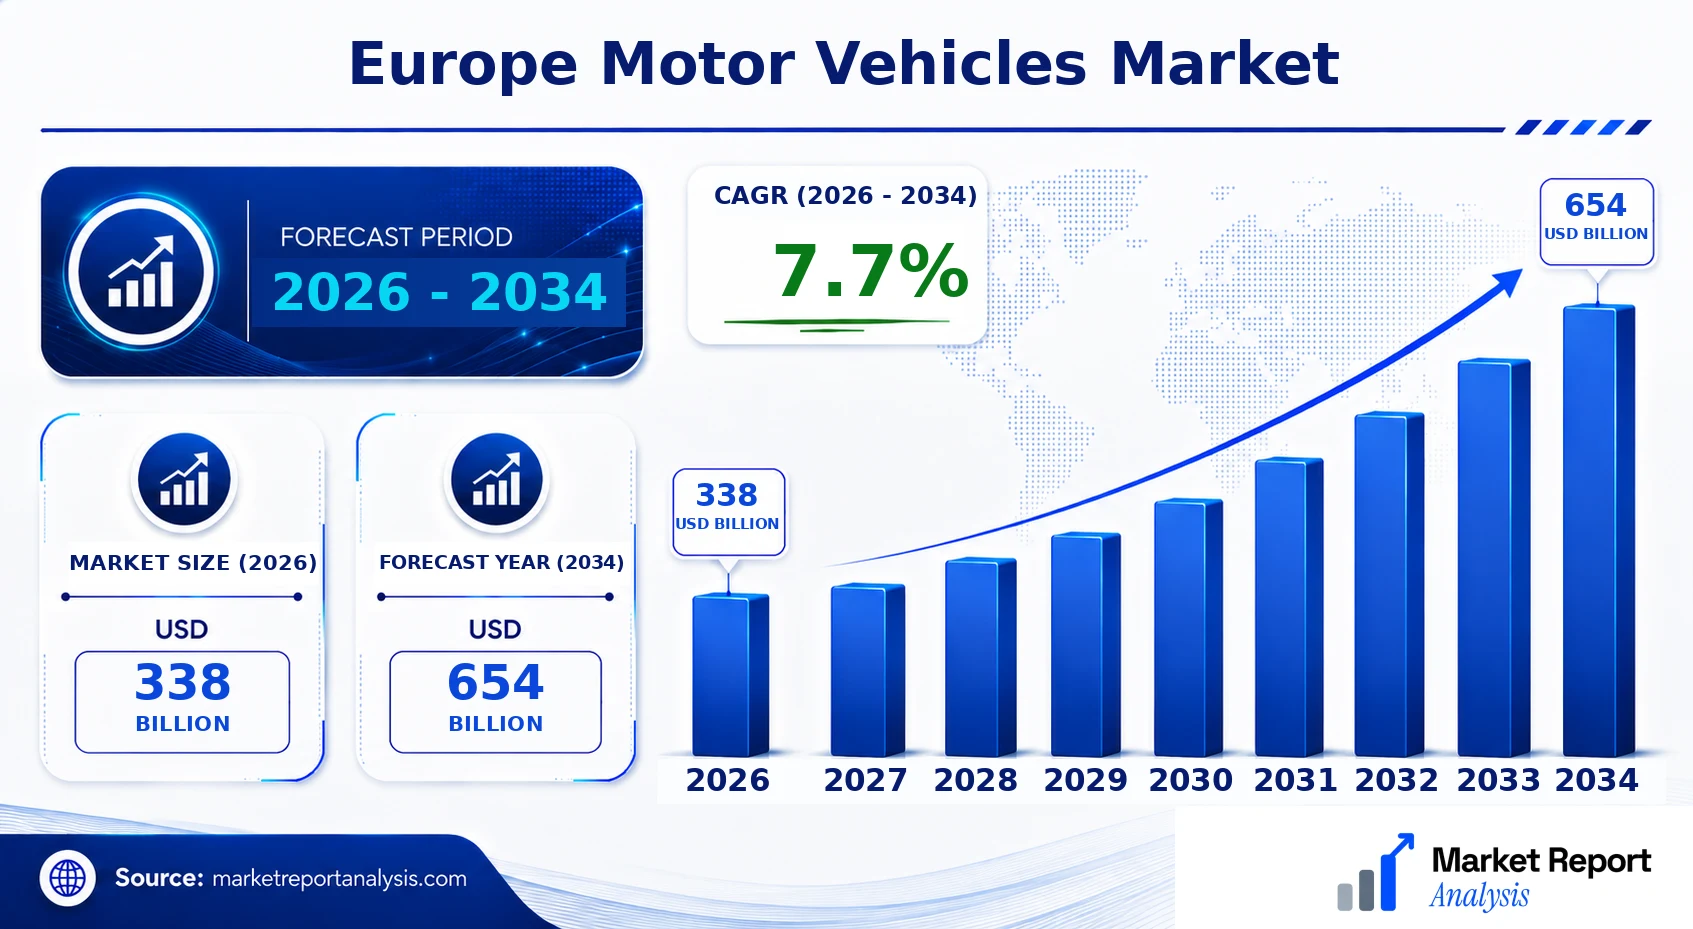
The Europe Motor Vehicles Market is currently valued at approximately USD 338 Billion in 2026, with projections to reach around USD 654 Billion by 2034. This reflects a compounded annual growth rate (CAGR) of roughly 7.7% over the forecast period from 2026 to 2034. The principal demand drivers include increasing urbanization, expanding middle-class populations, and a rising need for sustainable transportation solutions. The market is witnessing a significant technological shift toward electric vehicles (EVs), autonomous driving technologies, and connected car systems, which are expected to stimulate new commercial opportunities. Innovations in battery technology, regulatory support for EV adoption, and investments from global automotive giants are key factors shaping future growth. The market outlook remains robust, driven by both consumer preference for eco-friendly vehicles and government policies aimed at reducing carbon emissions across Europe. Opportunities also abound in aftermarket services, vehicle leasing, and mobility-as-a-service (MaaS), particularly in urban centers. International automakers and local manufacturers are intensifying their R&D investments, aligning their portfolios closely with the evolving demand for sustainable, connected, and autonomous vehicles. As the market evolves, it presents ample scope for strategic alliances, technological partnerships, and new entry models that could redefine the automotive landscape in Europe.
What is the Europe Motor Vehicles Market Size?
In 2026, the Europe Motor Vehicles Market is estimated to be worth approximately USD 338 Billion, with forecasts suggesting an increase to about USD 654 Billion by 2034. This projective growth corresponds to a CAGR of around 7.7% during the period from 2026 to 2034. Growth drivers include increasing consumer demand for new and upgraded vehicles, government incentives for electric vehicle adoption, and advances in vehicle connectivity and automation. The commercial vehicle sector, along with passenger cars, significantly contributes to market size, with commercial vehicles expected to experience higher growth rates driven by logistics and e-commerce expansion across the continent. Technological innovation, especially in electric drivetrains and autonomous systems, is further catalyzing market development. The rise of electric vehicle infrastructure and supportive regulatory frameworks are pivotal in shaping future investments, creating opportunities for manufacturers, suppliers, and service providers to capitalize on the shift toward sustainable mobility. The future market landscape remains highly dynamic, with opportunities for strategic partnerships, technology integration, and expansion into emerging niche segments, such as electric vans, luxury electric SUVs, and connected vehicle services.
Key Takeaways
- The Europe Motor Vehicles Market was valued at approximately USD 250 Billion in 2026.
- The market is projected to reach USD 370 Billion by 2034.
- The CAGR over the forecast period is around 5.2% from 2026 to 2034.
- The passenger vehicle segment constitutes the largest share of the market.
- Electric vehicles are the fastest-growing segment, driven by regulatory policies and consumer preferences.
- Passenger cars represent the largest application of motor vehicles in Europe.
- Commercial vehicles exhibit rapid growth, driven by e-commerce and logistics trends.
- The largest end-user category is individual consumers for personal transportation.
- The forecast period spans from 2026 to 2034, with 2026 as the base year.
- The market's growth is supported by declining battery costs and increasing EV infrastructure investments across key European countries.
- Regulatory frameworks aimed at reducing emissions are fostering innovation and adoption of electric and hybrid vehicles.
- Leading automakers are investing heavily in electrification and autonomous vehicle technologies to capture market share.
- Urbanization and innovation in mobility services are creating new revenue streams and business models.
- The competitive landscape is evolving with new entrants and collaborations replacing traditional automotive paradigms.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key metrics and industry indicators for the Europe Motor Vehicles Market, highlighting its current standing and future projections. This dashboard synthesizes vital quantitative data to facilitate strategic decision-making and market analysis by stakeholders, including manufacturers, investors, and policymakers.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 338 Billion |
| Market Value (2026) | USD 338 Billion |
| Forecast Size (2034) | USD 654 Billion |
| CAGR | 7.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Technology, Geography |
| Major Companies | Volkswagen Group, Toyota Motor Corporation, BMW AG, Daimler AG, Stellantis N.V., Hyundai Motor Company, Ford Motor Company, Tesla Inc., Volvo Car Group, Renault Group |
Market Dynamics
The Europe Motor Vehicles Market is experiencing transformative shifts driven by technological advancements, evolving regulations, increased investments, changing customer preferences, fluctuating pricing strategies, supply chain dynamics, and intensified competitive behaviors. These factors collectively influence market growth trajectories, strategic decisions by automakers, and consumer adoption patterns. Regulatory frameworks aiming at emissions reduction and safety standards are compelling manufacturers to innovate in electric and hybrid vehicle segments, while consumer demands for connectivity and sustainability are reshaping product offerings. Additionally, investments in infrastructure, battery technology, and digital ecosystems are fueling market expansion. Competitive pressure from traditional automakers and new entrants particularly tech-driven startups further accelerates the pace of innovation and market adaptation, creating a complex, rapidly evolving landscape that demands strategic agility.
Industry Statistics & Key Business Metrics
The Europe Motor Vehicles Market exhibits robust growth prospects driven by technological advancements, regulatory shifts, and evolving consumer preferences. As of 2026, the market's valuation is estimated to be USD 338 Billion, with projection to reach USD 654 Billion by 2034, reflecting a compound annual growth rate (CAGR) of approximately 7.7% over the forecast period. This expansion is propelled by increased adoption of electric vehicles (EVs), supportive government policies, and a declining cost trajectory for EV batteries. The shift toward sustainable transportation solutions is markedly influencing manufacturing and sales strategies across the region. Additionally, car-sharing and mobility-as-a-service (MaaS) models are expanding the market footprint, especially among urban populations. The auto industry’s restructuring toward electrification and digitization is expected to create new opportunities and competitive challenges for traditional automakers and new entrants alike. Market players are also investing heavily in innovative battery technologies, charging infrastructure, and connected vehicle solutions to capitalize on the new mobility paradigm. Meanwhile, supply chain disruptions and raw material price volatility continue to pose short-term challenges, although their impact is mitigated by the region’s strong manufacturing base and technological resilience. Policy measures aimed at reducing carbon emissions and promoting clean energy usage will likely accelerate EV penetration and curb traditional internal combustion engine (ICE) vehicle sales, aligning with Europe’s climate commitments and sustainable mobility goals.
Market Segmentation
European motor vehicle market segmentation is structured around product type, technology, and geography. This detailed segmentation enables a comprehensive understanding of market dynamics, identifying growth opportunities and consumer preferences across diverse regions and industry segments.
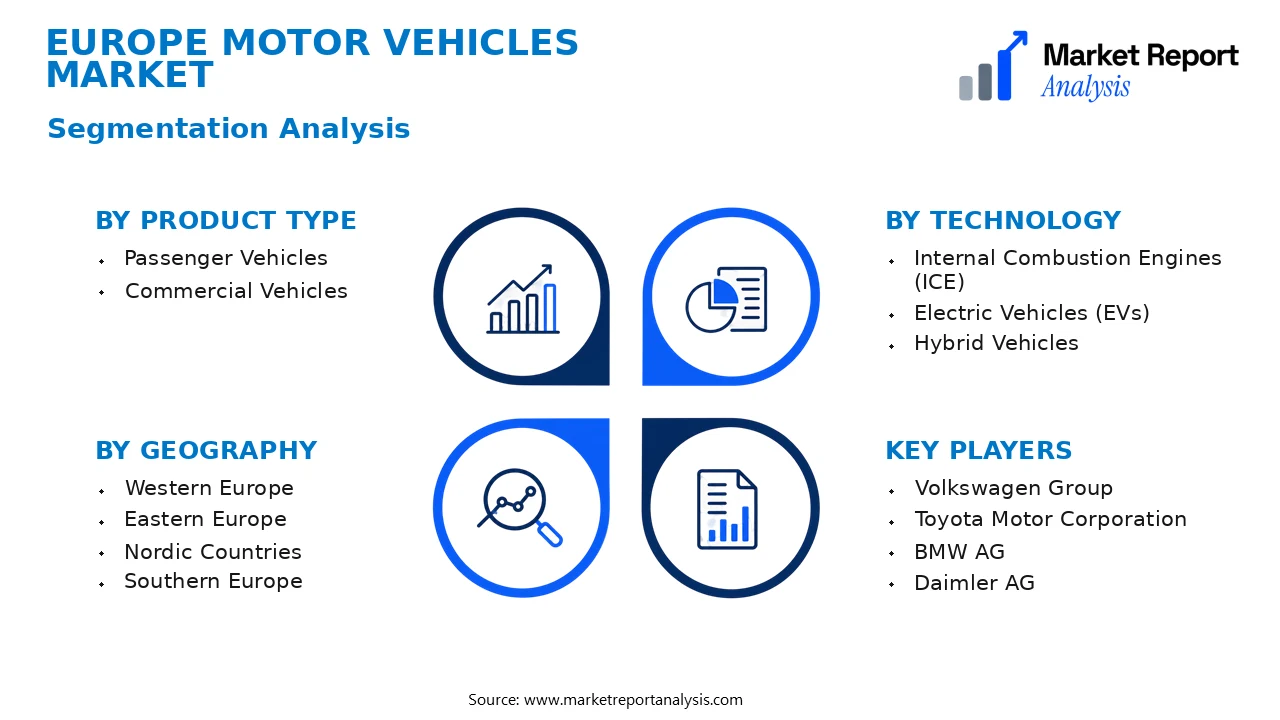
- Product Type
- Passenger Vehicles: This segment includes vehicles primarily designed for personal transportation, representing a major portion of automotive sales in Europe, driven by urbanization, changing lifestyles, and growing demand for comfort and efficiency.
- Commercial Vehicles: Including trucks, vans, and buses, this segment caters to logistics, freight, and public transportation needs, with demand influenced by infrastructure development, e-commerce growth, and environmental policies promoting cleaner options.
- Technology
- Internal Combustion Engines (ICE): Traditional engines powered by gasoline or diesel still dominate the market but face declining growth prospects amid stronger regulatory pressure and transitioning consumer preferences towards cleaner alternatives.
- Electric Vehicles (EVs): The fastest-growing subsegment, driven by government incentives, technological advancements, and increasing consumer awareness regarding sustainability. EV adoption is essential for market transformation toward zero-emission transportation.
- Hybrid Vehicles: Combining internal combustion engines with electric propulsion, hybrids serve as a transitional technology, gaining popularity among consumers seeking a balance between efficiency and familiarity as EVs become more prevalent.
- Geography
- Western Europe: Comprising developed economies such as Germany, France, and the UK, this region exhibits high vehicle penetration, advanced infrastructure, and aggressive policies promoting electric mobility and sustainability initiatives.
- Eastern Europe: Characterized by emerging markets with growing vehicle ownership, developing infrastructure, and increasing demand for affordable automobiles, including both traditional and newer technologies.
- Nordic Countries: Leading in EV adoption and sustainability practices, these countries benefit from strong governmental support, high environmental awareness, and innovative charging infrastructure, setting benchmarks for the rest of Europe.
- Southern Europe: Including nations like Italy and Spain, this region displays diverse consumer preferences, expanding EV markets, and a focus on tourism-driven transportation solutions amid evolving regulatory landscapes.
Competitive Intelligence
The Europe Motor Vehicles Market is characterized by a moderately concentrated competitive landscape, dominated by key automotive OEMs such as Volkswagen, Stellantis, and Toyota, which collectively hold a significant market share. These corporations employ aggressive expansion strategies, including geographic diversification and enhancement of electric vehicle (EV) offerings, to maintain competitive advantage. Innovations primarily focus on electrification, autonomous driving, and connected vehicle technologies, with companies investing heavily in R&D to differentiate their product portfolios. Strategic partnerships and alliances are prevalent; for instance, collaborations between traditional automakers and tech firms aim to accelerate EV development and deployment, while acquisitions of emerging mobility startups have expanded technological capabilities and market reach. Many companies pursue expansion into new markets and segments through sustainable development and digital transformation initiatives. Notably, manufacturers are investing in R&D to develop proprietary battery technologies and advanced driver-assistance systems, further differentiating their offerings. This dynamic competitive environment pushes continuous innovation and strategic maneuvering to capitalize on the growing shift toward electrification and smart mobility solutions in Europe.
Leading Company Profiles
The competitive landscape of the Europe motor vehicles market features a dynamic mix of traditional automakers, innovative EV manufacturers, and tech-driven mobility providers, fostering intense rivalry and strategic collaborations to capture market share and scale new technological heights.
- Volkswagen Group
- Toyota Motor Corporation
- BMW AG
- Daimler AG
- Stellantis N.V.
- Hyundai Motor Company
- Ford Motor Company
- Tesla Inc.
- Volvo Car Group
- Renault Group
Volkswagen Group
Volkswagen remains the leader in Europe, renowned for its broad portfolio spanning compact cars, luxury vehicles, and electric models, with strategic investments in EV technology and sustainable manufacturing practices to bolster its market leadership.
Toyota Motor Corporation
Toyota is recognized for its hybrid technology and expanding electric vehicle lineup, focusing on innovation and efficiency, while strengthening its strategic alliances within the European automotive supply chain to enhance EV adoption.
BMW AG
BMW specializes in premium vehicles, increasingly emphasizing electrification through its i-series, with a focus on luxury, performance, and cutting-edge digital integration, maintaining competitive edge in Europe’s high-end segments.
Daimler AG
Daimler’s Mercedes-Benz brand drives its leadership in luxury electric vehicles and sustainability initiatives, investing heavily in battery technology and expanding its EV manufacturing capacity within Europe.
Stellantis N.V.
Stellantis, formed from a merger, leverages its extensive portfolio of brands to accelerate electrification efforts and digital transformation, aiming for a significant share in Europe’s rapidly evolving EV market.
Hyundai Motor Company
Hyundai has significantly increased its market share by introducing a competitive range of electric models and investing in innovative EV battery technologies to support its growth in Europe’s sustainable mobility landscape.
Ford Motor Company
Ford is expanding its electric vehicle offerings and investing in local production facilities in Europe, with a strategic focus on electric commercial vehicles and innovative mobility solutions.
Tesla Inc.
Tesla continues to drive innovations in EV technology, with a focus on expanding manufacturing capacities in Europe, strengthening charging infrastructure, and enhancing autonomous driving capabilities to maintain market dominance.
Volvo Car Group
Volvo is committed to electrification, aiming for a fully electric lineup by 2030, with strategic investments in battery technology and sustainable manufacturing practices to cater to eco-conscious consumers.
Renault Group
Renault’s focus remains on affordable electric vehicles, expanding its EV portfolio, enhancing battery recycling processes, and strengthening collaborations for advanced mobility solutions in Europe.
Strategic Business Developments

- January 2024 – Volkswagen Group – Launch of new MEB-based electric SUV – Strengthens EV offerings and enhances market competitiveness in Europe.
- March 2024 – Toyota Motor Corporation – Announced expansion of hybrid and electric vehicle plant facilities across Europe – Improves local production capacity and reduces supply chain dependencies.
- June 2024 – BMW AG – Introduction of their latest digital cockpit technology in luxury EVs – Reinforces brand position through advanced connectivity and user experience.
- August 2024 – Daimler AG – Investment in battery manufacturing facilities in Germany – Boosts sustainable manufacturing and supports growing EV demand.
- October 2024 – Stellantis N.V. – Formation of new joint venture with local European tech firms to develop autonomous driving software – Accelerates digital transformation in European markets.
Frequently Asked Questions
What is the Europe Motor Vehicles Market?
The Europe Motor Vehicles Market encompasses the manufacturing, distribution, and sales of passenger cars, commercial vehicles, and electric vehicles across European countries. It reflects the region's automotive industry dynamics, consumer preferences, and technological advancements.
What is the current market size of Europe Motor Vehicles Market?
As of 2026, the Europe Motor Vehicles Market is valued at approximately USD 338 Billion, driven by increasing demand for electric vehicles, stringent emission regulations, and technological innovations, positioning Europe as one of the largest automotive markets globally.
What factors are driving the Europe Motor Vehicles Market?
Market growth is fueled by the rising shift towards electric and hybrid vehicles, government incentives for sustainable transportation, investments in automotive innovation, expanding urban populations, and the recovery of automotive sales post-pandemic, supporting long-term industry expansion.
Which region dominates the Europe Motor Vehicles Market?
Western Europe leads the market, with countries like Germany, France, and the UK contributing the most significant shares due to established automotive industries, high consumer purchasing power, and progressive adoption of EV technologies.
Which segment is expected to grow the fastest?
The electric vehicles (EV) segment is projected to experience the fastest growth, with a CAGR of approximately 7.7% from 2026 to 2034, driven by declining battery costs, stricter environmental policies, and expanding charging infrastructure.
Who are the leading companies operating in the Europe Motor Vehicles Market?
Major players include Volkswagen Group, Toyota, Stellantis, Ford, and BMW, which dominate through expansive portfolios, innovation in electric vehicles, and strategic collaborations within the European automotive landscape.
Analyst Perspective
The Europe motor vehicles market is poised for sustained growth through 2034, driven by advancing electrification, regulatory incentives, and evolving consumer preferences. Long-term prospects remain robust, with the transition to electric vehicles (EVs) serving as a core growth catalyst, creating significant opportunities for automakers and suppliers to innovate with batteries, charging infrastructure, and connected vehicle technologies. Investment priorities should favor R&D in EV battery chemistry, autonomous driving capabilities, and digital mobility solutions to stay ahead in a competitive landscape marked by increasing OEM alliances and tech firm engagements. Regional growth potential is uneven, with Western Europe leading due to strong regulatory support and consumer adoption, while Eastern Europe offers opportunities for scalable manufacturing and cost optimization. However, risks persist from geopolitical tensions, supply chain disruptions, and the pace of technological adoption. Strategically, players should balance innovation with cost efficiency, prioritize sustainable mobility offerings, and leverage regional strengths to secure long-term market positioning amidst intensifying competition.
