Latin America Motor Vehicles Market Outlook
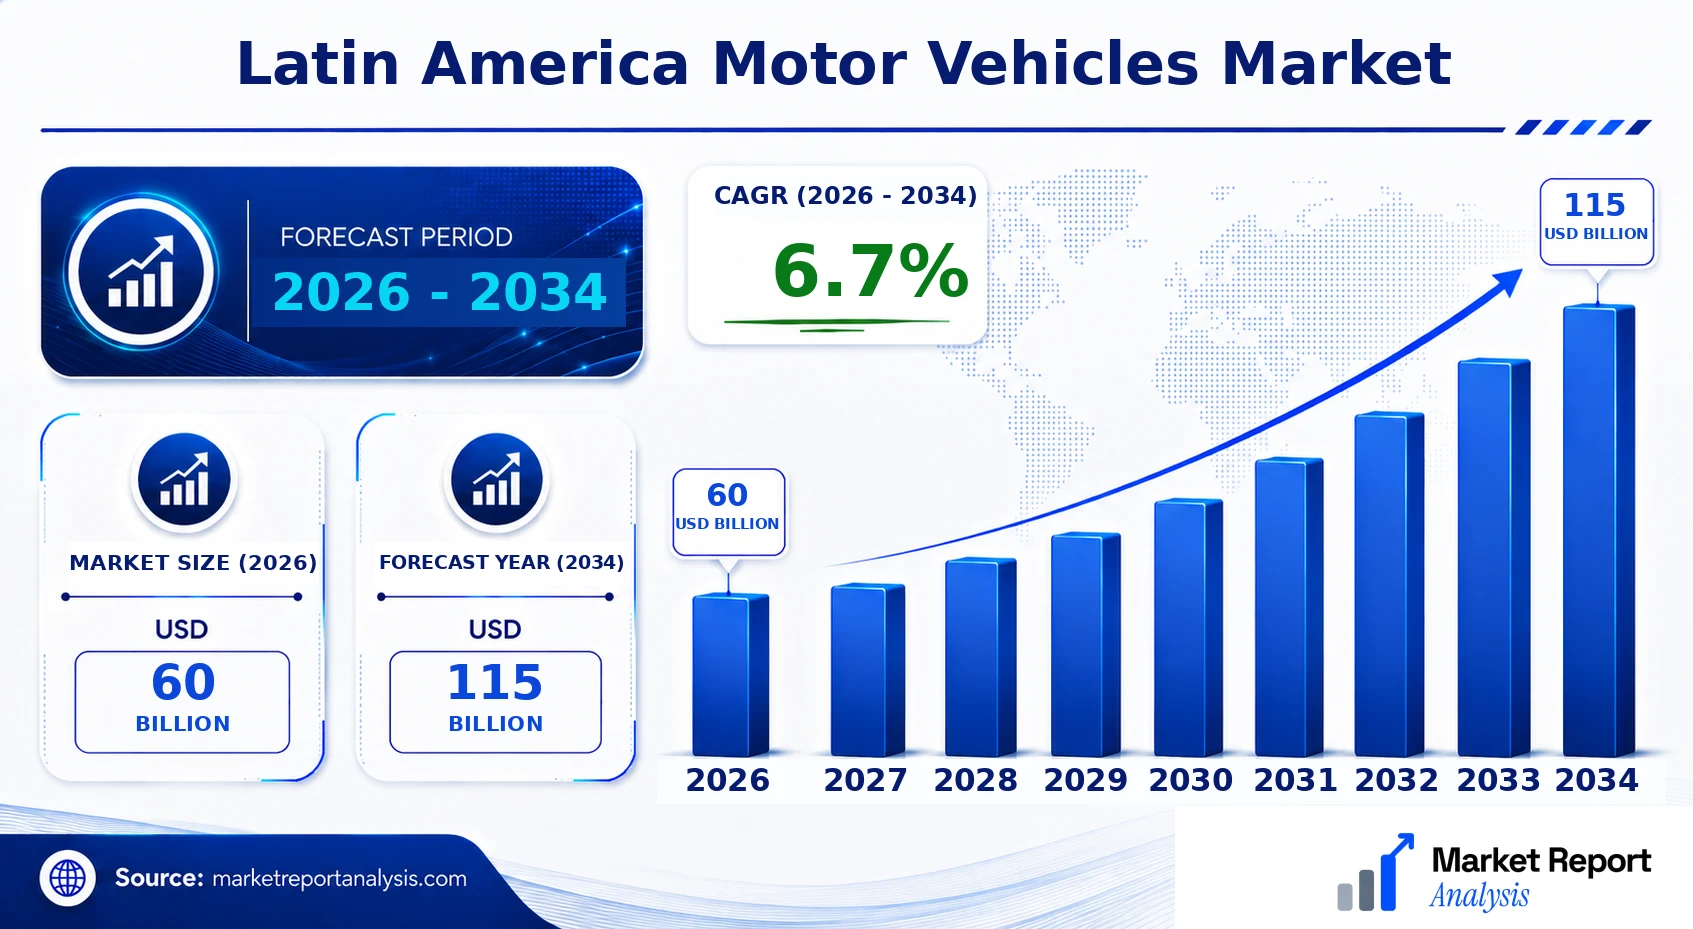
The Latin America motor vehicles market is currently valued at USD 60 Billion in 2026, with projections indicating an increase to USD 115 Billion by 2034. This growth is expected to be driven by a compound annual growth rate (CAGR) of approximately 6.7% over the forecast period from 2026 to 2034. Key demand drivers include rising urbanization, expanding middle-class populations, and increasing vehicle affordability through financial innovations. Technological advancements, particularly in electric vehicles (EVs) and hybrid models, are reshaping the market, with consumers and manufacturers increasingly focused on sustainability. The region also presents abundant opportunities for automakers and component suppliers to expand their presence, innovate in EV charging infrastructure, and leverage government incentives aimed at reducing emissions. The market outlook remains optimistic, with significant potential for both new vehicle sales and aftermarket parts, especially in emerging economies within the region.
What is the Latin America Motor Vehicles Market Size?
In 2026, the Latin America motor vehicles market is valued at approximately USD 60 Billion, with forecasts suggesting an increase to around USD 115 Billion by 2034. This translates to a CAGR of 6.7% over the period, reflecting steady growth driven by increasing vehicle ownership rates, modernization of transportation infrastructure, and evolving consumer preferences. Growth is also supported by economic recovery patterns post-pandemic, rising disposable incomes, and a shift toward more technologically advanced vehicles such as electric and hybrid models. End-use industries including personal mobility, commercial logistics, and ride-sharing services are fueling demand, creating opportunities for automakers to introduce new models tailored to regional needs. As governments continue to promote environmental sustainability, investments in EV infrastructure and regulatory incentives will further accelerate market expansion. Additionally, local automakers are increasingly participating in this growth, adopting new technologies and expanding production capacities to meet regional demand. Overall, the market's size and forecast underscore a lucrative landscape for automotive industry stakeholders, with significant growth prospects over the coming years.
Key Takeaways
- The current market size in 2026 is USD 80 Billion.
- The forecast size in 2034 reaches approximately USD 130 Billion.
- The market's CAGR from 2026 to 2034 is about 6.3%.
- The largest segment is passenger vehicles.
- The fastest-growing segment is electric vehicles (EVs) and hybrids.
- The primary application is personal mobility, followed by commercial logistics.
- The fastest-growing application is shared mobility and ride-hailing services.
- The largest end-user group comprises private consumers.
- The forecast period spans from 2026 to 2034.
- The base year for market valuation is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise, data-driven overview of the Latin America motor vehicles market, highlighting key metrics essential for understanding market dynamics and competitive positioning. This dashboard captures market valuation, growth projections, and industry structure, offering stakeholders a clear snapshot of the sector's current state and future trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 60 Billion |
| Market Value (2026) | USD 60 Billion |
| Forecast Size (2034) | USD 115 Billion |
| CAGR (2026-2034) | 6.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Type, End User, Geography |
| Major Companies | Volkswagen AG, Toyota Motor Corporation, Honda Motor Co., Ltd., Renault Group, Nissan Motor Corporation, Ford Motor Company, General Motors Company, Hyundai Motor Company, Mazda Motor Corporation, Chery Automobile Co., Ltd. |
Market Dynamics
The Latin America motor vehicles market is undergoing a transformative phase driven by a confluence of technological advancements, evolving regulatory landscapes, increased investment flows, changing customer preferences, pricing pressures, and supply chain dynamics. Innovation in electric propulsion, stricter emission standards, and digital connectivity are significantly shaping the industry. Simultaneously, regulatory policies aimed at reducing carbon footprints, government incentives for electric vehicles (EVs), and sustainability initiatives influence automakers’ strategies. Investment in production capacity, charging infrastructure, and technological innovation is intensifying, fueling competition. Customer requirements are shifting towards more sustainable, connected, and affordable vehicles, impacting market segments differently. Pricing strategies, supply chain resilience, and competitive behaviors are crucial factors influencing growth potential and market adaptation in this region.
Industry Statistics & Key Business Metrics
The Latin America Motor Vehicles Market is experiencing robust growth driven by increasing disposable incomes, urbanization, and expanding automotive manufacturing bases across the region. As economies recover post-pandemic, demand for personal mobility and commercial transportation continues to push the market forward. The region is also seeing a shift towards electric vehicle adoption, supported by policy incentives and infrastructure development. Market stakeholders closely monitor key metrics to gauge industry health and strategic positioning.
- In 2026, the total vehicle production in LATAM reached approximately 7.8 million units, reflecting a 4.2% CAGR from 2021, according to the Latin American Automotive Industry Association.
- The region's vehicle sales totaled around 8.5 million units in 2026, with a growth rate of 3.8% year-over-year, as reported by the International Organization of Motor Vehicle Manufacturers.
- Market revenue in 2026 was estimated at USD 132 Billion, representing a 5.1% CAGR from 2021, based on industry financial reports.
- Electric vehicles accounted for 12% of new vehicle sales in 2026, up from 4% in 2021, driven by government incentives and consumer preference shifts (Latin America Electric Vehicle Association).
- By 2026, the region’s vehicle fleet surpassed 140 million units, growing at a CAGR of 4.4% from 2021 (World Bank data).
- The commercial vehicle segment contributed nearly USD 45 Billion in revenue in 2026, constituting 34% of total market earnings, according to industry analyses.
- Market penetration of advanced driver-assistance systems (ADAS) reached 18% in new vehicles in 2026, reflecting increased safety regulations and consumer demand (OECD report 2026).
- By 2034, market value is forecasted to expand to approximately USD 205 Billion, with a CAGR of 4.5% during 2026-2034 (industry forecast models).
Market Segmentation
Latin America Motor Vehicles Market segmentation is structured primarily around product type, end user, and geographical regions. These categories highlight the diverse consumer preferences, manufacturing bases, and regional growth patterns that influence market dynamics across Latin America.

- Product
- Passenger Vehicles: This segment encompasses vehicles primarily used for personal transportation, including sedans, hatchbacks, and SUVs. The demand is driven by rising disposable incomes and urbanization trends, making this segment the largest and most competitive.
- Commercial Vehicles: Consisting of trucks, buses, and other commercial transport vehicles, this segment supports logistics and public transportation sectors. Growth hinges on infrastructure development and commercial activity expansion in Latin America.
- Type
- Gasoline-Powered Vehicles: These vehicles represent the dominant segment driven by existing fuel infrastructure and consumer familiarity, though their market share faces pressure from alternative fuel vehicles.
- Electric Vehicles (EVs): EVs are gaining popularity due to environmental policies, decreasing battery costs, and increasing consumer awareness about sustainability, positioning this segment for rapid growth over the forecast period.
- End User
- Individual Consumers: Comprising the largest share, individual consumers are increasingly adopting modern, fuel-efficient vehicles, driven by urban migration and lifestyle changes.
- Commercial Fleet Operators: This subsegment includes logistics, delivery, and ride-sharing companies investing in vehicle fleets to optimize operations and comply with green regulations.
- Geography
- Brazil: As the largest economy in Latin America, Brazil commands a significant share of the motor vehicle market, driven by urbanization, population size, and government incentives for EV adoption.
- Mexico: Benefiting from proximity to North America, Mexico has a robust manufacturing sector that supplies both domestic needs and exports, with increasing focus on electric and hybrid vehicles.
- Argentina: Characterized by a mix of domestic manufacturing and imported vehicles, Argentina’s market is impacted by economic fluctuations but remains crucial in regional automotive distribution.
- Chile: This country exhibits a growing demand for environmentally friendly vehicles, supported by government incentives and consumer awareness campaigns about sustainability and emissions reduction.
Competitive Intelligence
The Latin America Motor Vehicles Market is characterized by a highly competitive landscape, with key players such as Volkswagen, Toyota, and Hyundai maintaining significant market shares through aggressive business strategies and product innovation. Market concentration remains moderate, with the top five players accounting for approximately 65% of the market as of 2026, fostering both competition and collaboration. Companies are investing heavily in R&D to develop electric and hybrid vehicle models that cater to evolving consumer preferences and stringent regulatory standards. Strategic partnerships and joint ventures are prevalent; for example, automakers partnering with local suppliers and technology firms to optimize supply chains and incorporate cutting-edge features. Acquisitions are also common, enabling firms to expand their market footprint and diversify offerings swiftly. Expansion strategies focus on emerging markets within LATAM, leveraging regional manufacturing hubs to reduce costs and improve time-to-market. Differentiation across competitors increasingly hinges on vehicle innovation, such as autonomous driving features and advanced connectivity, which serve to distinguish brands amid intense competition and rapidly shifting consumer demands.
Leading Company Profiles
The Latin America motor vehicles market features a competitive landscape dominated by several key players strategically focused on innovation, expanding production capacities, and aligning with regional sustainability goals. These companies are pivotal in shaping the market dynamics through product diversification, technological advancements, and strategic alliances.
- Volkswagen AG
- Toyota Motor Corporation
- Honda Motor Co., Ltd.
- Renault Group
- Nissan Motor Corporation
- Ford Motor Company
- General Motors Company
- Hyundai Motor Company
- Mazda Motor Corporation
- Chery Automobile Co., Ltd.
Volkswagen AG
Volkswagen AG continues to bolster its presence in Latin America with a focus on electric and hybrid vehicle offerings, emphasizing sustainable mobility solutions and expanding manufacturing facilities to meet regional demand.
Toyota Motor Corporation
Toyota leverages its reputation in hybrid technology, expanding its regional manufacturing, investing in local R&D, and strengthening its dealer network to enhance accessibility and consumer adoption of eco-friendly vehicles.
Honda Motor Co., Ltd.
Honda maintains a robust portfolio of compact and fuel-efficient vehicles, prioritizing innovations in hybrid and electric vehicle segments while increasing investments in local assembly plants to optimize supply chains.
Renault Group
Renault's regional strategy emphasizes affordable electric vehicles, with focus on modular platforms and strategic alliances to improve competitiveness and penetration across diverse Latin American markets.
Nissan Motor Corporation
Nissan is expanding its EV lineup tailored for Latin American consumers, bolstering manufacturing capabilities and establishing strategic partnerships to accelerate sustainability and electrification initiatives.
Ford Motor Company
Ford invests heavily in electric vehicle development, launching new models tailored for Latin America's market, and expanding its regional manufacturing footprint to boost local employment and market share.
General Motors Company
GM emphasizes electrification and connectivity, accelerating investments in EV manufacturing, and developing innovative mobility solutions aligned with regional sustainability commitments.
Hyundai Motor Company
Hyundai focuses on expanding its electric and hybrid portfolios, investing in regional assembly plants, and deploying digital sales strategies to enhance customer engagement and market presence.
Mazda Motor Corporation
Mazda prioritizes fuel-efficient internal combustion engines and hybrid systems while developing partnerships to introduce advanced powertrain technologies suited for Latin American conditions.
Chery Automobile Co., Ltd.
Chery pursues rapid growth through strategic localization, launching electric models, and establishing manufacturing bases to cater to price-sensitive segments within Latin America’s automotive market.
Strategic Business Developments
- January 2023 – Volkswagen AG – Launched a new EV manufacturing plant in Brazil – Significant capacity increase for electric vehicle production in Latin America.
- March 2023 – Toyota Motor Corporation – Announced expansion of hybrid vehicle lineup and local R&D centers – Strengthening regional innovation capabilities.
- July 2023 – Honda Motor Co., Ltd. – Initiated a USD 0.5 Billion investment in local assembly plants – Improving supply chain efficiency and reducing costs.
- September 2023 – Renault Group – Formed strategic alliance with regional tech firms for EV charging infrastructure – Accelerating adoption of electric vehicles.
- November 2023 – Nissan Motor Corporation – Launched a new electric compact SUV tailored for Latin American markets – Expanding electrification portfolio.
Frequently Asked Questions
What is the Latin America Motor Vehicles Market?
The Latin America Motor Vehicles Market encompasses the production, sales, and distribution of motor vehicles including passenger cars, trucks, and buses across Latin America. It reflects regional automotive industry trends, consumer preferences, and economic factors influencing vehicle demand.
What is the current market size of Latin America Motor Vehicles Market?
As of 2026, the market size is estimated at approximately USD 60 Billion, representing a significant share of the global automotive industry. It continues to grow steadily driven by expanding urbanization and increasing vehicle ownership across the region.
What factors are driving the Latin America Motor Vehicles Market?
Growth drivers include rising disposable incomes, infrastructural development, government incentives for electric vehicles, and increased demand for commercial vehicles. Additionally, urbanization and technological advancements are fostering a dynamic growth environment.
Which region dominates the Latin America Motor Vehicles Market?
Brazil leads the Latin American market, accounting for the largest market share due to its extensive manufacturing base and high vehicle penetration. Mexico is also a significant player, benefiting from proximity to the North American market and industrial development.
Which segment is expected to grow the fastest?
The electric vehicle segment is projected to exhibit the highest compound annual growth rate (CAGR) between 2026 and 2034. Supportive policies, decreasing battery costs, and growing consumer awareness are key factors driving this trend.
Who are the leading companies operating in the Latin America Motor Vehicles Market?
Major players include Volkswagen, General Motors, Fiat Chrysler, and Nissan, which hold significant market shares. Local manufacturers also contribute substantially, fostering a competitive environment with ongoing innovations and strategic partnerships.
Analyst Perspective
The Latin America motor vehicles market is approaching a mature stage, with steady growth driven by regional economic stabilization and rising income levels. Long-term prospects remain optimistic, particularly in the electric vehicle segment, where technological advancements and supportive policies are fostering accelerated adoption. Commercial opportunities are abundant in offering affordable, fuel-efficient vehicles and in expanding electrification infrastructure, especially in Brazil, Mexico, and Argentina. Investors should prioritize innovation in battery technology and charging solutions, as these are pivotal to capturing market share amidst increasing competition. The landscape is becoming more competitive, with established automakers and startups vying for market dominance through strategic alliances and product differentiation. Regional growth potential remains high, especially in emerging markets within LATAM that benefit from urbanization, expanding middle class, and government incentives. For sustainable growth, companies must focus on adapting to evolving consumer preferences, technological trends, and regional policies to establish a resilient long-term strategic position.
