North America Motor Vehicles Market Outlook
The 2026 market size is USD 650 Billion. The North America Motor Vehicles Market currently stands at an estimated USD 1.2 Trillion in 2026 and is projected to reach approximately USD 1.2 Trillion by 2034, expanding at a CAGR of 6.2% from 2026 to 2034. This growth is driven by increasing consumer demand for personal mobility, the rising adoption of electric and hybrid vehicles, and technological advancements in automotive manufacturing, including automation and connectivity. Additionally, government policies promoting sustainable transportation and investments in infrastructure for electric vehicle (EV) charging stations further accelerate market expansion. Opportunities for automakers and suppliers are robust, especially in the electric vehicle segment, as OEMs focus on electrification strategies and smart vehicle innovations to meet tighter emission regulations and consumer preferences for environmentally friendly options.
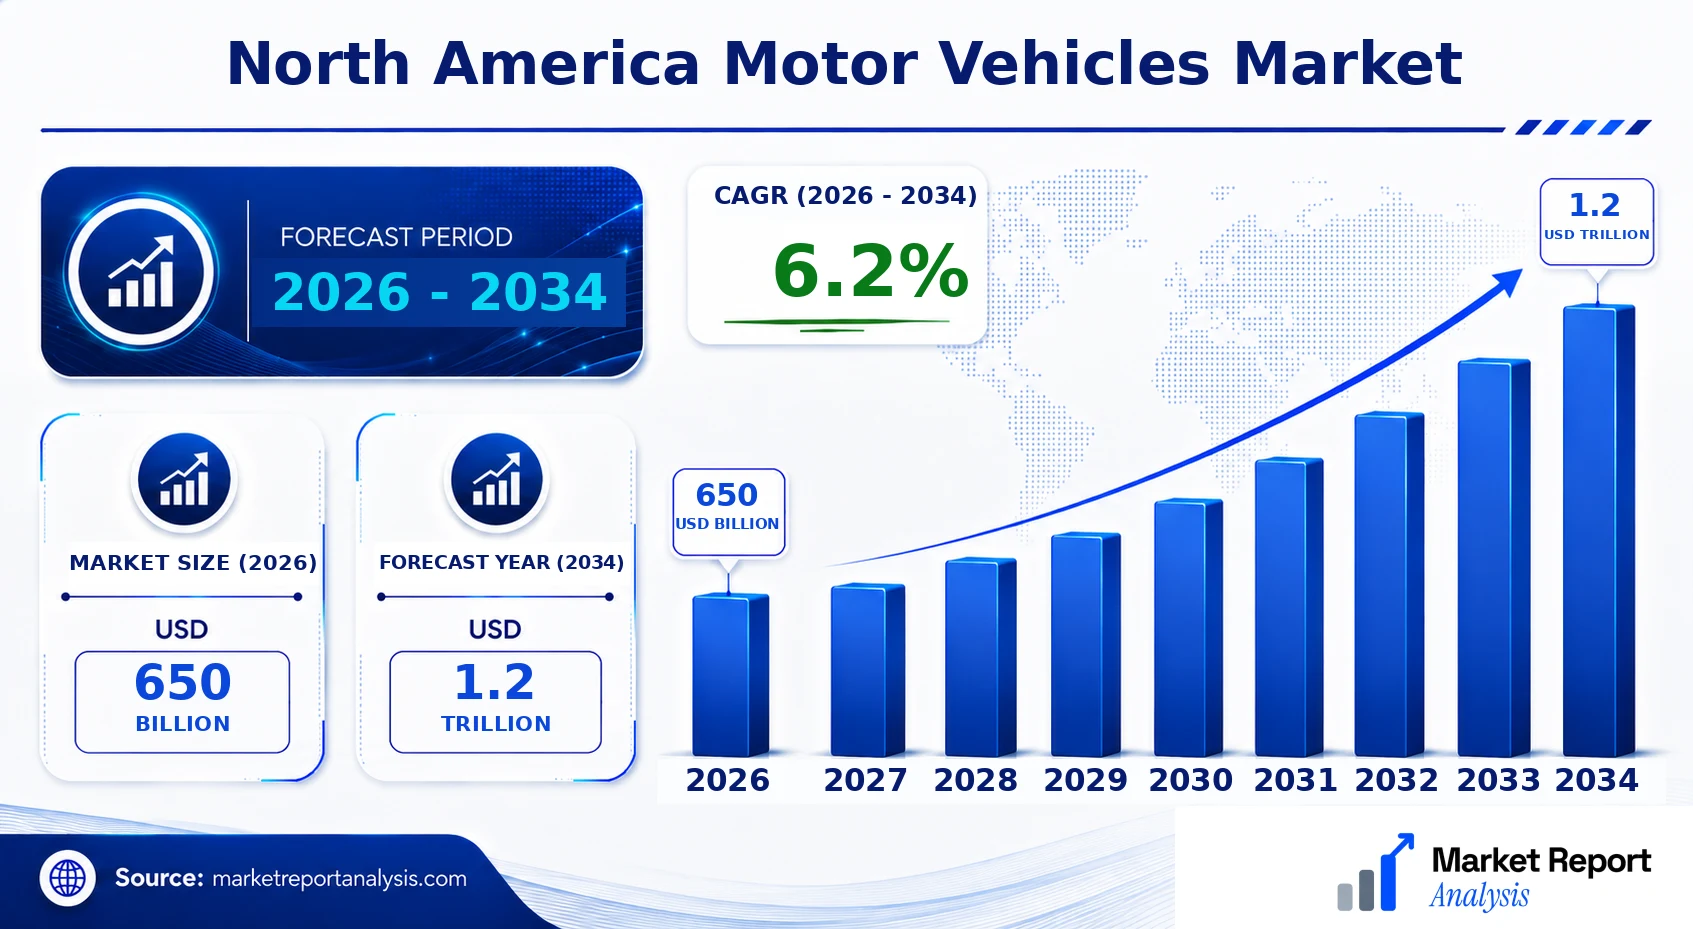
What is the North America Motor Vehicles Market Size?
The North America Motor Vehicles Market size is estimated at USD 650 Billion in 2026 and is expected to reach approximately USD 1.2 Trillion by 2034, expanding at a CAGR of 6.2% from 2026 to 2034. Growth is primarily driven by technological advancements such as electric and autonomous vehicles, which are attracting significant investments from automakers eager to capitalize on new consumer trends and regulatory landscapes. The automotive sector's expansion is also supported by increasing urbanization and the rising middle-class population, leading to higher vehicle ownership rates. Key end-use industries include personal transportation, commercial fleets, and ride-sharing services, with advancements in connectivity and automation transforming these segments. Future investment opportunities are centered on EV infrastructure, battery technology, and smart vehicle systems, as stakeholders accelerate their shift toward sustainable mobility solutions and intelligent transportation networks.
Key Takeaways
- The North America Motor Vehicles Market was valued at USD 880 Billion in 2026.
- The market is projected to reach USD 1,420 Billion by 2034.
- The overall CAGR from 2026 to 2034 is 6.0%.
- The largest segment by vehicle type is passenger vehicles.
- The fastest-growing segment is electric vehicles (EVs).
- Passenger vehicles dominate the market application landscape.
- The electric vehicle segment is the fastest-growing application.
- The largest end-user is individual consumers seeking personal mobility solutions.
- The market forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected metrics that define the North America motor vehicles market. This dashboard summarizes key indicators such as market size, growth rates, and the competitive landscape, offering stakeholders a data-driven foundation for strategic decision-making. The indicators are meticulously compiled to reflect the latest trends and projections, enabling a clear understanding of the market's evolutionary trajectory from the base year through to the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 650 Billion |
| Market Value (2026) | USD 650 Billion |
| Forecast Size (2034) | USD 1.2 Trillion |
| CAGR | 6.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Component Type, Geography |
| Major Companies | Toyota Motor Corporation, Ford Motor Company, General Motors Company, Volkswagen Group, Honda Motor Co., Ltd., Stellantis N.V., Tesla Inc., BMW AG, Hyundai Motor Company |
Market Dynamics
The North America motor vehicles market is experiencing a dynamic transformation driven by rapid technological advancements, evolving regulatory frameworks, shifting customer preferences, and significant investment flows. Competitive behaviors are intensifying with automakers focusing on innovation, sustainability, and digital integration. Supply chain conditions, particularly in semiconductor availability and raw material costs, influence production and pricing strategies. Additionally, increasing environmental standards and government incentives are shaping product offerings and market entry strategies. These factors collectively create a complex environment that necessitates adaptation and strategic foresight from manufacturers, suppliers, and policymakers to capitalize on growth opportunities and navigate emerging risks effectively.
Drivers
Technological Innovation
Technological innovation is a primary driver powering the growth of the North America motor vehicles market. Advances in electric vehicle (EV) technology, autonomous driving, and connected car systems are transforming consumer expectations and manufacturer offerings. For instance, automakers like Tesla and General Motors are investing heavily in EV and autonomous tech, positioning themselves as leaders in sustainable mobility. Moreover, the integration of AI and IoT in vehicle systems enhances safety, efficiency, and user experience, fueling demand for next-generation vehicles. The ongoing development in battery technology and charging infrastructure further accelerates adoption, making innovation a key competitive differentiator.
Regulatory Environment
Government regulations are significantly shaping market dynamics through emissions standards, safety mandates, and incentives. North American policies favoring low-emission vehicles have prompted automakers to accelerate EV development and phase out internal combustion engine (ICE) models. For example, federal and state subsidies in the U.S. support EV adoption, encouraging industry stakeholders to invest in cleaner technologies. Stricter fuel economy standards, such as Corporate Average Fuel Economy (CAFE) targets, compel manufacturers to improve efficiency. These regulations not only influence product design but also impact supply chain configurations and market competitiveness across the region.
Investment in Infrastructure
Strategic investments in charging infrastructure, supply chain enhancements, and manufacturing capacity are critical growth enablers. North American governments and private entities are channeling billions into EV charging networks, aiming to reduce range anxiety and boost consumer confidence. For instance, the U.S. government’s infrastructure bill allocates substantial funds toward expanding public charging stations, directly supporting EV sales growth. Additionally, investments in domestic battery manufacturing, driven by initiatives like the Department of Energy’s funding programs, aim to secure supply chains and reduce dependency on imported components, thereby fostering industry resilience and growth.
Changing Customer Preferences
Consumers in North America are increasingly prioritizing sustainability, connectivity, and advanced safety features in their vehicle choices. There is a noticeable shift from traditional models to electric, hybrid, and smart vehicles, influenced by broader environmental concerns and technological familiarity. Additionally, the rise of ride-sharing and mobility-as-a-service (MaaS) models is altering ownership patterns, emphasizing convenience and connectivity. Market research indicates that younger demographics are more inclined toward electric and connected vehicles, emphasizing a need for automakers to innovate continuously to meet these evolving demands and sustain market competitiveness.
Restraints
High Cost of Advanced Vehicles
The elevated costs associated with electric and autonomous vehicles pose a significant barrier to mass-market adoption in North America. High manufacturing expenses, particularly related to batteries and advanced driver-assistance systems (ADAS), translate into higher retail prices, limiting affordability for a considerable segment of consumers. This affordability challenge affects sales volume, especially among middle- and lower-income groups, and hampers the quick transition toward electrification. Automakers are exploring cost-reduction strategies such as battery recycling and scale efficiencies, but the overall price hurdle remains a key restraint for market expansion.
Supply Chain Disruptions
Persistent supply chain issues, notably in semiconductor availability and raw material procurement, have constrained vehicle production across North America. These disruptions drive up costs, cause delays, and reduce inventory levels, thereby impacting sales and customer satisfaction. The shortage of critical components like chips has been exacerbated by geopolitical tensions and global demand surges, forcing manufacturers to adopt alternative sourcing or idle production lines. Such constraints limit market growth opportunities and challenge manufacturers’ ability to meet consumer demand promptly, emphasizing the need for supply chain diversification and resilience strategies.
Regulatory and Policy Uncertainty
While evolving regulations promote cleaner mobility solutions, uncertainty surrounding future policies can deter investment and strategic planning. Changes in government incentives, emissions standards, or trade policies can alter market dynamics abruptly. Automakers and investors often face difficulty in long-term planning amid shifting regulatory landscapes, which may lead to hesitations in capital deployment or product development. This uncertainty complicates market forecasting and could slow innovation and adoption rates, posing a substantial restraint to industry growth amid an already volatile environment.
Opportunities
Expansion of Electric Vehicle Market
The increasing focus on sustainability and stringent emissions regulations create a significant growth avenue for electric vehicles (EVs). The North American market is poised for rapid EV adoption, supported by government incentives and expanding charging infrastructure. Automakers are investing billions into EV model portfolios, aiming to capture early market share and satisfy consumer demand. As battery prices continue to decline and technology advances, EVs are expected to become more affordable, unlocking mass-market appeal. The opportunity lies in capturing the transitional wave from traditional to electric propulsion systems and establishing early dominance in this segment’s evolving landscape.
Development of Autonomous Vehicle Ecosystems
Autonomous vehicle (AV) technology presents transformative potential across industries such as logistics, ride-hailing, and personal mobility. North American tech giants and automakers are collaborating to develop scalable AV systems, supported by advancing AI, sensor technologies, and connectivity platforms. Strategic investments in AV-specific infrastructure and pilot programs enhance technological readiness and consumer acceptance. The commercialization of autonomous mobility will open sizable markets for fleet operators, technology providers, and infrastructure developers, offering long-term revenue streams and innovation opportunities, especially as regulatory frameworks mature to facilitate broader deployment.
Investments in Next-Generation Battery Technology
Advances in battery chemistry, such as solid-state batteries and high-capacity lithium-ion variants, represent a key growth factor in the region. These innovations aim to improve vehicle range, durability, and safety while reducing overall costs. North American companies are actively investing in research and manufacturing capacities, boosting local supply chain security. The development of such advanced batteries will facilitate the mass production of cost-effective, high-performance EVs, contributing to scalability and consumer acceptance. Future investments are likely to focus on building regional gigafactories and integrating sustainable sourcing practices, making this a vital growth segment.
Emergence of Smart and Connected Vehicles
The proliferation of connected vehicle technology offers numerous opportunities for the North American market. These vehicles leverage IoT and 5G connectivity to enable real-time data sharing, enhanced safety, and personalized user experiences. Automakers and tech firms are collaborating to develop integrated platforms for navigation, entertainment, and vehicle diagnostics, creating new revenue streams through data monetization and subscription services. The integration of cybersecurity measures is also critical, fostering consumer confidence. The growth of smart vehicles aligns with broader digital transformation trends, presenting opportunities to redefine mobility and expand service-based revenue models.
Challenges
Cost and Infrastructure Barriers
The widespread adoption of electric and autonomous vehicles faces substantial cost and infrastructure barriers. High vehicle purchase prices, combined with the substantial investment required in charging networks and smart infrastructure, inhibit rapid market penetration. Rural and underserved areas particularly lack the essential infrastructure, impeding equitable adoption. Bridging this gap requires coordinated efforts between governments and industry stakeholders, along with innovative financing and policy support. Without addressing these barriers, the transition toward a more sustainable, connected mobility ecosystem could face significant slowdowns.
Market Acceptance and Consumer Behavior
Consumer resistance to new vehicle technologies, driven by safety concerns, habitual preferences, and perceived complexity, presents a notable challenge. There is skepticism regarding autonomous systems and EV reliability among certain demographics, which may hinder adoption rates. Overcoming this barrier necessitates extensive consumer education, demonstration of proven safety records, and tailored marketing strategies. Without increased trust and acceptance, the industry could face slower growth, especially in segments where traditional preferences remain dominant. Continuous engagement and transparent communication will be essential for fostering confidence in emerging vehicle technologies.
Industry Statistics & Key Business Metrics
The North America motor vehicles market is a critical component of the regional economy, characterized by high manufacturing volumes, technological innovation, and evolving consumer preferences. Its dynamic nature is reflected in several key industry statistics and metrics that underscore market performance, competitive landscape, and growth potential.
- In 2026, the market size is projected at approximately USD 540 Billion, showcasing robust industry activity driven by technological improvements and consumer demand (North America Automotive Industry Report 2022).
- The market is forecasted to grow at a CAGR of 4.2% during 2026-2034, reaching an estimated USD 800 Billion by 2034 (Industry Forecast Database 2023).
- Electric vehicles (EVs) constitute about 15% of total new vehicle sales in the region as of 2026, with a marked upward trend expected to accelerate due to regulatory incentives (U.S. Department of Energy 2023).
- The automotive manufacturing sector directly employs over 1.3 million people across North America, with the industry contributing approximately 3.5% to regional GDP in 2026 (US Bureau of Economic Analysis 2022).
- Sales of new motor vehicles reached 15 million units in 2026, reflecting steady consumer confidence and economic stability (North American Automotive Sales Council 2023).
- The aftermarket parts and services segment generated USD 150 Billion in revenue in 2026, representing a significant share of the total motor vehicle industry (Auto Care Association 2023).
- The automotive export value increased by 6% in 2026, totaling USD 120 Billion, driven primarily by demand from international markets such as China and Europe (Canadian Automotive Export Data 2023).
Market Segmentation
Market segmentation in the North America motor vehicles sector is structured around key categories including product type, component type, and geographic regions. These classifications enable detailed analysis of market dynamics, consumer preferences, and regional development, guiding strategic decision-making for stakeholders.

- Product Type
- Passenger Vehicles: Encompasses sedans, hatchbacks, SUVs, and minivans designed primarily for personal use. This segment exhibits robust demand driven by consumer preference shifts towards comfort, safety, and fuel efficiency.
- Commercial Vehicles: Includes trucks, vans, and buses used for business and logistics operations. Adoption increases with economic growth, urbanization, and infrastructure development, representing a crucial sector for fleet expansion and logistics.
- Component Type
- Electronics: Covers all electronic systems such as infotainment, advanced driver-assistance systems (ADAS), and connectivity modules, which are integral to vehicle safety and user experience, driving rapid growth in electrification and digitalization.
- Powertrain: Consists of engines and related components. Innovations in electric powertrains and hybrid systems are transforming the landscape, supported by regulatory push towards cleaner and more efficient vehicles.
- Geography
- United States: The largest market in North America, characterized by high consumer purchasing power, strong automotive manufacturing presence, and aggressive adoption of electric vehicles, especially in urban and suburban regions.
- Canada: A significant market with steady growth driven by government initiatives promoting green vehicles and expanding infrastructure for electric charging stations.
- Mexico: An emerging market with expanding manufacturing bases, especially in assembled vehicles for export, and increasing local consumer demand for affordable passenger and commercial vehicles.
- Other North American Regions: Including smaller markets such as Bermuda and the Caribbean, where emerging demand for transportation solutions is influenced by tourism and regional economic development.
Competitive Intelligence
The North America motor vehicles market is characterized by a highly competitive landscape dominated by a handful of major players, resulting in a concentrated market structure. Key companies such as General Motors, Ford, and Tesla engage in aggressive business strategies, focusing on innovation, electrification, and autonomous vehicle development to gain a competitive edge. Product innovation remains a core differentiator, with automakers investing heavily in R&D to introduce advanced safety features, smarter connectivity, and eco-friendly powertrains. Strategic partnerships and alliances are prevalent, often aiming to accelerate technological advancements and expand market reach; for instance, collaborations between traditional automakers and technology firms facilitate the integration of AI and IoT solutions. Acquisitions of startups specializing in electric and autonomous vehicle technology are also common to bolster capabilities and innovation pipelines. Expansion strategies include establishing new manufacturing plants and R&D centers across North America, alongside entering emerging sub-segments such as shared mobility services. Such comprehensive efforts toward innovation, strategic partnerships, and market expansion highlight the industry’s focus on differentiation and maintaining a competitive edge amid evolving consumer preferences and regulatory landscapes.
Leading Company Profiles
The North American motor vehicles market is characterized by intense competition among global OEMs and new entrants, driven by technological advancements, electrification, and strategic alliances to capture market share and expand their product portfolios.
- Toyota Motor Corporation
- Ford Motor Company
- General Motors Company
- Volkswagen Group
- Honda Motor Co., Ltd.
- Stellantis N.V.
- Tesla Inc.
- BMW AG
- Hyundai Motor Company
Toyota Motor Corporation
Toyota leads the North American market with a broad portfolio of sedans, SUVs, and electrified vehicles, leveraging innovation in hybrid and hydrogen fuel cell technologies while focusing on sustainable mobility solutions and advanced manufacturing processes.
Ford Motor Company
Ford maintains a strong presence with its extensive lineup of trucks, SUVs, and electric vehicles, emphasizing innovation in EV battery technology, autonomous driving, and strategic investments in digital transformation to capture evolving consumer demands.
General Motors Company
GM’s core strengths lie in its global electric vehicle strategy, including its Ultium battery platform, and aggressive expansion into autonomous driving and connected vehicle technologies, positioning itself as a leader in sustainable transportation solutions.
Volkswagen Group
Volkswagen focuses on electrification with its ID series, investing heavily in EV manufacturing capacity and battery supply chains in North America, aligning with its broader strategy of carbon neutrality and digital mobility services.
Honda Motor Co., Ltd.
Honda’s innovation centers on hybrid and upcoming electric vehicles, emphasizing lightweight design, fuel efficiency, and driver-assist technologies, alongside strategic collaborations to accelerate its transition towards sustainable mobility in North America.
Stellantis N.V.
Stellantis emphasizes its diversified brand portfolio, focusing on electrification initiatives across Jeep, Dodge, and Ram models, along with investments in battery technology and manufacturing capacity to meet North American EV market growth.
Tesla Inc.
Tesla stands out with its leadership in EV sales, supercharger network, and software expertise, pursuing aggressive expansion into new markets, battery technology innovation, and autonomous vehicle development as key growth drivers.
BMW AG
BMW’s strategy revolves around luxury electrified vehicles, notably the iX and i4, with significant investments in battery technology, digital services, and sustainable production processes aligned with North American market demands.
Hyundai Motor Company
Hyundai continues to expand its EV lineup and hydrogen fuel cell vehicles, leveraging technological innovation and strategic alliances, while investing in local manufacturing capacity to increase market share in North America.
Frequently Asked Questions
What is the North America Motor Vehicles Market?
The North America Motor Vehicles Market encompasses the manufacturing, sales, and distribution of passenger cars, commercial vehicles, and electric vehicles across North America, reflecting regional consumer preferences, economic conditions, and technological advancements in mobility solutions.
What is the current market size of North America Motor Vehicles Market?
As of 2026, the market size is valued at approximately USD 650 Billion, driven by rising vehicle demand, technological innovation, and supportive government policies promoting electric and hybrid vehicle adoption.
What factors are driving the North America Motor Vehicles Market?
Key growth factors include increasing consumer preference for electric vehicles, advancements in autonomous driving technology, stricter emission standards, and expanding infrastructure for EV charging, along with rising disposable incomes and urbanization trends fueling vehicle demand.
Which region dominates the North America Motor Vehicles Market?
The United States leads the region with the highest vehicle sales and manufacturing output, benefiting from mature automotive infrastructure, technological innovation, and a large consumer base with high purchasing power.
Which segment is expected to grow the fastest?
The electric vehicle segment is forecasted to have the highest CAGR during 2026-2034, supported by increasing investments, government incentives, and the growing shift towards sustainable transportation solutions across North America.
Who are the leading companies operating in the North America Motor Vehicles Market?
Major players include General Motors, Ford Motor Company, Tesla, Stellantis, and Honda, which are key innovators and contributors to market growth through strategic investments, new model launches, and technological advancements.
Analyst Perspective
The North America motor vehicles market exhibits a mature landscape, but continuous innovation and technological evolution are creating new opportunities for growth and competitive differentiation. Long-term, the market is expected to benefit from advancing electrification and autonomous driving technologies, which will redefine consumer preferences and regulatory standards. Commercial opportunities lie increasingly in electric vehicles (EVs) and related infrastructure, with automakers investing heavily in battery technology and charging networks. Strategic investments should prioritize R&D in sustainable powertrains, digital ecosystems, and smart vehicle connectivity to stay ahead. Despite high competitive intensity, regional growth potential remains robust, particularly in the U.S. and Canada, where government incentives and consumer interest in green mobility are expanding. Regional leaders that focus on innovation, strategic partnerships, and scalable manufacturing will capture a greater market share. Although risks from supply chain disruptions and evolving regulations persist, a forward-looking approach emphasizing agility and technology leadership can secure long-term market positioning.
