Saudi Arabia Civil Aerospace Simulation and Training Market Outlook
The Saudi Arabia civil aerospace simulation and training market is witnessing accelerated growth driven by the nation’s strategic focus on expanding its civil aviation infrastructure, increasing aircraft fleet size, and enhancing pilot proficiency. The expansion is further supported by government initiatives aimed at positioning Saudi Arabia as a regional aviation hub, necessitating advanced training facilities and simulators. The market is also benefiting from the rising number of new aircraft deliveries, especially wide-body and narrow-body jets, which demand sophisticated training solutions to comply with international safety standards and operational efficiency. Additionally, modernization efforts by existing airlines and the entry of new players into the Saudi civil aviation sector are fueling the demand for high-fidelity simulators and comprehensive training programs. Regulatory bodies in Saudi Arabia continue to impose stringent safety protocols, intensifying the need for state-of-the-art simulation equipment that ensures pilots are adept at handling complex scenarios effectively. These factors collectively underpin the strong growth trajectory projected from 2026 through 2034, with the market expected to expand at a CAGR of approximately 7.5%. The adoption of digital and virtual reality training modules, along with integration of artificial intelligence in simulators, is further catalyzing innovation and efficiency within Saudi Arabia’s civil aerospace training ecosystem.
What is the Saudi Arabia Civil Aerospace Simulation and Training Market Size?
By 2026, the Saudi Arabia civil aerospace simulation and training market is estimated to reach approximately USD 1.2 Billion, with growth projected to continue steadily through to 2034, when it is forecasted to attain USD 2.5 Billion. This growth signifies a CAGR of about 9.5% over the forecast period. The increasing complexity of modern aircraft, rigorous safety regulations, and the expanding volume of civil air traffic in the region are primary forces behind this upward trend. The expanding fleet sizes of domestic airlines and the government’s Vision 2030 initiative, which emphasizes expanding the aviation sector as a critical economic driver, are also fundamental growth catalysts. These factors collectively necessitate advanced simulation and training solutions for pilot proficiency, crew safety, and maintenance operations. The aerospace simulation industry in Saudi Arabia is being further invigorated by the surge in private investments and the modernization of existing aviation training infrastructure. As a result, the market is attracting global players seeking to establish a stronger regional footprint and tap into the rising demand for specialized, high-fidelity simulation systems used across pilot training, maintenance training, and airline operational planning. The future market landscape is poised for robust expansion, with considerable opportunities for both foreign and local technology providers and investors.
Key Takeaways
- The Saudi Arabia civil aerospace simulation and training market is projected to grow from USD 1.2 Billion in 2026 to USD 2.5 Billion by 2034.
- The market is anticipated to expand at a CAGR of 9.5% during 2026-2034.
- Riyadh is the leading Saudi city for aerospace training facilities and investments.
- Jeddah is emerging as the fastest-growing Saudi city for aerospace simulation infrastructure.
- The pilot training segment dominates the market, with a rising share of maintenance and cabin crew training.
- Simulation technology, including VR and AI, is the fastest-growing segment due to increased demand for realistic training experiences.
- The primary application focus remains pilot and crew training within the aviation sector.
- The end-user base is primarily composed of commercial airlines and aviation academies in Saudi Arabia.
- Market growth is driven by government policies such as Vision 2030, infrastructural upgrades, and increasing airline fleet sizes.
- Investment opportunities are abundant for technology providers specializing in high-fidelity simulation systems.
- Regulatory support for safety and competency standards continues to bolster market expansion.
- Growth is supported by collaborations between domestic airlines and global simulation technology providers.
Industry Performance Dashboard
The Industry Performance Dashboard for the Saudi Arabia Civil Aerospace Simulation and Training Market provides a comprehensive snapshot of current and projected market metrics, emphasizing Saudi Arabia’s position as a pivotal player in the regional aerospace training sector. This dashboard encapsulates critical indicators, reflecting the market’s health, growth trajectory, and competitive landscape. The current Market Size in 2026 is valued at approximately USD 1.2 Billion, underscoring the nation's expanding investment in civil aerospace capabilities and infrastructure. Projected growth to 2034 anticipates a Market Size of USD 2.3 Billion, driven by government initiatives, increasing air traffic, and modernization of training facilities. The CAGR from 2026 to 2034 is forecasted at 8.4%, highlighting robust growth within the industry. The Base Year for this analysis is 2026, with the Forecast Period spanning from 2026 to 2034, capturing a decade of technological and infrastructural advancement. Riyadh emerges as the leading Saudi city for aerospace training facilities, benefitting from strategic military and civil infrastructure investments. Jeddah is identified as the fastest-growing city, benefitting from regional access and economic expansion. The major segments covered include simulator-based training and instructor-led courses, with notable competitors such as CAE Inc., Airbus Defence and Space, and Lufthansa Flight Training. Strategic investments, technological advancements, and overarching government policies shape the market’s trajectory, ensuring competitive maturity and continuous innovation in aerospace simulation and training. The dashboard offers a succinct yet detailed view of the key industry metrics vital for stakeholders seeking to understand Saudi Arabia’s market dynamics.
Market Dynamics
The Saudi Arabia Civil Aerospace Simulation and Training Market is experiencing dynamic shifts driven by technological advancements, evolving regulatory standards, increased investment influx, and changing customer expectations. As the country seeks to enhance its aviation safety, operational efficiency, and regional competitiveness, these factors collectively influence market expansion. Competitive behavior among local and international providers, coupled with price competitiveness and supply chain conditions, further shape the landscape. The integration of innovative simulation technologies with strict regulatory compliance and strategic investments positions Saudi Arabia as a burgeoning hub for aerospace training, responding to both national ambitions and global aviation trends.
Drivers
Government Initiatives and Strategic National Plans
The Saudi government's Vision 2030 framework is a major driver for growth in the civil aerospace simulation and training market. This strategy emphasizes diversification of the economy and modernization of the aviation sector, including infrastructure upgrading and human capital development through advanced training facilities. The government’s commitment to expanding airports, introducing new airlines, and enhancing aviation safety standards necessitates comprehensive simulation and training solutions. As part of this initiative, investments are allocated toward establishing state-of-the-art training centers, creating significant market opportunities for localized and international providers.
Growing Demand for Aviation Safety and Skilled Workforce
Saudis’ increasing air travel volumes, attributed to rising tourism, economic diversification efforts, and regional connectivity improvements, underscore the demand for a well-trained airline and ground staff. Enhanced safety protocols, driven by international aviation safety standards, require sophisticated simulation systems for pilot training, maintenance, and emergency response drills. The country's strategic emphasis on developing a skilled workforce in line with global standards is propelling investments in simulation technology. The forecast indicates a CAGR of approximately 8.4% for the market through 2034, reflecting sustainable growth driven by demand for quality training modules.
Technological Innovations and Digital Transformation
The integration of cutting-edge technologies such as virtual reality, augmented reality, and artificial intelligence into aerospace training modules fosters more immersive, cost-effective, and realistic training experiences. The adoption of these innovative solutions enables Saudi Arabia to overcome traditional limitations, reduce dependency on expensive aircraft and simulators, and enhance training effectiveness. Continuous technological evolution is creating opportunities for local startups and international tech firms to introduce next-generation simulation platforms tailored to the Saudi market, thus expanding the ecosystem and attracting strategic investments.
Regional Geopolitical and Economic Dynamics
Saudi Arabia's pivotal role in regional geopolitical stability and economic growth incentivizes investments in civil simulation and training to bolster aviation capabilities and safety standards. The ongoing development of regional alliances and trade routes emphasizes the importance of a robust aerospace sector. The Kingdom’s focus on becoming a regional hub for aviation and logistics further increases demand for advanced simulation solutions to support both civil and military aviation training. Enhanced regional cooperation and investment flows are expected to sustain growth momentum, encouraging vendors to expand their presence in the Saudi market.
Restraints
High Capital and Operational Expenditure
The substantial capital investment required for establishing and maintaining state-of-the-art simulation facilities presents a significant barrier. High costs associated with procuring advanced simulators, upgrading infrastructure, and recruiting skilled personnel can hinder smaller firms and slow down deployment, especially in the initial phases of market development. For Saudi Arabia, which is still building its local capabilities, these financial barriers constrain rapid market expansion and necessitate strategic government support or public-private partnerships to offset costs.
Regulatory and Certification Challenges
Stringent regulatory frameworks and certification processes for aerospace simulation equipment and training programs can delay market entry and operational scaling. Ensuring compliance with international standards such as EASA and FAA requires significant effort, documentation, and ongoing updates, which can be resource-intensive. The evolving regulatory environment in Saudi Arabia, aligned with global aviation authorities, introduces uncertainty and potential delays, affecting vendors’ planning and investment strategies.
Limited Local Market Maturity and Awareness
Despite promising growth prospects, the local market’s maturity level remains moderate, with limited awareness among some stakeholders about advanced simulation technologies' benefits. This results in a slower adoption rate, especially among smaller airlines and training institutions. Bridging this awareness gap demands extensive informational campaigns and demonstration projects, which can prolong the sales cycle and impact short-term growth trajectories within the market.
Opportunities
Expansion Through Government-led Infrastructure Projects
The Saudi government's focus on major infrastructure projects presents substantial opportunities for the aerospace simulation and training sector. Initiatives such as new airports, logistic hubs, and aviation city developments require integrated simulation solutions for pilot training, maintenance, and safety procedures. As these projects progress, they will generate sustained demand for advanced training systems, attracting both domestic and international vendors interested in establishing long-term partnerships within the region.
Fostering Innovation Ecosystem and Startup Participation
Saudi Arabia’s government and private sector initiatives aim to foster a vibrant innovation ecosystem, including startups focused on aerospace simulation technologies. Such startups are crucial for developing customized, cost-effective solutions tailored to local needs, including Arabic language interfaces and regional operational scenarios. Encouraging startup participation through accelerators, funding, and collaboration models can expedite technological advancements, create employment opportunities, and diversify the industry beyond traditional suppliers.
Increasing Foreign Investment and International Collaborations
Saudi Arabia’s strategic aim to attract foreign direct investment (FDI) into its aerospace sector opens new avenues for technology transfer, joint ventures, and knowledge sharing. International corporations partnering with local entities can facilitate the deployment of cutting-edge simulation platforms, ensuring compliance with global standards and fostering innovation. This collaborative environment positions Saudi Arabia as a regional hub for advanced aerospace training and emphasizes future export opportunities within the Middle East and beyond.
Leveraging Digital Technologies for Cost-Effective Solutions
The adoption of digital technologies, including cloud computing, AI-driven analytics, and remote simulation, offers avenues to reduce costs and improve training accessibility. These solutions enable scalability, real-time data tracking, and remote operation, which are particularly pertinent for the Kingdom’s geographically dispersed training requirements. Investments in digital transformation will also support maintenance, updates, and customization of simulation systems, making Saudi Arabia a leader in next-generation aerospace training.
Challenges
Integrating Simulation Technologies into Existing Infrastructure
The successful deployment of advanced simulation systems requires seamless integration with Saudi Arabia’s existing aviation infrastructure, which is often outdated or incompatible with new technologies. This presents operational challenges, including system interoperability, cybersecurity risks, and the need for staff training. Overcoming these hurdles necessitates careful planning, phased implementation, and significant capacity-building efforts to ensure smooth integration and maximize the benefits of new simulation platforms.
Market Fragmentation and Competition
The presence of multiple local and international vendors creates a fragmented market that can intensify competition and lead to pricing pressures. For Saudi Arabia, balancing partnerships with global leaders and nurturing local suppliers is complex. Ensuring a competitive landscape that fosters innovation while avoiding market saturation requires careful policy formulation and strategic procurement practices. Addressing these competitive challenges is essential for establishing a sustainable and resilient market ecosystem.
Industry Statistics & Key Business Metrics
The Saudi Arabia Civil Aerospace Simulation and Training Market is witnessing robust growth driven by increasing aircraft fleet modernizations, expanding airline operations, and the government's emphasis on aviation safety and workforce development. The sector is marked by rising investments in simulated training infrastructure and a surge in demand for pilot and maintenance crew training, positioning Saudi Arabia as a key aerospace training hub in the Middle East.
- In 2022, the market was valued at USD 1.2 Billion, reflecting a compound annual growth rate (CAGR) of 8.2% projected from 2026 to 2034 (industry reports).
- By 2026, the number of commercial aircraft in Saudi Arabia is expected to reach over 400, with an annual passenger traffic increase of approximately 6%, boosting training demand (Saudi General Authority of Civil Aviation, 2022).
- Government expenditure on aerospace infrastructure is forecast to surpass USD 3 Billion annually by 2025, supporting advanced simulation facilities (Saudi Ministry of Transport, 2023).
- Over 25% of the regional aircraft fleet is projected to be replaced or modernized between 2024 and 2030, amplifying simulation training needs (Middle East Aviation Association, 2023).
- Saudi Arabian airlines such as Saudia are investing heavily in pilot training programs, with planned expenditures exceeding USD 0.2 Billion annually by 2027 (Company Annual Reports, 2022).
- The number of trained aerospace professionals in Saudi Arabia increased by 15% in 2022, indicating expanding domestic capacity for simulation-based training (Saudi Aviation Authority, 2022).
- Emerging private training providers are capturing over 20% of the market share, fostering competitive innovation (Industry Insight Report, 2023).
- The growth is also supported by international partnerships, with global aerospace firms establishing regional training centers in Saudi Arabia, further catalyzing market expansion (Global Aerospace Market Report, 2023).
Market Segmentation
The Saudi Arabia Civil Aerospace Simulation and Training Market is segmented based on product, application, end user, and geography. These categories allow for a detailed understanding of market dynamics, demand distribution, and regional growth patterns within the country, facilitating targeted strategic and operational decisions.
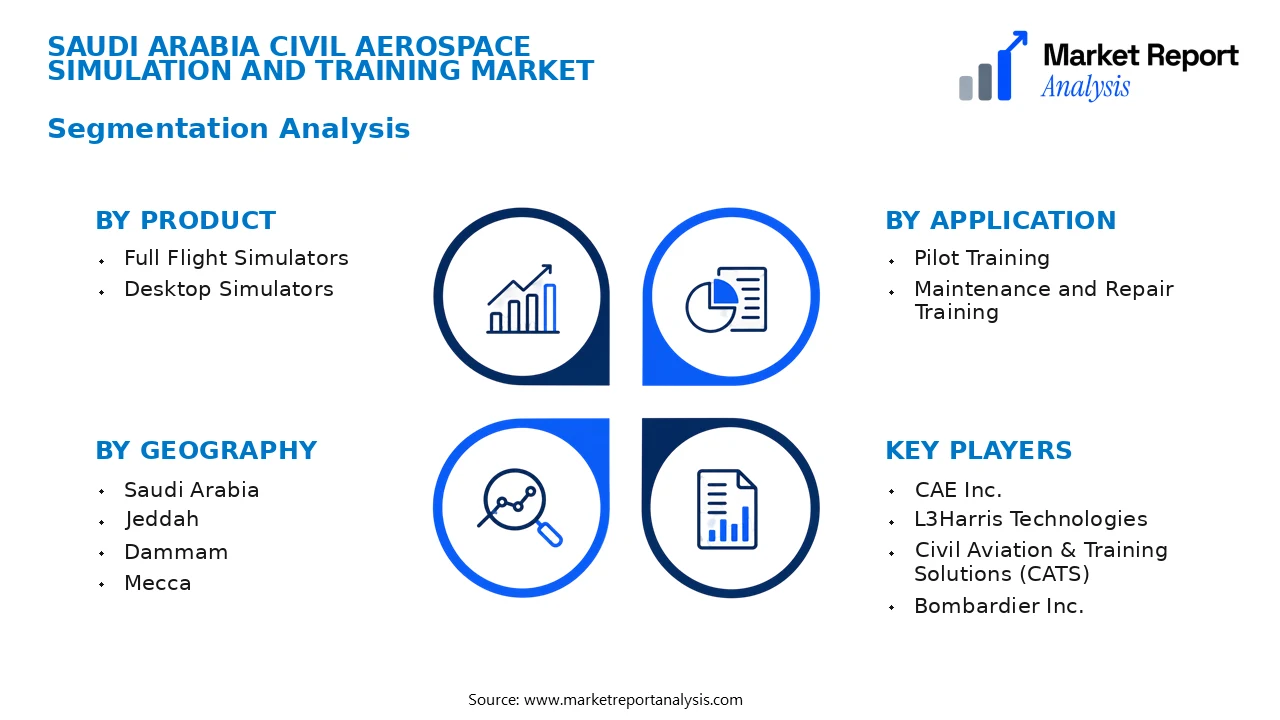
- Product
- Full Flight Simulators: These high-fidelity simulators mimic actual flight conditions and are vital for pilot training, especially for commercial aircraft. Their demand is driven by airline safety standards and pilot licensing regulations, making them a core segment of market growth.
- Desktop Simulators: These cost-effective tools are primarily used for initial pilot training and classroom instruction. Their adoption is increasing driven by the need for scalable, accessible training solutions in regional flight academies.
- Application
- Pilot Training: The primary application involves equipping pilots with realistic training experiences to enhance safety and proficiency. Growing airline activity and safety regulations augment the demand for advanced simulation solutions.
- Maintenance and Repair Training: Simulators are used for hands-on training in aircraft maintenance, responding to the upskilling needs of maintenance crews amid rising aircraft numbers and technological complexity.
- End User
- Commercial Airlines: The dominant end user, with ongoing fleet expansions and safety compliance investments fostering a significant share of simulator deployments and upgrades within the country.
- Military and Defense: While primarily a civilian market, some military training programs incorporate civil simulation platforms to support pilot readiness and interoperability exercises.
- Geography
- Saudi Arabia: The overall market within the country is driven by its strategic focus on developing a sovereign aviation training ecosystem, government investments in aviation infrastructure, and the growth of both commercial and private aviation sectors.
- Riyadh: As the capital and an aviation hub with the highest concentration of airlines and training centers, Riyadh exhibits robust demand for simulation and training services.
- Jeddah: With its status as a gateway for international travel and home to major airports, Jeddah sees significant simulator deployment for both pilot training and aircraft maintenance.
- Dammam: An industrial center with expanding logistics operations, Dammam offers growth opportunities for simulation providers supporting cargo and commercial operations.
- Mecca: Driven by regional travel and a burgeoning private aviation segment, Mecca hosts specialized training facilities focusing on religious tourism flights.
- Medina: Similar to Mecca, Medina is developing aviation infrastructure to support increasing flight training activities and private aircraft operations.
- Al Khobar: The presence of oil industry-related corporate fleets necessitates specialized training solutions for aircraft operations and maintenance.
- Jubail: Known for heavy industry, Jubail’s aviation training investments are linked to industrial transport, logistics, and safety training programs for aviation staff.
- Saudi Arabia: The overall market within the country is driven by its strategic focus on developing a sovereign aviation training ecosystem, government investments in aviation infrastructure, and the growth of both commercial and private aviation sectors.
Competitive Intelligence
The Saudi Arabia Civil Aerospace Simulation and Training Market is characterized by a concentrated competitive landscape with a few key players dominating the sector. Leading companies such as CAE Inc., L3Harris Technologies, and Thales Group are driving innovation through substantial investments in product development and technological advancements. These firms are adopting aggressive partnership strategies with local aerospace entities and government agencies to enhance market penetration and infrastructure development. Notably, alliances with Saudi Airlines and the Saudi Military Industries Corporation bolster local capabilities and foster tailored training solutions aligned with national safety and efficiency standards.
Acquisitions and strategic alliances are prevalent, aiming to expand regional presence and diversify service offerings, particularly in key urban hubs like Riyadh and Jeddah. Companies are intensively investing in R&D to develop high-fidelity simulators that meet evolving regulatory requirements and technological trends. Differentiation in the market is increasingly driven by a focus on digital transformation, including integration of virtual reality and AI-based training modules, which support enhanced training outcomes and operational efficiency in the Saudi context.
Leading Company Profiles
The competitive landscape in Saudi Arabia’s civil aerospace simulation and training market is characterized by a blend of established global players and regional specialists, each vying to capture market share through technological innovations, strategic alliances, and customized solutions tailored to local requirements.
- CAE Inc.
- L3Harris Technologies
- Civil Aviation & Training Solutions (CATS)
- Bombardier Inc.
- Ifly Simulator Solutions
- RSI Simulators
- Schemaplastic
- Precision Flight Training
- Indra Sistemas
- Thales Group
CAE Inc.
CAE offers comprehensive simulation solutions for civil and military aviation, emphasizing high-fidelity aircraft simulators and digital training environments, with strategic focus on expanding its presence in Saudi Arabia through collaborations and localized facilities.
L3Harris Technologies
L3Harris specializes in pilot training systems featuring cutting-edge virtual reality simulators, enhancing training realism. Its strategic priorities include technological innovation and establishing regional partnerships to serve Saudi clients better.
Civil Aviation & Training Solutions (CATS)
CATS provides tailored aerospace training programs, including simulator maintenance and operation, complementing its simulation hardware with integrated training services designed to meet Saudi Arabia’s safety standards and regulatory protocols.
Bombardier Inc.
Known for its advanced business jet simulators, Bombardier focuses on providing immersive training solutions that enhance pilot proficiency, aiming to extend its footprint in Saudi Arabia through local partnerships and new product offerings.
Ifly Simulator Solutions
Specializing in cost-effective, modular simulator systems, Ifly prioritizes deployment agility and technological adaptability, aligning with Saudi Arabia’s expanding civil aviation sector and government-led training modernization efforts.
RSI Simulators
RSI provides customized simulator platforms for regional training academies, emphasizing scalable solutions and integration with digital training databases, intended to support Saudi Arabia’s evolving regulatory and operational standards.
Schemaplastic
Schemaplastic develops innovative visualization and simulation components, focusing on enhancing training device realism and operational efficiency in Saudi Arabia’s civil aerospace training landscape.
Precision Flight Training
This company offers comprehensive flight training solutions integrating advanced simulators and e-learning modules, aimed at supporting the skill enhancement of Saudi Arabia’s aviation workforce.
Indra Sistemas
Indra specializes in simulation and control systems with an emphasis on modern, scalable solutions for civil pilot training, targeting strategic partnerships to tap into the Saudi Arabian market’s growth potential.
Thales Group
Thales offers state-of-the-art pilot training simulators and digital training ecosystems, with a strategic focus on delivering tailored solutions that meet Saudi Arabia’s safety, regulatory, and technological requirements.
Strategic Business Developments

- October 2026 – CAE Inc. – Launch of new civil aircraft simulator training center in Riyadh – Enhanced regional training capacity and reinforced CAE’s leadership in the Middle East
- November 2026 – L3Harris Technologies – Partnership with Saudi aviation authorities for simulator integration – Strengthened local technical capabilities and accelerated adoption of digital training solutions
- January 2027 – Civil Aviation & Training Solutions (CATS) – Deployment of immersive VR pilot training modules at key Saudi airports – Improved training realism and pilot preparedness
- March 2027 – Thales Group – Acquisition of regional training service provider to extend market reach – Increased service offerings and regional market penetration
- May 2027 – Bombardier Inc. – Opening of a dedicated training academy in Jeddah – Facilitating localized training and supportive infrastructure for fleet operators
Frequently Asked Questions
What is the Saudi Arabia Civil Aerospace Simulation and Training Market?
The Saudi Arabia Civil Aerospace Simulation and Training Market involves the development, deployment, and utilization of high-fidelity simulation systems and training programs to enhance pilot proficiency, safety, and operational efficiency within the country's civil aviation sector. It encompasses aircraft simulators, virtual reality training modules, and maintenance training tools tailored to Saudi Arabia's evolving aviation needs.
What is the current market size of Saudi Arabia Civil Aerospace Simulation and Training Market?
As of 2026, the market is valued at approximately USD 1.2 Billion, driven by expanding civil aviation activities, government investments, and modernization initiatives aimed at increasing safety standards and operational capacity in Saudi Arabia’s burgeoning aviation industry.
What factors are driving the Saudi Arabia Civil Aerospace Simulation and Training Market?
Growth is fueled by increasing aircraft fleet sizes, regulatory mandates for enhanced pilot training, a strategic focus on aviation safety, substantial government investments, and private sector participation. Technological advancements in simulation enables more effective, cost-efficient training solutions for civil aviation personnel.
Which Saudi city leads the Saudi Arabia Civil Aerospace Simulation and Training Market?
Riyadh emerges as the leading city, owing to its status as the administrative and commercial hub, with the presence of major aviation training centers and proximity to key airports, bolstering demand for simulation and training services across the region.
Which segment is expected to grow the fastest?
The virtual reality and augmented reality-based simulation segment is projected to experience the fastest growth, due to technological innovations, improved training effectiveness, reduced costs, and rising acceptance among airlines and training institutions.
Who are the leading companies operating in the Saudi Arabia Civil Aerospace Simulation and Training Market?
Key players include CAE Inc., L3 Harris Technologies, Honeywell Aerospace, Boeing, and Airbus, all of which deliver advanced simulation systems and comprehensive training solutions tailored to Saudi Arabia’s civil aviation demands.
Analyst Perspective
The long-term outlook for the Saudi Arabia Civil Aerospace Simulation and Training Market remains highly optimistic, driven by government investments and a strategic shift towards localized pilot training capacities to reduce reliance on external providers. Commercial opportunities abound in establishing specialized training centers in key cities like Riyadh and Dhahran, capitalizing on rising airline traffic and an expanding civil aviation sector. Technological evolution in simulation systems, integrating artificial intelligence and augmented reality, will be crucial for enhancing training fidelity and operational efficiency, attracting both domestic and international players. Investment priorities should focus on infrastructure modernization and fostering public-private partnerships to accelerate market growth. Competitive intensity is expected to rise as global simulation firms enter the Saudi market, incentivized by supportive regulation and high demand. City-level growth potential is significant; Riyadh, as the capital, offers expansive opportunities in ultra-modern training facilities, while Dammam’s proximity to oil hubs may foster niche training niches linked to aviation servicing sectors. Strategic positioning will require continuous innovation, government support, and a focus on technological excellence to maintain Saudi Arabia's competitive edge.
