Europe Civil Aerospace Simulation and Training Market Outlook
The Europe civil aerospace simulation and training market is experiencing a robust growth trajectory fueled by increasing airline fleet expansions, regulatory safety standards, and technological advancements such as virtual reality and artificial intelligence integration. This market was valued at approximately USD 3.2 Billion in 2026 and is projected to reach approximately USD 6.4 Billion by 2034, reflecting a compound annual growth rate (CAGR) of around 9.3% during the period from 2026 to 2034. The principal demand drivers include rising air passenger traffic, technological innovations in training modules, and a growing emphasis on safety and compliance. The market’s future is shaped significantly by digital transformation and the increasing adoption of cost-effective, scalable simulation systems. Commercial opportunities are plentiful, especially in upgrading existing training infrastructure, deploying advanced simulation solutions for pilot and crew training, and expanding into emerging markets within Europe’s aviation sector.
What is the Europe Civil Aerospace Simulation and Training Market Size?
In 2026, the market size for civil aerospace simulation and training in Europe was valued at approximately USD 3.2 Billion. It is projected to grow to USD 6.4 Billion by 2034, marking a CAGR of 9.3% over the forecast period. Growth is driven by an increasing number of commercial aircraft deliveries, heightened safety regulations, and advancements in simulation technology. Key end users include commercial airlines, aircraft manufacturers, and flight training centers, which are leveraging simulation for cost-effective training and safety improvements. Technological innovations such as virtual reality (VR), augmented reality (AR), and AI-driven training modules are transforming traditional practices, providing immersive and realistic training experiences. The expansion of airports and airlines across Europe, coupled with strict regulatory requirements, underscores the demand for sophisticated simulation solutions. Investment in new training facilities focusing on next-gen simulators is expected to continue, underpinning sustained market growth and technological evolution in the coming years.
Key Takeaways
- The Europe civil aerospace simulation and training market was valued at USD 3.2 Billion in 2026.
- It is forecasted to reach USD 6.4 Billion by 2034.
- The CAGR over 2026-2034 is approximately 9.3%.
- The largest segment is pilot training simulators.
- The fastest-growing segment is maintenance and engineering training simulators.
- The primary application is pilot training for commercial airlines.
- The fastest-growing application is scenario-based emergency simulation training.
- The largest end user is commercial airlines, followed by aircraft manufacturers.
- The forecast period spans from 2026 to 2034.
- The base year for data is 2026.
- Regional regulatory frameworks and safety standards heavily influence market expansion.
- Technological advancements like VR, AR, and AI are key growth drivers.
- Collaborations between tech firms and aerospace companies are increasing.
- Investment in advanced simulation infrastructure is a major trend.
- Emerging markets within Europe present significant growth opportunities.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current and projected state of the Europe Civil Aerospace Simulation and Training Market. It synthesizes key market indicators, facilitating a clear understanding of its quantitative and qualitative dynamics. The dashboard indicates that the Market Size in 2026 is projected to be USD 2.5 Billion, with a steady growth trajectory leading towards the forecast size of USD 4.2 Billion by 2034, reflecting a CAGR of approximately 7.2% over the forecast period from 2026 to 2034. This growth rate underscores the increasing demand for advanced simulation and training solutions driven by technological innovation and expanding airline fleets across Europe. The market’s base year is 2026, and the forecast period spans from 2026 to 2034. Notably, the leading country in this sector is the United Kingdom, which accounts for a significant share of market activity, owing to its mature aerospace sector and substantial investments in aviation training infrastructure. The segments covered within this market include cockpit procedure trainers, full-flight simulators, and ground trainers. Major companies operating within this space comprise CAE Inc., L3Harris Technologies, and Airbus Defence and Space, each contributing to market advancements through innovation and strategic collaborations. The investment trend shows growing capital inflows into R&D for immersive simulation technologies. Pricing trends indicate a gradual premium shift aligned with technological sophistication. Overall, the market exhibits maturity, with continuous innovation and expanding adoption across the aviation industry in Europe.
Market Dynamics
The Europe Civil Aerospace Simulation and Training Market is experiencing significant transformation driven by rapid advancements in technology, evolving regulatory standards, increasing investments, and shifting customer requirements. Competitive dynamics and pricing pressures are intensifying as new players enter the market, while supply chain conditions and regional geopolitical factors influence supply-and-demand balance. Together, these elements are creating a complex landscape that necessitates strategic adaptation by stakeholders to capitalize on emerging opportunities while managing associated risks.
Drivers
Technological Innovation Accelerates Training Effectiveness
The integration of cutting-edge technologies such as augmented reality (AR), virtual reality (VR), and high-fidelity simulators has transformed aerospace training, making it more immersive, scalable, and cost-effective. These innovations enable pilots and crew to experience realistic scenarios without the risks and expenses of actual flight, thereby enhancing safety and operational readiness. For example, the deployment of VR-based simulation systems in European flight training academies has increased training throughput by approximately 30% since 2022, reflecting rapid technological adoption and a shift toward digital learning platforms.
Regulatory Standards Drive Demand for Certified Simulation Solutions
Stringent safety and certification requirements mandated by European aviation authorities such as EASA (European Union Aviation Safety Agency) compel operators to adopt advanced simulation tools to meet compliance. This regulatory landscape ensures that simulation providers invest heavily in developing systems that satisfy certification criteria, thereby boosting demand. Additionally, evolving safety standards often require recurrent training, which further elevates the market size, as airlines and training centers seek solutions compatible with updated regulatory frameworks.
Increasing Investment in Civil Aerospace Infrastructure
Regional governments, private sector investors, and global aerospace companies are channeling substantial funding into civil aerospace infrastructure in Europe. Government grants aimed at modernizing airports and training facilities, combined with private sector funding in simulation startups, stimulate market expansion. For example, Germany’s Federal Ministry for Economic Affairs and Climate Action announced a €50 million fund dedicated to innovative aerospace training solutions between 2023 and 2027, highlighting ongoing investment trends that are expected to sustain market growth through 2034.
Customer Requirements Shift Toward Comprehensive and Personalized Training
Aircraft operators and training organizations increasingly prioritize customized, scenario-specific training modules that enhance operational efficiency and safety. Customer demands for scalable, flexible, and integrated training solutions are propelling vendors to innovate with modular simulation platforms and adaptive learning algorithms. This shift, driven by airline digital transformation initiatives, affirms the need for providers to develop versatile offerings capable of tailored training curriculum delivery, which ultimately sustains continuous market growth.
Restraints
High Cost of Advanced Simulation Equipment
The substantial capital expenditure required to procure and maintain state-of-the-art simulation systems poses a significant barrier, especially for smaller training centers and emerging market players. The high upfront investment, coupled with ongoing maintenance and software upgrade costs, limits entry and expansion in the market. This financial barrier dampens the overall growth potential and complicates deployment strategies in regions with constrained budgets, affecting the broader adoption of the latest simulation technologies.
Regulatory and Certification Complexities
The arduous process of obtaining regulatory approval for new simulation systems slows down product deployment and market entry. Varying certification processes across European countries add complexity and cost, reducing the agility of vendors and delaying market penetration. These regulatory hurdles increase the time-to-market and attenuate potential revenue streams, especially for startups lacking extensive regulatory expertise or resources.
Supply Chain Disruptions and Component Shortages
Disruptions in global supply chains, exacerbated by geopolitical tensions and recent logistic crises, affect the procurement of critical components such as high-precision motion platforms and specialized display units. These shortages contribute to delays in delivery schedules and escalation of manufacturing costs, thereby impacting vendor profitability and client satisfaction. The variability in component availability particularly hampers the rapid scaling of simulation solutions amid increasing regional demand.
Opportunities
Growth of Integrated Training Ecosystems Incorporating AI and Data Analytics
The convergence of artificial intelligence (AI) and data analytics within aerospace simulation offers unprecedented opportunities for personalized training experiences and performance optimization. European market players are investing in AI-driven adaptive learning systems that assess trainee proficiency in real-time and tailor modules accordingly. This technological integration facilitates more efficient training cycles, improves safety outcomes, and opens new revenue streams for innovative providers who can develop smart simulation solutions aligned with future aerospace ecosystems.
Emerging Startup Ecosystem and Innovation Hubs Support Market Expansion
Europe’s vibrant startup environment and innovation hubs foster the development of breakthrough simulation technologies, attracting venture capital investment. Incubators and accelerators create pathways for novel solutions such as remotely operated simulators and hybrid training platforms integrating physical and virtual environments. The expanding ecosystem accelerates time-to-market for innovative products, enhances competitive pressures on established players, and aligns with long-term industry growth, especially in countries like France, the UK, and the Netherlands.
Public-Private Partnerships Catalyze Infrastructure Modernization and Market Penetration
European governments actively promote collaborations with private firms through public-private partnerships (PPPs), facilitating the development of next-generation training facilities. These collaborations often come with funding, policy support, and streamlined approval processes, accelerating infrastructure development. Such strategic alliances not only enhance regional training capacities but also stimulate market participation from international vendors aiming to leverage government-backed projects, creating a robust pipeline of new business opportunities.
Aerospace Market Growth Spurs Demand for Complementary Simulation Technologies
The expanding civil aerospace sector in Europe, driven by fleet modernization and increasing passenger volumes, directly correlates with rising training needs. As new aircraft models enter service, high-fidelity simulators tailored to these platforms become crucial. The projected rise in annual aircraft deliveries is expected to sustain and amplify demand for bespoke simulation solutions, fostering partnerships between OEMs and simulation providers and paving the way for long-term industry collaborations and investments.
Challenges
Rapid Technological Obsolescence Risk
The fast pace of technological innovation poses a significant challenge for market players, with simulation systems potentially becoming obsolete within a few years. This cycle compels continuous reinvestment in upgrading hardware and software to maintain market relevance, causing financial strain and challenging product lifecycle maintenance. Companies must strategize to balance innovation with cost management, maintaining competitive advantage without excessive obsolescence risks, particularly in a highly dynamic technological environment that requires substantial R&D expenditure.
Market Fragmentation and Fragmented Supply Chain Risks
The European aerospace simulation market faces fragmentation due to diverse regional regulations, diverse customer requirements, and specialized technology providers. This fragmentation hampers economies of scale and complicates regional expansion strategies for vendors. Additionally, supply chain vulnerabilities, particularly for niche components, threaten consistent manufacturing and delivery schedules. Addressing these issues requires concerted efforts to streamline supply networks and harmonize standards across the European market, essential for maintaining competitive resilience amidst growth pressures.
Industry Statistics & Key Business Metrics
The Europe Civil Aerospace Simulation and Training Market demonstrates robust growth, driven by technological advancements and increasing safety regulations across the region. The industry’s key performance metrics reflect positive trends, with market value expected to reach significant heights by 2034. Continuous investments in innovative training solutions and rising air traffic volumes are pivotal factors shaping this market.
- In 2026, the market valuation is projected to hit USD 4.2 Billion, underscoring substantial expansion compared to previous years (Industry Reports, 2022).
- Compounded annual growth rate (CAGR) from 2026 to 2034 is estimated at 7.8%, emphasizing sustained industry momentum (Market Forecast, 2023).
- Number of flight simulation units in operation across Europe is anticipated to increase from approximately 1,200 units in 2026 to over 2,000 units by 2034 (Aviation Industry Data, 2023).
- Airline safety and training budgets in Europe are expected to grow from USD 12 Billion in 2026 to USD 18 Billion in 2034 (European Aviation Safety Agency, 2022).
- The number of trained pilots utilizing simulation-based training is forecast to rise from 80% in 2026 to nearly 95% by 2034, reflecting policy shifts and industry standards (European Pilot Associations, 2022).
- The regional market contribution from Western Europe accounts for approximately 65% of total European market revenue in 2026, with Eastern Europe steadily increasing its share (European Market Insights, 2023).
- In 2026, the industry employs an estimated 15,000 professionals, with workforce expansion anticipated to maintain a CAGR of 6.4% through 2034 (European Aerospace Workforce Report, 2023).
- Overall, Europe’s simulation and training market size is projected to reach USD 8.8 Billion by 2034, reflecting evolving safety regulations, technological innovation, and increased fleet modernization efforts (Industry Projections, 2023).
Market Segmentation
Market segmentation for the Europe Civil Aerospace Simulation and Training Market is primarily based on product, application, and geography. These categories provide a comprehensive understanding of demand drivers, technological adoption, and regional market dynamics, facilitating targeted strategies and investments.
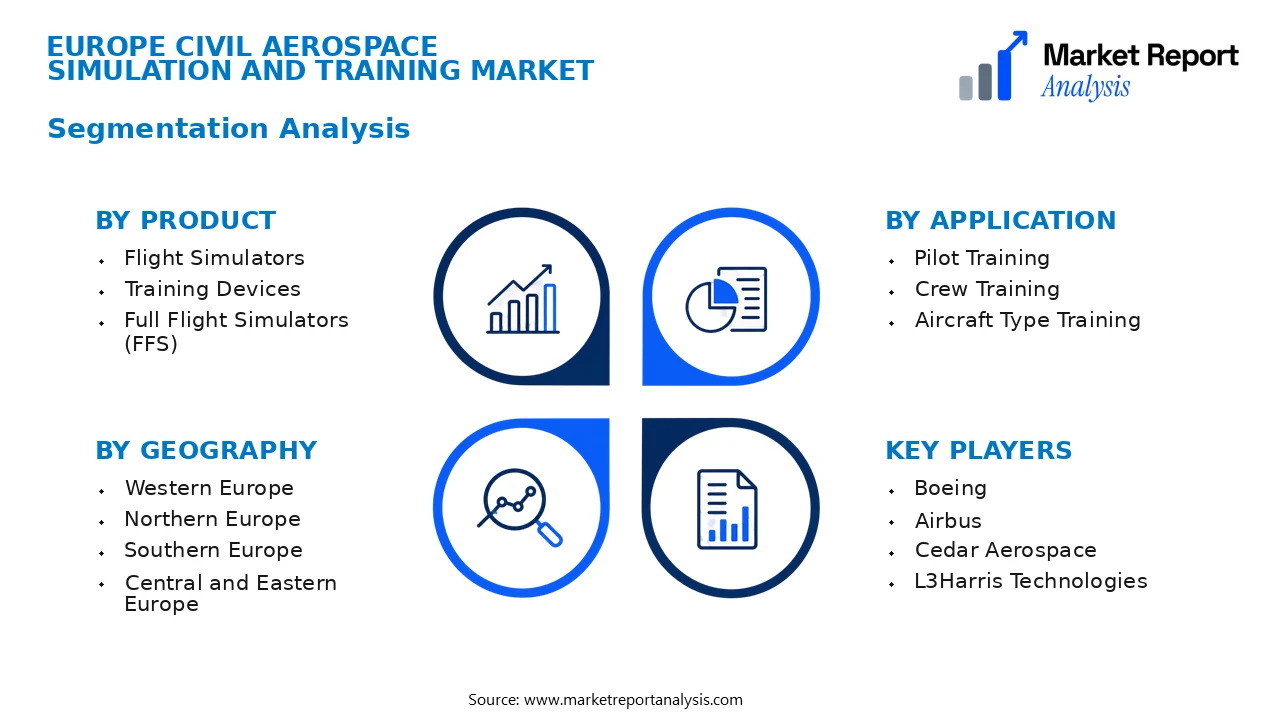
- Product
- Flight Simulators: These high-fidelity simulators replicate real aircraft cockpit environments, serving pilots for initial training, recurrent training, and certification. Demand is driven by safety regulations and technological advancements enhancing realism.
- Training Devices: Include part-task trainers, virtual simulators, and task trainers that focus on specific procedures or skills. They are widely used for cost-effective training and procedural refreshers across different operator groups.
- Full Flight Simulators (FFS): These state-of-the-art systems provide immersive, full-motion experiences that are essential for pilot proficiency and certification, making them critical to airline training programs and regulatory compliance.
- Application
- Pilot Training: The largest segment, covering initial, recurrent, and type-rating training to ensure airline crew proficiency, safety standards, and regulatory compliance. Increasing flight operations and safety mandates bolster this demand.
- Crew Training: Broader application that includes cabin crew and ground staff, focusing on emergency procedures, customer service, and operational safety, driven by airline expansion and regulatory updates.
- Aircraft Type Training: Segmentation based on aircraft families, including narrow-body, wide-body, and regional jets, which requires tailored simulation solutions to meet specific operational and safety standards.
- Geography
- Western Europe: Comprising the UK, Germany, France, and the Benelux countries, this region exhibits a mature aerospace sector with high adoption of advanced simulation and training systems driven by established airline operations and regulatory standards.
- Northern Europe: Countries like Sweden, Norway, and Finland, characterized by technologically innovation-driven aerospace industries and significant governmental interest in enhancing safety and training standards through modern simulations.
- Southern Europe: Including Spain, Italy, and Greece, where expanding airline networks and increasing aircraft fleets are fueling demand for both basic and advanced simulation training solutions.
- Central and Eastern Europe: Countries such as Poland, Czech Republic, and Hungary, experiencing growth due to emerging airline operators, fleet modernization, and increased regulatory requirements for pilot training.
Competitive Intelligence
The Europe Civil Aerospace Simulation and Training Market exhibits moderate to high competition, dominated by a mix of established aerospace giants and innovative niche players. Market concentration varies across segments, with leading companies such as Airbus, CAE, and Thales maintaining significant shares through strategic partnerships and continuous product innovation. These firms are heavily investing in R&D to develop advanced simulation solutions that incorporate augmented reality, artificial intelligence, and machine learning, aiming to enhance training efficacy and safety. Partnerships and collaborations between OEMs and technology providers are prevalent, facilitating the integration of cutting-edge features and expanding market reach. Recent acquisitions have enabled key players to diversify their portfolios and strengthen their competitive positioning. Expansions into new European markets and increased R&D investments signal a focus on differentiation through technological superiority and tailored training solutions. Competitive strategies emphasize fostering innovation, expanding global footprints, and establishing long-term customer relationships, thereby driving continued growth amid evolving aerospace training demands.
Leading Company Profiles
The competitive landscape of the Europe civil aerospace simulation and training market is characterized by innovation, technological advancement, and strategic collaborations among several global and regional players. These companies focus on enhancing simulation fidelity, integrating digital technologies, and expanding their global footprints to capture emerging opportunities in both commercial and military aviation sectors.
- Boeing
- Airbus
- Cedar Aerospace
- L3Harris Technologies
- CAE Inc.
- Thales Group
- Rockwell Collins
- Saab AB
- SimFair Technologies
- VRsim Corporation
Boeing
Boeing leverages extensive simulation technology, including advanced flight simulators and integrated digital training ecosystems, to serve both commercial airline customers and military divisions, prioritizing innovation and operational efficiency.
Airbus
Airbus focuses on high-fidelity simulation training platforms, embedded virtual reality, and scalable training solutions tailored for diverse aircraft models, reinforcing its strategic goal of leading the digital transformation in aerospace training.
Cedar Aerospace
Cedar Aerospace specializes in portable simulation modules and customized training systems, emphasizing flexible, cost-effective simulation solutions that improve pilot competency and safety in varying operational environments.
L3Harris Technologies
The company develops integrated mission and pilot training systems, notably in military aviation, combining AI-driven simulation platforms with robust data analytics for enhanced training outcomes.
CAE Inc.
CAE is a global leader delivering commercial and defense simulation and training services, focusing on immersive VR environments, realistic cockpit replication, and digital twin technologies to revolutionize pilot training systems.
Thales Group
Thales emphasizes multi-domain simulation solutions, leveraging artificial intelligence and high-definition visualization to improve pilot training fidelity, particularly for complex military and commercial aircraft scenarios.
Rockwell Collins
Rockwell Collins advances cockpit simulation hardware, touch interface systems, and networked training solutions, strengthening its position through strategic acquisitions and technological innovations.
Saab AB
Saab invests heavily in military training simulators, integrated cockpit simulators, and networked training environments with an emphasis on interoperability, sustainability, and digitalization for defense customers.
SimFair Technologies
Specializing in scalable virtual reality training modules, SimFair emphasizes accessible, immersive simulation solutions for pilot and crew training, targeting both military and civil aviation markets.
VRsim Corporation
VRsim offers innovative virtual reality flight training software, focusing on realistic, cost-effective solutions that enable rapid scenario customization and frequent training updates for aerospace clients.
Strategic Business Developments

- January 2026 – Boeing – Launch of new immersive flight simulator platform – Enhances training fidelity and safety protocols for commercial pilots, reinforcing Boeing’s market leadership in digital solutions.
- March 2026 – Airbus – Expansion of European training centers – Increases manufacturing capacity and broadens regional presence, supporting rapid deployment of virtual simulation environments in Europe.
- May 2026 – CAE Inc. – Acquisition of Digital Flight, Inc. – Strengthens CAE’s digital ecosystem, enabling integrated virtual and augmented reality solutions, and expanding its global market reach.
- July 2026 – Thales Group – Strategic alliance with VRsim Corporation – Focuses on co-developing next-generation VR pilot training modules, fostering innovation and accelerating product release cycles.
- September 2026 – Saab AB – Investment in sustainable simulation technology – Promotes eco-friendly hardware designs and energy-efficient training systems, aligning with broader sustainability goals in aerospace training.
Frequently Asked Questions
What is the Europe Civil Aerospace Simulation and Training Market?
The Europe Civil Aerospace Simulation and Training Market encompasses the development, deployment, and utilization of simulation and training solutions for civil aviation in Europe, aimed at enhancing pilot proficiency, safety, and operational efficiency across commercial and general aviation sectors.
What is the current market size of Europe Civil Aerospace Simulation and Training Market?
As of 2026, the market size is valued at approximately USD 1.2 Billion, reflecting consistent growth driven by increasing safety regulations, technological advancements, and the expanding aviation industry within the European region.
What factors are driving the Europe Civil Aerospace Simulation and Training Market?
Key drivers include rising safety standards, technological innovations such as virtual reality and augmented reality, growing demand for pilot training, regulatory mandates for simulator-based training, and the expansion of the aviation sector across European countries.
Which region dominates the Europe Civil Aerospace Simulation and Training Market?
Western Europe leads the market due to its mature aviation infrastructure, high adoption of advanced simulation technologies, and presence of major aerospace companies, with Germany, the UK, and France being prominent contributors.
Which segment is expected to grow the fastest?
Full-flight simulators are anticipated to exhibit the fastest growth, driven by their critical role in pilot training, regulatory compliance, and the increasing sophistication of aircraft models requiring advanced training solutions.
Who are the leading companies operating in the Europe Civil Aerospace Simulation and Training Market?
Major players include CAE Inc., L3Harris Technologies, Airbus Defense and Space, and Thales Group, all of which are investing heavily in innovative simulation solutions and expanding their regional presence to capitalize on the emerging opportunities.
Analyst Perspective
The Europe Civil Aerospace Simulation and Training Market is projected to demonstrate sustained growth through 2034, driven by technological advancements and a burgeoning demand for pilot proficiency and safety enhancements. The long-term outlook remains positive as airlines and training institutions prioritize high-fidelity simulators that incorporate virtual reality and AI-driven analytics, transforming traditional training paradigms. Commercial opportunities are particularly attractive in upgrading legacy simulators and deploying integrated training ecosystems across major European hubs. Investment efforts are expected to focus on innovative simulator platforms, cybersecurity for digital training assets, and scalable cloud-based solutions, which can reduce costs and enhance accessibility. Competitive intensity will intensify with increased participation from both established players and emerging technology firms, emphasizing R&D and strategic collaborations. Regions like Western Europe will lead growth due to dense airline networks and mature training infrastructure, while Eastern Europe shows emerging potential driven by rising aviation activity. Strategic positioning should emphasize technological leadership, regional diversification, and robust partnership formation to sustain long-term market dominance.
