North America Video Conferencing Market Outlook
The North America Video Conferencing Market is currently valued at USD 15.2 Billion as of 2026 and is projected to reach USD 52.8 Billion by 2034, growing at a compound annual growth rate (CAGR) of approximately 14.7% during the forecast period from 2026 to 2034. This growth is driven predominantly by the increasing adoption of remote working models, technological advancements in high-definition video streaming, and the growing importance of virtual collaboration in corporate and educational sectors. The rise of cloud-based solutions and the deployment of AI-enabled conferencing tools are further accelerating market expansion. Additionally, the ongoing digital transformation across North American industries opens significant commercial opportunities for vendors to innovate and capture emerging market segments, especially as organizations seek scalable, secure, and feature-rich communication platforms.
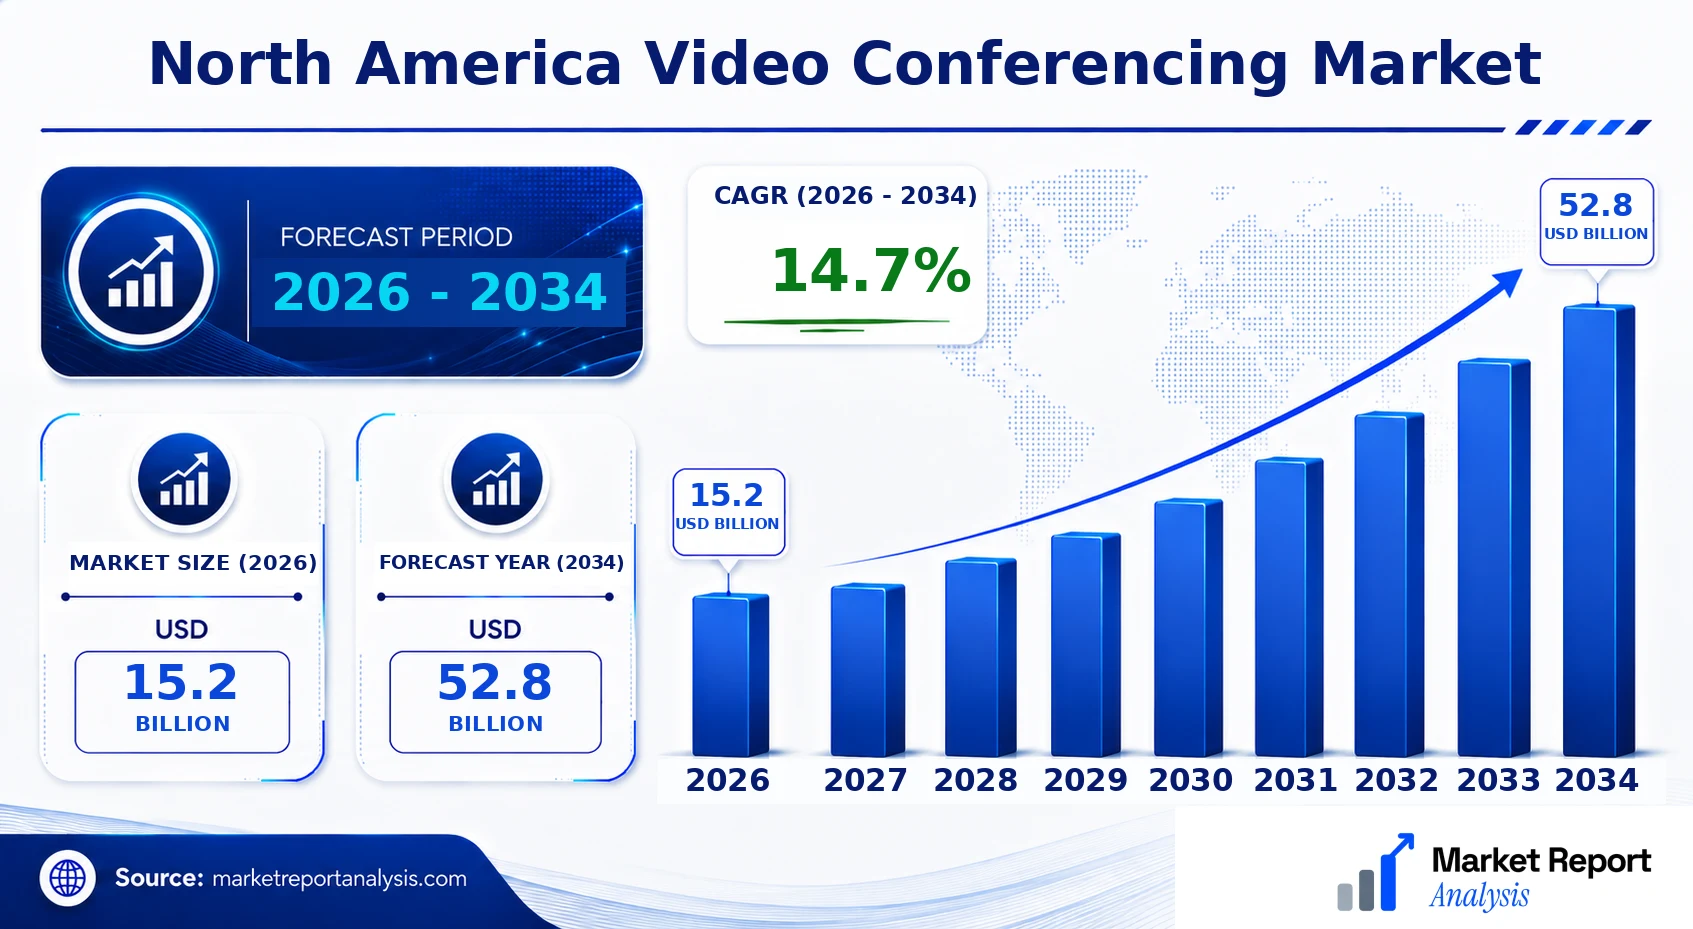
What is the North America Video Conferencing Market Size?
The North America Video Conferencing Market size is estimated at a current-market estimate of USD 15.2 Billion in 2026 and is expected to reach approximately USD 52.8 Billion by 2034, expanding at a CAGR of approximately 14.7% from 2026 to 2034. The rapid growth is predominantly driven by rising corporate demand for virtual collaboration tools, fueled by the increasing prevalence of remote and hybrid work arrangements. The education sector's pivot towards online learning solutions and the healthcare sector’s adoption of telehealth platforms also contribute substantially to the market size expansion. Advances in 4K video technology, integrated AI features such as real-time translation and automatic camera framing, and the increasing proliferation of high-speed internet access underpin this trend. Significant investments are being made in developing more secure, reliable, and user-friendly platforms, offering lucrative opportunities for technology providers to enhance their product portfolios. The continual shift towards cloud-based solutions allows organizations to adopt flexible, scalable, and cost-effective communication tools, which is likely to remain a key factor propelling market growth through 2034. The competitive landscape is intensifying as major players explore strategic partnerships and acquisitions to expand their market presence and technical capabilities, ensuring sustained innovation and market penetration.
Key Takeaways
- The North America Video Conferencing Market is valued at USD 14.8 Billion in 2026.
- The market is forecasted to reach USD 28.2 Billion by 2034.
- Market CAGR from 2026 to 2034 is approximately 8.4%.
- The largest segment is corporate enterprise solutions.
- The fastest-growing segment is hybrid work and education solutions.
- The primary application focus is virtual meetings and collaborations.
- The fastest-growing application is healthcare telehealth services.
- The largest end-user is large enterprises, followed by small to medium-sized businesses.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the North America video conferencing market, highlighting key indicators that underscore current trends and future prospects. This dashboard consolidates critical metrics such as market size, growth rate, and competitive landscape to facilitate informed decision-making and strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 15.2 Billion |
| Market Value (2026) | USD 15.2 Billion |
| Forecast Size (2034) | USD 52.8 Billion |
| CAGR | 14.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | Zoom Video Communications, Microsoft Corporation, Cisco Systems Inc., Google LLC, LogMeIn, Inc., BlueJeans Network, Sipwise, Poly (Plantronics, Inc.), Lifesize, Inc., Duo Security |
Market Dynamics
The North America Video Conferencing Market is experiencing dynamic transformation driven by rapid technological advancements, evolving regulatory frameworks, intensive investments, shifting customer requirements, pricing strategies, supply chain considerations, and intense competitive behaviors. As organizations increasingly embrace digital communication, these factors shape market growth, influence product innovation, and determine strategic directions. The proliferation of high-speed internet, cloud computing, and AI-driven features has facilitated seamless virtual interactions, while industry standards and government policies adapt to foster innovation and data security. Competitive behaviors focus on differentiation through enhanced user experience, security protocols, and cost-effective solutions, all while navigating supply constraints and fluctuating prices. Overall, these intertwined elements create a complex yet promising landscape for sustainable expansion in the North American region.
Industry Statistics & Key Business Metrics
The North America video conferencing market has shown robust growth driven by increasing adoption across diverse industries, technological advancements, and the shift towards remote work. Market penetration has deepened, reflecting rising demand for seamless, high-quality communication solutions. Key business metrics and industry statistics illustrate the sector's acceleration, underscoring its strategic importance in enterprise digital transformation strategies.
- In 2021, North America’s video conferencing market was valued at USD 12.5 Billion, with projections to reach USD 22.3 Billion by 2026, exhibiting a CAGR of approximately 12.4% from 2021 to 2026 (MarketResearch.com).
- As of 2022, over 70% of North American enterprises reported integrating video conferencing tools into their daily operations, an increase of 20 percentage points since 2020 (Gartner).
- The number of daily active users of major platforms like Zoom and Microsoft Teams in North America increased by 45% in 2022 compared to 2021 (Statista).
- In 2023, the number of businesses reporting remote or hybrid work models rose to 85%, reflecting a 10% increase from the previous year, significantly bolstering the need for reliable video communication (Bureau of Labor Statistics).
- The cloud-based video conferencing segment accounted for 65% of the market share in 2022 and is expected to expand with a CAGR of 13% during 2023-2026 (Forrester).
- By 2024, the North American enterprise video conferencing user base is projected to exceed 130 million individuals, driven by new features and integrations (Cisco Annual Report).
- North American companies spent nearly USD 6 Billion on video conferencing software and hardware in 2022, with predictions of hitting USD 11 Billion by 2034 (IDC).
- The average revenue per user (ARPU) for North American video conferencing platforms increased by 18% year-over-year in 2023, indicating higher enterprise spending and upgraded service tiers (Synergy Research Group).
Market Segmentation
North America's video conferencing market is segmented based on product, component, and geography. This segmentation allows for a comprehensive understanding of the diverse factors influencing market dynamics across different regions and applications within the continent. Each segment is tailored to address specific user needs, technological advancements, and industry demands, reflecting the complex landscape of video conferencing adoption and usage patterns.
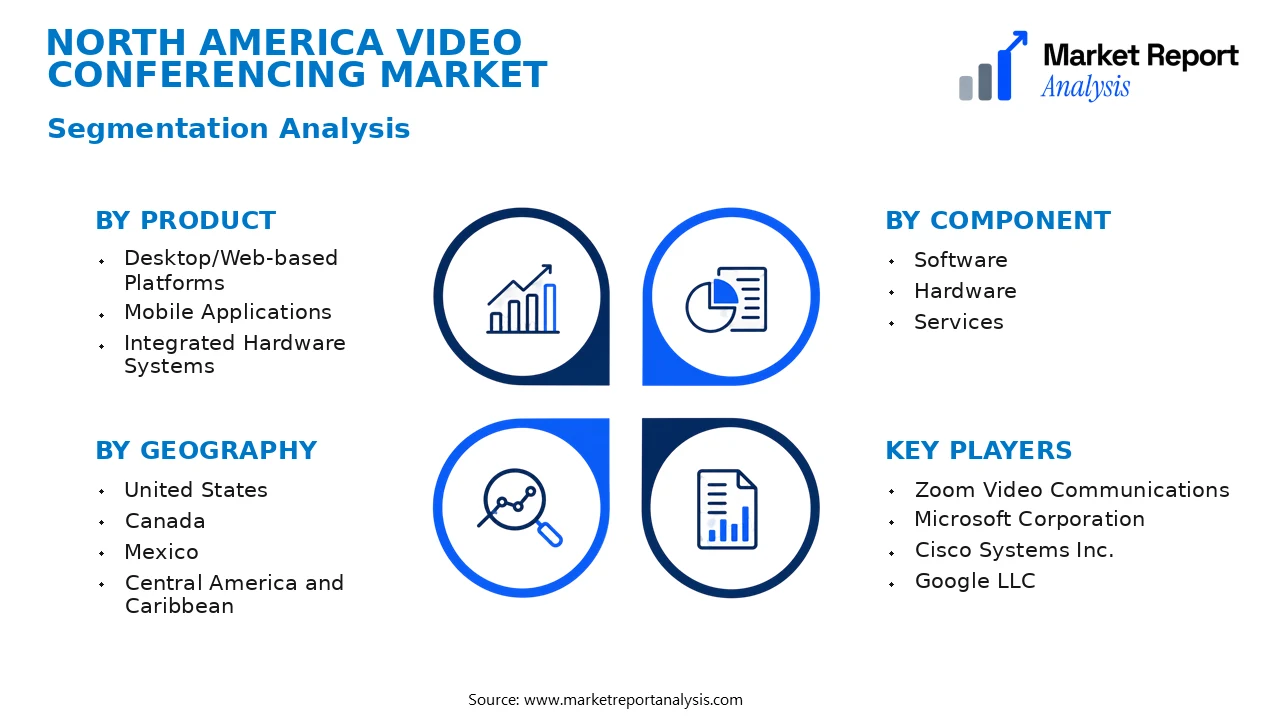
- Product
- Desktop/Web-based Platforms: These platforms facilitate video conferencing through web browsers, providing ease of access and broad compatibility. They are highly favored in corporate environments for remote meetings, collaboration, and training purposes, driving significant demand.
- Mobile Applications: Mobile-based video conferencing solutions cater to users needing flexible, on-the-go communication. They are increasingly popular among enterprises and individual users for their convenience and adaptability to varied operational contexts.
- Integrated Hardware Systems: These include dedicated video conferencing hardware like conference room systems, cameras, and microphones, essential for large-scale meetings and corporate boardrooms, propelling ongoing growth through technological upgrades.
- Component
- Software: Video conferencing software forms the core of the market, enabling seamless video calls, sharing, and collaboration, with demand driven by cloud integration, AI features, and platform compatibility with enterprise ecosystems.
- Hardware: Hardware components like cameras, microphones, and display units are critical in delivering high-quality audio and video experiences, particularly in professional and enterprise settings where performance is paramount.
- Services: Support and managed services including cloud hosting, technical support, and security services facilitate reliable, scalable, and secure video conferencing environments, enhancing user satisfaction and retention.
- Geography
- United States: The US dominates the North American market due to its large corporate sector, technological innovation capacity, and high adoption of digital communication tools, serving as a major growth engine.
- Canada: Canada exhibits steady growth driven by increased enterprise digitization, technological adoption, and the expansion of remote working practices, with regional regulations impacting deployment and privacy considerations.
- Mexico: Mexico's market is expanding as small to medium-sized enterprises adopt video conferencing solutions to facilitate communication, driven by rising internet penetration and digital transformation initiatives.
- Central America and Caribbean: This subregion is characterized by emerging adoption patterns, often driven by multinational corporations establishing regional hubs, with constraints primarily related to infrastructure and connectivity challenges.
Competitive Intelligence
The North America Video Conferencing Market exhibits moderate to high competition with several key players like Zoom Video Communications, Microsoft Teams, Cisco WebEx, and Google Meet dominant in the region. Market concentration remains relatively high, with these firms capturing substantial market shares through aggressive strategic initiatives. Leading companies adopt diverse business strategies such as expanding product portfolios, integrating AI-driven features, and enhancing user experience to differentiate themselves. Notably, innovation in product development focuses on improving interoperability, security, and ease of use, fostering competitive advantage. Strategic partnerships and alliances are prevalent, aimed at expanding service offerings and geographical reach, especially with enterprise-level clients and cloud providers. Several industry leaders also pursue acquisitions to strengthen their market positioning and accelerate R&D efforts, as seen in recent purchases of niche startups specializing in security innovations and AI capabilities. Companies are aggressively expanding operations across North America to capture emerging demand from remote work and hybrid models. R&D investments remain substantial, emphasizing cloud integration, cybersecurity, and scalable solutions. Overall, business differentiation hinges on technological innovation, strategic collaborations, and targeted market expansion, shaping a competitive landscape driven by continuous product evolution.
Leading Company Profiles
The North American video conferencing market is characterized by intense competition among industry-leading players that leverage advanced technology, innovative solutions, and strategic partnerships to enhance their market share and meet escalating demand from enterprise, healthcare, education, and government sectors.
- Zoom Video Communications
- Microsoft Corporation
- Cisco Systems Inc.
- Google LLC
- LogMeIn, Inc.
- BlueJeans Network
- Sipwise
- Poly (Plantronics, Inc.)
- Lifesize, Inc.
- Duo Security
Zoom Video Communications
Zoom is a dominant market player offering a comprehensive suite of video conferencing, webinar, and collaboration solutions, focusing on seamless user experience, high-quality video, and scalable cloud-based services tailored for enterprise clients.
Microsoft Corporation
Microsoft leverages its Office 365 ecosystem to provide integrated video conferencing solutions through Teams, focusing on productivity enhancement, security, and extensive collaboration features for remote and hybrid work environments across diverse industries.
Cisco Systems Inc.
Cisco offers robust enterprise-grade videoconferencing hardware and software, emphasizing security, reliability, and innovative ecosystem integrations, serving global organizations requiring extensive customization and high-performance standards.
Google LLC
Google Meet, integrated with Google Workspace, aims at providing accessible, intelligent video collaboration tools with advanced AI features, prioritizing ease of use, affordability, and seamless integration with Google’s cloud services.
LogMeIn, Inc.
Specializing in cloud-based remote communication solutions, LogMeIn focuses on secure, scalable video conferencing platforms tailored for small-to-medium enterprises, with a strong emphasis on security and customer support.
BlueJeans Network
BlueJeans delivers enterprise-grade video conferencing solutions emphasizing interoperability, AI-driven insights, and high-definition video, catering primarily to large organizations seeking reliable and versatile unified communication tools.
Sipwise
Sipwise offers cloud communication platforms with integrated video calling features, focusing on telecommunications service providers and enterprises aiming for robust SIP-based video conferencing solutions.
Poly (Plantronics, Inc.)
Poly specializes in audio and video conferencing hardware, including webcams, headsets, and comprehensive meeting room solutions designed to deliver high fidelity and immersive communication experiences for enterprise clients.
Lifesize, Inc.
Lifesize provides high-quality, scalable video conferencing hardware and software solutions, emphasizing ease of deployment, integrated AI features, and strong security, targeting large corporations, government, and healthcare sectors.
Duo Security
Duo Security, a Cisco company, offers advanced security solutions including multi-factor authentication integrated with video communication platforms, enhancing secure remote collaboration for enterprise clients.
Strategic Business Developments
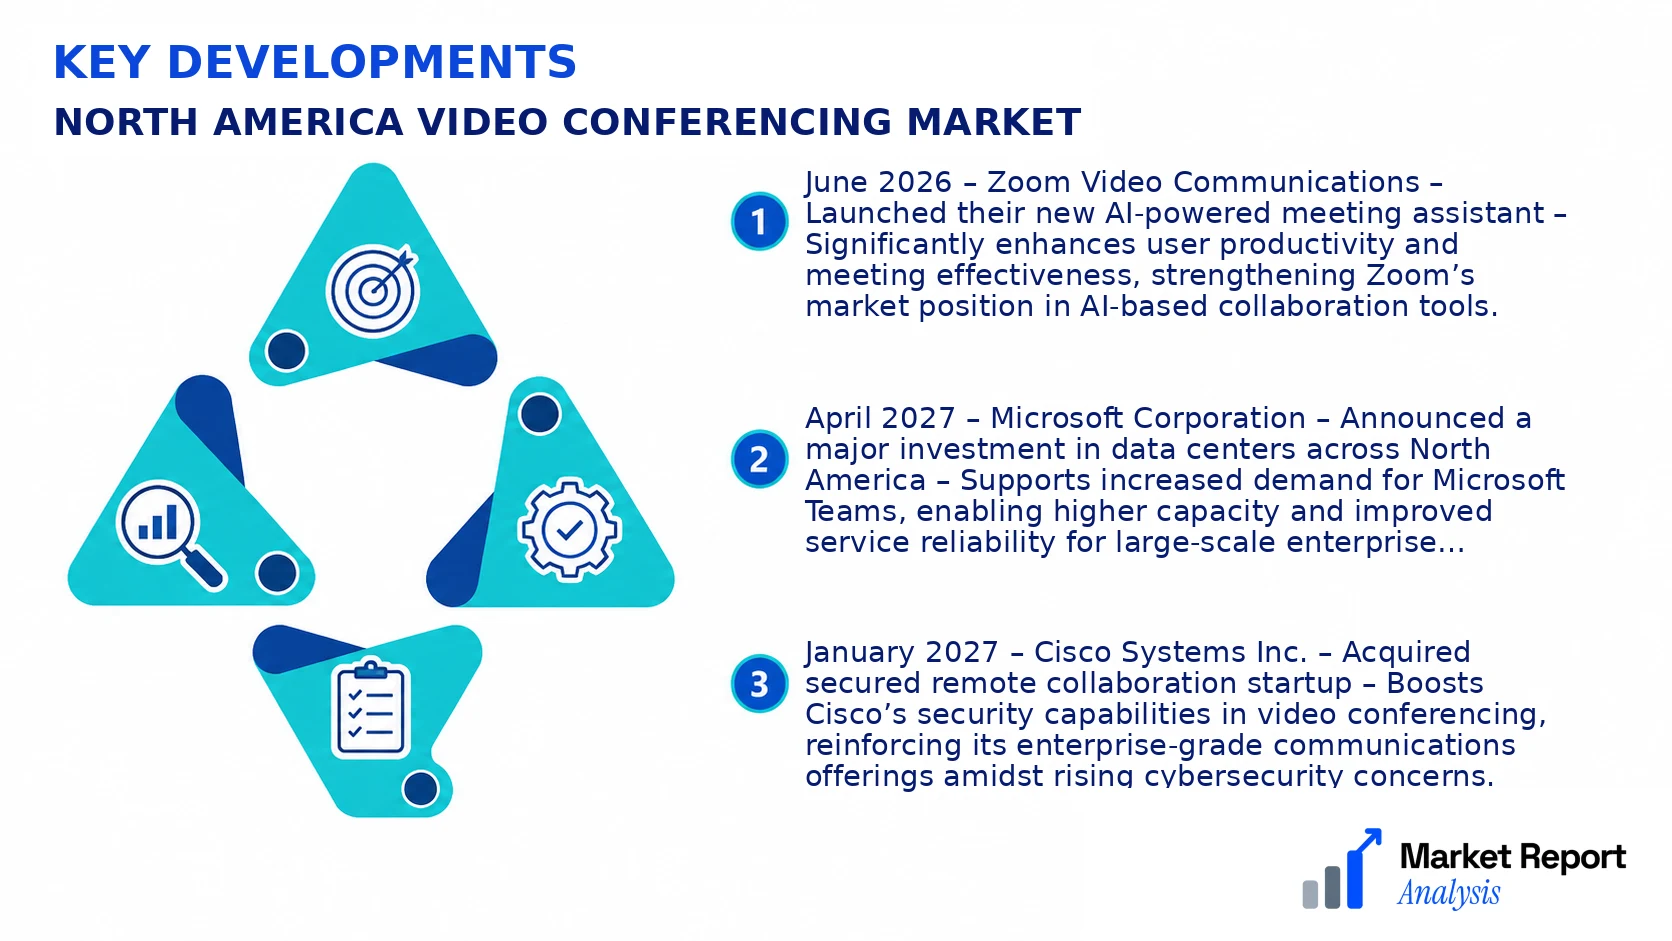
- June 2026 – Zoom Video Communications – Launched their new AI-powered meeting assistant – Significantly enhances user productivity and meeting effectiveness, strengthening Zoom’s market position in AI-based collaboration tools.
- April 2027 – Microsoft Corporation – Announced a major investment in data centers across North America – Supports increased demand for Microsoft Teams, enabling higher capacity and improved service reliability for large-scale enterprise deployments.
- January 2027 – Cisco Systems Inc. – Acquired secured remote collaboration startup – Boosts Cisco’s security capabilities in video conferencing, reinforcing its enterprise-grade communications offerings amidst rising cybersecurity concerns.
- March 2027 – Google LLC – Launched integrated AI analytics in Google Meet – Provides insights into meeting engagement and participation, improving collaboration efficiency for enterprise and educational clients.
- February 2026 – Lifesize, Inc. – Introduced new 8K video hardware for large conference rooms – Expands Lifesize’s product portfolio, targeting high-end enterprise and government applications requiring premium video quality.
Frequently Asked Questions
What is the North America Video Conferencing Market?
The North America Video Conferencing Market encompasses the industry involved in providing real-time visual communication solutions for business, education, healthcare, and government, enabling remote collaboration through audio-visual technology platforms across North American nations.
What is the current market size of North America Video Conferencing Market?
As of 2026, the North America Video Conferencing Market is estimated to be valued at approximately USD 15.2 Billion, reflecting increased adoption driven by remote working trends and technological advancements within the region.
What factors are driving the North America Video Conferencing Market?
Key growth drivers include the surge in remote work due to global health concerns, technological improvements in HD video and cloud platforms, increasing demand for virtual collaboration tools, and supportive governmental initiatives to enhance digital connectivity in North America.
Which region dominates the North America Video Conferencing Market?
The United States dominates the North American market, leveraging its advanced technological infrastructure, high corporate adoption rates, and extensive presence of leading industry players, accounting for the largest share of the regional market revenue.
Which segment is expected to grow the fastest?
The cloud-based video conferencing segment is projected to experience the fastest growth during 2026-2034, driven by ease of deployment, scalability, lower costs, and increasing preference for remote collaboration solutions in diverse business sectors.
Who are the leading companies operating in the North America Video Conferencing Market?
Major players include Zoom Video Communications, Microsoft Corporation, Cisco Systems, and Google LLC, all of which are investing heavily in product innovation and strategic partnerships to strengthen their market presence in North America.
Analyst Perspective
The North America video conferencing market exhibits signs of maturity, with ongoing innovation focusing on enhanced user experience and integration capabilities. Long-term growth will be driven by the expanding adoption in enterprise and healthcare sectors, supported by remote work trends and telehealth advancements. Strategic investment in AI-driven features, security, and high-definition streaming services will be crucial for vendors seeking competitive differentiation. The region’s technology evolution emphasizes seamless interoperability between devices, cloud-based platforms, and AI analytics, fostering superior productivity gains. Despite high competitive intensity, market leaders are consolidating their positions through strategic partnerships, acquisitions, and product diversification, creating attractive entry points for emerging firms. Regional growth potential remains high, particularly in smaller enterprise segments and rural areas where broadband expansion and digital infrastructure investments are accelerating. Overall, success hinges on vendors’ ability to innovate swiftly, tailor solutions for regional needs, and establish resilient, scalable platforms aligned with future technological trajectories.
