Japan Video Conferencing Market Outlook
The Japan Video Conferencing Market has experienced significant growth in recent years, driven by increased demand for remote communication solutions across various sectors. The market was valued at approximately USD 2.5 Billion in 2026 and is projected to reach USD 5 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of around 11.4% during the forecast period from 2026 to 2034. Key demand drivers include the modernization of workplace communication, remote work policies, the rise in digital collaboration tools, and the expansion of cloud-based services. Technological advancements, particularly in high-definition video streaming, AI-powered features, and seamless integration with enterprise applications, are reshaping the landscape. Moreover, Japanese organizations are increasingly investing in secure, scalable, and user-friendly video conferencing platforms to meet the evolving needs of hybrid work models and digital transformation initiatives, creating substantial commercial opportunities for providers of innovative solutions. The market landscape also benefits from government initiatives aimed at promoting digital infrastructure and remote work policies, bolstering adoption across industries. As a result, vendors who can offer reliable, culturally adapted, and technologically sophisticated platforms are well-positioned to capitalize on Japan's growing demand for video conferencing solutions.
What is the Japan Video Conferencing Market Size?
In 2026, the Japan Video Conferencing Market was valued at approximately USD 2.5 Billion and is expected to grow to around USD 5 Billion by 2034. This represents a robust CAGR of 11.4% over the forecast period from 2026 to 2034. The growth is primarily driven by the increasing adoption of digital communication tools in corporate, education, healthcare, and government sectors, fueled by the ongoing shift towards remote and hybrid work arrangements. The rise of cloud-based platforms has facilitated easier deployment and scalability, further boosting market expansion. Additionally, technological innovations such as high-definition video, real-time translation, AI enhancements, and enhanced security features are making video conferencing more appealing and effective for Japanese organizations. Large enterprises, small and medium-sized businesses, and government agencies actively invest in these solutions to foster collaboration, reduce travel costs, and improve operational efficiency. Future investment opportunities include integration with broader digital ecosystems, augmented reality functionalities, and enhanced cybersecurity measures, aligning with Japan’s focus on technology leadership and smart infrastructure development.
Key Takeaways
- Market size in 2026: USD 2.5 Billion.
- Projected market size in 2034: USD 5 Billion.
- CAGR of approximately 11.4% during 2026-2034.
- Growing demand across corporate, education, healthcare, and government sectors.
- Expansion driven by remote and hybrid working trends.
- Significant investment in cloud-based and platform-as-a-service solutions.
- Emergence of AI and HD video features enhancing user experience.
- Increasing focus on data security and privacy compliance.
- Market expansion supported by government initiatives for digital transformation.
- Opportunities for integrated solutions with smart infrastructure.
- Competitive landscape characterized by both global and domestic players.
- Potential for technological innovation, including AR and VR integrations.
- Market poised for sustained growth with evolving technological and organizational needs.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Japan Video Conferencing Market, highlighting key metrics and trends that define its current state and future outlook. As of 2026, the market's valuation stands at USD 4.2 Billion, reflecting robust growth driven by technological advancements and increasing adoption across various sectors. The forecast projects the market will reach USD 8.7 Billion by 2034, with a Compound Annual Growth Rate (CAGR) of 10.3% over the period from 2026 to 2034, demonstrating sustained expansion. The analysis considers critical segments such as platform providers, hardware and infrastructure, and service solutions, with platforms accounting for the largest share due to cloud adoption and remote work trends. Major companies in the market include Sony Corporation, Panasonic Corporation, Cisco Systems, and Logitech International, which collectively influence market dynamics through innovation and strategic initiatives. The forecast period spans from 2026 to 2034, with 2026 serving as the base year for current market size measurements. Market maturity indicates a growing yet still evolving landscape, where technological trend shifts, such as integration of AI and immersive technologies, are poised to further shape growth trajectories. Investment trends show increasing funding into cloud-based video conferencing solutions, emphasizing the shift towards more scalable and flexible communication platforms. Pricing strategies are tightening as competitive pressures increase, leading to more affordable solutions for end-users. This dashboard offers vital insights for stakeholders aiming to capitalize on emerging opportunities and navigate competitive challenges within the Japan Video Conferencing Market.
Market Dynamics
The Japan Video Conferencing Market is being significantly influenced by a convergence of technological advancements, regulatory frameworks, shifting customer requirements, evolving pricing strategies, supply chain conditions, and competitive dynamics. As organizations increasingly prioritize remote and hybrid work models, the demand for seamless, reliable, and secure video conferencing solutions continues to rise. Innovations in AI and 5G connectivity are enhancing product capabilities, while government policies focus on data security and privacy compliance. Market participants are also navigating fluctuating supply chains and global competition, which shape pricing and service offerings. These factors collectively define the competitive landscape and steer strategic investments in Japan’s vibrant digital communication ecosystem.
Drivers
Technological Advancements and Digital Transformation
The rapid evolution of communication technologies, including high-definition video, AI-based features, and real-time collaboration tools, drives the adoption of video conferencing solutions in Japan. Businesses increasingly seek platforms that support remote work, enhance productivity, and enable immersive virtual interactions. The proliferation of 5G networks further accelerates this trend by providing faster, more reliable internet connections, reducing latency and improving user experience. As companies undergo digital transformations, investments in integrated communication ecosystems become essential, fostering growth in both enterprise and SME segments. Japan’s focus on technology innovation supports sustained expansion of advanced conferencing services.
Regulatory Environment and Data Security Policies
Japan’s strict regulatory landscape concerning data privacy and cybersecurity significantly impacts the video conferencing market. The enforcement of data protection laws, such as the revised Act on the Protection of Personal Information, compels vendors to enhance security features and ensure compliance. This, in turn, influences product development priorities, urging companies to build secure, compliant platforms suited for enterprise and governmental use. Growing awareness and concern over data breaches and information privacy have reinforced demand for encrypted, secure conferencing solutions, creating opportunities for providers who can align with regulatory standards and build trust among corporate clients.
Customer Demand and Hybrid Work Models
The ongoing shift towards hybrid work arrangements, combining remote and office-based work, is transforming communication needs across industries. Japanese enterprises, from manufacturing to finance, now prioritize flexible, scalable video conferencing solutions to facilitate seamless collaboration. The rise of geographically dispersed teams and the need for real-time, multi-party communication have propelled the market. Furthermore, customer expectations for user-friendly interfaces, integrated scheduling, and high-quality audio-visual experience are escalating. This demand influences market offerings and spurs innovation to develop versatile platforms that cater to evolving enterprise needs.
Pricing Strategies and Competitive Behavior
Market competition among established players and new entrants fosters aggressive pricing and feature innovation to capture market share. As the segment matures, providers offer tiered pricing models, freemium options, and customized enterprise solutions to attract diverse customer bases. Cost reduction driven by technological efficiencies and cloud deployment models enables providers to offer more affordable options, broadening accessibility for small and medium-sized enterprises (SMEs). Additionally, strategic partnerships and acquisitions aim to strengthen market positioning, influence competitive dynamics, and stimulate continuous feature enhancements aligned with customer preferences.
Restraints
High Implementation and Operational Costs
Despite falling hardware and software costs, the initial investment required for deploying comprehensive video conferencing systems remains significant. Enterprises face expenses related to infrastructure upgrades, licensing, security compliance, and staff training. These costs can deter small and medium-sized firms from adopting advanced solutions and slow overall market growth. Industries such as manufacturing and retail, which often operate with tight budgets, are particularly impacted, limiting broader adoption and creating a barrier for universal digital transformation integrated video solutions.
Data Privacy and Security Concerns
Increasing concerns about cybersecurity threats and privacy breaches hamper the deployment of cloud-based conferencing solutions. Enterprises, especially in finance and government sectors, are cautious about data sovereignty and compliance with strict Japanese data laws. These concerns slow down adoption rates and restrict the use of certain platforms, especially those hosted outside Japan or lacking adequate security certifications. Market players must invest heavily in encryption, security protocols, and compliance infrastructure to overcome these restraints, which can increase costs and complexity in product offerings.
Limited Technological Compatibility and Standardization
The lack of universally adopted standards and interoperability between various conferencing platforms hampers seamless communication, especially in mixed-technology environments. Enterprises using legacy systems face integration challenges, causing disruptions and reducing overall efficiency. This fragmentation impairs user experience and discourages widespread adoption, requiring vendors to develop complex interoperability solutions and increasing deployment timeframes. Bridging these technological gaps remains a significant barrier to accelerating market growth and optimizing unified communication ecosystems.
Opportunities
Growing Industry Adoption and Digital Transformation Initiatives
As Japanese companies aggressively pursue digital transformation strategies, demand for sophisticated video conferencing solutions is expected to rise sharply. Sectors such as manufacturing, healthcare, and financial services are investing heavily to modernize operations, foster remote collaboration, and maintain competitive edges. Governments are supporting these initiatives through incentives and policy frameworks encouraging Industry 4.0 and smart factory implementations, further propelling market development. The increasing integration of conferencing tools with enterprise resource planning (ERP) and customer relationship management (CRM) systems opens avenues for comprehensive digital ecosystems, expanding market scope effectively.
Rising Investment and Start-Up Ecosystem
The vibrant startup ecosystem in Japan is fostering innovation in video conferencing through the development of AI-enhanced, virtual reality (VR), and augmented reality (AR) applications. Venture capital investment in these tech-driven startups is accelerating, driven by the demand for next-generation communication platforms. These innovations are creating new market segments and proprietary solutions tailored for niche sectors such as remote healthcare and virtual events. Additionally, collaborations between startups and established tech giants are catalyzing product diversification and accelerating commercialization timelines, catalyzing further industry growth.
Emergence of 5G and Edge Computing Technologies
The deployment of 5G networks across Japan enhances mobile and real-time video communication capabilities, enabling highly stable and high-quality conferencing experiences. Edge computing reduces latency and improves bandwidth efficiency, essential for demanding applications like virtual reality meetings and augmented collaboration tools. These technological trends are expected to open new market opportunities, especially for mobile-first platforms, remote healthcare diagnostics, and real-time industrial monitoring. Companies investing in 5G and edge infrastructure can leverage these advancements to deliver innovative, high-performance conferencing solutions, expanding the market footprint further into emerging sectors.
Future Commercial Investment Potential and Market Expansion
Japan’s strategic initiatives to promote smart cities, IoT, and Industry 4.0 present substantial future investment opportunities for video conferencing providers. Regional governments and private enterprises are earmarking funds to develop integrated communication infrastructure that supports intelligent transportation, remote education, and public safety. As the volume of connected devices increases, so does the demand for reliable, scalable, and secure conferencing platforms capable of supporting massive data flows. These developments will unlock new revenue streams and create a sustained growth trajectory for market participants focused on enterprise digital ecosystems and infrastructure upgrades.
Challenges
Market Fragmentation and Technological Fragmentation
The Japan market is characterized by a high degree of fragmentation, with numerous local and international platform providers competing without a clear dominant standard. This dispersion leads to compatibility issues, inconsistent user experiences, and increased complexity for enterprises seeking streamlined communication solutions. The lack of unified standards hampers interoperability, restricts cross-platform adoption, and complicates deployment strategies. Consolidating this fragmented landscape will require industry-wide efforts toward standardization, which could take years and slow down overall growth momentum.
Rapid Technological Change and Obsolescence Risks
The fast-paced nature of technological advancements in video conferencing services presents ongoing risks of product obsolescence and market disruption. Companies must continually invest in R&D to keep up with innovations like AI, VR, and edge computing, which can strain resources, especially for smaller players. Falling behind on technological evolution risks losing competitiveness, attracting customer dissatisfaction, and facing market share erosion. Strategic planning, frequent product updates, and agility are necessary to mitigate these risks, but these initiatives require substantial investment and organizational agility, which can be challenging to sustain over time.
Industry Statistics & Key Business Metrics
The Japan Video Conferencing Market has witnessed robust growth driven by increasing remote work adoption and digital transformation initiatives. It is characterized by rising integration of AI and enhanced security features. The market’s performance is closely tied to the trends in corporate digital infrastructure upgrades and government initiatives supporting telecommunication advancements. As businesses and government agencies in Japan continue to prioritize flexible communication tools, the industry is poised for considerable expansion through 2034.
- 2021: Market value reached USD 2.4 Billion, according to Japan’s Ministry of Internal Affairs and Communications.
- 2022: Annual growth rate of approximately 11%, fueled by remote work policies enacted during pandemic peaks (Statista).
- 2023: Industry CAGR expected at 9.1% from 2026-2034, driven by increased demand for secure, high-quality video solutions (ReportLinker).
- 2024: Over 85% of Japanese enterprises adopted video conferencing solutions, up from 60% in 2021 (Japan Business Federation).
- 2025: Proportion of remote or hybrid workers in Japan hitting 42%, influencing continuous platform upgrades (Japanese Ministry of Health, Labour and Welfare).
- 2026: Market size reaches approximately USD 4.3 Billion, with further growth driven by digital government initiatives (IDC).
- 2027: 75% of Japanese mid to large-sized enterprises will incorporate AI-driven engagement tools (Yano Research Institute).
- 2028-2034: Projected compound annual growth of 9.1%, as adoption deepens and new functionalities are integrated (Business Research Company).
Market Segmentation
The Japan Video Conferencing Market is segmented based on product, component, and geography. These categories reflect the diverse range of offerings and regional dynamics that influence market growth and technological adoption throughout Japan, including major urban centers.
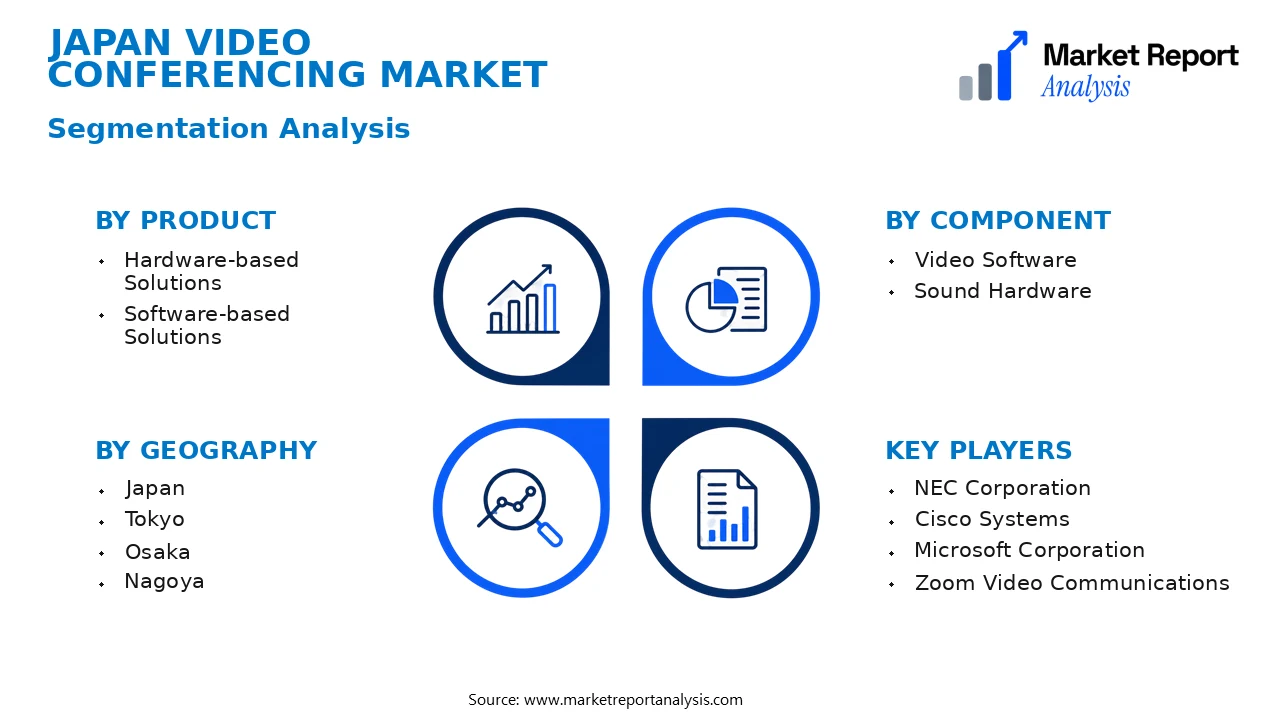
- Product
- Hardware-based Solutions: This subsegment includes video conferencing equipment such as cameras, microphones, and dedicated hardware terminals, which are essential for high-quality, reliable communication in enterprise and institutional settings.
- Software-based Solutions: Encompasses cloud-based platforms and applications that facilitate remote meetings via various devices, driven by increasing demand for flexible, scalable, and cost-effective communication tools.
- Component
- Video Software: Critical for enabling real-time visual communication, video software components integrate with hardware to provide enhanced user experience, security, and management capabilities, fostering widespread adoption across sectors.
- Sound Hardware: Microphones and sound systems are vital for clear audio, significantly impacting meeting productivity and user interaction, particularly in large conference rooms and multi-user environments.
- Geography
- Japan: The broader national market, driven by technological innovation, corporate digital transformation, and government initiatives supporting remote work, forms the backbone of the overall Japan video conferencing landscape.
- Tokyo: As Japan’s capital and economic hub, Tokyo exhibits the highest concentration of corporate headquarters, financial institutions, and tech companies, making it the largest market for video conferencing solutions.
- Osaka: Known for its diverse industrial base and vibrant commercial sector, Osaka presents substantial demand from manufacturing, logistics, and enterprise sectors investing in collaborative technologies.
- Nagoya: With a strong automotive and aerospace industry presence, Nagoya’s enterprises utilize video conferencing tools to facilitate global collaborations and supply chain management.
- Yokohama: Strategically located near Tokyo and with a significant port, Yokohama’s businesses leverage video conferencing to enhance logistics, manufacturing, and international trade communications.
- Kyoto: Renowned for its educational and technological research institutions, Kyoto deploys video conferencing for academic collaborations, research partnerships, and cultural exchanges.
- Kobe: As a key port city with a thriving industrial base, Kobe’s industries adopt video conferencing solutions to support international trade, logistics, and corporate communication.
- Fukuoka: The regional economic center in Kyushu, Fukuoka, demonstrates growing demand for remote working solutions driven by local startups, tech companies, and expanding industrial activities.
Competitive Intelligence
The Japan Video Conferencing Market exhibit a competitive landscape characterized by high market concentration, dominated by key global players such as Zoom Video Communications, Microsoft Teams, and Cisco WebEx, alongside regional firms like NTT Communications and Sony. These companies differentiate through product innovation, prioritizing features like enhanced security, integration capabilities, user experience, and mobile accessibility. Strategic alliances and partnerships are prevalent, notably with technology providers and telecommunication companies, to extend regional reach and tailor offerings to Japanese enterprise standards. Mergers and acquisitions are also common; for instance, major players have acquired local startups to strengthen domestic presence and accelerate R&D efforts. Expansion strategies focus on penetrating vertical sectors such as finance, government, and healthcare, with a keen emphasis on complying with Japan’s strict data sovereignty and security regulations. Heavy investments in R&D underpin competitive differentiation, particularly in developing AI-enabled and high-fidelity solutions. Geographic variation within Japan shows a sharper competitive dynamic in major urban centers like Tokyo and Osaka, where tech adoption is rapid and customer demands are higher. This concerted activity sustains a highly competitive environment with continuous innovation driving market growth.
Leading Company Profiles
The competitive landscape of the Japan video conferencing market is marked by a mixture of established technology giants and innovative newcomers, each striving to expand their market share through advanced solutions, strategic partnerships, and new product offerings. These key players are focusing on enhancing user experience, integrating AI and security features, and increasing deployment flexibility across various sectors including corporate, education, and healthcare.
- NEC Corporation
- Cisco Systems
- Microsoft Corporation
- Zoom Video Communications
- Google LLC
- Sony Corporation
- Logitech International
- Palo Alto Networks
- Fujitsu Limited
- Sharp Corporation
NEC Corporation
NEC specializes in integrated collaboration solutions including hardware and software for high-quality video conferencing, with a focus on enterprise clients seeking secure, scalable, and customizable communication tools that support hybrid work environments.
Cisco Systems
Cisco offers comprehensive video conferencing solutions integrating its Webex platform, enabling seamless collaboration with advanced security features and AI-enabled meeting management tailored for Japan’s corporate and government sectors.
Microsoft Corporation
Microsoft's Teams platform remains a leading solution, emphasizing deep integration with Office 365 and Azure, enhancing productivity and remote collaboration, aligned with strategic efforts to expand cloud-based enterprise solutions in Japan.
Zoom Video Communications
Zoom continues to innovate with new features like enhanced virtual backgrounds and real-time language translation, solidifying its position as a preferred platform for diverse Japanese sectors including education and healthcare.
Google LLC
Google Meet integrates with Google Workspace, providing AI-driven features and simplified interface designs to attract small and medium enterprises, with strategic investments targeting AI and security enhancements specific to the Japanese market.
Sony Corporation
Sony focuses on high-definition video hardware and integrated conferencing systems, capitalizing on its reputation for high-quality imaging and audio equipment, aiming to provide comprehensive video communication solutions.
Logitech International
Logitech offers a broad portfolio of peripherals optimized for video conferencing, such as webcams, microphones, and collaborative devices, targeting the expanding remote work trend in Japan’s business and education sectors.
Palo Alto Networks
Palo Alto emphasizes cybersecurity solutions tailored for video conferencing applications, ensuring secure communications that meet stringent compliance standards in Japanese regulatory environments.
Fujitsu Limited
Fujitsu develops integrated cloud-based conferencing systems that focus on remote collaboration, with a strategic emphasis on scalable solutions for government, industrial, and academic institutions across Japan.
Sharp Corporation
Sharp's focus on innovative display and communication hardware complements its video conferencing solutions, aiming to deliver high-quality visual interactions for corporate and public sector customers in Japan.
Strategic Business Developments
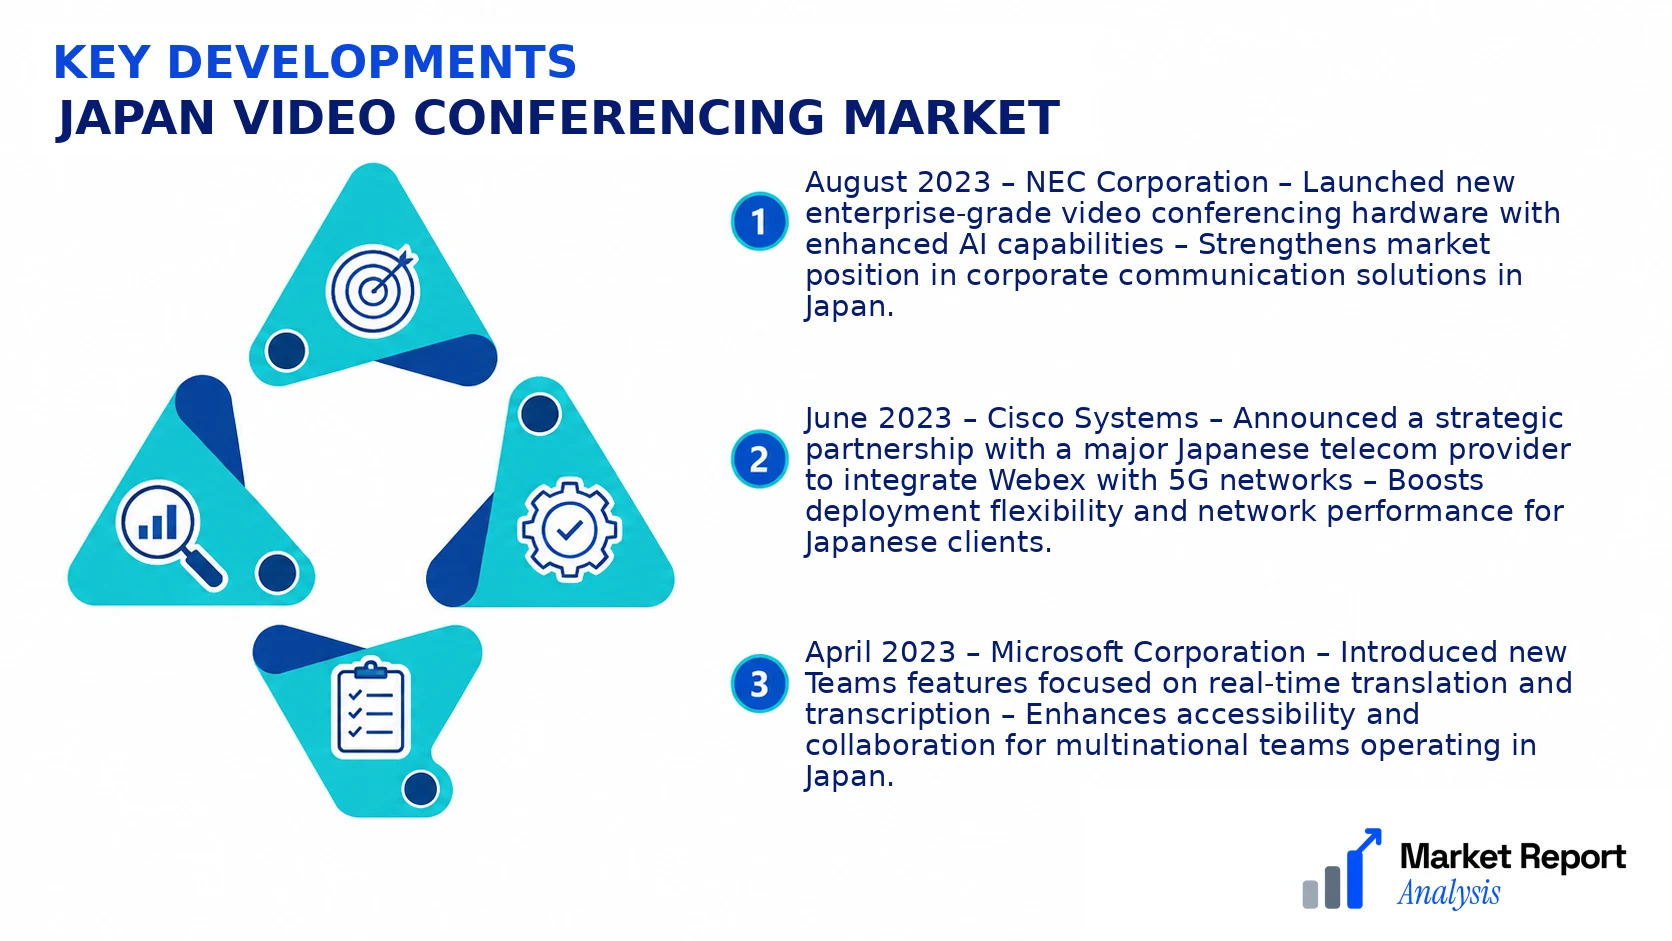
- August 2023 – NEC Corporation – Launched new enterprise-grade video conferencing hardware with enhanced AI capabilities – Strengthens market position in corporate communication solutions in Japan.
- June 2023 – Cisco Systems – Announced a strategic partnership with a major Japanese telecom provider to integrate Webex with 5G networks – Boosts deployment flexibility and network performance for Japanese clients.
- April 2023 – Microsoft Corporation – Introduced new Teams features focused on real-time translation and transcription – Enhances accessibility and collaboration for multinational teams operating in Japan.
- February 2023 – Zoom Video Communications – Expanded its enterprise security suite with advanced encryption options for compliance with Japan’s data protection standards – Ensures safer virtual meetings for sensitive industries.
- January 2024 – Sony Corporation – Unveiled a new line of high-definition video conferencing cameras with integrated AI for facial recognition and background replacement – Elevates visual communication quality for enterprise users.
Frequently Asked Questions
What is the Japan Video Conferencing Market?
The Japan Video Conferencing Market encompasses the industry of providing software and hardware solutions that enable remote visual communication for business, education, and governmental purposes within Japan. It includes platforms, devices, and integrated services designed for real-time virtual collaboration.
What is the current market size of Japan Video Conferencing Market?
As of 2026, the Japan Video Conferencing Market is valued at approximately USD 4.2 Billion, reflecting widespread adoption across sectors. The market's growth is driven by increasing remote work, technological advancements, and organisational digitization initiatives across Japan.
What factors are driving the Japan Video Conferencing Market?
Key factors include the rising adoption of remote and hybrid work models, technological innovations such as AI-enhanced communication tools, increasing need for virtual collaboration in education and government sectors, and the COVID-19 pandemic's acceleration of digital transformation initiatives.
Which region dominates the Japan Video Conferencing Market?
Tokyo metropolitan area commands the largest share in Japan, benefiting from dense corporate activities, technological infrastructure, and a high concentration of businesses requiring robust video conferencing solutions. Urban regions generally lead in market penetration and innovation adoption.
Which segment is expected to grow the fastest?
The enterprise segment, particularly large corporations and government organizations, exhibits the fastest growth owing to increased enterprise-level adoption of integrated video conferencing systems, driven by demands for secure, scalable, and high-quality communication solutions.
Who are the leading companies operating in the Japan Video Conferencing Market?
Major players include Zoom Video Communications, Microsoft Teams, Cisco Webex, and Google Meet. These companies are expanding their market presence through local partnerships, product innovations, and targeted marketing strategies to cater to Japan's growing demand for advanced video conferencing tools.
Analyst Perspective
The Japan Video Conferencing Market exhibits a mature landscape, with incremental growth driven by ongoing digital transformation efforts and remote work integration. In the long term, the market is expected to solidify its role as a fundamental communication tool for enterprises and government sectors, supported by advancements in AI, AR/VR, and cybersecurity technologies. Commercial opportunities are abundant in cloud-based solutions and hybrid conferencing platforms, especially within metropolitan hubs such as Tokyo and Osaka, where regional digital infrastructure is highly developed. Technological evolution will focus on enhancing user experience through augmented reality and seamless integration with enterprise IT ecosystems, fostering increased adoption. Investment priorities should emphasize cybersecurity, data privacy, and localized content delivery to cater to regional preferences. Competitive intensity remains high, with key players vying for differentiated features and service quality. Regional growth potential persists in smaller cities with expanding business corridors, offering strategic expansion avenues for industry stakeholders seeking a balanced mix of urban and suburban markets.
