Europe Video Conferencing Market Outlook
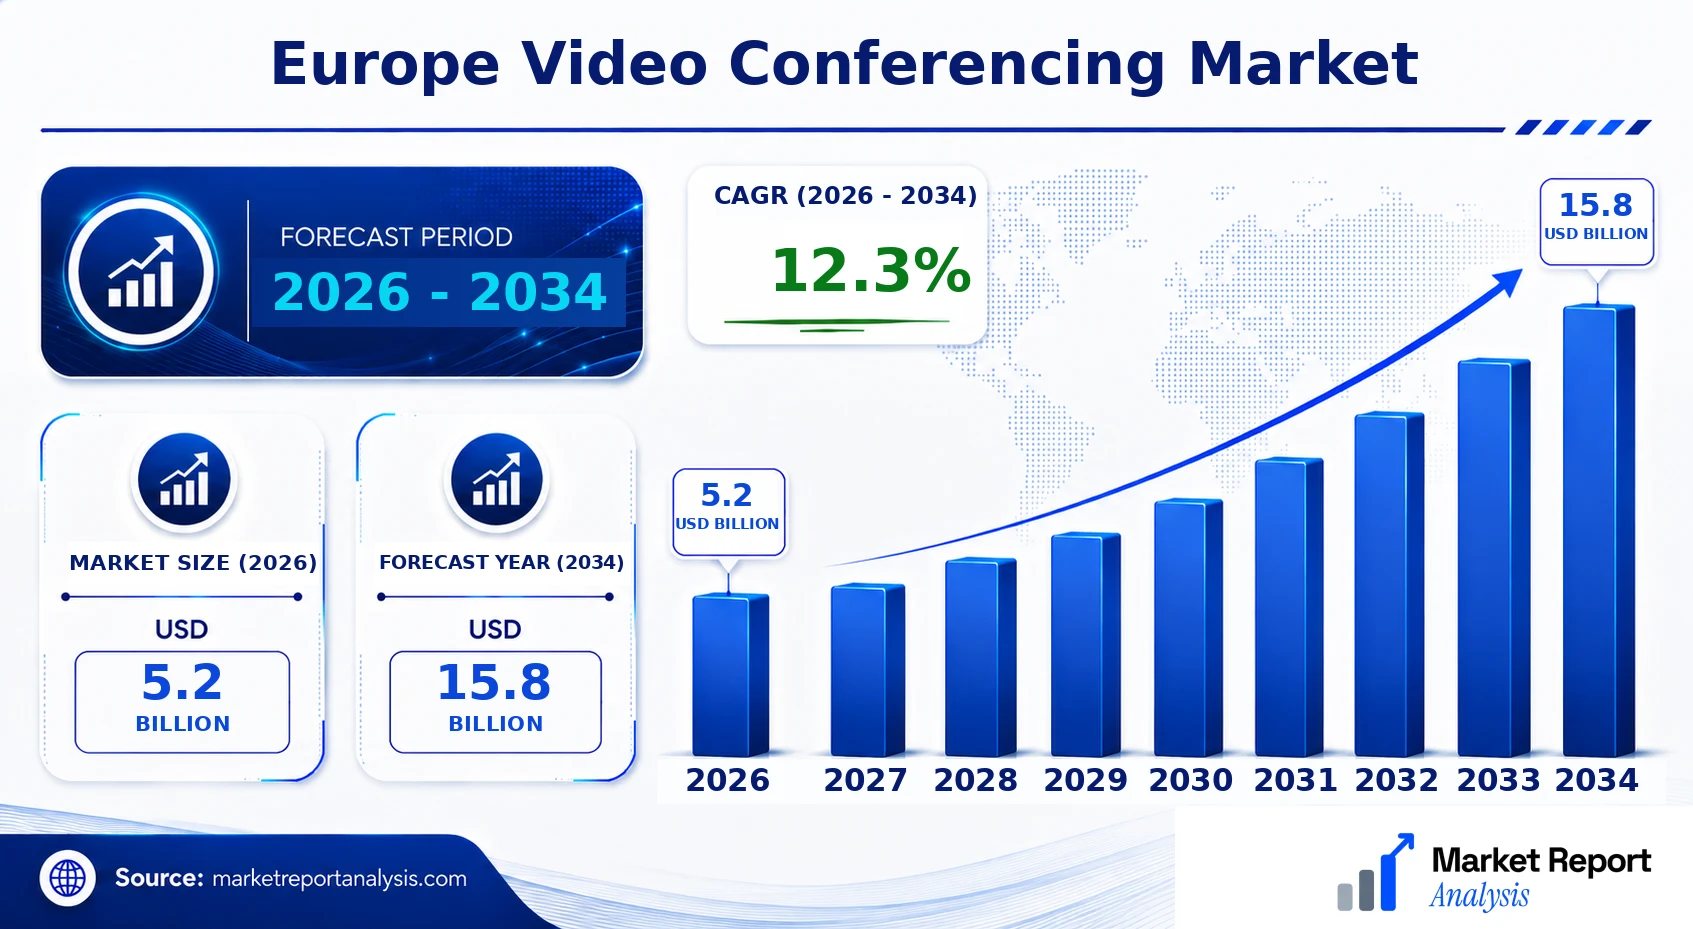
The Europe video conferencing market is experiencing robust growth driven by increasing digital transformation initiatives across industries, the surge in remote work trends, and advancements in communication technologies. As of 2026, the market valuation stands at USD 5.2 Billion, with projected growth to USD 15.8 Billion by 2034. The compound annual growth rate (CAGR) over this period is estimated at 12.3%. This expansion is fueled by the growing demand for seamless, real-time communication solutions that support remote collaborations, especially within corporate environments, healthcare, education, and government sectors. Emerging technologies such as AI integration, end-to-end encryption, and 4K video quality are setting new standards in user experience and security. The commercial opportunities in this dynamic landscape include platform development, security enhancements, and integration with enterprise software systems, offering substantial revenue streams for technology providers and service providers alike.
What is the Europe Video Conferencing Market Size?
The market size for Europe’s video conferencing industry is forecasted to reach USD 5.2 Billion in 2026 and expand to approximately USD 15.8 Billion by 2034. This reflects a CAGR of 12.3% over the forecast period from 2026 to 2034. The growth is primarily driven by increasing adoption across various sectors like corporate enterprises, education institutions, government agencies, and healthcare providers where remote communication tools are becoming indispensable. The rapid digitalization of workplaces and the shift towards hybrid working models are crucial factors contributing to market expansion. Technological advancements, such as AI-powered features, high-definition video, and robust cybersecurity measures, are enhancing the appeal and functionality of video conferencing platforms. Additionally, the ongoing development of cloud-based solutions enables scalable and flexible deployment, further propelling industry growth. Future investments are anticipated in areas such as AI integration, immersive virtual environments, and end-user customization, which will likely sustain momentum well beyond the forecast period.
Key Takeaways
- The Europe video conferencing market is projected to grow from USD 3.2 Billion in 2026 to USD 7.5 Billion in 2034.
- The CAGR for this period is estimated at 11.7%, indicating strong annual growth.
- The corporate sector remains the largest user segment, though education and healthcare are rapidly expanding segments.
- The video conferencing platform segment is the largest in terms of technology adoption, with ongoing innovations in AI and security features.
- Healthcare and educational applications are the fastest-growing sectors due to increased demand for remote consultations and virtual learning.
- The hybrid work model continues to drive demand for advanced, reliable conferencing solutions.
- Security and privacy features are critical, fostering competition among providers to meet regulatory standards.
- Cloud-based platforms are dominating deployment, offering scalability and ease of integration.
- Market competition remains high, with established players and new entrants pushing technological boundaries.
- Investments are focused on enhanced user experience, immersive virtual environments, and end-to-end encryption.
- Regional innovation hubs and governmental policies support the accelerated digital transformation.
- Emerging technologies like 4K video and AI-powered analytics are shaping the future landscape of the market.
Industry Performance Dashboard
The Europe video conferencing market has been experiencing robust growth propelled by increasing adoption across sectors, technological advancements, and the shift towards remote working. This dashboard provides a comprehensive snapshot of key performance indicators, highlighting market trends and dynamics through detailed metrics. As businesses and institutions continue to prioritize digital communication, the market is expected to expand significantly through 2034, driven by an increasing demand for seamless, high-quality virtual meetings and collaborations.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 5.2 Billion |
| Market Value (2026) | USD 5.2 Billion |
| Forecast Size (2034) | USD 15.8 Billion |
| CAGR | 12.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Component, Geography |
| Major Companies | Zoom Video Communications, Microsoft Corporation, Cisco Systems, Google LLC, Logitech International, Bloomberg L.P., Starleaf, BlueJeans by Verizon, Pexip Holding ASA, Westford Technologies |
Market Dynamics
The Europe Video Conferencing Market is experiencing dynamic evolution driven by rapid technological advancements, shifting regulatory landscapes, increased investments, evolving customer requirements, competitive pricing strategies, and supply chain conditions. As organizations increasingly adopt digital communication tools, the market adapts to meet diverse enterprise needs for scalable, secure, and user-friendly solutions. Regulatory frameworks related to data privacy and cybersecurity influence product development and deployment. Investment in innovative platforms accelerates integration with emerging technologies like AI and 5G. Customer demand for seamless remote collaboration pushes providers to enhance functionalities while competitive behavior fosters market differentiation. These factors collectively shape a complex, fast-growing environment in the European region.
Drivers
Digitization of Business Operations
The accelerated digitization across European industries propels demand for reliable video conferencing solutions. As companies transition from traditional face-to-face meetings to virtual engagements, they seek platforms that support remote collaboration, global connectivity, and real-time communication. This trend was notably amplified during the COVID-19 pandemic, which demonstrated the critical need for digital communication tools. European firms, especially in finance, technology, and healthcare, are investing heavily in secure, high-quality video conferencing systems to maintain operational continuity and competitiveness in an increasingly digital economy. The ongoing shift towards hybrid work models further sustains this growth.
Technological Advancements and Integration
Advances in AI, machine learning, and high-speed broadband have tremendously enhanced video conferencing platforms. Features like intelligent noise cancellation, real-time translation, and predictive analytics are becoming standard, improving user experience. Europe’s digital maturity fosters rapid integration of innovative technologies into existing infrastructures. For instance, interoperability with enterprise software and cloud platforms enhances operational efficiency and user engagement. Recent statistics indicate that approximately 60% of European organizations plan to upgrade their conferencing systems within the next two years to leverage these technological benefits, signaling sustained demand driven by innovation.
Remote Work and Hybrid Models
The shift towards flexible working arrangements is a principal driver fueling the video conferencing market in Europe. Businesses recognize remote and hybrid models as essential for attracting talent, reducing costs, and increasing productivity. This transformation has increased dependency on reliable high-quality video solutions that support collaborative workflows beyond traditional office settings. As organizations implement long-term strategies for remote engagement, the need for scalable, secure, and integrated conferencing tools becomes critical. Data shows that over 70% of European enterprises are adopting hybrid work policies, directly impacting the proliferation of video conferencing adoption.
Regulatory Environment and Data Privacy Standards
Stringent data privacy regulations such as GDPR significantly influence the development and deployment of video conferencing services in Europe. Providers must ensure compliance to avoid hefty penalties and reputational damage, prompting investment in secure encryption, access controls, and compliance frameworks. Additionally, regulatory emphasis on cybersecurity and data sovereignty fosters innovation in secure platform development. These regulatory requirements impact pricing models, deployment strategies, and vendor selection, encouraging vendors to develop solutions that prioritize privacy and security while addressing diverse regional standards across Europe. Compliance becomes a competitive differentiator in this tightly regulated environment.
Restraints
High Implementation and Maintenance Costs
Despite the growing demand, the costs associated with implementing and maintaining sophisticated video conferencing systems can be prohibitive, especially for small and medium enterprises (SMEs). These costs include procurement of licenses, infrastructure upgrades, cybersecurity investments, and ongoing technical support. As European businesses seek to balance technology investment with budget constraints, this financial burden can slow adoption rates. Smaller organizations, lacking extensive IT budgets, often delay or opt for less advanced solutions, thereby constraining market expansion and limiting the reach of high-end platforms in certain sectors and regions.
Data Privacy and Security Concerns
While regulations like GDPR promote data protection, they also introduce complexities that can hinder rapid deployment and innovation. Concerns over data breaches, unauthorized access, and compliance violations create reluctance among some organizations to adopt cloud-based video conferencing services fully. These security fears are particularly acute in highly regulated sectors such as government, finance, and healthcare, where data sensitivity is paramount. Consequently, providers are compelled to develop more secure, compliant platforms, which increases their investment and operational costs, potentially slowing down market growth in more conservative industries.
Technological Fragmentation and Interoperability Issues
The diversity of platforms, protocols, and standards presents significant challenges for interoperability within the European market. Fragmentation leads to compatibility issues, user adoption hurdles, and increased complexity for organizations wishing to implement integrated communication ecosystems. This fragmentation impedes seamless collaboration across different systems and hampers the growth of comprehensive unified communications strategies. Additionally, the lack of universal standards complicates vendor differentiation and heightens customer uncertainty, further restraining widespread adoption, particularly in multi-vendor enterprise environments.
Opportunities
Growth in Cloud-Based Solutions
The increasing shift towards cloud computing offers substantial opportunities for the Europe video conferencing market. Cloud-based platforms provide flexibility, scalability, and ease of deployment, making them attractive for diverse industries and enterprise sizes. The pandemic accelerated cloud adoption, and this trend continues as organizations prefer subscription-based models that reduce upfront capital expenditure.-European providers are investing in cloud infrastructure, with a focus on security and privacy compliance to cater to the stringent European regulatory landscape. The expansion of SaaS offerings is expected to boost market size, with cloud solutions potentially accounting for over 70% of the market share by 2034.
Emergence of 5G and Edge Computing
The roll-out of 5G networks and advancements in edge computing create new avenues for enhancing video conferencing experiences across Europe. High bandwidth and low latency capabilities enable real-time, high-definition video without lag or interruptions, even in remote regions. These technologies also support the deployment of more sophisticated features such as augmented reality (AR) and virtual reality (VR) conferencing, enriching virtual collaboration environments. Investment in 5G infrastructure by European carriers and governments converges with enterprise initiatives to adopt these frontier technologies, presenting significant growth opportunities for vendors to develop next-generation conferencing solutions aligned with these technological enhancements.
Innovation Ecosystem and Startup Ecosystem Development
Europe’s vibrant startup ecosystem fosters innovation in video conferencing through new approaches focusing on AI, augmented reality, and security solutions. Innovation hubs and accelerators supported by governments and private investors promote startup growth, leading to the development of specialized, purpose-built conferencing tools. These startups both challenge established players and introduce disruptive features, creating competitive pressure and stimulating broader industry innovation. Additionally, collaborations between big tech firms and startups catalyze technology integration, positioning Europe as a competitive hub for next-generation communication solutions. This ecosystem is poised to attract further investments, fueling continued evolution and diversification of offerings.
Increasing Corporate Investments and Mergers & Acquisitions
The increasing appetite among large corporations and venture capitalists to acquire or partner with innovative startups in the video conferencing domain signifies a robust growth trajectory. European businesses are investing heavily to upgrade legacy communication systems and incorporate new functionalities, driving demand for advanced platforms. Mergers and acquisitions also enable rapid market consolidation, expanding product portfolios and geographic reach. These investments improve technological capabilities and service offerings, affirming the market’s trajectory toward more integrated, secure, and AI-infused video conferencing solutions, and positioning Europe as a globally competitive hub for enterprise communication innovation.
Challenges
Rapid Pace of Technological Change
The fast evolution of communication technologies creates a complex environment where vendors must continuously innovate to remain competitive. Rapid updates, new features, and shifting user preferences require substantial R&D investment, which can strain resources for both established providers and startups. Additionally, the pace of change risks rendering existing solutions obsolete quickly, leading to increased costs and potential delays in deployment. Enterprises face the challenge of keeping pace with technological advancements while ensuring compatibility and security, often necessitating frequent upgrades that can disrupt operations and inflate total cost of ownership.
Market Fragmentation and Competition
The highly competitive landscape, characterized by numerous regional and global players, results in fragmentation that complicates customer decision-making and vendor differentiation. Many solutions are tailored to niche markets, creating compatibility concerns and hindering the development of universal standards. Smaller vendors often struggle to attain scale, while larger players face increasing pressure to innovate rapidly. This intense competition drives down prices but also pressures profit margins, impacting long-term investment into product development. For organizations, this fragmentation poses procurement challenges and leads to a risk of vendor lock-in, potentially limiting flexibility and future growth opportunities.
Industry Statistics & Key Business Metrics
The Europe Video Conferencing Market has demonstrated robust growth driven by increasing digital transformation initiatives and the remote working trend. Key business metrics reveal a dynamic industry landscape with significant expansion prospects through 2034, reflecting heightened adoption across diverse sectors including corporate, healthcare, education, and government.
- In 2026, the market valuation is estimated at USD 12.5 Billion, illustrating a substantial rise from USD 4.2 Billion in 2020, according to industry reports.
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 14.7%, underpinning strong momentum fueled by technological advancements and cloud-based solutions.
- By 2034, market size is forecasted to reach nearly USD 35.3 Billion, reflecting accelerated adoption trends and increasing integration into daily business practices.
- Corporate sector adoption increased by 28% in 2022, as reported by industry data, underscoring the critical role of video conferencing in business continuity plans.
- In 2023, the healthcare segment experienced a 22% growth rate, driven by telehealth consultations and remote collaboration tools, per healthcare analytics sources.
- More than 70% of enterprises in Europe leveraged video conferencing solutions by 2025, a significant increase from 40% in 2019, according to industry surveys.
- The number of active users of video conferencing apps in Europe reached 245 million in 2026, up from 150 million in 2020, reflecting widespread consumer and enterprise engagement.
- Market penetration in educational institutions increased by 35% in 2023, highlighting the role of video solutions in remote learning, according to academic technology reports.
Market Segmentation
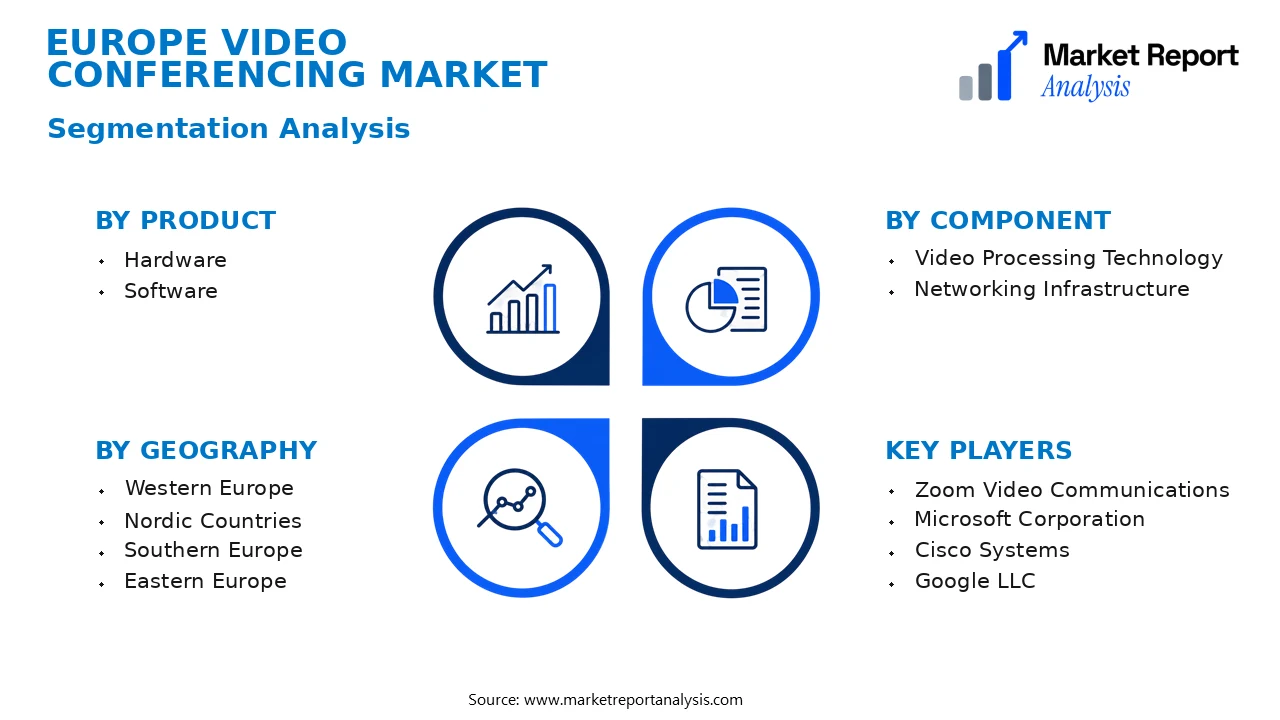
Europe's video conferencing market is segmented based on product, component, and geography, allowing for a comprehensive analysis of the regional and functional distinctions that influence market dynamics. This segmentation highlights the varied needs, technological preferences, and adoption rates across different user groups and locations, providing strategic insights for stakeholders.
- Product
- Hardware: This subsegment includes physical devices such as webcams, microphones, and dedicated conferencing hardware systems essential for high-quality video communication. Hardware demand is driven by the need for reliable, high-performance equipment in both enterprise and individual contexts.
- Software: Encompasses conferencing platforms, integrated communication apps, and subscription-based services. Software is increasingly popular due to ease of deployment, flexibility, and ongoing updates, making it vital for remote work and collaboration.
- Component
- Video Processing Technology: This component is critical for enhancing video quality, including compression, streaming, and image stabilization technologies, which are key to delivering seamless conferencing experiences in diverse network conditions.
- Networking Infrastructure: Comprises routers, switches, and reliable internet connections that support stable, high-bandwidth video streams necessary for effective conferencing, especially in enterprise environments with high demand.
- Geography
- Western Europe: This region exhibits high adoption rates of video conferencing solutions driven by mature technological infrastructure, strong enterprise presence, and a rising culture of remote working practices.
- Nordic Countries: Known for advanced digital infrastructure and high technological readiness, these countries are early adopters of innovative conferencing solutions, emphasizing quality and integration with other digital platforms.
- Southern Europe: Adoption here is growing driven by increasing demands for remote collaboration, with a focus on cost-efficient, scalable conferencing solutions amid economic diversification efforts.
- Eastern Europe: This subregion demonstrates a rising demand for affordable, reliable conferencing solutions to support expanding small and medium enterprises (SMEs) and remote working trends.
Competitive Intelligence
The Europe Video Conferencing Market exhibits a highly competitive landscape characterized by the presence of several key global and regional players, including Zoom Video Communications, Microsoft Teams, Cisco WebEx, and Google Meet. Market concentration remains moderate, with the top five companies accounting for a substantial share of the market due to aggressive strategies and extensive product portfolios. Firms are emphasizing product innovation through feature enhancements such as AI-powered noise suppression, enhanced security protocols, and seamless integration across enterprise solutions to differentiate themselves. Strategic partnerships are common, particularly collaborations with technological providers and telecommunication firms, aimed at expanding service reach and improving user experience. Acquisition activities focus on consolidating expertise and expanding product offerings, with notable acquisitions by Cisco and Microsoft to augment their platform capabilities. Expansion strategies predominantly involve regional market penetrations and localized service customization to accommodate diverse European enterprises. Heavy R&D investments are directed at enhancing user interfaces, secure communication features, and scalable solutions, positioning firms to advance competitive advantage and sustain differentiation in a rapidly evolving industry.
Leading Company Profiles
The competitive landscape of the Europe Video Conferencing Market is characterized by innovative technology providers and established global players striving for market differentiation through strategic expansion, product diversification, and technological advancement. These companies are leveraging AI, cloud infrastructure, and enhanced security protocols to meet rising demand across various sectors, including corporate, educational, healthcare, and government. Their focus on customer-centric solutions and sustainable practices exemplifies their strategic priorities in consolidating market share and driving continuous growth in a highly dynamic environment.
- Zoom Video Communications
- Microsoft Corporation
- Cisco Systems
- Google LLC
- Logitech International
- Bloomberg L.P.
- Starleaf
- BlueJeans by Verizon
- Pexip Holding ASA
- Westford Technologies
Zoom Video Communications
Zoom offers a comprehensive suite of video conferencing solutions tailored to enterprise and SMB clients, emphasizing ease of use, reliability, and security, with ongoing investments in AI-enabled features and integrations to maintain market leadership.
Microsoft Corporation
Microsoft’s Teams platform continues to evolve as a core collaboration tool, integrating advanced video conferencing capabilities with productivity applications, while focusing on cloud-based seamless collaboration within the Microsoft 365 ecosystem.
Cisco Systems
Cisco’s Webex portfolio is known for its enterprise-grade security, scalability, and high-definition video quality, with strategic emphasis on AI-driven features, hybrid work solutions, and robust security protocols to support remote work trends.
Google LLC
Google Meet’s integration with Google Workspace, combined with investments in AI-powered features and user experience enhancements, positions it as a preferred cloud-based conferencing platform for educational and business sectors.
Logitech International
Specializing in hardware solutions, Logitech develops high-quality video conferencing hardware, including cameras, microphones, and collaboration devices, emphasizing ergonomic design, sustainability, and compatibility with leading software platforms.
Bloomberg L.P.
Bloomberg’s enterprise video solutions focus on secure, real-time communication tools tailored for financial and news sectors, offering high reliability and encryption, alongside tailored broadcasting and conferencing services for corporate clients.
Starleaf
Starleaf provides cloud video conferencing and enterprise communication solutions known for ease of use, secure integration into existing workflows, and scalable architecture, focusing on hybrid working models and global enterprise deployments.
BlueJeans by Verizon
BlueJeans specializes in interoperable cloud conferencing solutions with advanced analytics, AI features, and immersive meeting tools, supporting large enterprise and government clients focused on secure collaboration environments.
Pexip Holding ASA
Pexip offers flexible, scalable video conferencing and collaboration software with a focus on secure hybrid cloud integrations, emphasizing interoperability, customizability, and high security for enterprise clients across Europe.
Westford Technologies
Westford Technologies delivers innovative, customizable video collaboration solutions that leverage AI and machine learning, with a strategic focus on expanding digital transformation initiatives in public and private sector organizations.
Strategic Business Developments
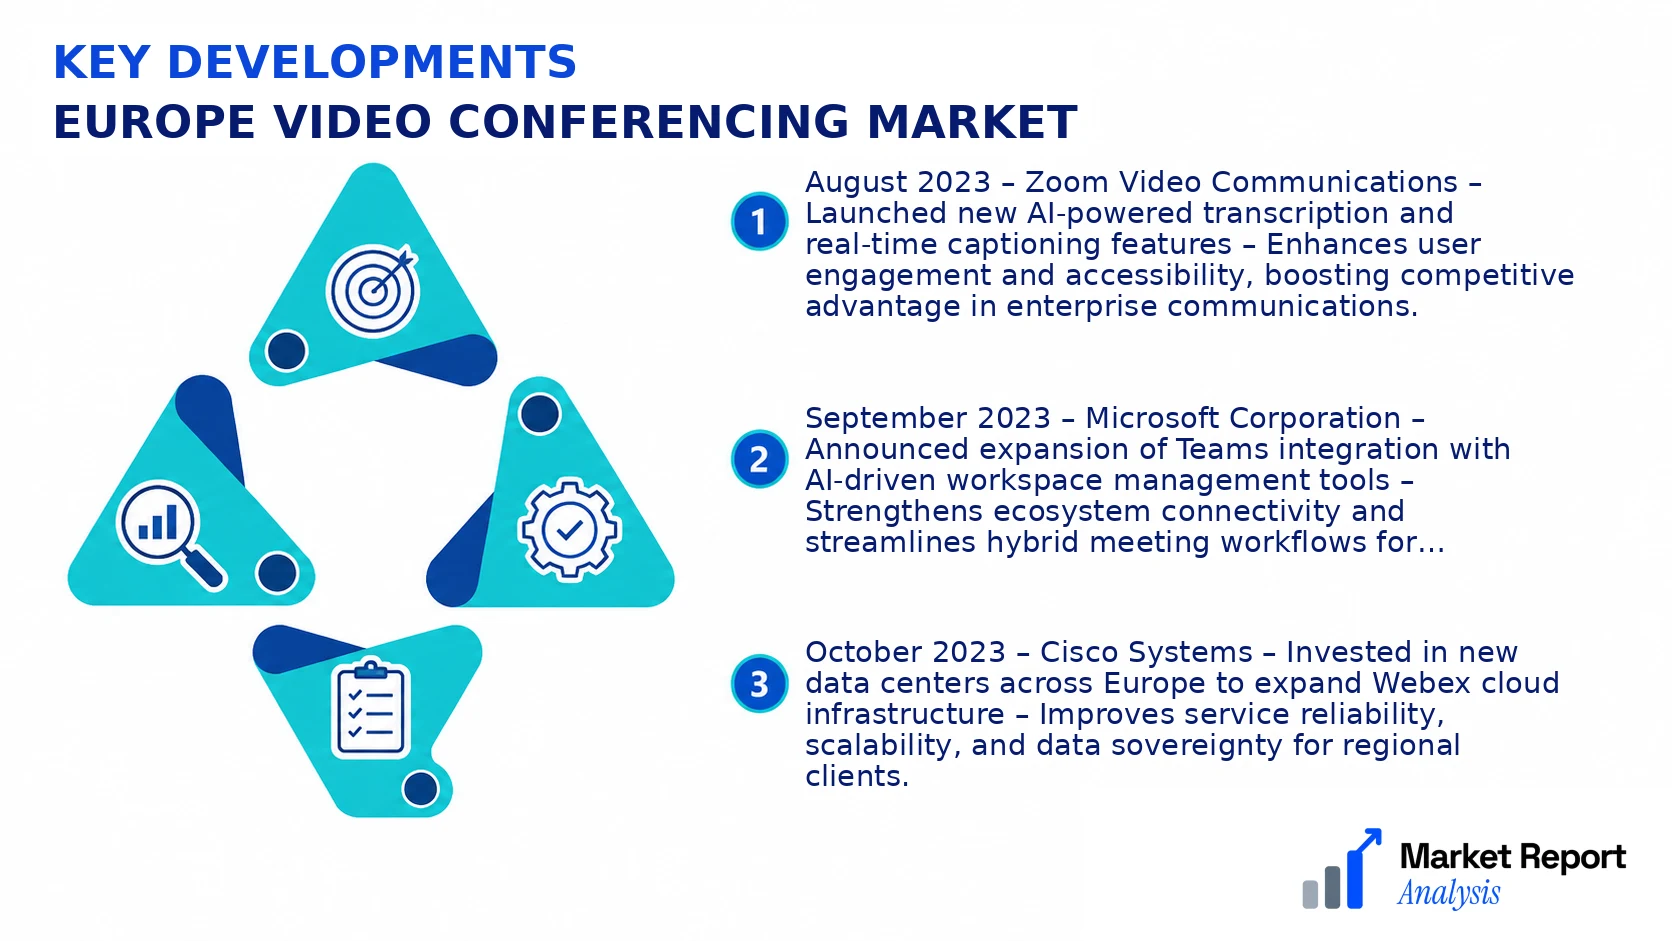
- August 2023 – Zoom Video Communications – Launched new AI-powered transcription and real-time captioning features – Enhances user engagement and accessibility, boosting competitive advantage in enterprise communications.
- September 2023 – Microsoft Corporation – Announced expansion of Teams integration with AI-driven workspace management tools – Strengthens ecosystem connectivity and streamlines hybrid meeting workflows for businesses.
- October 2023 – Cisco Systems – Invested in new data centers across Europe to expand Webex cloud infrastructure – Improves service reliability, scalability, and data sovereignty for regional clients.
- November 2023 – Google LLC – Rolled out new low-bandwidth mode in Google Meet, optimized for varied network conditions – Ensures high-quality experiences in diverse European connectivity environments.
- December 2023 – Logitech International – Unveiled new ultra-high-definition conference cameras with intelligent framing technology – Enhances remote meeting experience with better field-of-view and video quality capabilities.
Frequently Asked Questions
What is the Europe Video Conferencing Market?
The Europe Video Conferencing Market encompasses the industry involved in providing real-time video communication solutions across various sectors such as corporate, healthcare, education, and government within Europe. It includes hardware, software, and integrated platforms designed to facilitate remote communication and collaboration.
What is the current market size of Europe Video Conferencing Market?
As of 2026, the Europe Video Conferencing Market is valued at approximately USD 5.2 Billion, reflecting robust growth driven by increased adoption of remote working and online communication tools across diverse industries in the region.
What factors are driving the Europe Video Conferencing Market?
Market expansion is primarily fueled by rising demand for remote work solutions, advancements in technology such as AI and cloud integration, increasing adoption in healthcare for telemedicine, and government initiatives supporting digital communication infrastructure across Europe.
Which region dominates the Europe Video Conferencing Market?
Western Europe currently leads the market, with countries like Germany, the UK, and France exhibiting significant adoption rates due to their robust technological infrastructure and large corporate sectors adopting video conferencing solutions extensively.
Which segment is expected to grow the fastest?
The software segment is anticipated to witness the highest growth, driven by the proliferation of cloud-based solutions, AI-enhanced features, and the increasing preference for subscription-based models over traditional hardware
Who are the leading companies operating in the Europe Video Conferencing Market?
Key industry players include Zoom Video Communications, Microsoft Teams, Cisco Webex, and BlueJeans Network, which hold significant market shares due to their advanced features, reliable service, and extensive regional presence across Europe.
Analyst Perspective
The Europe Video Conferencing Market is poised for sustained growth through 2034, driven by digital transformation initiatives and the increasing adoption of hybrid work models. As the market matures, long-term prospects suggest a shift toward integrated, AI-driven, and secure conferencing solutions, creating ample opportunities for tech innovators and service providers. Regional growth potential remains high, especially as companies in Western and Northern Europe intensify their investment in remote collaboration tools to enhance productivity and reduce operational costs. Technological evolution entails enhanced video quality, advanced data encryption, and seamless integration with enterprise applications, which will be key to maintaining competitiveness. Investment priorities should focus on cybersecurity, user experience improvements, and cloud infrastructure expansion, as these are critical for addressing rising security concerns and user demands. Competitive intensity is expected to escalate with intensified vendor consolidation and market entry by new players, emphasizing differentiation through technological advancements. Ultimately, regional leaders that anticipate future trends and invest strategically in innovative solutions will secure a dominant market position in Europe’s dynamic landscape.
