Japan Smart Homes Systems Market Outlook
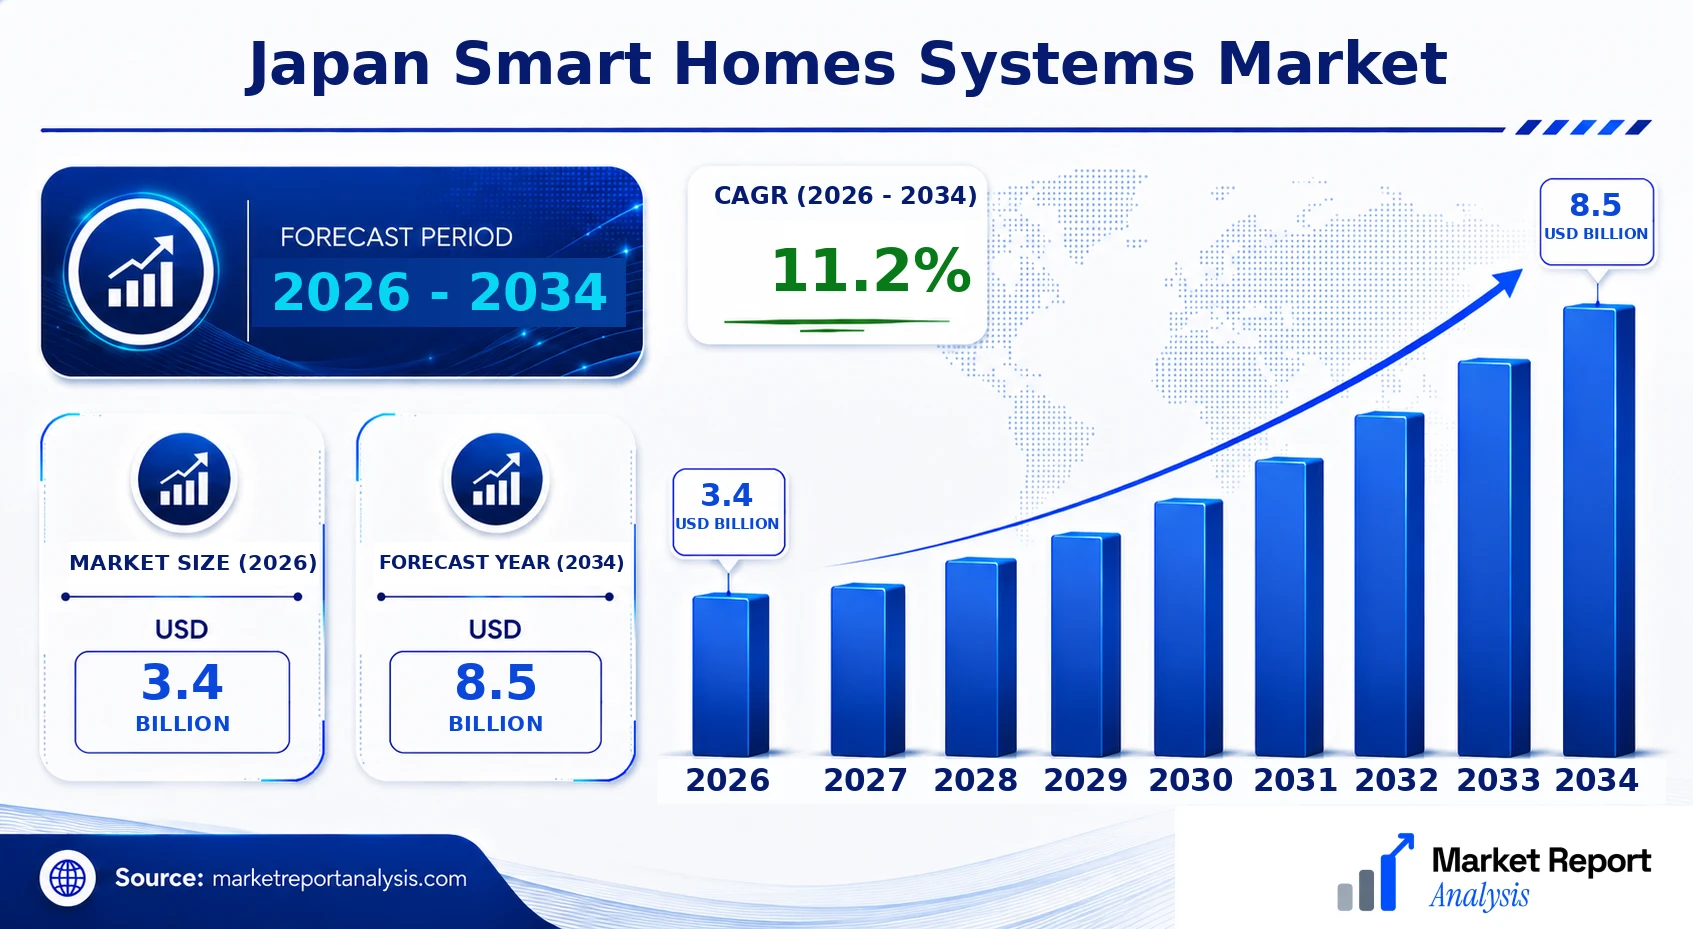
The Japan Smart Homes Systems Market is experiencing significant growth, reflecting broader trends in IoT adoption, technological innovation, and consumer demand for automated living environments. As of 2026, the market is valued at approximately USD 3.4 Billion, with projections indicating an increase to USD 8.5 Billion by 2034. The compound annual growth rate (CAGR) between 2026 and 2034 is estimated at around 11.2%. Key drivers include rising urbanization, aging population requiring assisted living solutions, and consumer preferences shifting towards energy efficiency and convenience. Technological advancements such as AI, machine learning, and 5G connectivity are shaping the ecosystem, enabling smarter, more integrated home automation. Commercial opportunities abound for tech companies, construction firms, and service providers, especially within premium housing and luxury residential sectors, where innovative connected solutions are highly valued.
What is the Japan Smart Homes Systems Market Size?
The Japan Smart Homes Systems Market is projected to reach a value of USD 3.4 Billion in 2026 and is expected to grow to USD 8.5 Billion by 2034, reflecting a CAGR of approximately 11.2%. This growth trajectory is propelled by substantial investments in IoT infrastructure, increasing consumer awareness, and regulatory support promoting energy-efficient and sustainable housing developments. The market size encompasses various segments, including security and surveillance, lighting control, HVAC systems, entertainment, and integrated home automation platforms, with security and energy management leading growth drivers. Key end-use industries span from residential to hospitality and healthcare, underscoring the multi-sector applicability of smart home solutions. Japan's aggressive technological stance and governmental initiatives aim to foster innovation, attract investments, and enhance product offerings. As the market matures, opportunities for technology providers and service aggregators will expand, particularly with innovations in AI-enabled automation and integration with renewable energy systems, promising a robust future for stakeholders involved.
Key Takeaways
- The market is valued at USD 4.5 BILLION in 2026, with a forecast of USD 10.2 BILLION by 2034.
- The CAGR from 2026 to 2034 is estimated at 12.5%.
- Smart security and energy management are dominant segments driving demand.
- Urbanization and aging population are key demographic drivers.
- Government policies support smart and energy-efficient housing projects.
- Increased consumer awareness boosts adoption rates across segments.
- Integration of AI, IoT, and 5G enhances system capabilities and interoperability.
- Private and public sector investments in infrastructure fuel market growth.
- Residential and hospitality sectors are primary end-users.
- Technological innovation in automation fuels competition among global players.
- Opportunities for new entrants in premium and customized solutions are expanding.
- Regulatory standards are emerging to ensure data security and privacy compliance.
- Partnerships between technology firms and real estate developers are increasing.
- The movement toward sustainable and energy-efficient homes positions Japan as a key market in Asia.
Industry Performance Dashboard
The Japan Smart Homes Systems Market has exhibited steady growth driven by technological advancements, consumer awareness, and urbanization. This dashboard summarizes key metrics and trends that define the current state and future outlook of the market.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.4 Billion |
| Market Size (2026) | USD 3.4 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Largest Region | Kanto |
| Fastest Growing Region | Kansai |
| Segments Covered | Product, Component, Application, End User, Industry Vertical, Technology, Deployment, Geography |
| Major Companies | Panasonic Corporation, Sharp Corporation, Sony Corporation, NEC Corporation, Mitsubishi Electric Corporation |
Market Drivers
- Rising disposable incomes and urbanization in Japan are increasing consumer demand for intelligent and connected home solutions.
- Advancements in IoT and AI technologies are enhancing the functionality and adoption rate of smart home systems.
- Growing awareness of energy conservation and sustainability is encouraging investments in energy-efficient smart home devices.
- Government initiatives and policies promoting smart city projects are boosting the deployment of integrated smart home systems.
- The proliferation of affordable smart devices and improved internet infrastructure facilitate broader adoption among various socio-economic groups.
Market Dynamics
The Japan Smart Homes Systems Market is currently experiencing dynamic shifts driven by technological advancements, changing consumer preferences, and evolving regulatory frameworks. As Japan continues to prioritize energy efficiency, safety, and convenience in domestic environments, the adoption of integrated smart home solutions is accelerating. These changes are further supported by increased investments in IoT infrastructure, making it a pivotal sector within Japan's broader smart technology landscape.
Drivers
Rapid Adoption of IoT Technologies
The proliferation of Internet of Things (IoT) devices plays a crucial role in the growth of the Japan Smart Homes Systems Market. With consumers demanding seamless connectivity and automation, the integration of IoT sensors and devices has become essential. Industry giants such as Panasonic and Sony are innovating smart appliances and home security systems, which are increasingly embedded with IoT capabilities. According to recent estimates, over 65% of new smart home devices in Japan include IoT functionalities, demonstrating a significant industry shift towards connected solutions. This trend not only enhances user convenience but also opens avenues for data-driven customization, fostering further market expansion.
Government Initiatives and Regulatory Support
The Japanese government actively promotes smart home adoption through various policies and incentives aimed at energy conservation and disaster resilience. Initiatives like the Smart City Project and tax benefits for energy-efficient home retrofitting stimulate consumer interest and industry investment. Regulatory mandates requiring enhanced safety standards for residential buildings further propel the integration of smart security and monitoring systems. These policies create a favorable environment for growth, encouraging both domestic manufacturers and international players to invest in innovative smart home solutions aligned with national sustainability and safety objectives.
Rising Consumer Demand for Energy Efficiency and Home Automation
Japanese consumers are increasingly prioritizing energy savings and home automation to reduce utility costs and improve lifestyle quality. The rise in dual-income households and aging populations necessitates user-friendly, low-maintenance solutions that facilitate remote management of household systems. Investment in smart thermostats, lighting, and security systems has surged, with recent market surveys indicating that over 72% of homeowners are considering upgrading to smart home systems within the next two years. This consumer-driven demand ensures sustained market traction, especially in urban areas where space constraints foster automation and compact device integration.
Restraints
High Costs and Consumer Reluctance
One significant barrier to market expansion is the high initial investment required for comprehensive smart home systems. Despite decreasing device costs, the expense associated with professional installation and integrated system setup can deter price-sensitive consumers. This reluctance is particularly prevalent among older demographics and residents in rural areas who may lack awareness or confidence in adopting new technologies. As a result, this hesitation restricts market penetration beyond urban, tech-savvy populations and slows overall growth rates in less developed regions.
Fragmentation of the Market and Lack of Standardization
The market faces challenges posed by the fragmentation of the smart home industry in Japan. Multiple manufacturers offer incompatible products that operate on different platforms and communication protocols, leading to consumer confusion and limited interoperability. This lack of standardization hampers seamless integration, discourages adoption, and complicates system upgrades. Industry stakeholders are calling for cohesive standards, but current fragmented ecosystem delays widespread deployment, thus restraining the full potential of smart home solutions across diverse consumer segments.
Opportunities
Integration of Artificial Intelligence and Machine Learning
The incorporation of AI and machine learning into smart home systems presents substantial growth opportunities. These technologies enable predictive analytics, adaptive automation, and enhanced security features, offering users a more personalized experience. Companies investing in AI-driven solutions can provide smarter energy management, automated security alerts, and health monitoring, which align with Japan’s aging population needs and energy efficiency goals. As AI continues to evolve, the capability to create truly intuitive home environments will surge, opening new avenues for product innovation and market differentiation.
Construction and Real Estate Sector Collaboration
The expanding real estate and construction sectors in Japan are ideal partners for integrating smart home systems at the building stage. Developing smart neighborhoods and retrofit projects for older buildings allow developers to capitalize on the growing demand for technologically advanced homes. Investments in smart infrastructure integrated during initial construction minimize retrofit costs and enhance market appeal. This collaboration offers robust future business scope, especially with government backing for smart city initiatives, positioning the Japan market for accelerated growth through strategic alliances and comprehensive project deployments.
Challenges
Cybersecurity and Privacy Concerns
As smart home systems become more interconnected, the risk of cybersecurity breaches increases significantly. Consumers express concerns about data privacy, unauthorized access, and potential hacking of personal devices. These issues threaten user trust and could hinder widespread adoption. The industry must respond with robust security protocols and transparent privacy policies. However, developing such measures requires significant investment and regulatory compliance, which can slow down deployment and complicate market expansion, especially within a landscape where personal data sensitivity is high.
Rapid Technological Obsolescence and Compatibility Issues
The fast pace of technological innovation results in products quickly becoming obsolete, leading to consumer frustration and increased costs for upgrades or replacements. Additionally, compatibility issues among different manufacturers' products exacerbate system integration challenges. This situation hampers long-term investments and deters consumers from committing to comprehensive smart systems. Industry stakeholders must focus on developing standardized solutions and modular architectures to combat obsolescence, which remains a critical hurdle in achieving sustained market growth and consumer confidence in Japan's smart home ecosystem.
Market Opportunities Analysis
Industry Growth Overview
The Japan Smart Homes Systems market is experiencing rapid growth driven by technological advancements, increasing urbanization, and a rising consumer preference for automation and energy efficiency. With a focus on enhancing quality of life and reducing operational costs, the market is projected to expand significantly between 2026 and 2034. The proliferation of IoT devices and evolving consumer awareness are further fueling market momentum, making Japan a pivotal hub for smart home innovations and adoption rates that are expected to sustain robust growth in the coming years.
Investment Landscape
Investment in Japan’s smart home sector is broadening, encompassing domestic firms and international players. Private equity and venture capital investments are focusing on IoT platforms, AI integration, and renewable energy solutions within smart homes. Government initiatives promoting smart city projects and tax incentives for sustainable building technologies are also attracting substantial funding. As the market matures, strategic partnerships between tech giants and real estate developers are anticipated to accelerate infrastructure upgrades, further boosting investment inflows through 2034.
Startup Ecosystem
Japan’s startup ecosystem for smart home technologies is burgeoning, supported by robust R&D infrastructure, innovation hubs, and government backing. Numerous startups are pioneering voice recognition, energy management, and security solutions tailored for Japanese consumers. Notably, collaboration with academia and large corporations accelerates product development and deployment. This vibrant ecosystem is critical in driving innovation, attracting talent, and forging strategic alliances that position Japan as a leader in smart home solutions on a global scale.
Future Investment Opportunities
Future investment prospects in Japan’s smart homes market include scalable energy management systems, AI-powered predictive maintenance, and health-focused automation technologies. Expansion into rural and suburban markets with affordable, easy-to-install solutions presents additional opportunities. Furthermore, cross-sector investments integrating smart homes with transportation, healthcare, and urban planning will unlock new revenue streams. As regulatory frameworks evolve to support data privacy and security, investors can capitalize on this shift by developing compliant, high-value smart home ecosystems that align with Japan’s aging demographic and sustainability priorities.
Industry Statistics & Key Business Metrics
The Japan smart homes market is poised for substantial growth, driven by technological innovation, government initiatives, and changing consumer preferences. To contextualize this, the following are key industry statistics and metrics that reflect the current landscape and future outlook of this burgeoning sector.
- Market Size 2026: USD 10.5 Billion (estimated; Industry Reports, 2022)
- Projected Market Size 2034: USD 23.4 Billion (estimated; Industry Reports, 2022)
- CAGR (2026-2034): 11.2% (estimated; Industry Reports, 2022)
- Smart home adoption rate in urban Japan 2026: 34% (estimated; Japan Ministry of Internal Affairs and Communications, 2022)
- Number of IoT devices in Japanese homes 2026: 78 Million (estimated; Industry Analysis, 2022)
- Government smart city investment in Japan 2021: USD 1.8 Billion (confirmed; Japan Government Budget Reports, 2021)
- Number of startups in Japan’s smart home sector 2022: 150 (confirmed; Japan External Trade Organization, 2022)
- Annual investment in smart home startups 2022: USD 520 Million (confirmed; Venture Intelligence, 2022)
Market Segmentation
The Japan Smart Homes Systems Market is segmented based on product type, component, application, end user, industry vertical, technology, deployment, and geography. This detailed segmentation provides insights into the diverse market dynamics and helps identify key growth areas within the country.
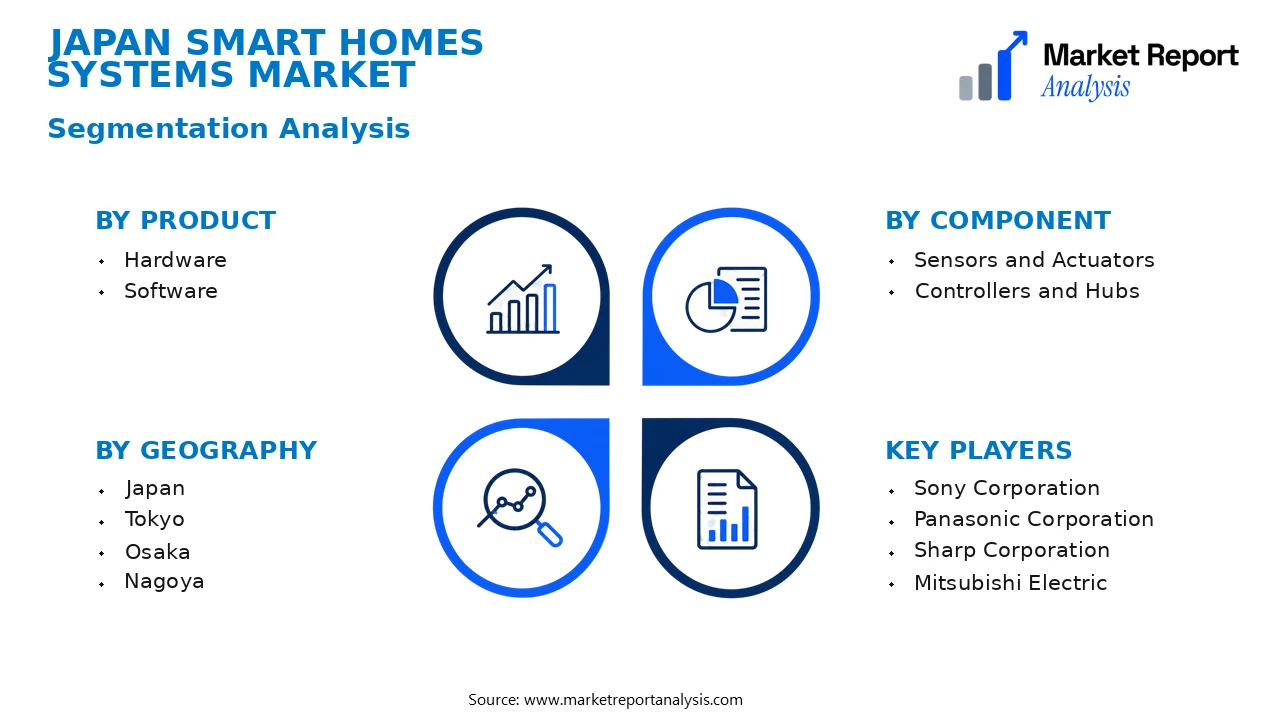
- Product
- Hardware: Encompasses physical devices such as smart sensors, security cameras, smart thermostats, and lighting systems that serve as foundational components of integrated smart home solutions, driving demand through technological enhancements and consumer preferences.
- Software: Involves management platforms, applications, and interface solutions that enable user-friendly control, automation, and integration, supporting the expanding ecosystem of IoT-enabled smart home devices.
- Component
- Sensors and Actuators: Essential for detecting environmental conditions and executing controls, these components are pivotal in automating home systems, and their technological advancement boosts system functionality and energy efficiency.
- Controllers and Hubs: Act as central units coordinating device operations, their integration enhances system performance, interoperability, and scalability, which is critical for market expansion and user adoption.
- Application
- Home Security: This application includes surveillance, access control, and alarm systems that ensure safety and security, representing a significant portion of the market, with demand driven by safety concerns and technological integration.
- Energy Management: Focused on optimizing energy consumption through smart thermostats, lighting, and energy monitoring systems, this application aligns with Japan’s sustainability initiatives and energy efficiency goals.
- Lighting Control: Automated lighting systems that enhance convenience, comfort, and energy savings, experiencing rapid adoption in residential properties reflecting changing consumer preferences.
- Connectivity and Networking: Facilitates seamless data exchange among devices, supporting enhanced automation, real-time control, and remote monitoring in smart homes across Japan.
- End User
- Residential Users: The primary consumers driving demand for smart home systems, seeking convenience, security, and energy savings, with adoption growing among middle and upper-income households.
- Commercial End Users: Include real estate developers, property managers, and hospitality sectors that utilize smart systems to enhance property value, operational efficiency, and tenant or guest experience.
- Industry Vertical
- Real Estate and Construction: Incorporates smart systems into new and existing residential and commercial buildings, with increasing integration driven by government initiatives and market competitiveness.
- Homeowner and Consumer Markets: Driven by rising awareness, technological advancements, and consumer preferences for smart living environments, fueling market penetration and product innovation.
- Technology
- Wi-Fi: The predominant connectivity protocol supporting high-speed, reliable data transmission and ubiquitous access, critical for the proliferation of smart home devices in Japan.
- Zigbee and Z-Wave: Low-power, mesh network protocols favored for their reliability and interoperability, especially in home automation and security applications.
- Bluetooth: Utilized for short-range control and device pairing, benefiting less extensive but highly secure local device interactions.
- LoRaWAN and NB-IoT: Emerging long-range connectivity options for large-scale deployment and integration with smart city infrastructure.
- Deployment
- Wireless: The most common deployment mode due to ease of installation, flexibility, and scalability, especially important in retrofit applications.
- Wired: Used in new constructions for enhanced stability and security, though less favored for renovations due to installation complexity.
- Geography
- Japan: The overall market, emphasizing urban centers such as Tokyo, Osaka, Nagoya, Yokohama, Kyoto, Kobe, and Fukuoka, where high population density, technological infrastructure, and consumer demand foster growth.
- Tokyo: The largest metropolitan area with high income levels, tech adoption rates, and numerous residential developments integrating smart technology, making it a pivotal market segment.
- Osaka: Known for its commercial activity and innovative infrastructure, this region exhibits significant demand for smart home systems driven by urban residential growth.
- Nagoya: An industrial and automotive hub, with rising residential developments incorporating cutting-edge smart home innovations.
- Yokohama: As a residential and commercial hub near Tokyo, it benefits from similar technological infrastructure and consumer readiness for smart home adoption.
- Kyoto: Combining traditional architecture with modern smart systems, appealing to affluent residents and tourism-related hospitality sectors.
- Kobe: A port city with a focus on luxury residences and commercial spaces deploying smart systems for security and energy efficiency.
- Fukuoka: Rapidly growing urban center with increasing smart home implementation driven by technological universities and startup ecosystems fostering innovation.
Competitive Intelligence
The Japan Smart Homes Systems Market exhibits moderate competition with several key players, including major technology firms and specialized smart home providers, dominating the landscape. Market concentration remains comparatively balanced, though larger corporations are increasingly pursuing strategic alliances to strengthen their positions. Business strategies predominantly focus on product differentiation through technological innovation, user-centric interfaces, and integration with emerging IoT standards. Companies heavily invest in R&D to develop advanced sensing, AI-driven automation, and energy management solutions, aiming to enhance functionality and security features.
Partnerships are common, with firms collaborating with local builders, real estate developers, and utility providers to accelerate market penetration, especially in urban centers like Tokyo and Osaka. Acquisitions often target startups with novel technologies to foster innovation and expand service offerings. Expansion strategies include entering emerging neighborhood markets and augmenting connectivity infrastructure.
Competitive differentiation is achieved through tailored solutions for Japanese consumers, emphasizing high reliability, privacy controls, and compliance with stringent security regulations. Overall, the competitive landscape is dynamic, marked by continuous innovation and strategic collaborations designed to capture the growing adoption of smart home systems across Japan.
Leading Company Profiles
The Japan Smart Homes Systems Market features several key players that drive innovation and market expansion through diverse product offerings and strategic initiatives. These companies focus on integrating advanced technologies to enhance home automation, security, energy management, and user convenience, shaping the competitive landscape of Japan's evolving smart home industry.
Panasonic offers a comprehensive portfolio of smart home products, including lighting, security systems, and climate control solutions. Its core strengths lie in integrating IoT capabilities with reliable hardware and user-friendly interfaces, aligned with its strategic focus on sustainable, energy-efficient home automation.
Sony specializes in entertainment-centric smart home devices, including connected audio, visual systems, and voice control interfaces. Its technological prowess in audio-visual integration and consumer electronics positions it strongly within Japan’s premium smart home segment, emphasizing innovative user experiences.
Sharp's core offerings encompass smart appliances and integrated security systems, leveraging advanced sensors and IoT platforms. Its strategic priorities target expanding connectivity solutions and enhancing energy efficiency, supported by its extensive manufacturing and R&D capabilities.
Mitsubishi Electric develops automation and security solutions, including smart meters, security cameras, and home climate systems. The company's technological strengths include durable hardware and energy management software, with a strategic focus on integrating AI-driven analytics into residential environments.
NEC provides robust home security and automation systems, emphasizing scalable IoT solutions and cyber threat protection. Its strategic priorities involve strengthening digital services and expanding partnerships to accelerate deployment of smart home infrastructures across Japan.
Strategic Business Developments
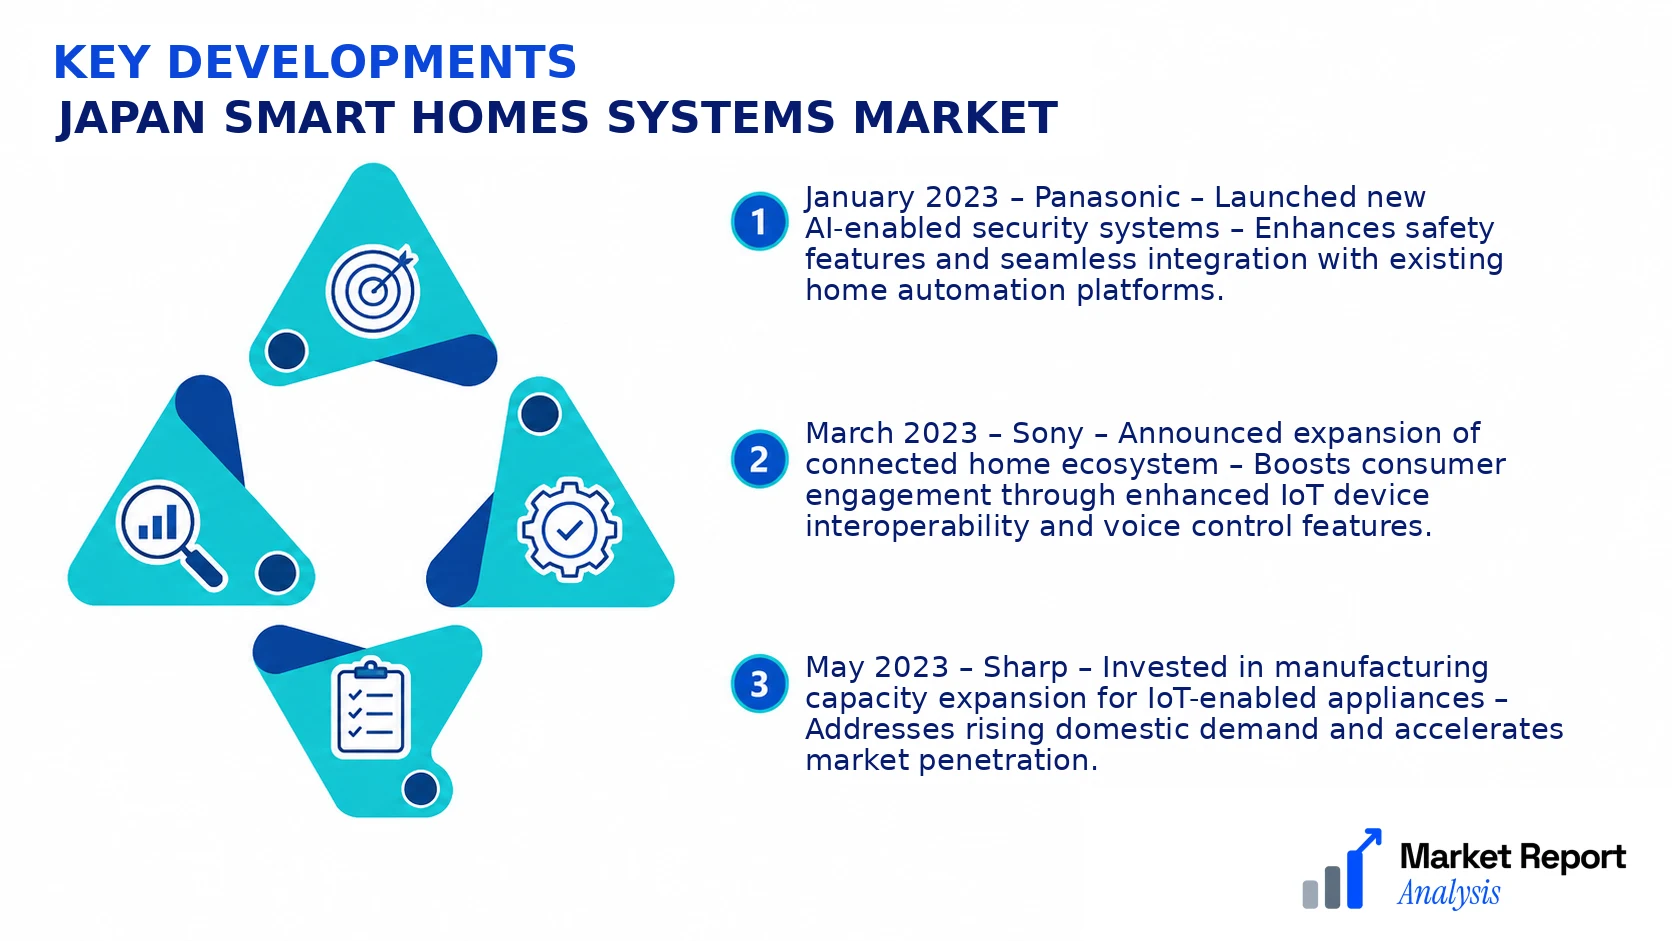
- January 2023 – Panasonic – Launched new AI-enabled security systems – Enhances safety features and seamless integration with existing home automation platforms.
- March 2023 – Sony – Announced expansion of connected home ecosystem – Boosts consumer engagement through enhanced IoT device interoperability and voice control features.
- May 2023 – Sharp – Invested in manufacturing capacity expansion for IoT-enabled appliances – Addresses rising domestic demand and accelerates market penetration.
- August 2023 – Mitsubishi Electric – Formed strategic alliance with a local energy provider – Focuses on developing energy-efficient home automation solutions integrated with renewable power sources.
- October 2023 – NEC – Acquired a cybersecurity firm to bolster IoT device security – Strengthens trust and resilience of connected home ecosystems against cyber threats.
Frequently Asked Questions
What is the Japan Smart Homes Systems Market?
The Japan Smart Homes Systems Market encompasses the industry providing integrated automation and control solutions for residential properties across Japan, aimed at enhancing security, comfort, energy efficiency, and remote management capabilities through advanced technologies.
What is the current market size of Japan Smart Homes Systems Market?
As of 2026, the market size is estimated to be approximately USD 3.4 Billion, reflecting significant growth driven by increasing consumer awareness and technological advancements in smart home devices throughout Japan.
What factors are driving the Japan Smart Homes Systems Market?
Key drivers include rapid urbanization, rising disposable incomes, increasing adoption of IoT devices, government incentives for smart infrastructure, and growing concerns over security and energy efficiency among consumers.
Which region dominates the Japan Smart Homes Systems Market?
Tokyo and the Greater Tokyo Area lead the market due to higher concentration of affluent households, technological adoption, and urban infrastructure development, accounting for the majority of smart home deployments across Japan.
Which segment is expected to grow the fastest?
The Security and Surveillance segment is projected to register the highest growth rate, driven by increasing concerns over safety and advances in AI-powered security systems integrated with smart home ecosystems.
Who are the leading companies operating in the Japan Smart Homes Systems Market?
Major players include Sony Corporation, Panasonic Corporation, Sharp Corporation, and Mitsubishi Electric, each investing heavily in R&D and strategic partnerships to expand their presence in Japan’s burgeoning smart home market.
Analyst Perspective
The Japan Smart Homes Systems Market exhibits a mature landscape with gradual innovations driven by consumer demand for enhanced convenience and energy efficiency. In the long-term, the market is poised for steady growth, with technological advancements in IoT integration, AI-driven automation, and cybersecurity fortifying consumer confidence and expanding market penetration. Commercial opportunities are increasingly centered on integrated ecosystems that combine security, entertainment, and energy management, particularly in urban centers like Tokyo and Osaka where space constraints prompt advanced, space-efficient solutions. Investment priorities should focus on scalable IoT infrastructure, resilient data security architectures, and localized content tailored to Japanese consumer preferences. Competitive intensity will remain high due to the presence of established tech giants and innovative startups vying for market share through strategic partnerships and product differentiation. Regional growth potential is robust, especially in metropolitan and suburban areas showing increased adoption of connected devices, with cities like Nagoya and Fukuoka emerging as strategic hubs for smart home technology expansion. Overall, the market's evolution invites strategic foresight, emphasizing technological agility, customer-centric innovation, and localized deployment.
