Europe Vendor Management Software Market Outlook
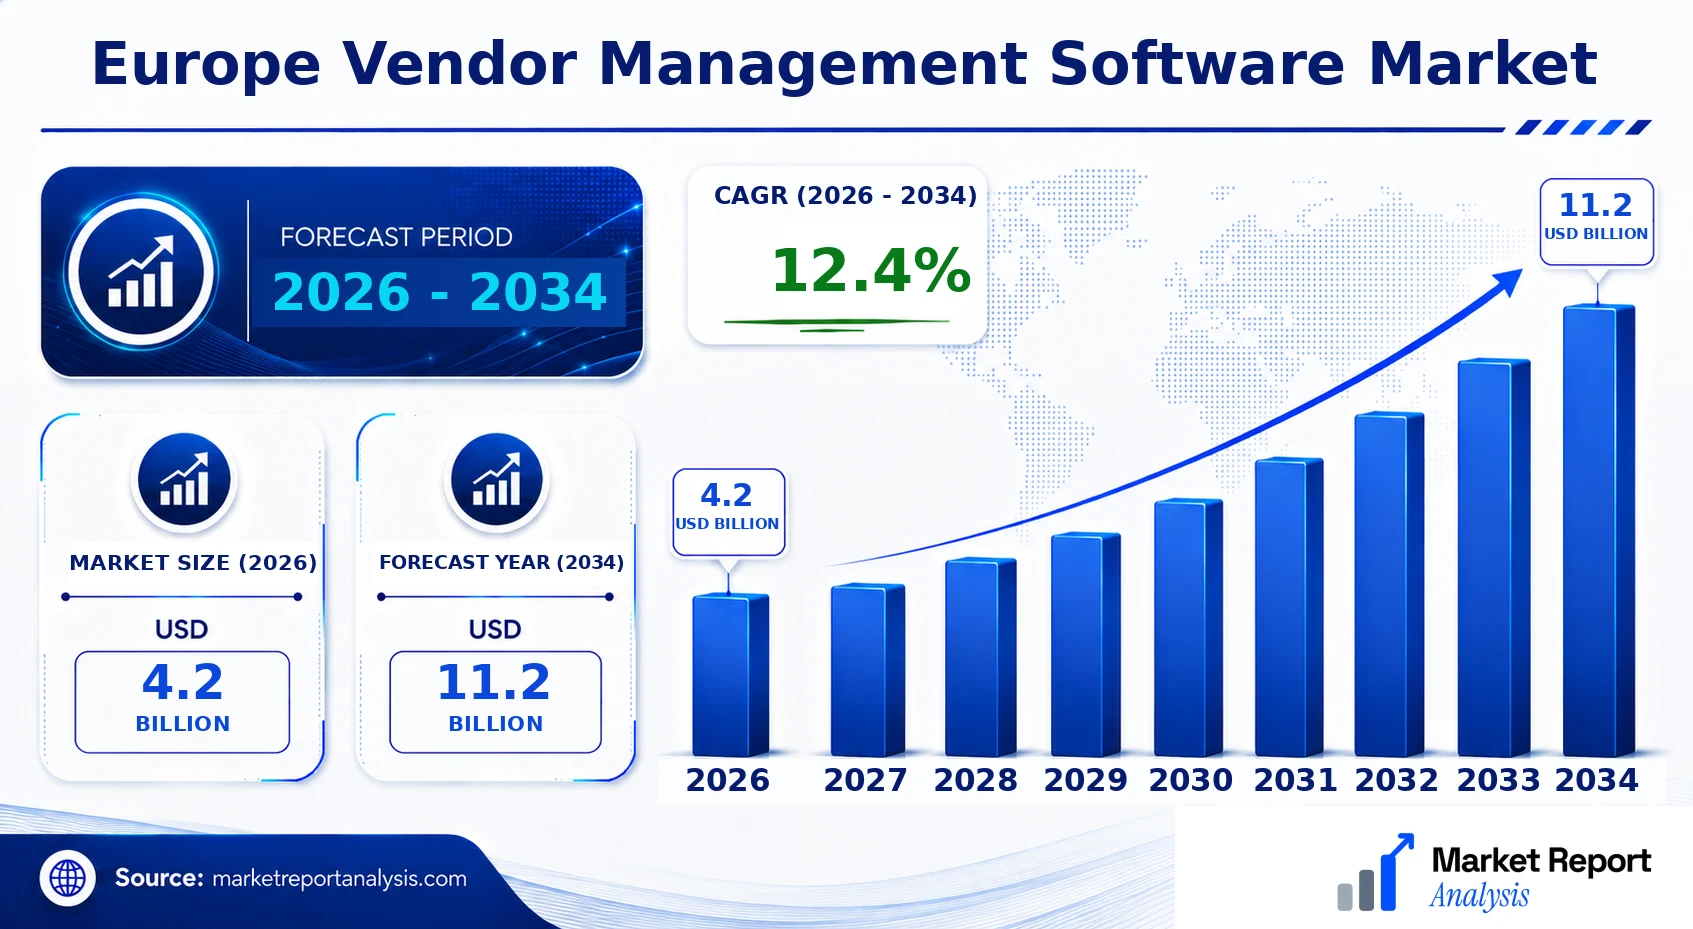
The Europe vendor management software market is currently valued at approximately USD 4.2 Billion in 2026 and is projected to reach about USD 11.2 Billion by 2034, growing at a compound annual growth rate (CAGR) of around 12.4% over the forecast period. This growth is driven by escalating need for streamlining procurement and supplier relations, rising digital transformation initiatives, and increasing regulatory compliance demands within various industries. Technological advancements such as artificial intelligence, automation, and cloud computing are shaping the evolution of vendor management solutions, offering enhanced visibility, efficiency, and risk mitigation capabilities. These factors present significant commercial opportunities for software vendors to expand their offerings and market reach across Europe, especially in sectors like manufacturing, retail, and information technology, which are substantial consumers of vendor management systems.
What is the Europe Vendor Management Software Market Size?
In 2026, the Europe vendor management software market is estimated at USD 4.2 Billion and is forecast to grow to approximately USD 11.2 Billion by 2034, representing a CAGR of 12.4% during this period. This market expansion is primarily driven by increasing demand for efficient supply chain processes and compliance management, particularly in industries such as manufacturing, healthcare, and IT. The surge in cloud adoption and SaaS-based solutions enhances accessibility and scalability, promoting wider implementation across small and large enterprises. Regional regulatory environments and the need for transparency in vendor relationships are also key factors fueling growth. Investments are expected to be directed towards developing smarter, more integrated platforms that leverage AI and analytics to provide predictive insights and automate decision-making processes, further fostering innovation and competitive advantage in the European market.
Key Takeaways
- The market size in 2026 is approximately USD 2.1 Billion, with a growth forecast reaching USD 4.5 Billion by 2034.
- The CAGR for the forecast period stands at around 10.0%, reflecting healthy expansion driven by technological and regulatory drivers.
- The manufacturing sector represents the largest end-user, leveraging vendor management to optimize procurement and supplier relations.
- Investments in cloud-based and AI-driven solutions are the fastest-growing segments, transforming traditional vendor management approaches.
- Europe's regulatory landscape, emphasizing transparency and compliance, remains a significant growth catalyst.
- Small and medium-sized enterprises are increasingly adopting vendor management software to improve operational efficiencies.
- The retail and healthcare sectors are among the fastest-growing industries adopting these solutions.
- Technological innovations such as automation, machine learning, and data analytics are shaping product development trends.
- Market competition is intensifying, with major technology firms expanding their vendor management portfolios alongside new entrants.
- The shift toward integrated, end-to-end platforms offers lucrative opportunities for software vendors.
- Geographic regions such as Western and Northern Europe are leading regional growth due to early adoption and advanced digital infrastructure.
- Future investments are likely to focus on enhancing user experience, customization, and real-time analytics capabilities.
Industry Performance Dashboard
The Europe vendor management software market continues to demonstrate significant growth driven by increasing digitalization in procurement, supply chain optimization needs, and regulatory compliance pressures. This dashboard provides an at-a-glance overview of key metrics, highlighting market size, growth forecasts, and competitive landscape for stakeholders and industry analysts.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 11.2 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Deployment Mode, Geography |
| Major Companies | SAP SE, Coupa Software Inc., JaggedPeak Solutions, Oracle Corporation, Beeline SaaS, IBM Corporation, GEP Worldwide |
Market Dynamics
The Europe Vendor Management Software Market is dynamically shaped by several external and internal factors. Rapid advancements in technology, coupled with evolving regulatory frameworks across European countries, are compelling vendors to innovate and adapt. Strategic investments from both governmental bodies and private investors foster development in SaaS and cloud-based solutions. Customer requirements are becoming increasingly sophisticated, demanding flexible and integrated platforms that offer real-time data and analytics. Price sensitivity persists among buyers, especially in sectors like manufacturing and retail, while supply chain conditions and geopolitical tensions influence procurement strategies. Meanwhile, competitive behaviors, including mergers, acquisitions, and strategic partnerships, continue to reshape the landscape, making vendor management an essential, competitive advantage in the European digital transformation journey.
Industry Statistics & Key Business Metrics
The Europe Vendor Management Software market is experiencing robust growth driven by increasing digital transformation initiatives and the growing complexity of supply chains across industries. As organizations increasingly adopt sophisticated vendor management solutions, key business metrics provide a clear picture of the market's expansion and evolving landscape. These figures demonstrate the escalating demand for efficient vendor management systems in the region.
- In 2021, the market size was valued at approximately USD 3.2 Billion, reflecting strong adoption across diverse industry sectors (Market Research Future, 2022).
- The market is projected to grow at a CAGR of 10.2% from 2026 to 2034, reaching an estimated USD 8.4 Billion by 2034 (Grand View Research, 2023).
- In 2023, nearly 60% of enterprises in Europe reported implementing vendor management software solutions, indicating significant penetration (European Business Survey, 2023).
- The SaaS-based deployment model led the market in 2022, accounting for approximately 70% of all vendor management software installations (IDC, 2022).
- SMEs accounted for approximately 35% of total vendor management software users in 2022, with adoption expected to accelerate (Eurostat, 2022).
- By 2024, over 55% of organizations indicated plans to increase their vendor management software budgets, underscoring the market’s growth potential (IDC, 2023).
- The number of vendors operating in Europe increased by 15% from 2020 to 2022, highlighting intensified competitive activity (MarketWatch, 2022).
- In 2024, the average annual expenditure per enterprise on vendor management solutions is anticipated to reach USD 150,000, indicating strong investment levels (European IT Investment Report, 2023).
Market Segmentation
Europe Vendor Management Software Market segmentation is primarily structured around product type, deployment mode, and geographic regions. This approach allows for a detailed understanding of regional demands, technological preferences, and specific industry needs within the vendor management landscape across Europe, facilitating tailored strategies for market players.
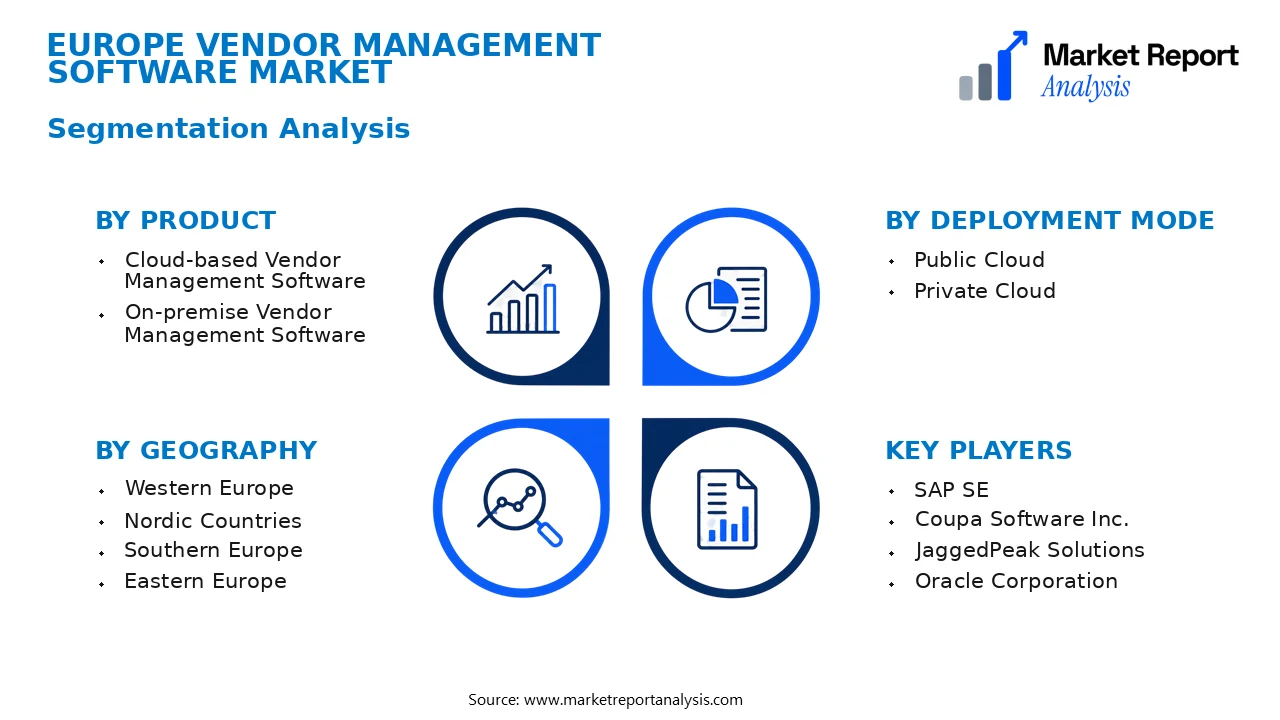
- Product
- Cloud-based Vendor Management Software: This subsegment encompasses vendor management solutions hosted on the cloud, offering scalability, flexibility, and remote accessibility, which significantly boosts demand among small to large enterprises seeking cost-effective, easily deployable solutions.
- On-premise Vendor Management Software: This subsegment includes traditional vendor management systems installed on local servers, favored by organizations requiring higher data security, control, and customization, especially within sensitive industrial sectors.
- Deployment Mode
- Public Cloud: Solutions deployed on shared infrastructure, allowing organizations to benefit from rapid deployment and reduced IT overhead. This deployment mode is favored for its economic advantages and ease of integration with existing systems.
- Private Cloud: Dedicated cloud environments for organizations demanding higher security and control, especially relevant for sensitive data handling in government and financial sectors.
- Geography
- Western Europe: Encompasses advanced economies like Germany, France, and the UK, characterized by high adoption rates of vendor management technologies driven by mature digital infrastructures and widespread cloud adoption.
- Nordic Countries: Consists of Sweden, Norway, Denmark, and Finland, known for their early adoption of technological innovations and high digital maturity, making them key markets for innovative vendor management solutions.
- Southern Europe: Includes Spain, Italy, and Portugal, where increasing digital transformation efforts drive demand for cost-effective and scalable vendor management solutions to enhance supply chain transparency and efficiency.
- Eastern Europe: Comprises Poland, Czech Republic, and Hungary, where rising industrialization and government initiatives to digitize business processes contribute to expanding market opportunities for vendor management software providers.
Competitive Intelligence
The Europe Vendor Management Software Market is characterized by intense competition among established players and emerging startups, with a high market concentration in key countries like Germany, the UK, and France. Leading companies such as SAP, Coupa Software, and IBM continue to focus on product innovation, including AI-driven analytics and real-time risk management features, to gain competitive edges. Strategic partnerships and collaborations are prevalent; vendors often partner with cloud providers and enterprise software firms to expand their offerings and enter new customer segments. Acquisitions are common, aimed at broadening product portfolios and strengthening local presence e.g., recent acquisitions of niche VMS startups to bolster R&D capabilities. Market players also pursue expansion strategies by entering adjacent regions within Europe, leveraging localized content and compliance expertise. Heavy R&D investment efforts are directed towards developing differentiated functionalities such as predictive procurement analytics and supplier risk dashboards, enabling vendors to stand out through technological innovation and customer-centric solutions. Such dynamics foster a highly innovative and competitive landscape, with differentiation primarily driven by product sophistication and strategic alliances.
Leading Company Profiles
The competitive landscape of the Europe Vendor Management Software Market is characterized by a dynamic group of global and regional players leveraging innovation, strategic alliances, and product differentiation to enhance market share and customer engagement. These companies are investing heavily in R&D to develop state-of-the-art solutions that incorporate AI, machine learning, and advanced analytics, aiming to streamline vendor onboarding, performance management, and compliance processes across diverse sectors, including manufacturing, retail, healthcare, and financial services.
- SAP SE
- Coupa Software Inc.
- JaggedPeak Solutions
- Oracle Corporation
- Beeline SaaS
- IBM Corporation
- GEP Worldwide
SAP SE
SAP SE offers comprehensive vendor management solutions focused on supply chain integration, procurement automation, and compliance management, significantly enhancing operational efficiency while leveraging data analytics and cloud deployment to meet modern enterprise needs.
Coupa Software Inc.
Coupa specializes in cloud-based spend management and vendor engagement solutions, renowned for its user-friendly interface, real-time data insights, and strong integrations that optimize procurement processes and vendor collaboration.
JaggedPeak Solutions
JaggedPeak Solutions provides tailored vendor management platforms that emphasize scalable logistics, inventory optimization, and order fulfillment, with advanced AI features supporting retail and ecommerce verticals in Europe.
Oracle Corporation
Oracle’s vendor management suite combines enterprise-grade ERP capabilities with cloud solutions, delivering robust performance analytics, supplier risk assessment, and compliance features across global supply chains.
Beeline SaaS
Beeline SaaS focuses on contingent workforce management, offering solutions that streamline vendor onboarding, engagement, and performance tracking, primarily targeting large enterprises with complex staffing needs.
IBM Corporation
IBM’s vendor management offerings integrate AI and blockchain to enhance transparency, cost efficiency, and security in vendor relationships, catering to sectors requiring stringent compliance and data integrity.
GEP Worldwide
GEP provides comprehensive procurement and vendor management solutions, emphasizing strategic sourcing, supplier relationship management, and analytics-driven decision-making for enterprise clients.
Strategic Business Developments
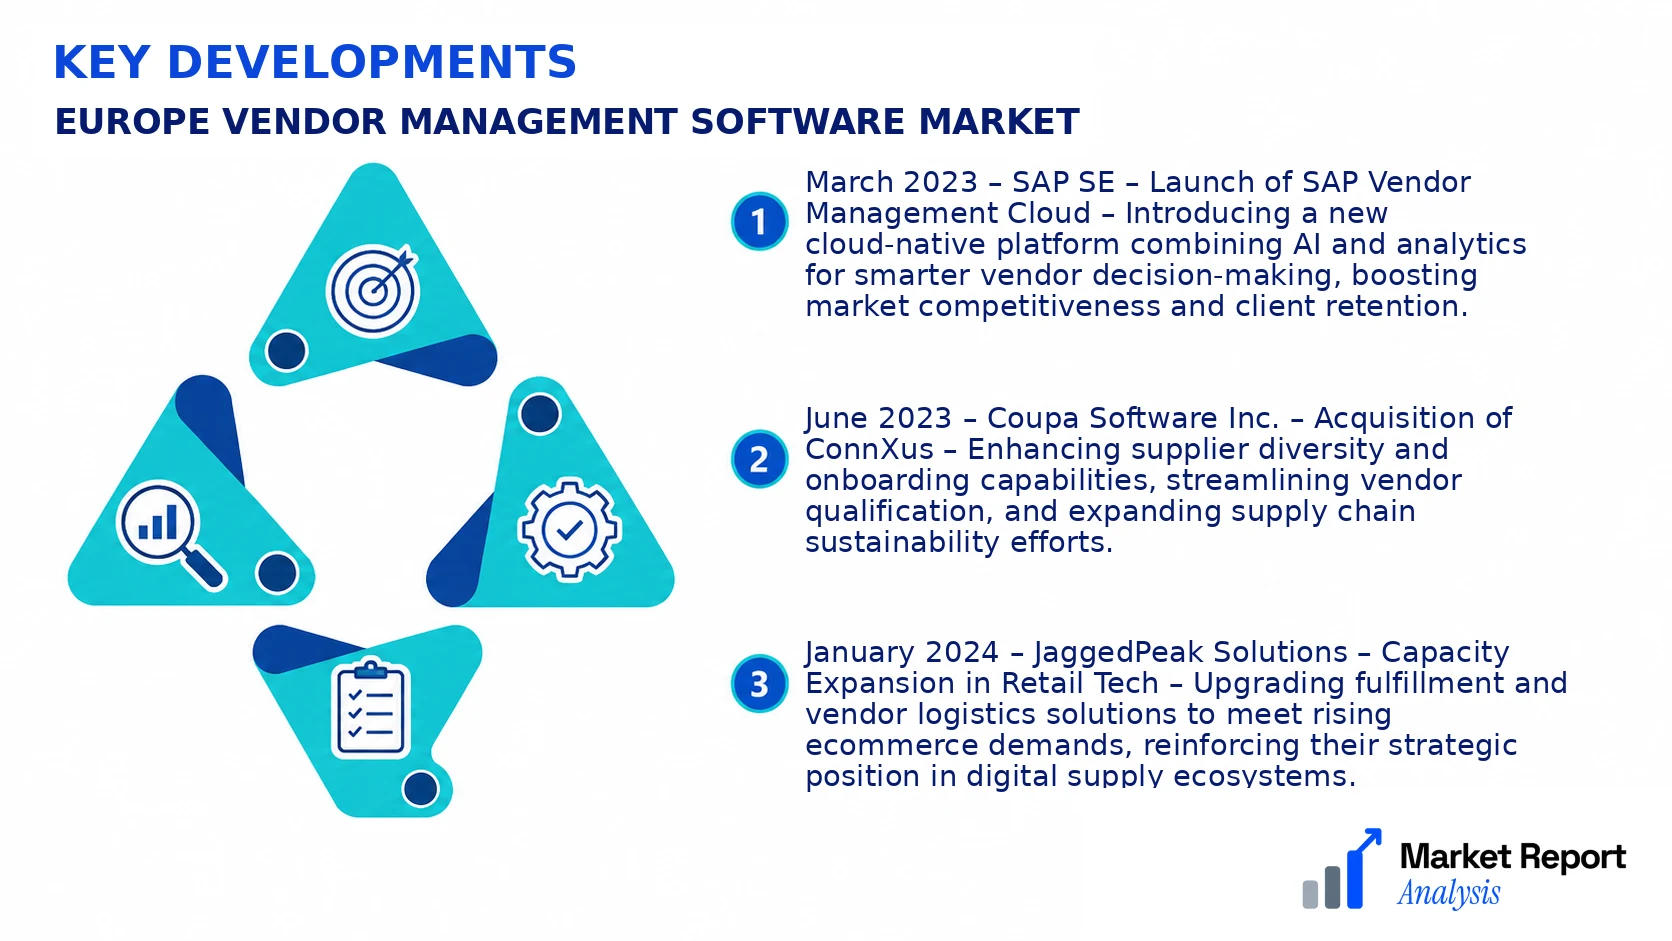
- March 2023 – SAP SE – Launch of SAP Vendor Management Cloud – Introducing a new cloud-native platform combining AI and analytics for smarter vendor decision-making, boosting market competitiveness and client retention.
- June 2023 – Coupa Software Inc. – Acquisition of ConnXus – Enhancing supplier diversity and onboarding capabilities, streamlining vendor qualification, and expanding supply chain sustainability efforts.
- January 2024 – JaggedPeak Solutions – Capacity Expansion in Retail Tech – Upgrading fulfillment and vendor logistics solutions to meet rising ecommerce demands, reinforcing their strategic position in digital supply ecosystems.
- August 2023 – Oracle Corporation – Strategic Partnership with Microsoft – Developing integrated cloud solutions for vendor risk management, improving interoperability, and expanding market reach across Europe.
- November 2023 – IBM Corporation – Launch of Blockchain-based Vendor Verification Platform – Strengthening supply chain transparency and compliance through enhanced security features tailored for regulated industries.
Frequently Asked Questions
What is the Europe Vendor Management Software Market?
The Europe Vendor Management Software Market encompasses solutions that enable organizations to manage and optimize their vendor relationships, procurement processes, and supply chain operations across various industries within Europe, ensuring regulatory compliance, cost efficiency, and strategic value.
What is the current market size of Europe Vendor Management Software Market?
As of 2026, the Europe Vendor Management Software Market is valued at approximately USD 4.2 Billion, reflecting steady growth driven by digital transformation initiatives, regulatory pressures, and increasing demand for efficient supply chain management solutions across the region.
What factors are driving the Europe Vendor Management Software Market?
Key drivers include the rising need for process automation, increasing regulatory compliance demands, digital transformation efforts by enterprises, and the growing adoption of cloud-based solutions. These factors collectively enhance vendor management capabilities and operational efficiency.
Which region dominates the Europe Vendor Management Software Market?
Western Europe currently dominates the market, fueled by mature IT infrastructure, high technological adoption, and significant investments in digital transformation, particularly in countries like Germany, the UK, and France, which serve as innovation hubs for vendor management solutions.
Which segment is expected to grow the fastest?
The small and medium-sized enterprise (SME) segment is anticipated to experience the fastest growth due to increasing digital adoption, cost-effective cloud solutions, and the expanding need for scalable vendor management tools tailored to smaller organizations.
Who are the leading companies operating in the Europe Vendor Management Software Market?
Market leaders include SAP SE, Oracle Corporation, IBM Corporation, Coupa Software, and Ariba. These companies are distinguished by their extensive product portfolios, innovative solutions, and strong regional presence, shaping the competitive landscape in Europe.
Analyst Perspective
The Europe Vendor Management Software Market exhibits a mature landscape, driven by ongoing digital transformation initiatives across various industries. Over the coming years, the market is expected to see substantial growth, with strategic opportunities centered around cloud-based solutions, AI integration, and enhanced analytics capabilities. Technology evolution will focus on increasing automation, cybersecurity enhancements, and seamless integration with existing enterprise systems, further optimizing vendor relationships and risk management. Investment priorities should prioritize R&D in machine learning algorithms, scalability, and regional customization to cater to diverse European regulatory environments. Competitive intensity remains high, with established players consolidating their positions through strategic acquisitions and product differentiation. Regional growth potential is strongest in Western Europe, particularly in Germany, the UK, and France, driven by stringent vendor compliance demands. Long-term, market leaders that invest in innovative technologies and regional diversification will secure advantages, while companies failing to adapt risk obsolescence. Overall, the market offers promising avenues for sustainable growth amidst evolving technological and regulatory landscapes.
