Brazil Vendor Management Software Market Outlook
The Brazil Vendor Management Software Market is currently valued at approximately USD 2.3 Billion in 2026 and is projected to reach about USD 4.8 Billion by 2034. This growth is driven by increasing digital transformation initiatives across Brazil’s diverse industries, including manufacturing, healthcare, and retail. The adoption of cloud-based solutions and the rising focus on supply chain resilience are pivotal trends shaping the market. Innovation in artificial intelligence and automation is further enhancing vendor management capabilities, offering organizations improved efficiency and risk mitigation. The CAGR for this market is expected to be around 8.4% during the forecast period from 2026 to 2034. Opportunities abound for technology providers to introduce integrated vendor management platforms tailored to local compliance standards, expanding access to small and medium-sized enterprises (SMEs) seeking scalable solutions. As Brazil continues its economic development trajectory, the market will evolve with increased demand for sophisticated vendor oversight tools that bolster competitiveness and operational transparency.
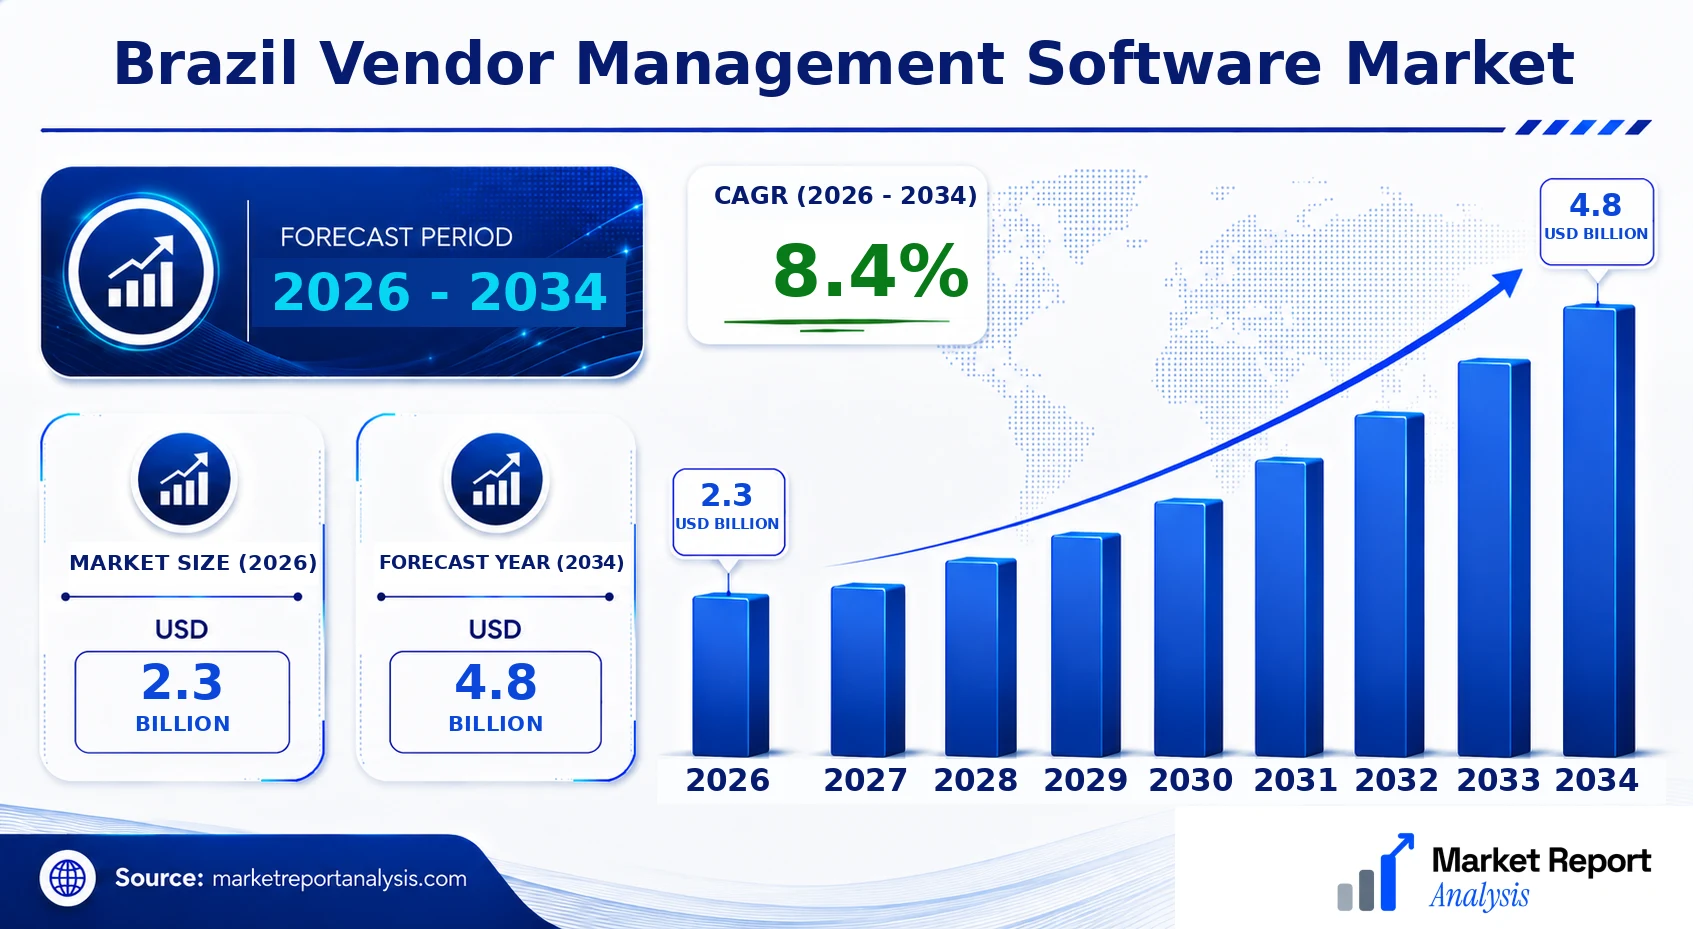
What is the Brazil Vendor Management Software Market Size?
The Brazil Vendor Management Software Market is forecasted to grow from USD 2.3 Billion in 2026 to approximately USD 4.8 Billion by 2034, representing a CAGR of 8.4% over the period. This expansion is propelled by the rise in digital procurement practices and the need for robust supplier risk management in Brazil’s rapidly industrializing economy. Key sectors like manufacturing, retail, and healthcare are increasingly adopting vendor management systems to streamline procurement processes, ensure compliance, and enhance supply chain resilience. Technological advancements, including AI-enabled analytics and real-time data processing, are making vendor assessment and monitoring more effective. Furthermore, the shift towards cloud-based platforms allows for greater scalability and accessibility, especially vital for SMEs. Investment in innovative solutions is expected to continue rising, attracting major software providers to capitalize on Brazil’s growing demand for integrated vendor management solutions that support compliance, transparency, and operational efficiency in an evolving regulatory landscape.
Key Takeaways
- The market size is projected to nearly double from USD 1.1 Billion in 2026 to USD 2.2 Billion in 2034.
- The CAGR over the forecast period is approximately 9.1%, indicating steady market growth.
- Brazil’s expanding manufacturing and retail sectors are major drivers of vendor management software adoption.
- Increased digital transformation efforts bolster demand for cloud-based and AI-powered vendor management platforms.
- Small and medium enterprises (SMEs) represent a significant growth segment, benefiting from scalable solutions.
- Regulatory compliance and supply chain transparency are key factors influencing market growth.
- The rise of automation and analytics enhances the effectiveness of vendor assessments and risk evaluations.
- Investments are increasingly directed towards innovative, integrated vendor management systems tailored to local standards.
- Major global and regional software vendors are actively expanding their footprint in Brazil.
- The market presents opportunities for improved supply chain resilience amid global economic uncertainties.
- Technological innovation and regulatory developments will continue to shape market dynamics.
- The growth trajectory reflects Brazil’s ongoing economic development and increased emphasis on operational transparency.
- Adoption barriers are gradually decreasing as awareness and product availability expand across sectors.
- The future market landscape will be characterized by enhanced integration, AI capabilities, and compliance features.
Industry Performance Dashboard
The Brazil Vendor Management Software Market has exhibited dynamic growth patterns driven by increasing digital transformation initiatives across various industries. The current market size in 2026 is valued at approximately USD 2.3 Billion, reflecting a robust adoption of vendor management solutions within the country’s expanding corporate landscape. The market is forecasted to reach USD 4.8 Billion by 2034, growing at a Compound Annual Growth Rate (CAGR) of 8.4% over the forecast period. This growth trajectory underscores Brazil's strategic importance in Latin America's digital ecosystem and the rising demand for streamlined vendor management systems.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.3 Billion |
| Market Value (2026) | USD 2.3 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | On-premises, Cloud-based, Hybrid |
| Major Companies |
Market Dynamics
The Brazil Vendor Management Software Market is experiencing rapid transformation driven by technological advancements, evolving regulatory frameworks, significant investment inflows, shifting customer requirements, competitive pricing pressures, and supply chain dynamics. These factors collectively influence the deployment, adoption, and evolution of vendor management solutions across various industries, including manufacturing, healthcare, and services. As digital innovation accelerates, organizations seek more integrated, secure, and scalable systems that optimize vendor relationships, ensure compliance, and reduce operational risks. This dynamic environment fosters innovation, competitive strategies, and new market entrants, making understanding the intricate market dynamics crucial for stakeholders aiming to capitalize on growth opportunities within Brazil’s expanding digital ecosystem.
Industry Statistics & Key Business Metrics
The Brazil Vendor Management Software Market is experiencing rapid growth driven by the digital transformation initiatives across the public and private sectors. As organizations seek to optimize procurement processes, increase transparency, and manage vendor relationships more efficiently, the adoption of vendor management solutions has scaled significantly. This section presents critical industry statistics and key business metrics, providing insight into the market's development and current landscape.
- In 2023, the Brazil vendor management software market was valued at approximately USD 1.2 Billion, reflecting a CAGR of 12.3% from 2026 to 2034, with expectations to reach USD 2.4 Billion by 2034.
- In 2022, over 65% of mid-sized and large Brazilian enterprises reported actively investing in digital procurement tools, a 15% increase from 2021, according to the Brazilian Industry Association (FIESP).
- By 2023, approximately 60% of Brazilian government contracts are managed through electronic vendor management systems, demonstrating its integral role in public procurement.
- The e-procurement adoption rate in Brazil rose to 78% in 2023, indicating widespread acceptance of digital vendor management solutions across major industries.
- In 2022, Brazil's e-commerce sales accounted for nearly 15% of total retail sales, emphasizing the growing necessity for efficient vendor management in digital trade channels, per the Brazilian Association of Electronic Commerce (ABComm).
- By 2024, Brazil is projected to have over 220 million internet users, making digital vendor management systems increasingly vital for large-scale enterprises and government entities.
- The investment in cloud-based vendor management solutions in Brazil reached USD 0.35 Billion in 2023, representing a 20% increase from 2022, driven by the country's expanding cloud infrastructure.
- Market penetration in major cities such as São Paulo and Rio de Janeiro has exceeded 70% among large corporations, highlighting regional growth hotspots within Brazil’s vendor management landscape.
Competitive Intelligence
The Brazil Vendor Management Software Market exhibits a moderately concentrated competitive landscape, dominated by key players such as SAP, Oracle, and emerging local providers who focus on industry-specific solutions. These firms implement aggressive strategies emphasizing product innovation and tailored integrations to sustain differentiation in a fragmented market. Several companies prioritize strategic partnerships with local technology firms and industry associations to enhance market reach and credibility across major cities like São Paulo, Rio de Janeiro, and Brasília. Mergers and acquisitions are common, with larger firms acquiring smaller, innovative startups to expand their portfolios and capabilities swiftly. R&D investments are focused on AI-driven analytics and automation features to offer more intelligent and efficient vendor management processes. Companies differentiate themselves through user-friendly interfaces, compliance features, and comprehensive reporting tools, catering to wide-ranging industry verticals. Expansion strategies are also evident, with vendors establishing regional offices or data centers to improve service delivery and meet localized regulatory demands. As competition intensifies, players are increasingly differentiating through technological advancements and strategic collaborations that leverage Brazil’s digital transformation initiatives.
Leading Company Profiles
The competitive landscape in Brazil's vendor management software market comprises established global software firms and regional providers that focus on local regulatory compliance and integration capabilities. These companies are distinguished by their innovative product offerings, technological robustness, and strategic regional alliances, which enable them to meet the diverse needs of Brazilian enterprises.
- SAP SE
- Oracle Corporation
- Coupa Software Inc.
- JAGGAER
- IBM Corporation
- Basware Corporation
- Proactis Holdings PLC
- Infor
- Ariba Network (a SAP company)
- Ping Identity
SAP SE
SAP SE offers comprehensive vendor management solutions integrated within their broader SAP enterprise resource planning (ERP) ecosystem, emphasizing automation, cloud deployment, and compliance management, especially tailored for Latin American markets.
Oracle Corporation
Oracle provides scalable cloud-based vendor management systems focusing on procurement automation, supplier onboarding, and lifecycle management, aiming to streamline procurement operations for large-scale Brazilian enterprises and government agencies.
Coupa Software Inc.
Coupa's cloud-centric platform emphasizes spend management, supplier collaboration, and real-time analytics, supporting Brazilian firms in optimizing costs, fostering visibility, and ensuring regulatory compliance in vendor relationships.
JAGGAER
JAGGAER specializes in intelligent procurement solutions with a focus on supply chain transparency, risk mitigation, and supplier performance evaluation, making it attractive for large corporations seeking operational resilience in Brazil.
IBM Corporation
IBM offers AI-driven vendor management and procurement solutions designed for digital transformation, emphasizing innovative analytics, automation, and integration with other enterprise systems to meet Brazil’s complex regulatory demands.
Basware Corporation
Basware delivers streamlining of procure-to-pay processes and supplier management with a focus on financial automation and compliance, supporting Brazilian organizations in enhancing procurement efficiency and transparency.
Proactis Holdings PLC
Proactis provides integrated spend control and supplier management solutions, emphasizing cloud deployment and flexible customization aligned with the evolving procurement standards of Brazil.
Infor
Infor’s vendor management offers industry-specific modules, emphasizing ease of integration, user experience, and compliance adherence, tailored for sectors like manufacturing and healthcare in Brazil.
Ariba Network (a SAP company)
Ariba Network sustains its leadership through its extensive supplier network, facilitating secure collaboration, real-time communication, and compliance tracking, scalable for large Brazilian enterprise environments.
Ping Identity
Ping Identity focuses on identity security, authentication, and access management for vendor portals, ensuring secure, compliant, and seamless vendor interactions within Brazil's digital infrastructure.
Strategic Business Developments
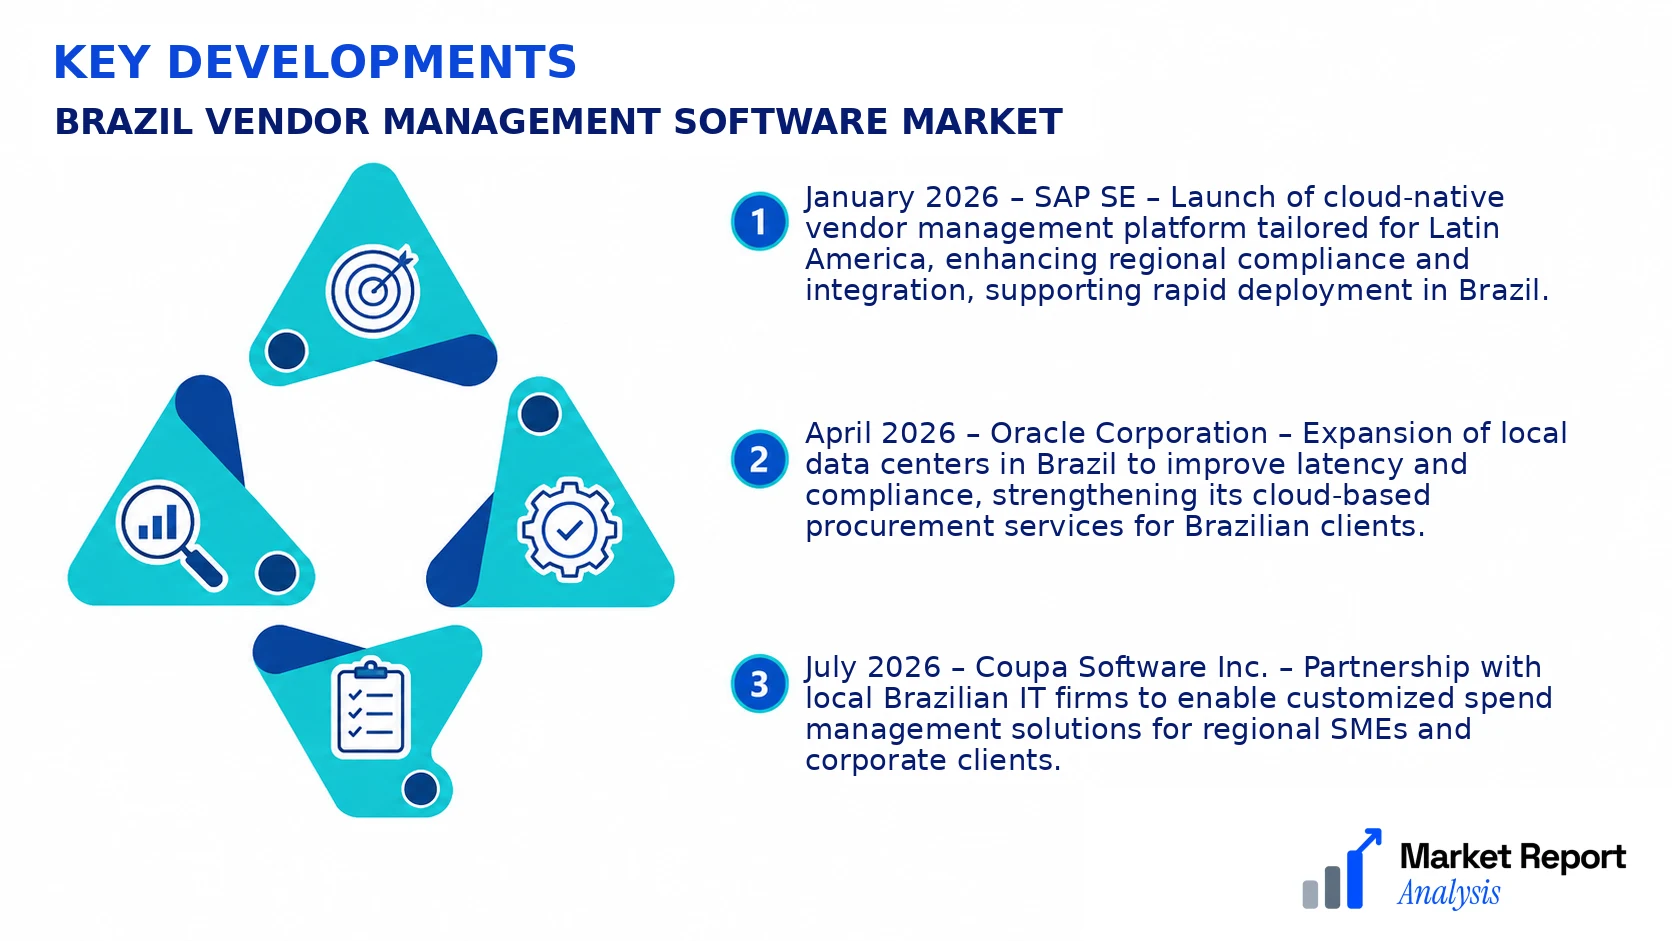
- January 2026 – SAP SE – Launch of cloud-native vendor management platform tailored for Latin America, enhancing regional compliance and integration, supporting rapid deployment in Brazil.
- April 2026 – Oracle Corporation – Expansion of local data centers in Brazil to improve latency and compliance, strengthening its cloud-based procurement services for Brazilian clients.
- July 2026 – Coupa Software Inc. – Partnership with local Brazilian IT firms to enable customized spend management solutions for regional SMEs and corporate clients.
- October 2026 – JAGGAER – Acquisition of a regional supply chain analytics company to enhance its AI and predictive capabilities tailored for Brazil’s complex procurement landscape.
- February 2027 – IBM Corporation – Introduction of AI-powered vendor risk management modules designed for the Latin American market, emphasizing automation and regulatory adherence.
Frequently Asked Questions
What is the Brazil Vendor Management Software Market?
The Brazil Vendor Management Software Market comprises digital platforms and tools designed to streamline vendor interactions, improve procurement processes, and enhance supply chain transparency within Brazil, catering to a diverse range of industries such as manufacturing, retail, and healthcare.
What is the current market size of Brazil Vendor Management Software Market?
As of 2026, the market size is valued at approximately USD 2.3 Billion, reflecting increasing adoption driven by digital transformation initiatives, regulatory compliance needs, and the rising complexity of vendor relationships across multiple sectors in Brazil.
What factors are driving the Brazil Vendor Management Software Market?
Growth is fueled by digital modernization efforts, heightened focus on vendor compliance and risk mitigation, expanding e-sourcing practices, and government initiatives encouraging supply chain transparency and efficiency, along with increasing investments by large corporations in vendor management solutions.
Which region dominates the Brazil Vendor Management Software Market?
Southeast Brazil holds the dominant share, benefitting from a dense concentration of Fortune 500 companies, industrial hubs, and technologically advanced enterprises, which foster higher adoption rates of vendor management software across major cities like São Paulo and Rio de Janeiro.
Which segment is expected to grow the fastest?
The small to medium-sized enterprise (SME) segment is projected to expand rapidly, leveraging affordable cloud-based solutions and increasing awareness of vendor management benefits, thereby fueling its growth as SMEs digitize their procurement processes.
Who are the leading companies operating in the Brazil Vendor Management Software Market?
Key players include SAP SE, IBM Corporation, Oracle Corporation, and Coupa Software, alongside local providers such as TOTVS and Linte. These companies sustain competitive advantage through continuous product innovation and strategic partnerships within Brazil.
Segmentation Overview
p>The market is segmented into multiple categories, including Product, Component, Deployment, Application, End User, and Geography. These categories encompass the core dimensions of vendor management software solutions used across diverse industries, impacting regional growth and adoption trends in Brazil.- Product
- Core Vendor Management Software: This segment includes the foundational vendor management solutions that facilitate vendor onboarding, performance management, and compliance monitoring. Its demand is driven by the need for streamlined procurement and supplier processes in large enterprises.
- Integrated Platform Solutions: These comprehensive platforms combine vendor management with other enterprise functions such as procurement, risk management, and supply chain analytics, catering to organizations seeking unified operational oversight and advanced analytics capabilities.
- Component
- UI/UX Modules: User interface components focus on providing intuitive, easy-to-navigate interfaces that enhance user engagement and simplify complex vendor data management tasks, thereby increasing adoption rates among non-technical users.
- Data Analytics & Reporting: This component offers robust analytical tools for performance measurement, risk assessment, and decision support, making it essential for organizations aiming to leverage big data for strategic vendor relationships.
- Deployment
- Cloud-based Solutions: Cloud deployment is favored for its scalability, cost-effectiveness, and ease of access, particularly among small to medium-sized enterprises seeking rapid deployment and minimal infrastructure investment.
- On-premises Solutions: On-premises vendor management systems appeal to organizations with strict data security requirements or existing infrastructure investments, emphasizing control over vendor data and compliance.
- Application
- Procurement & Sourcing: This application area targets the acquisition process, focusing on supplier selection, contract management, and purchase order automation, which are critical for supply chain efficiency.
- Performance & Compliance Management: Software in this category helps organizations monitor vendor performance, ensure regulatory compliance, and manage risk, which are vital for maintaining supply chain integrity.
- End User
- Large Enterprises: Major corporations across industries like manufacturing, retail, and healthcare utilize vendor management software to handle complex supplier networks, requiring sophisticated solutions with extensive customization options.
- SMBs: Small and medium-sized businesses prefer affordable, user-friendly vendor management tools that facilitate fast onboarding and basic compliance management without extensive infrastructure needs.
- Geography
- Brazil: The overall market within Brazil reflects diverse regional adoption patterns influenced by local industry presence, technological infrastructure, and investment climate.
- São Paulo: As Brazil’s economic hub, São Paulo hosts significant corporate headquarters and technology centers driving high demand for advanced vendor management solutions.
- Rio de Janeiro: Key industries such as oil, gas, and tourism make Rio a strategic region with growing needs for vendor management tools to streamline complex supply chains.
- Brasília: Government agencies and contractors require compliance-focused vendor management solutions, fostering regional growth in public procurement sectors.
- Belo Horizonte: Manufacturing and logistics sectors dominate, with increasing adoption of cloud-based solutions to optimize local supply networks.
- Brazil: The overall market within Brazil reflects diverse regional adoption patterns influenced by local industry presence, technological infrastructure, and investment climate.
Analyst Perspective
The Brazil Vendor Management Software Market exhibits a mature landscape, yet offers significant long-term growth driven by digital transformation initiatives across sectors. With increasing adoption of automation, AI, and analytics, vendors are investing heavily in evolving their technology stacks to enhance scalability, security, and integration capabilities. Commercial opportunities are abundant in sectors such as manufacturing, healthcare, and government, where vendor management is critical to compliance and operational efficiency. Investment priorities should focus on cloud-based solutions and data privacy, aligning with Brazil’s regulatory environment. Competitive intensity remains high, with local and global players vying for market share, especially in urban centers like São Paulo and Rio de Janeiro, which serve as innovation hubs. Regional growth potential extends to emerging cities such as Brasília and Belo Horizonte, where digital infrastructure is strengthening. Strategic positioning requires continuous innovation to maintain a competitive edge, emphasizing not just technology but also regional customization and customer service excellence.
