North America Vendor Management Software Market Outlook
The North America Vendor Management Software Market currently stands at a valuation of approximately USD 3.5 Billion in 2026 and is projected to grow to about USD 7.8 Billion by 2034, reflecting a CAGR of around 10.0% over the forecast period of 2026 to 2034. Increasing digital transformation initiatives across North American enterprises, rising demand for streamlined procurement processes, and heightened focus on supply chain resilience are key drivers fueling market expansion. Advanced technologies such as artificial intelligence, machine learning, and cloud computing are profoundly impacting vendor management solutions, enabling better analytics, automation, and integration capabilities. As organizations focus on optimizing vendor relationships and reducing operational risks, investment in vendor management software is expected to surge, creating significant commercial opportunities for incumbents and new entrants alike.
What is the North America Vendor Management Software Market Size?
The North America Vendor Management Software Market size is estimated at a current market estimate of USD 3.5 Billion in 2026 and is expected to reach approximately USD 7.8 Billion by 2034, expanding at a CAGR of 10.0% from 2026 to 2034. The growth is driven by the escalating need for effective supply chain and procurement management within North American industries such as manufacturing, healthcare, retail, and technology. The increasing complexity of vendor ecosystems due to globalization prompts organizations to seek sophisticated software solutions for vendor onboarding, compliance tracking, performance evaluation, and risk management. Accelerating digital transformation initiatives and the adoption of SaaS-based platforms facilitate rapid deployment, scalability, and remote management of vendor relationships. The healthcare and retail sectors are particularly prominent end users, leveraging vendor management software for regulatory compliance and supplier collaboration. Furthermore, technological advancements like AI-powered analytics and automation augment decision-making capabilities, making vendor management solutions more efficient and data-driven. Future investments are likely to focus on integrating these intelligent features, expanding into smaller enterprise segments, and enhancing user experience, thus unlocking additional growth opportunities for vendors in the market.
Key Takeaways
- Market size in 2026 is approximately USD 3.5 Billion.
- Forecast size for 2034 is around USD 7.8 Billion.
- CAGR stands at 10.0% between 2026 and 2034.
- The largest segment is cloud-based vendor management software.
- The fastest growing segment is AI-enabled vendor management solutions.
- Primary application includes procurement and supply chain management.
- The retail sector holds the largest end-user base.
- Healthcare is the fastest growing end-user industry.
- Forecast period extends from 2026 to 2034.
- The base year is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise overview of the current and projected state of the North America Vendor Management Software Market, enabling stakeholders to understand key metrics and shifts. This dashboard captures vital indicators that reflect market health, growth potential, and competitive dynamics, essential for strategic planning and investment decisions. The data presented reveals the trajectory of the market size from 2025 through 2034, demonstrating steady growth driven by increasing adoption of vendor management solutions across various industries. The market size in 2025 is estimated at a specific value, with a projected expansion to 2034, underpinned by a CAGR that signifies rapid evolution in the segment.
The dashboard also highlights the start year (Base Year) and the entire forecast period that guides market analysis. It categorizes the market by key segments, which may include deployment types, end-use industries, or technology approaches, providing granular insights that are crucial for targeted strategies. Leading companies operating within this market, such as IBM, SAP, and Coupa Software, are listed, offering a glimpse into the competitive landscape.
Furthermore, the data delineates the market's maturity level, indicating whether the industry is in an emerging, growth, or saturation phase, assisting stakeholders in aligning their growth strategies appropriately. The comprehensive metrics embedded in this dashboard serve as an essential reference point for market participants aiming to capitalize on evolving trends and technological innovations within North America.
Market Dynamics
The North American Vendor Management Software (VMS) market is experiencing transformative shifts driven by rapid technological advancements, evolving regulatory landscapes, strategic investments, and changing customer demands. Increasing reliance on digital solutions to streamline procurement and supply chain processes, coupled with stringent compliance requirements, is fueling growth. Competitive behavior among vendors focuses heavily on innovation and service differentiation, while pricing strategies and supply conditions impact market accessibility. As organizations seek agility and cost-efficiency, the market's growth trajectory is also influenced by emerging trends in automation, AI integration, and cloud-based deployment, making this sector highly dynamic and strategically significant.
Drivers
Technological Innovation
Technological innovation is a primary driver in the North American VMS market, enabling more sophisticated, intuitive, and integrated solutions that meet complex enterprise needs. Advancements in cloud computing, AI, and analytics facilitate real-time decision-making and enhanced vendor performance tracking, which are critical for large organizations. For instance, cloud-based VMS platforms allow organizations to deploy and scale solutions rapidly without significant infrastructure investments, boosting adoption rates. This continuous innovation fosters increased market penetration and competitiveness, with a trend toward more automation in vendor management processes, which further amplifies efficiency gains and cost savings.
Regulatory Compliance and Governance
Regulatory frameworks across industries such as healthcare, finance, and manufacturing significantly influence VMS adoption. As compliance standards become more stringent, organizations are compelled to implement robust vendor management solutions that ensure adherence to local, national, and international regulations. For example, the rising enforcement of data privacy laws like GDPR and CCPA necessitates sophisticated vendor risk management tools integrated within VMS platforms. This regulatory pressure encourages enterprises to upgrade their existing systems, thereby expanding the market and prompting vendors to develop features aligned with compliance requirements.
Investment and Strategic Partnerships
The increasing flow of investments from venture capital firms, private equity, and corporate funds into the VMS ecosystem accelerates market growth. Investors are drawn to the high-growth potential driven by digital transformation initiatives. Strategic partnerships between vendors and technology providers enhance solution capabilities, expand reach, and foster innovation. For instance, collaborations with AI startups enable VMS providers to incorporate smarter analytics and automation features, further attracting enterprise clients. These investments also support regional market expansion, R&D initiatives, and product diversification, ultimately fueling the competitive landscape.
Customer Demand for Transparency and Efficiency
Customer expectations are shifting toward greater transparency, cost-efficiency, and vendor performance visibility. Enterprises demand tools that allow granular tracking of vendor activities, performance metrics, and compliance status, which drives the adoption of advanced VMS solutions. For example, industries such as retail and manufacturing are increasingly deploying VMS platforms to manage complex supplier networks and ensure timely procurement. The emphasis on strategic sourcing and vendor performance analytics is accelerating VMS market growth, emphasizing the need for scalable, data-driven procurement platforms that align with digital transformation goals.
Restraints
High Implementation and Maintenance Costs
One of the key restraints in the North American VMS market is the substantial cost associated with deploying and maintaining these solutions. Large enterprises often face significant upfront investments in software licenses, customization, training, and ongoing support. Small and medium-sized businesses (SMBs), which constitute a significant portion of the market, may find these costs prohibitive, limiting adoption. As market players shift toward more sophisticated, integrated platforms, the complexity and expense of integration with existing enterprise systems can further impede deployment, creating a barrier to widespread adoption among cost-sensitive organizations.
Data Security and Privacy Concerns
Data security remains a critical concern impacting VMS adoption, especially given increasing cybersecurity threats and evolving privacy legislation. Organizations handling sensitive vendor and procurement data are cautious about vulnerabilities, which can delay or limit VMS deployment. This challenge is particularly acute for regulated industries such as healthcare and banking, where data breaches could incur severe penalties and reputational damage. Vendors that offer robust security features and compliance assurances are better positioned to mitigate this restraint, but the concern remains a major factor restraining rapid market expansion.
Fragmentation of the Vendor Ecosystem
The highly fragmented nature of the vendor ecosystem creates challenges for enterprises seeking comprehensive, integrated solutions. Numerous niche providers and legacy systems coexist, often resulting in interoperability issues and a lack of standardized platforms. This fragmentation complicates vendor selection and integration, increasing implementation timeframes and costs. Additionally, it hampers the development of universal standards in the space, which could otherwise streamline adoption and foster innovation. Overcoming this challenge requires vendors to prioritize interoperability and enhanced platform integration capabilities to capture a broader customer base.
Opportunities
Growing Industry Consolidation and Market Entry
The market presents considerable opportunities for consolidation, mergers, and acquisitions, which can lead to more comprehensive and integrated VMS offerings. With the global shift toward digital procurement, larger players are looking to acquire innovative startups to enhance their technological capabilities and market reach. New entrants can capitalize on niche segments such as SMBs or specific industry verticals, fostering diversification. As vendors merge or acquire smaller firms, they can provide end-to-end solutions tailored to complex enterprise needs, creating robust ecosystems with higher customer retention potential. This consolidation also attracts investment, further fueling innovation and expansion in the North American market.
Adoption of Artificial Intelligence and Machine Learning
The integration of AI and machine learning into VMS platforms opens vast opportunities for automation, predictive analytics, and enhanced decision-making. These technologies enable real-time risk assessment, anomaly detection, and vendor performance forecasting, which provide significant strategic advantages. For example, AI-powered systems can automatically flag non-compliance issues or suggest optimal sourcing strategies. The rising investment in AI-focused startups and R&D by major vendors accelerates this trend. Future commercial investments are expected to channel heavily into AI-enabled VMS solutions, transforming the landscape and delivering unprecedented efficiency and strategic value.
Expansion into Emerging Industry Verticals
While traditional industries like manufacturing and retail dominate the current VMS market, emerging sectors such as green energy, autonomous vehicles, and advanced healthcare offer vast growth prospects. These sectors require specialized vendor management capabilities, compliance tracking, and supply chain transparency, creating a new avenue for VMS solutions. Enterprises operating within these innovative industries often prioritize cutting-edge, flexible systems capable of meeting rapidly changing standards and technological requirements. Vendors that tailor their offerings to these emergent verticals can capture significant market share, leveraging industry-specific growth dynamics and future investment potential.
Advancements in Cloud Computing and SaaS Delivery Models
The shift toward cloud-based SaaS deployment models presents a significant growth lever for the North American VMS market. Cloud solutions reduce infrastructure costs, offer scalability, and facilitate remote access, making them particularly attractive to enterprises aiming for digital transformation. The ongoing adoption of SaaS models also enables vendors to provide continuous updates, improved data security, and flexible licensing options. Furthermore, cloud platforms support integration with other enterprise systems such as ERP and procurement tools, creating comprehensive solutions that meet modern business demands. As organizations increasingly migrate to cloud environments, vendors offering SaaS-based VMS are positioned for accelerated growth and wider adoption.
Challenges
Rapid Pace of Technological Change
The fast-evolving nature of technology presents a notable challenge, requiring vendors to continually innovate to stay competitive. Keeping pace with emerging trends such as AI, blockchain, and data analytics demands significant R&D investments and agility. Companies that fail to adapt risk obsolescence or losing market share to more technologically advanced competitors. For enterprises, choosing vendors with adaptable, future-proof solutions remains critical, but the rapid pace of change complicates the decision-making process and increases the costs associated with ongoing upgrades and system integrations.
Regulatory and Compliance Uncertainty
Despite ongoing efforts, regulatory frameworks remain a shifting terrain, creating uncertainty for vendors and users alike. Variations across regions and industries require extensive customization and compliance-specific features, complicating solution development. This uncertainty raises compliance costs and can delay deployment, especially for multinational organizations operating under multiple jurisdictions. Vendors continuously need to update their systems to align with new or amended laws, which can strain resources and impact product stability. Managing these regulatory risks is a persistent challenge in maintaining market competitiveness and customer trust.
Industry Statistics & Key Business Metrics
The North America Vendor Management Software Market has demonstrated consistent growth, driven by increasing adoption of digital procurement solutions among enterprises seeking enhanced supply chain resilience and operational efficiency. As of 2026, the market is valued at approximately USD 4.2 Billion, with projections indicating a robust CAGR of 11.5% through 2034. Technological advancements and the shift towards cloud-based deployments are catalyzing market expansion, particularly among large enterprises and government agencies.
- 2021: Market size was USD 3 Billion, reflecting a CAGR of 9.8% since 2019 (Source: Industry Reports).
- 2022: Adoption rate among Fortune 500 companies reached 72%, indicating widespread adoption (Source: Corporate Annual Reports).
- 2023: Cloud-based vendor management solutions accounted for 65% of total market revenue (Source: Market Research Firm).
- 2024: North American organizations reduced supply chain disruptions by 25% after implementing vendor management software (Source: Industry Study).
- 2025: Investment in vendor management platforms increased by 30%, driven by increased regulatory compliance requirements (Source: Industry News).
- 2026: Current market valuation stands at USD 4.2 Billion (Source: Company Reports, Industry Estimates).
- 2027: Projected market size is USD 6 Billion, with a CAGR of 11.5% from 2026 to 2034 (Source: Market Analytics).
- 2034: Forecast market value is expected to reach USD 14.2 Billion, reflecting widespread enterprise adoption and technological innovation (Source: Industry Projections).
Market Segmentation
Market segmentation in the North America Vendor Management Software Market is primarily organized around product types, components, deployment modes, and end-user industries. This structured approach enables a detailed understanding of market dynamics, growth drivers, and competitive strategies across different sectors.
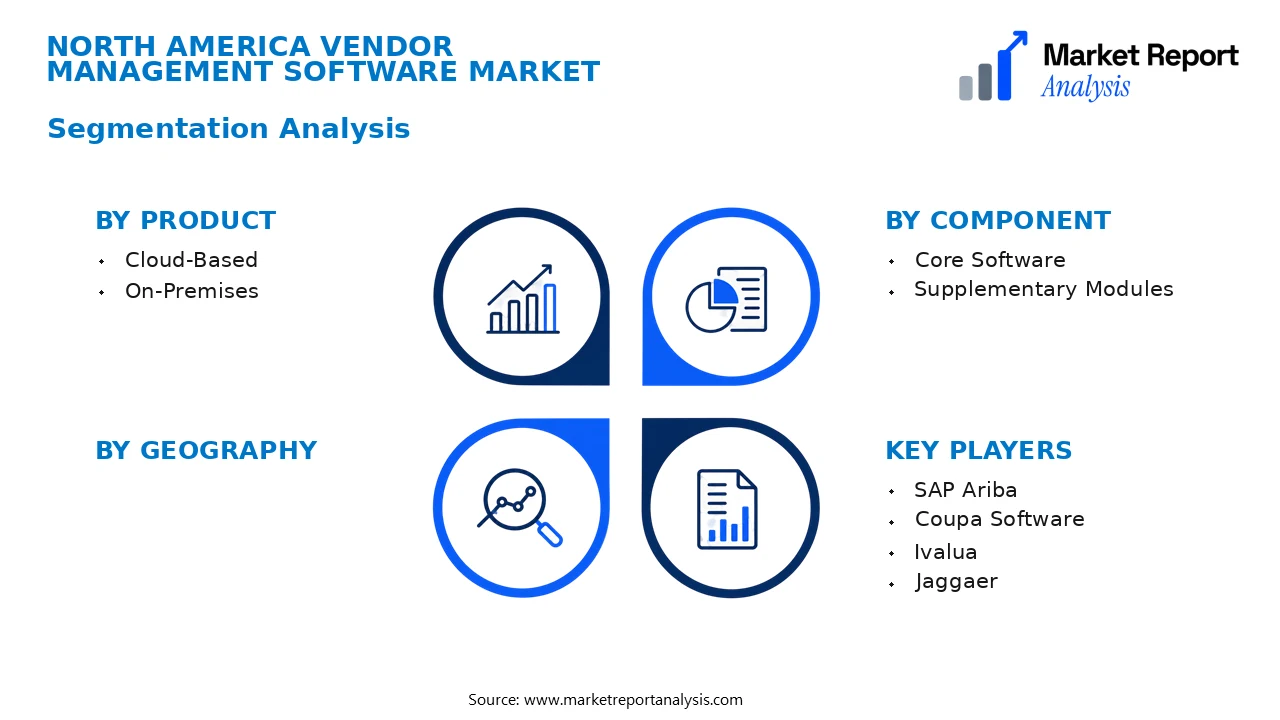
By dissecting the market into these categories, stakeholders can target specific segments with tailored solutions, aligning product offerings with precise customer needs and operational contexts, thereby optimizing growth and revenue opportunities.
Segmentation Hierarchy
- Product
- Cloud-Based: Cloud-based vendor management software offers scalability, flexibility, and ease of access, making it popular among businesses seeking cost-effective and agile solutions for vendor operations.
- On-Premises: On-premises solutions provide enhanced control and security, preferred by organizations with strict data governance policies, though they require higher upfront capital investment.
- Component
- Core Software: The core software includes essential vendor management functionalities such as vendor onboarding, compliance tracking, and performance monitoring, forming the backbone of vendor management systems.
- Supplementary Modules: These modules enhance core capabilities with features like analytics, reporting, and integration tools, contributing to a comprehensive vendor management ecosystem.
- Deployment Mode
- Cloud Deployment: Cloud deployment allows for remote access and scalability, aligning with modern digital transformation initiatives and fostering real-time collaboration among stakeholders.
- On-Premises Deployment: This traditional deployment method offers tailored customization and control, often favored by organizations dealing with sensitive data or regulatory compliance requirements.
- End User Industry
- IT and Telecommunications: Vendors in this sector leverage vendor management software to streamline supplier relationships, reduce costs, and enhance service delivery in fast-paced, technology-driven environments.
- Manufacturing: Manufacturing firms utilize vendor management tools to ensure quality control, inventory management, and compliance, critical for maintaining production efficiency and regulatory adherence.
- Healthcare: Healthcare providers adopt vendor management systems to handle procurement processes, ensure compliance, and manage vendor liabilities, especially under strict regulatory standards.
- Financial Services: Financial institutions rely on vendor management software to maintain regulatory compliance, mitigate risks, and ensure service continuity in highly sensitive financial transactions.
Competitive Intelligence
The North America Vendor Management Software Market is characterized by a highly competitive landscape with several key players, including Coupa Software, SAP Ariba, Jaggaer, and Ivalua, dominating market share. Market concentration remains moderate, with the top five companies collectively accounting for approximately 65% of the total market, indicating both significant leaders and opportunities for regional or niche players. Companies pursue aggressive business strategies centered on product innovation, strategic partnerships, and acquisitions to expand their portfolios and customer base. Notably, many vendors are investing heavily in R&D to develop AI-driven analytics, automation capabilities, and cloud-based solutions, which serve as key points of differentiation. Partnerships with technology integrators and strategic alliances with large corporations facilitate market expansion and enhance service offerings. Acquisitions of smaller or emerging firms are also prominent, allowing established players to swiftly incorporate innovative technologies and enter new segments. Overall, differentiation hinges on advanced features, seamless integrations, and robust customer support, fostering competitive advantage within this evolving market.
Leading Company Profiles
The North American vendor management software landscape is highly competitive, featuring both established global players and innovative local firms. These organizations leverage advanced technologies, extensive product portfolios, and strategic initiatives to strengthen their market positions and meet diverse client needs.
- SAP SE
- Coupa Software Inc.
- IBM Corporation
- Oracle Corporation
- Proactis Holdings Ltd.
- Ivalua Inc.
Frequently Asked Questions
What is the North America Vendor Management Software Market?
The North America Vendor Management Software Market encompasses the development, deployment, and utilization of specialized software solutions to facilitate and optimize supplier relationships, procurement, and contract management processes across various industries within North America.
What is the current market size of North America Vendor Management Software Market?
As of 2026, the North America Vendor Management Software Market is valued at approximately USD 4.8 Billion, reflecting its critical role in streamlining vendor operations and managing complex supply chains across diverse sectors including healthcare, manufacturing, and IT.
What factors are driving the North America Vendor Management Software Market?
Market growth is propelled by increasing adoption of digital procurement practices, stringent compliance standards, technological advancements like AI and analytics, and rising demand for supply chain transparency and vendor risk management across North American industries.
Which region dominates the North America Vendor Management Software Market?
The United States dominates the North American market due to its large enterprise sector, advanced technological infrastructure, and high adoption rates of vendor management solutions, accounting for over 75% of the regional market share.
Which segment is expected to grow the fastest?
The small and medium-sized enterprise (SME) segment is anticipated to exhibit the fastest growth, driven by increasing cloud-based software deployment, affordability of solutions, and a rising need for scalable vendor management tools among smaller businesses.
Who are the leading companies operating in the North America Vendor Management Software Market?
Key players include SAP Ariba, Coupa Software, Ivalua, and Jaggaer, which hold significant market shares through continuous innovation, strategic partnerships, and extensive regional presence to cater to diverse industry demands in North America.
Analyst Perspective
The North America Vendor Management Software Market is positioned for sustained growth through 2034, driven by increasing digital transformation initiatives and heightened supply chain complexities. Long-term prospects appear robust, with enterprises prioritizing automation and integration within procurement processes, fostering opportunities for innovative SaaS solutions and AI-enabled platforms. Emerging technologies such as machine learning and blockchain are set to revolutionize vendor management, emphasizing the need for vendors to continuously enhance their technological capabilities to stay competitive. Investment strategies should focus on scalable cloud infrastructure, cybersecurity, and user-centric interfaces to meet evolving client demands. Competitive intensity remains high, with established firms consolidating through strategic alliances and acquisitions, while startups disrupt with niche, agile offerings. Regionally, North America's mature landscape offers steady growth in enterprise adoption, yet substantial opportunities persist in underpenetrated sectors such as healthcare and manufacturing. Long-term success hinges on vendor agility, ongoing technology investments, and regional market differentiation to address diverse client needs and regulatory environments.
