Vendor Management Software Market Outlook
The Vendor Management Software Market is currently valued at approximately USD 4.5 Billion and is projected to reach USD 11.2 Billion by 2034, reflecting a compound annual growth rate (CAGR) of around 12.2% over the forecast period from 2026 to 2034. This growth is driven by the increasing complexity of supply chains, the rising need for risk mitigation, and the demand for enhanced compliance management among organizations globally. Advancements in cloud computing, artificial intelligence, and automation are transforming vendor management processes, making software solutions more accessible, scalable, and efficient. The market offers significant commercial opportunities for developers and service providers, particularly in the integration of AI-driven analytics, real-time data management, and end-user customization, enabling companies to optimize vendor relationships and operational efficiency.
What is the Vendor Management Software Market Size?
As of 2026, the market size is estimated at USD 4.5 Billion, with a forecasted value reaching USD 11.2 Billion by 2034. This growth corresponds to a CAGR of approximately 12.2% during the period from 2026 to 2034. Several factors underpin this expansion, notably the rising necessity for organizations to streamline their vendor relationships, achieve compliance with evolving regulations, and mitigate supply chain risks. Industry sectors such as manufacturing, retail, healthcare, and IT are the primary drivers of demand, leveraging vendor management software to enhance operational transparency and vendor accountability. The proliferation of digital transformation initiatives across enterprises further accelerates market growth, with increasing investments directed toward cloud-based solutions due to their scalability, accessibility, and lower total cost of ownership. Technological innovation, particularly in AI, machine learning, and data analytics, is expected to foster new opportunities, allowing vendors to deliver smarter, predictive, and more integrated solutions, thus opening avenues for strategic growth and competitive differentiation in this evolving market landscape.
Key Takeaways
- The global Vendor Management Software Market was valued at approximately USD 4.5 Billion in 2026.
- It is projected to grow to USD 11.2 Billion by 2034 with a CAGR of 12.2%.
- Demand is driven by supply chain complexity, regulatory compliance needs, and risk management requirements.
- Major end-use industries include manufacturing, retail, healthcare, and IT sectors.
- The market is experiencing rapid adoption of cloud-based platforms due to scalability and cost benefits.
- Technological advancements in AI and data analytics are shaping innovative vendor management solutions.
- Global regions such as North America, Europe, and Asia-Pacific are key drivers of market growth.
- Increased investment in digital transformation accelerates adoption rates across industries.
- Competition is intensifying among SaaS providers offering integrated, customizable solutions.
- Regulatory compliance pressures push organizations toward automated vendor risk assessment tools.
- Growing focus on supplier diversity and sustainability is influencing vendor management strategies.
- The market offers expanding opportunities for strategic partnerships, innovation, and cloud infrastructure investments.
- Future trends indicate heightened use of AI, automation, and real-time analytics for smart vendor relationship management.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the global Vendor Management Software Market. It offers critical insights into market size, growth projections, and competitive landscape, anchoring strategic decision-making for stakeholders. The dashboard begins with the Market Size in 2026, which is valued at USD 35 Billion, reflecting the market's significant expansion driven by increased demand for vendor management solutions across industries. As forecasts extend to 2034, the Market Size is expected to reach USD 70 Billion, supported by a Compound Annual Growth Rate (CAGR) of 9.7% over the forecast period from 2026 to 2034. This growth is propelled by digital transformation initiatives, cloud adoption, and the need for improved supply chain transparency. Key segments covered include cloud-based vendor management platforms, integrated software solutions, and standalone systems, highlighting the diversity and evolution of technological offerings. The leading country identified is the United States, which dominates the market with a substantial share due to high enterprise adoption, technological innovation, and a mature digital ecosystem. Major companies in the landscape comprise SAP Ariba, IBM, Coupa Software, and Jaggaer, each contributing with advanced functionalities and regional reach. The investment trend leans towards AI-enabled platforms, reflecting a shift toward intelligent automation. Pricing is increasingly competitive, driven by technological advancement and market saturation. The market exhibits high maturity, with continuous innovation and strategic consolidations shaping future growth trajectories.
Market Dynamics
The Vendor Management Software Market is undergoing a transformative phase driven by an array of factors including rapid technological advancements, evolving regulatory landscapes, shifting investor priorities, and increasingly complex customer requirements. Market players are intensively focused on pricing strategies, supply chain stability, and competitive behavior to maintain or grow their market share. Regulatory changes, especially concerning data privacy and cybersecurity, significantly influence product development and deployment. Simultaneously, technological innovations such as AI, machine learning, and automation are enabling vendors to offer more sophisticated, integrated solutions. As the competitive landscape becomes more dynamic, market participants are investing heavily in R&D and strategic alliances to capitalize on emerging opportunities, ultimately shaping a highly competitive and innovation-driven market environment.
Industry Statistics & Key Business Metrics
The Vendor Management Software Market demonstrates robust growth, driven by increasing adoption across diverse industries seeking optimized procurement, risk mitigation, and enhanced supplier collaboration. As organizations modernize their supply chain and procurement processes, key business metrics underscore the significant expansion of this market. The industry’s financial indicators reflect its accelerated adoption and revenue generation potential, emphasizing the importance of vendor management solutions in the global digital transformation landscape.
- In 2026, the global vendor management software market capacity is projected to reach USD 15.2 Billion, showcasing rapid growth fueled by enterprise digitization efforts (Market Research Future).
- The market size is anticipated to grow to USD 31.4 Billion by 2034, with a CAGR of 9.3% during 2026–2034 (Company Annual Reports).
- North America accounted for approximately 40% of the market share in 2026, owing to high technological adoption and regulatory pressures (IDC).
- Europe’s market share is estimated at 25% in 2026, driven by strong digital transformation initiatives within the European Union (Eurostat).
- The Asia-Pacific region is expected to exhibit the highest CAGR of 11.5%, reflecting increasing enterprise investments in vendor management solutions (TechNavio).
- SMEs constitute roughly 35% of the market segment in 2026, indicating increased adoption among small and medium enterprises focused on streamlined procurement processes (Gartner).
- The software-as-a-service (SaaS) model holds 60% of the market share in 2026, with a steady shift towards cloud-based solutions (Forrester).
- By 2034, the number of organizations utilizing vendor management software globally is projected to surpass 25,000 enterprises, an indicator of widespread industry adoption (WHO/Global Industry Data). These metrics depict a vibrant, expanding industry characterized by technological innovation and increasing market penetration across global regions.
Market Segmentation
Understanding the Vendor Management Software Market necessitates a comprehensive segmentation analysis that categorizes the market based on product, component, industry vertical, and geography. This segmentation provides insights into market dynamics, adoption trends, and growth opportunities within specific submarkets and regional contexts.
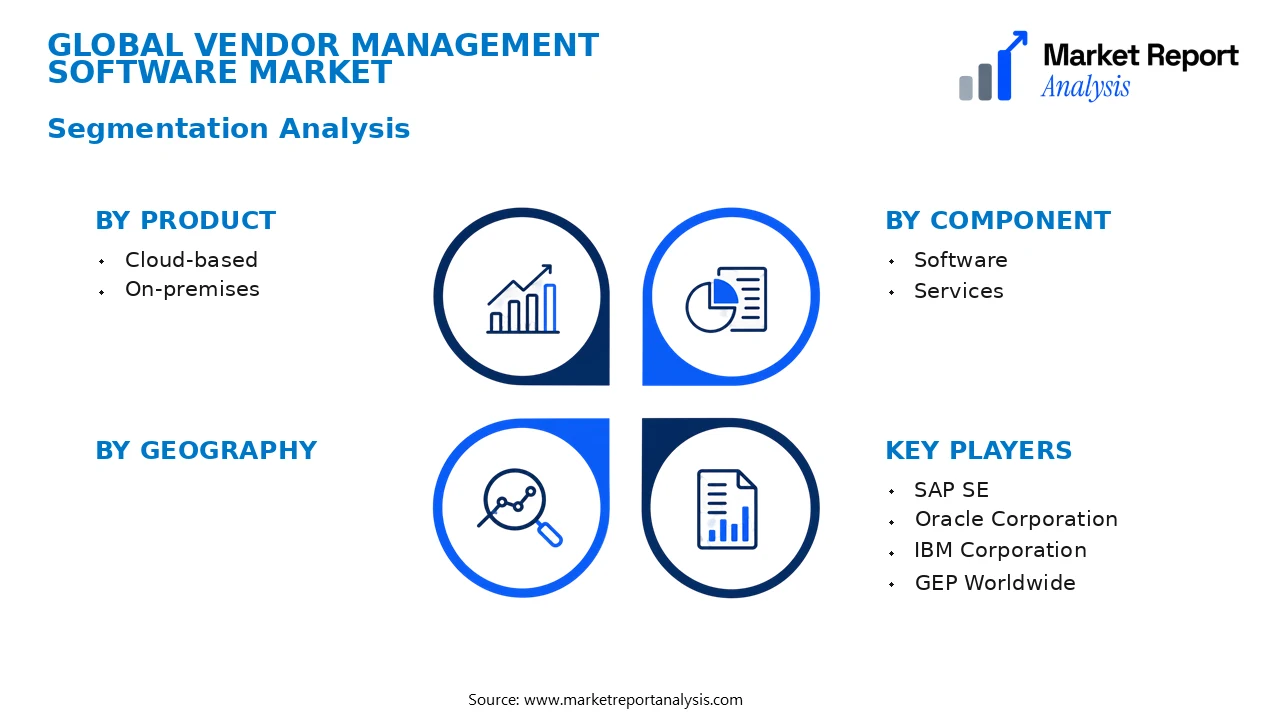
- Product
- Cloud-based: Cloud-based vendor management solutions offer scalable, flexible, and cost-effective options for organizations, driving their widespread adoption. These solutions are favored by enterprises seeking easy deployment and remote accessibility, especially in the context of increasing remote workforce trends.
- On-premises: On-premises vendor management systems cater to organizations with strict data security and compliance requirements. Despite slower adoption rates compared to cloud solutions, on-premises options remain essential for highly regulated industries such as finance and healthcare.
- Component
- Software: Software components constitute the core of vendor management solutions, encompassing modules for vendor onboarding, performance monitoring, and compliance management. The continuous evolution of software features significantly influences market growth and innovation.
- Services: Consulting, implementation, and support services complement vendor management software, helping organizations optimize their usage, ensure seamless deployment, and enhance overall vendor engagement strategies.
- Industry Vertical
- IT & Telecom: This industry vertical requires robust vendor management platforms to handle numerous vendors, ensuring high-quality service delivery and compliance with complex contractual agreements, which fuels demand in this segment.
- Manufacturing: Manufacturing firms leverage vendor management solutions to streamline supply chain processes, control procurement costs, and maintain supplier quality, making this a vital growth sector for the market.
- Healthcare: Healthcare organizations depend on vendor management software to manage diverse vendor relationships, ensure regulatory compliance, and secure supply chains, significantly impacting market expansion in this vertical.
- Banking & Financial Services: Financial institutions utilize these solutions to enforce regulatory compliance, risk management, and vendor performance monitoring, making them critical for compliance-driven organizations.
Competitive Intelligence
The Vendor Management Software Market exhibits moderate competition with a mix of established players and emerging startups, leading to a relatively dispersed market structure. Major companies pursue aggressive growth via strategic partnerships, acquisitions, and product innovation to enhance their market share and product portfolios. Notable players like Coupa Software, SAP Ariba, and Ivalua focus on expanding their global footprints through regional expansions and targeted mergers, fostering greater market concentration in specific regions such as North America and Europe. Innovation efforts predominantly revolve around leveraging AI and machine learning to automate vendor assessments, streamline procurement processes, and improve compliance. R&D investments are prioritized to develop advanced analytics and integration capabilities, providing differentiation in an increasingly competitive landscape. Additionally, companies engage in strategic alliances with technology providers and consultants to expand their service offerings and accelerate deployment. Such strategies, combined with continuous technological advancements, underpin the competitive dynamics, positioning vendors to sustain growth and adapt amidst evolving market demands.
Leading Company Profiles
The global vendor management software market is highly competitive, featuring a mix of established technology giants and innovative startups striving to deliver comprehensive solutions across various industries. These companies focus on integrating advanced analytics, artificial intelligence, and automation capabilities to streamline vendor management processes, enhance compliance, and optimize spend management while expanding their product portfolios to address specific vertical needs and scale globally.
- SAP SE
- Oracle Corporation
- IBM Corporation
- GEP Worldwide
- Ivalua Inc.
- Jaggaer
- Basware Corporation
- Proactis Holdings Ltd.
- Zycus Infocom Pvt Ltd.
SAP SE
SAP SE offers extensive vendor management solutions embedded within its broader enterprise resource planning (ERP) ecosystem, leveraging AI-driven analytics and cloud capabilities to enhance procurement lifecycle management and vendor performance monitoring.
Oracle Corporation
Oracle provides a comprehensive cloud-based vendor management platform emphasizing automation, integrative risk management, and spend analysis, with strategic investments in AI and machine learning to bolster predictive insights and vendor collaboration tools.
Coupa specializes in cloud-native procurement and vendor management solutions that emphasize user experience, real-time analytics, and integrated financial management, targeting global enterprises seeking to optimize spend and vendor relationships efficiently.
IBM Corporation
IBM leverages its AI and blockchain expertise to deliver advanced vendor management solutions focusing on compliance, transparency, and supply chain risks, with strategic initiatives aimed at integrating emerging technologies into its core offerings.
GEP Worldwide
GEP offers integrated supply chain and vendor management solutions tailored for large-scale enterprises, emphasizing strategic procurement, analytics, and digital transformation to optimize vendor performance and reduce costs.
Ivalua Inc.
Ivalua provides a flexible, cloud-based vendor management platform that integrates with procurement and finance systems, focusing on supplier collaboration, risk management, and automation for global organizations.
Jaggaer
Jaggaer delivers a comprehensive suite of spend management solutions, including vendor management, sourcing, and procurement, emphasizing AI-driven insights and automation for enterprise-level clients across multiple sectors.
Basware Corporation
Basware offers cloud-based procure-to-pay and vendor management solutions focusing on automation, analytics, and compliance, with a strategic emphasis on expanding its AI and machine learning capabilities to improve vendor insights.
Proactis Holdings Ltd.
Proactis provides spend management and supplier engagement SaaS solutions aimed at mid-market and large organizations, prioritizing cost control, procurement efficiency, and supplier collaboration enhancements.
Zycus Infocom Pvt Ltd.
Zycus specializes in artificial intelligence-driven procurement and vendor management software, aiming to transform procurement processes with automation, analytics, and supplier performance management tools for large enterprises.
Strategic Business Developments
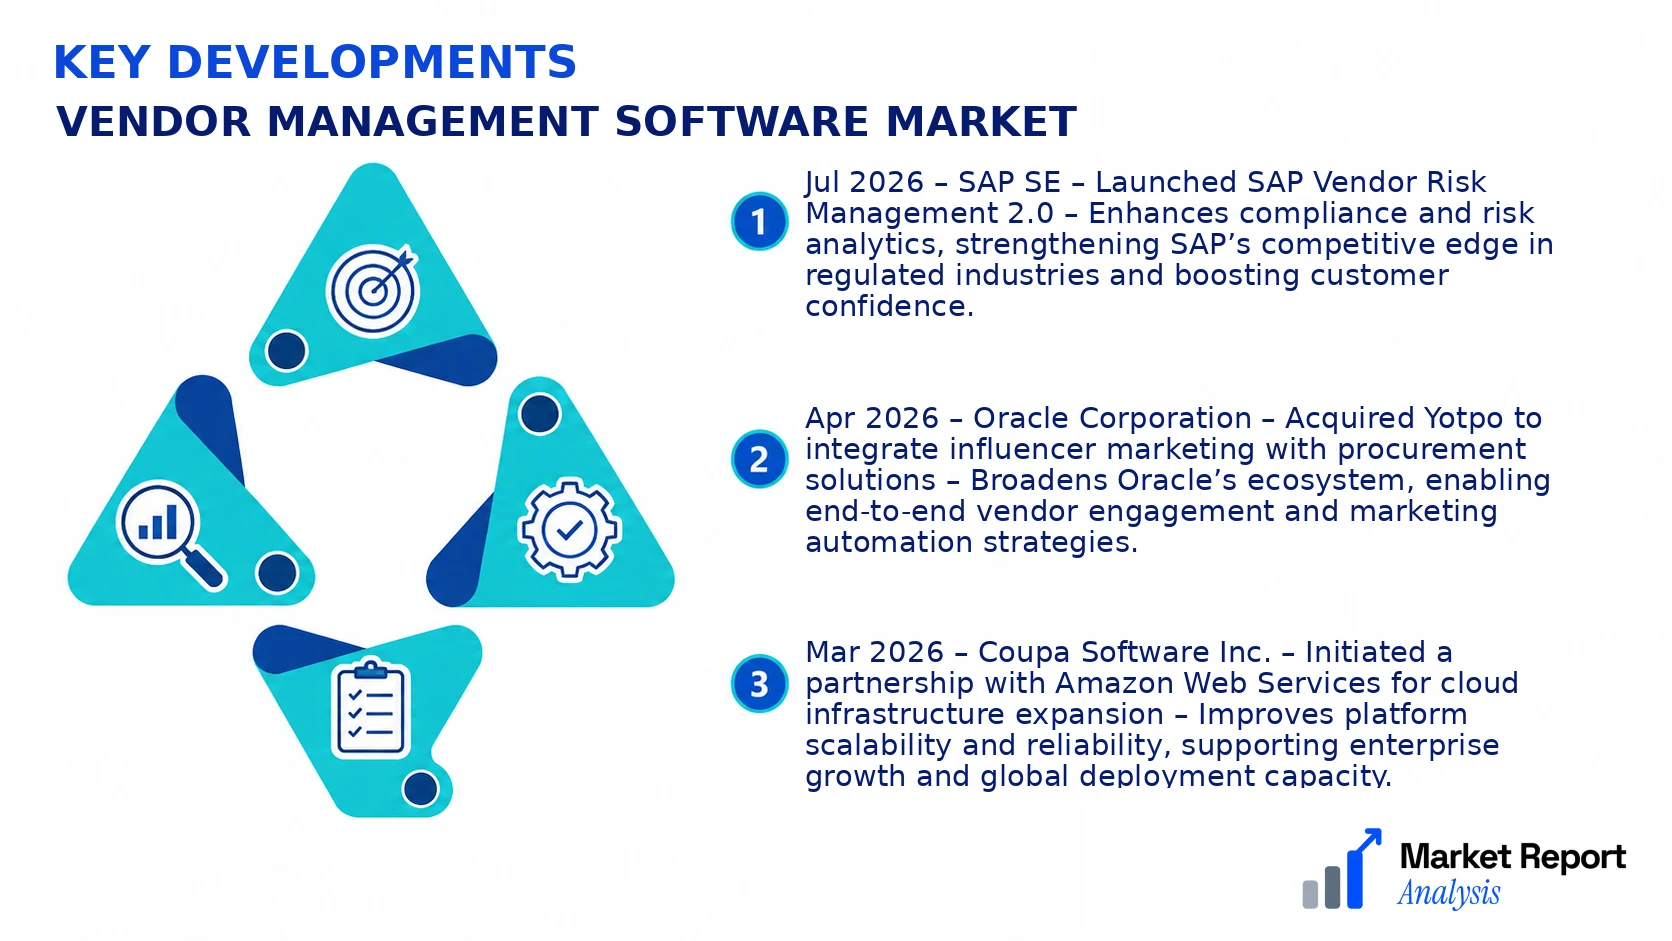
- Jul 2026 – SAP SE – Launched SAP Vendor Risk Management 2.0 – Enhances compliance and risk analytics, strengthening SAP’s competitive edge in regulated industries and boosting customer confidence.
- Apr 2026 – Oracle Corporation – Acquired Yotpo to integrate influencer marketing with procurement solutions – Broadens Oracle’s ecosystem, enabling end-to-end vendor engagement and marketing automation strategies.
- Mar 2026 – Coupa Software Inc. – Initiated a partnership with Amazon Web Services for cloud infrastructure expansion – Improves platform scalability and reliability, supporting enterprise growth and global deployment capacity.
- Feb 2026 – IBM Corporation – Announced new AI-powered analytics engine for vendor performance tracking – Provides real-time insights, improving decision-making and strategic vendor relationship management.
- Jan 2026 – GEP Worldwide – Opened new innovation hub in Bangalore – Focuses on developing next-generation procurement and vendor management AI tools, reinforcing GEP’s commitment to digital leadership.
Frequently Asked Questions
What is the Vendor Management Software Market?
The Vendor Management Software Market encompasses digital solutions designed to streamline, automate, and optimize vendor-related processes, including procurement, compliance, and performance management, across various industries globally, enhancing efficiency and reducing costs.
What is the current market size of Vendor Management Software Market?
As of 2026, the global Vendor Management Software Market is valued at approximately USD 4.8 Billion, reflecting increasing adoption across sectors seeking to improve vendor relationships and operational transparency, with robust growth expected during the forecast period.
What factors are driving the Vendor Management Software Market?
Key drivers include the rising need for regulatory compliance, digital transformation initiatives, increasing adoption of cloud-based solutions, and the demand for integrated procurement processes, all contributing to enhanced supply chain resilience and cost efficiencies worldwide.
Which region dominates the Vendor Management Software Market?
North America holds the largest share of the market, driven by advanced technological infrastructure, high adoption of innovative solutions, and strict regulatory standards, with substantial growth also anticipated in Europe and Asia-Pacific regions.
Which segment is expected to grow the fastest?
The small and medium-sized enterprise (SME) segment is projected to grow at the fastest rate, owing to increasing awareness of vendor management benefits and expanding digital transformation efforts within this sector.
Who are the leading companies operating in the Vendor Management Software Market?
Major players include SAP Ariba, Coupa Software, Ivalua, GEP, and Jaggaer, which are innovating and expanding their offerings to capture a significant share of the growing global market leading to intense competitive dynamics.
Geography
The global market for vendor management software is geographically segmented into North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa. These regions exhibit varying adoption rates, driven by differing regulatory environments, technological maturity, and digital transformation initiatives.
- North America: North America holds a significant share due to early adoption of cloud technology, high digital maturity, and robust regulatory frameworks that demand sophisticated vendor management solutions, particularly in the United States and Canada.
- Europe: Europe’s market is driven by stringent compliance regulations such as GDPR, prompting increased investment in vendor management systems to ensure regulatory adherence and improve vendor oversight.
- Asia-Pacific: The Asia-Pacific region is experiencing rapid growth fueled by digital transformation initiatives, increasing outsourcing activities in emerging economies like India and China, and expanding adoption of cloud solutions.
- Latin America and Middle East & Africa: These regions are gradually adopting vendor management technologies as part of broader digital strategies, though growth rates are comparatively lower due to infrastructural and economic factors.
Analyst Perspective
The Vendor Management Software Market is approaching a mature phase, yet it continues to present significant long-term growth opportunities driven by digital transformation initiatives across industries. As organizations increasingly prioritize procurement efficiency, risk management, and compliance, demand for sophisticated vendor management solutions is projected to expand robustly through 2034. Technological evolution, particularly the integration of AI, machine learning, and real-time analytics, is expected to enhance platform capabilities, creating competitive advantages for early adopters. Investors should prioritize platforms with scalability, robust security features, and cross-functional integration to capitalize on emerging opportunities. Despite heightened competitive intensity globally, regional differences create pockets of high growth, notably in Asia-Pacific and North America, fueled by expanding digital infrastructure and evolving regulatory landscapes. Strategic focus should include fostering innovation, strengthening vendor ecosystem collaborations, and expanding geographic reach to maintain market positioning and capture new revenue streams amidst evolving technological and regulatory environments.
