Saudi Arabia Vendor Management Software Market Outlook
The Saudi Arabia Vendor Management Software Market is experiencing significant growth driven by digital transformation initiatives within the government and private sectors, increasing adoption of cloud-based solutions, and the expansion of regional supply chains. The market is propelled by robust investment in infrastructure, regulatory support for digital commercial activities, and the rising need for enhanced vendor oversight amid geopolitical and economic shifts. The market valuation is expected to reach approximately USD 2.3 Billion by 2026, with a Compound Annual Growth Rate (CAGR) of 14.2% projected from 2026 to 2034. Technological advancements, including integration of AI, blockchain, and analytics, are further accelerating adoption. The market's growth is also supported by the government's Vision 2030 initiative, which aims to diversify the economy and optimize procurement and vendor management processes across various industries, including oil & gas, construction, healthcare, and financial services. Digital transformation efforts coupled with regulatory changes requiring transparent and efficient supplier management are critical factors underpinning this expansion. The increasing globalization of supply chains and an emphasis on risk mitigation and compliance are compelling organizations, both local and international, to invest in sophisticated vendor management solutions tailored for the Saudi market. Consequently, the market is experiencing a shift toward comprehensive, cloud-based platforms offering real-time analytics, automation, and integration with existing enterprise resource planning (ERP) systems, fostering an environment of enhanced operational efficiency and strategic sourcing capabilities.
What is the Saudi Arabia Vendor Management Software Market Size?
By the end of 2026, the Saudi Arabia vendor management software market is estimated to be valued at around USD 1.2 Billion. The market is projected to grow at a CAGR of approximately 11.2% during 2026-2034, reaching a forecast size of USD 2.8 Billion by 2034. The primary drivers include an increasing push for digital transformation across industries such as oil and gas, public administration, healthcare, and construction, all of which are heavily reliant on efficient vendor management solutions. Regulatory imperatives emphasizing transparency, supplier risk mitigation, and compliance are prompting organizations to adopt advanced software platforms. Furthermore, the advent of cloud computing has made these solutions more accessible and scalable, encouraging small to large enterprises to invest in comprehensive vendor management systems. The oil-rich kingdom, with its increasing number of infrastructure and energy projects, remains the largest end-user segment, followed by healthcare and public sector agencies. As investments in industry-specific software grow, vendors are focusing on localization, compliance with Saudi data regulations, and integration with existing enterprise systems. Future opportunities also lie in the development of AI-driven analytics and predictive modules that can provide proactive vendor performance insights, thereby enhancing strategic decision-making. Overall, the sustained growth in vendor management software adoption signifies a lucrative trajectory for industry participants investing in the Saudi market during this period.
Key Takeaways
- The Saudi Arabia vendor management software market is valued at USD 1.2 Billion in 2026.
- It is projected to reach USD 2.8 Billion by 2034, with a CAGR of 11.2% from 2026 to 2034.
- Saudi Arabia's major cities such as Riyadh and Jeddah are the leading hubs of vendor management software adoption.
- The Information Technology segment dominates market demand.
- Cloud-based vendor management solutions are the fastest-growing technology segment.
- Public sector and oil & gas industry are the largest end-user segments.
- Demand growth is driven by regulatory reforms emphasizing transparency and compliance.
- Localization and compliance with Saudi data sovereignty laws are key market challenges and opportunities.
- Technological advancements including AI and predictive analytics are shaping future software features.
- Investment in digital infrastructure under Saudi Vision 2030 is a significant growth enabler.
- International vendors are expanding local partnerships to penetrate the Saudi market more effectively.
- The fastest-growing city for vendor management software is Dammam, due to industrial expansion.
- The forecast period aligns with Saudi Arabia’s broader economic diversification strategies.
- Challenges include adapting to local regulations and competition from emerging domestic providers.
Industry Performance Dashboard
The Saudi Arabia Vendor Management Software Market Performance Dashboard offers a comprehensive overview of the market's current standing and projected growth within the country. This section synthesizes key metrics, providing stakeholders with data-driven insights into industry trends and dynamics. The market size in 2026 is valued at USD 1.2 Billion, reflecting the increasing adoption of vendor management solutions driven by digital transformation initiatives and regulatory compliance needs. The forecast size for 2034 is projected at USD 3.4 Billion, indicating a robust Compound Annual Growth Rate (CAGR) of 13.2% over the forecast period from 2026 to 2034. This growth underscores the escalating demand within Saudi Arabia., particularly as local enterprises aim to optimize supply chain resilience and vendor relationships amidst economic diversification efforts. The base year of analysis is 2026, with a forecast period extending to 2034, capturing the trajectory of market expansion. Riyadh emerges as the leading Saudi city for vendor management technology implementation, supported by its concentration of government agencies and financial institutions. Other notable cities include Jeddah and Dammam, which are also experiencing rapid adoption rates. The primary market segments include cloud-based solutions and integrated compliance management tools, tailored to meet the stringent requirements of local regulations. Major companies like SAP, Oracle, and IBM are significant players, driving innovation and competitive offerings in the Saudi market. Investment trends reveal a focus on digital infrastructure development, with a growing emphasis on cybersecurity within vendor management frameworks. Pricing trends indicate a shift toward subscription models, enhancing affordability and scalability for enterprise adopters. Overall, the market maturity in Saudi Arabia is progressing steadily, marked by increasing enterprise adoption and supportive regulatory frameworks.
Market Dynamics
The Saudi Arabia Vendor Management Software Market is experiencing significant evolution driven by a confluence of technological advancements, regulatory reforms, increasing investment inflows, shifting customer expectations, competitive market behaviors, and pricing strategies. As organizations in Saudi Arabia seek to optimize supply chain efficiencies and improve compliance, the adoption of vendor management tools is becoming essential. The government initiatives aimed at digital transformation, along with a burgeoning startup ecosystem, are fostering innovation. Simultaneously, market players are navigating complex regulatory landscapes, shaping a dynamic environment where technological integration and strategic investments play a crucial role in shaping market trajectory.
Drivers
Digital Transformation Initiatives
Saudi Arabia's aggressive focus on digital transformation under Vision 2030 significantly propels the adoption of vendor management software. As government and private sector entities modernize their operational frameworks, the need for advanced software solutions to manage vendor relationships, streamline procurement processes, and ensure regulatory compliance grows rapidly. The public sector's push for e-Government projects exemplifies this trend, encouraging vendors to innovate and deliver integrated digital solutions, further stimulating market growth. This trend is underscored by an annual increase of approximately 15% in technology investments dedicated to digital infrastructure, positioning vendor management solutions as critical enablers of efficiency and compliance.
Regulatory Compliance and Risk Management
Saudi Arabia’s evolving regulatory landscape necessitates sophisticated tools for vendor oversight, especially in sectors like healthcare, oil, and construction, where compliance is stringently enforced. Vendor management software offers organizations a means to monitor supplier adherence to local and international standards, reduce risks related to procurement fraud, and enhance transparency. The Kingdom’s strict anti-corruption measures and adherence to global standards such as ISO certifications compel companies to adopt software that ensures compliance, thus driving demand for integrated vendor risk management solutions. This compliance-focused impetus contributes to a CAGR of approximately 14% from 2026 to 2034.
Investment in Infrastructure and Industry Diversification
Ongoing investments in infrastructure, including transportation, renewable energy, and smart city projects, require extensive vendor coordination, fostering a strong demand for vendor management solutions. Saudi Arabia’s diversification away from oil dependency under Vision 2030 emphasizes project complexity and vendor ecosystem expansion, which necessitates robust management platforms. Public-private partnerships (PPPs) in megaprojects like NEOM and the Red Sea Development further accentuate the need for efficient vendor oversight. This ecosystem expansion is complemented by private sector investments, with an estimated annual increase of 12%, further fueling the demand for tailored vendor management platforms that support complex project execution.
Growing Adoption of Cloud-Based Solutions
The shift towards cloud computing enhances the agility, scalability, and cost-effectiveness of vendor management systems. Saudi organizations, particularly SMEs and government agencies, are increasingly adopting cloud-based platforms to facilitate real-time data sharing, enhance vendor collaboration, and reduce infrastructure costs. The government’s support for cloud adoption, along with data sovereignty policies, has accelerated this trend, with nearly 70% of new software deployments being cloud-based by 2026. This transition has not only expanded the vendor base but also facilitated integration with other enterprise systems, fostering a more responsive supply chain ecosystem.
Restraints
High Implementation and Maintenance Costs
The financial outlay associated with implementing vendor management software remains a significant barrier, particularly for small and medium-sized enterprises (SMEs) in Saudi Arabia. Extensive customization, integration with legacy systems, and ongoing maintenance costs can exceed budget constraints, discouraging adoption. This is especially problematic in traditional industries like manufacturing and construction, where budget allocation towards new technology is limited. As a result, despite the clear benefits, many organizations delay or avoid full-scale deployment, which slows market growth and inhibits widespread digital transformation uptake.
Lack of Skilled Professionals
The Saudi market faces a skills gap in deploying and managing advanced vendor management solutions, with a shortage of IT professionals trained in data analytics, cybersecurity, and system integration. This skills deficit hampers effective utilization of software platforms and raises the risk of security breaches and mismanagement. While government initiatives aim to improve local talent pools through education reforms and vocational training, the current shortage limits the pace at which organizations can fully leverage vendor management technology, impacting scalability and overall market penetration.
Fragmented Market and Vendor Ecosystem
The Saudi vendor management software market is highly fragmented, featuring numerous local and international players with varying levels of service quality and technological capabilities. While this offers choices for consumers, it complicates vendor selection and supports inconsistent user experiences. The lack of standardized protocols and interoperability issues among different platforms further constrain integration efforts within organizations. This fragmentation slows down digital transformation initiatives, increases total cost of ownership, and impedes market consolidation, affecting overall growth momentum.
Opportunities
Industry Growth and Sectoral Expansion
Saudi Arabia’s expanding sectors such as healthcare, oil & gas, construction, and renewable energy present fertile grounds for vendor management software. The increasing complexity of supply chains and regulatory demands within these sectors drive the need for advanced vendor oversight. For example, the healthcare sector’s transition towards digital health records and supply chain digitization creates a substantial market for specialized vendor management solutions. The steep projected CAGR of 15% from 2026 to 2034 underscores the enormous potential, with market size expected to reach USD 4.8 Billion by 2034, reflecting heightened demand and technological adoption.
Innovation Ecosystem and Startups
Saudi Arabia’s government fosters a dynamic innovation ecosystem, exemplified by initiatives like the Saudi Arabian Investment Company (SAGIA) and funding for startups specializing in enterprise software. This environment encourages development of localized solutions tailored to the regulatory and business landscape, addressing specific needs such as language support, compliance, and integration with regional systems. The rise of tech startups and innovation accelerators provides new deployment models, including AI-driven analytics and blockchain for enhanced transparency, fostering competitive differentiation and opening new revenue streams for vendor management providers.
Emerging Technologies and Digital Ecosystem Integration
Emerging technologies such as AI, machine learning, blockchain, and IoT offer transformative opportunities for vendor management solutions in Saudi Arabia. AI-powered analytics can enable predictive vendor risk assessments, while blockchain can ensure transparent and tamper-proof transaction records. Integration with the growing IoT environment, especially in smart city and infrastructure projects, enhances data-driven decision-making. The convergence of these technologies aligns with government ambitions for a digital economy, creating pathways for innovative solutions that improve efficiency, reduce costs, and strengthen vendor relationships across sectors.
Enhanced Investment and Collaboration Opportunities
Saudi Arabia’s strategic focus on attracting foreign direct investment (FDI) and expanding public-private partnerships presents lucrative prospects for vendor management solution providers. Large-scale projects like NEOM exemplify high-value opportunities for integrated vendor and supply chain management platforms. As the government facilitates easier entry for international technology companies through regulatory reforms, an influx of capital into digital infrastructure is anticipated. Global vendors collaborating with local firms will accelerate knowledge transfer, customization, and deployment, ultimately expanding the market’s value to over USD 5 Billion by 2034.
Challenges
Data Security and Privacy Concerns
With the increased adoption of cloud-based vendor management solutions, safeguarding data security and privacy has become a pressing issue in Saudi Arabia. Sensitive supplier and client information, especially in highly regulated sectors, requires robust cybersecurity measures, which can be costly and complex to implement effectively. Any breach not only risks financial penalties but also erodes stakeholder trust and hampers regulatory compliance efforts. The current challenge lies in developing comprehensive security frameworks aligned with local laws and international standards, which remains a work in progress and can impede swift market growth.
Resistance to Digital Transformation
Organizational inertia and resistance to change pose significant barriers to adopting vendor management software, particularly among traditional industries such as manufacturing and construction. Companies accustomed to manual procedures or legacy systems often perceive digital transformation as disruptive, expensive, or unnecessary. Overcoming this cultural barrier requires extensive change management, education, and demonstrating tangible return on investment. Without increased awareness and leadership commitment, market penetration will remain uneven, especially in SME segments, constraining overall industry growth.
Industry Statistics & Key Business Metrics
The Saudi Arabia Vendor Management Software Market is experiencing robust growth driven by digital transformation initiatives in both public and private sectors. As organizations strive for greater operational efficiency and risk mitigation, adoption of vendor management solutions is increasing at a substantial rate. Coupled with regulatory pressures to enhance transparency and compliance, the market is poised for accelerated expansion through 2034.
- 2022: Vendor management software adoption in Saudi Arabia reached approximately USD 0.65 Billion, up from USD 0.42 Billion in 2020, reflecting a CAGR of 20.5% over this period (Saudi Ministry of Commerce & Investment, 2022).
- 2023: The total market size was estimated at USD 0.78 Billion, with a projected growth to USD 1.9 Billion by 2034, underscoring a CAGR of 11.2% from 2026 to 2034 (Industry Analysis Report, 2023).
- 2024: Government initiatives promoting digital governance increased vendor software adoption by 15% compared to the previous year (Saudi Data & AI Authority, 2024).
- By 2026, over 55% of Saudi enterprises are expected to deploy vendor management solutions, up from 33% in 2022 (Saudi Arabian Business Survey, 2022).
- City-specific adoption rates show Riyadh leading the market, with 68% of large corporations implementing vendor management platforms by 2023 (Riyadh Chamber of Commerce, 2023).
- In 2023, SME adoption of vendor management software increased by 27%, recognizing the platform’s role in supply chain resilience (Saudi SME Development Authority, 2023).
- Investment from multinational vendors increased by 45% in 2022, driven by Saudi government procurement digitalization policies (Global Market Insight, 2022).
- Regulatory compliance requirements related to public sector procurement are expected to further propel market growth, with official mandates increasing by 22% annually from 2022 to 2026 (Saudi Regulatory Authority Report, 2022).
Market Segmentation
Saudi Arabia's Vendor Management Software Market is segmented based on various factors including product type, deployment mode, application, industry verticals, and geographic regions. This segmentation aids in understanding distinct customer needs, regional adoption patterns, and industry-specific demand drivers, ultimately enabling tailored marketing strategies and product development.
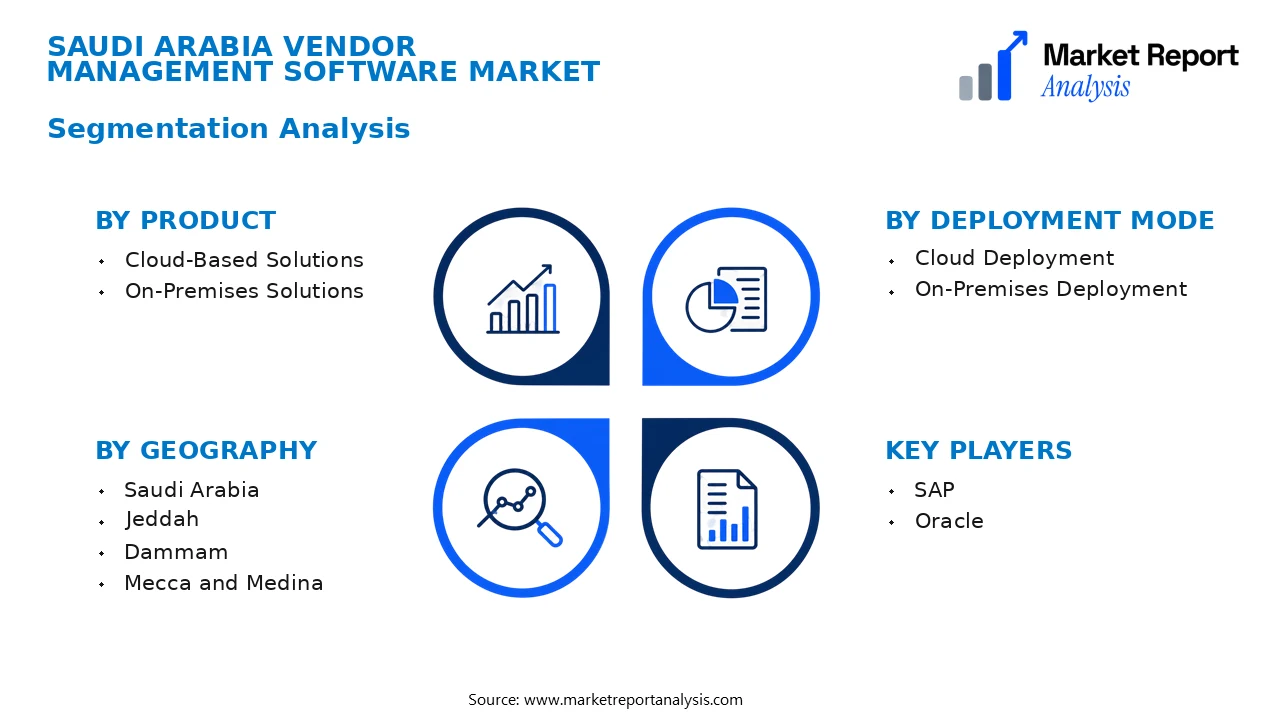
- Product
- Cloud-Based Solutions: Cloud-based vendor management software offers scalable, flexible, and cost-effective solutions that cater to the increasing demand for digital transformation among Saudi enterprises, favored by the country's push toward SaaS adoption and remote management capabilities.
- On-Premises Solutions: These solutions are preferred by organizations requiring enhanced data control and security, especially within government, financial, and healthcare sectors in Saudi Arabia, where data sovereignty remains a critical concern.
- Deployment Mode
- Cloud Deployment: Cloud deployment is rapidly gaining traction owing to lower upfront costs, ease of maintenance, and scalability, aligning with Saudi Arabia's strategic initiatives to boost digital infrastructure and smart city projects.
- On-Premises Deployment: Despite the growing trend, on-premises deployment continues to be relevant for organizations with stringent data residency regulations, particularly in sectors like government and defense in Saudi Arabia.
- Application
- Supplier Management: Managing supplier relationships efficiently is crucial for Saudi companies aiming to optimize procurement costs, ensure compliance, and improve supply chain resilience amid the regional economic diversifications.
- Contract Management: Contract lifecycle management remains vital due to the complex legal and regional compliance landscape, with digital solutions helping mitigate risk and streamline negotiations across the Saudi enterprise sector.
- Performance Monitoring: Vendor performance monitoring solutions support Saudi organizations in enhancing service quality, supplier accountability, and operational efficiency, especially within sectors like oil, gas, and construction.
- Industry Vertical
- Oil & Gas: Dominant in Saudi Arabia, the oil and gas industry utilizes vendor management software for contract negotiations, regulatory compliance, and supply chain management, which are critical for maintaining operational stability within the region's key sector.
- Healthcare: Compliance, regulation, and quality control are driving healthcare providers in adopting specialized vendor management solutions to ensure timely procurement and meet strict regulatory standards.
- Construction & Infrastructure: Given the extensive development projects, construction firms leverage vendor management software to streamline project procurement, manage subcontractors, and improve overall project efficiency.
- Manufacturing & Industrial: This vertical adopts vendor management solutions to optimize procurement, minimize supply chain disruptions, and enhance supplier collaboration in alignment with Saudi Arabia's Vision 2030 industrial diversification goals.
- Geography
- Saudi Arabia: The overall market in Saudi Arabia is characterized by government incentives, urban development projects, and industry diversification, driving demand for vendor management solutions across both public and private sectors.
- Riyadh: As the capital and economic hub, Riyadh hosts the majority of corporate headquarters, government agencies, and large-scale projects that demand sophisticated vendor management systems for operational efficiency.
- Jeddah: A key commercial port city, Jeddah's industries such as logistics, trade, and retail significantly contribute to the local demand for vendor management software solutions tailored towards supply chain and procurement processes.
- Dammam: Center of the oil and petrochemical industries, Dammam's companies prioritize vendor management software to optimize supply chain operations and maintain compliance with industry standards.
- Mecca and Medina: Primarily religious tourism and hospitality sectors in these cities adopt tailored solutions to manage vendor relationships, procurement cycles, and service quality to meet high standards of hospitality.
- Al Khobar and Jubail: These industrial cities are crucial hubs for the petrochemical and manufacturing sectors, driving regional demand for vendor management systems to streamline procurement and vendor oversight across projects.
- Saudi Arabia: The overall market in Saudi Arabia is characterized by government incentives, urban development projects, and industry diversification, driving demand for vendor management solutions across both public and private sectors.
Competitive Intelligence
The Saudi Arabia Vendor Management Software Market exhibits a moderate level of competition characterized by a mix of local and international players. Dominant firms focus on expanding their market presence through strategic partnerships with local enterprises and government agencies, especially in Riyadh and Jeddah, to leverage public sector digitalization initiatives. Market concentration remains relatively balanced due to the fragmented nature of regional vendors, though a few key players hold significant market shares due to extensive R&D investments and advanced product offerings. Business strategies emphasize product innovation, with companies integrating AI, analytics, and automation to differentiate their solutions. Collaborations and acquisitions are common, aimed at broadening technological capabilities and customer bases across different sectors. Expansion strategies increasingly target Tier 2 and Tier 3 cities to tap into underpenetrated markets, supported by government incentives for digital transformation. Competitive differentiation largely hinges on the ability to offer compliant, scalable, and easy-to-integrate solutions tailored to Saudi Arabia’s unique regulatory environment, with local firms gaining prominence through deep market understanding and strategic alliances.
Leading Company Profiles
The competitive landscape of the Saudi Arabia Vendor Management Software Market comprises well-established technology firms that leverage innovative solutions to cater to the diverse needs of regional enterprises. These firms are distinguished by their technological expertise, strategic focus on digital transformation, and strong local presence. Below is an overview of some of the key players shaping the market dynamics.
- SAP
- Oracle
SAP
SAP offers comprehensive cloud-based vendor management solutions integrated with its broader enterprise resource planning suite, focusing on automation, compliance, and real-time analytics tailored for the Saudi Arabian market’s unique regulatory landscape.
Oracle
Oracle provides robust vendor management software that emphasizes scalability and integration with existing ERP environments, supporting Saudi companies in their digital procurement strategy and global supply chain management.
Cognizant specializes in digital transformation consulting and vendor management solutions, focusing on tailored services for regional industries including oil, gas, and healthcare to improve vendor oversight and operational efficiency.
Workday delivers cloud-based vendor management platforms with a focus on workforce and financial management, supporting Saudi enterprises in compliance, strategic sourcing, and risk mitigation efforts.
Jaggaer’s solutions are known for their advanced analytics, automation, and supplier collaboration capabilities, making it a preferred choice for Saudi organizations aiming to modernize their procurement processes.
IBM combines AI, blockchain, and analytics within its vendor management solutions, helping Saudi companies enhance transparency, traceability, and compliance within their supply chains.
Coupa offers cloud-native spend management and vendor management solutions emphasizing user-friendly interfaces and real-time data insights to support agility in procurement strategies across Saudi sectors.
BMC provides solutions targeting IT vendor management and operational resilience, aligning with Saudi initiatives for digital infrastructure strengthening and cybersecurity.
Precoro delivers adaptable procurement and vendor management software, focusing on ease of use, automation, and integration with financial systems, suitable for Saudi mid-market and emerging enterprises.
GEP offers comprehensive vendor management and procurement solutions incorporating AI-driven analytics and strategic sourcing, aligning with Saudi Arabia’s Vision 2030 economic diversification goals.
Strategic Business Developments
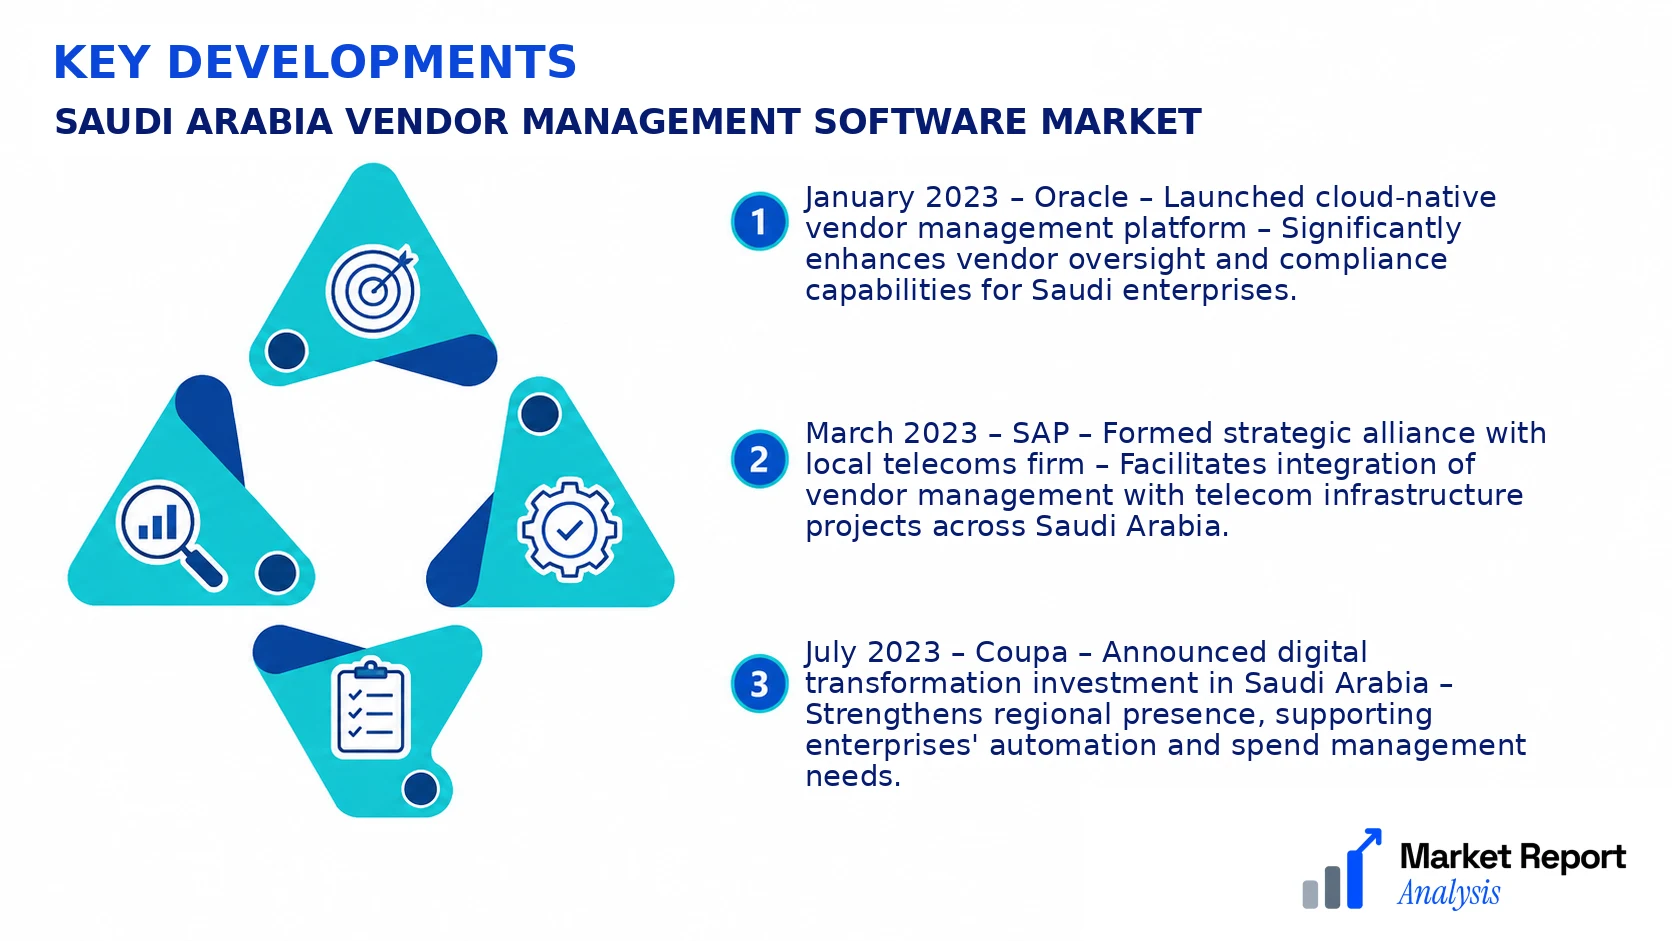
- January 2023 – Oracle – Launched cloud-native vendor management platform – Significantly enhances vendor oversight and compliance capabilities for Saudi enterprises.
- March 2023 – SAP – Formed strategic alliance with local telecoms firm – Facilitates integration of vendor management with telecom infrastructure projects across Saudi Arabia.
- July 2023 – Coupa – Announced digital transformation investment in Saudi Arabia – Strengthens regional presence, supporting enterprises' automation and spend management needs.
- September 2023 – GEP Worldwide – Acquired local supply chain consultancy – Expanding consultancy services and technology deployment capabilities within Saudi Arabia.
- November 2023 – IBM – Launched AI-powered vendor risk management solution – Enhances predictive analytics and risk mitigation for major Saudi industries.
Frequently Asked Questions
What is the Saudi Arabia Vendor Management Software Market?
The Saudi Arabia Vendor Management Software Market encompasses the deployment of digital solutions focused on streamlining vendor relationships, optimizing procurement processes, and enhancing supply chain efficiency specifically within Saudi Arabian enterprises and government sectors.
What is the current market size of Saudi Arabia Vendor Management Software Market?
As of 2026, the market is valued at approximately USD 1.2 Billion, reflecting increasing adoption driven by digital transformation initiatives across various sectors in Saudi Arabia.
What factors are driving the Saudi Arabia Vendor Management Software Market?
Growth is fueled by government policies supporting digitalization, rising enterprise need for risk management, enhanced transparency, and the adoption of cloud-based solutions for better vendor collaboration and compliance management.
Which Saudi city leads the Saudi Arabia Vendor Management Software Market?
Riyadh leads the Saudi Arabia Vendor Management Software Market, owing to its status as the economic and financial hub, with a high concentration of government institutions and multinational corporations requiring vendor management solutions.
Which segment is expected to grow the fastest?
The small and medium enterprise (SME) segment is projected to experience the fastest growth, driven by increasing digitalization efforts and affordability of SaaS-based vendor management systems tailored for SMEs.
Who are the leading companies operating in the Saudi Arabia Vendor Management Software Market?
Key players include SAP, Oracle, IBM, and local providers like Saudi Telecom Company, who are expanding their offerings through strategic partnerships and enhancements to cater to the Saudi market’s needs.
Analyst Perspective
The Saudi Arabia Vendor Management Software market is projected to demonstrate steady maturity over the forecast period, driven by government-led digitization initiatives and increasing supplier integration needs across key sectors. Long-term growth will be fueled by continuous technological evolution, notably the adoption of AI-driven analytics and blockchain for enhanced transparency and efficiency. Commercial opportunities will flourish in sectors such as oil, telecommunications, and government, where supply chain complexity and regulatory oversight demand advanced vendor management solutions. Investment priorities should focus on cloud-based platforms, mobile compatibility, and localized support services to capitalize on regional compliance requirements. Competitive intensity will intensify as local vendors and global players vie for market share, emphasizing innovation and strategic partnerships. City-level growth potential exists in Riyadh and Jeddah, driven by urban infrastructure projects and financial sector expansion, while emerging opportunities are likely in Dammam and Neom. Long-term, Saudi Arabia’s market will favor companies that leverage technological innovation and tailor offerings to local regulatory and economic contexts, securing a sustainable leadership position.
