Latin America Vendor Management Software Market Outlook
The Latin America Vendor Management Software (VMS) market is currently valued at USD 2.3 Billion, with projections indicating an increase to USD 4.8 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 10.5% over the forecast period from 2026 to 2034. The principal drivers fueling this expansion include the escalating need for streamlined procurement processes, increased adoption of digital transformation initiatives within enterprises, and heightened emphasis on supply chain transparency and risk mitigation. Technological advancements, particularly the integration of AI and machine learning, are further facilitating improved vendor evaluation, performance monitoring, and compliance management. Commercial opportunities are abundant, especially for vendors offering cloud-based solutions, tailored regional compliance modules, and analytics-driven features that provide actionable insights for businesses operating across diverse Latin American markets.
What is the Latin America Vendor Management Software Market Size?
In 2026, the Latin America Vendor Management Software market is valued at approximately USD 2.3 Billion. It is forecasted to reach around USD 4.8 Billion by 2034, reflecting a CAGR of 10.5% during this period. The growth is primarily driven by the increasing digitalization of procurement and supply chain functions across various industries such as manufacturing, retail, healthcare, and government agencies. The expansion of regional economic zones and the rising complexity of vendor networks further contribute to the demand for sophisticated VMS solutions. Technological innovations, including cloud computing, AI, and data analytics, are enabling vendors to deliver more efficient, scalable, and intelligent platforms, thus attracting more enterprise adoption. Additionally, regulatory pressures and an increasing focus on sustainable and ethical sourcing practices are reinforcing investments in vendor management solutions. As Latin American companies seek competitive advantages through digital tools, market entrants are also anticipated to explore new avenues for growth, including vertical-specific and modular VMS offerings tailored to regional business needs.
Key Takeaways
- The Latin America Vendor Management Software market was valued at USD 2.3 Billion in 2026.
- It is projected to expand to USD 4.8 Billion by 2034, achieving a CAGR of 10.5%.
- The largest segment by deployment is cloud-based solutions.
- The fastest-growing segment is AI-enabled vendor analytics platforms.
- The retail and manufacturing sectors constitute the largest application areas.
- Supply chain management and compliance are the major application focuses.
- The healthcare sector is the fastest-growing end user, driven by enhanced regulatory requirements.
- The market is driven by rising digital transformation initiatives and supply chain transparency needs.
- Increased regional economic integration fosters more vendor relationships requiring management solutions.
- Emerging technologies, including AI and data analytics, are key to future innovation in VMS.
- Competitive landscape is intensifying with both regional and global vendors expanding offerings.
- Investments in scalable, flexible, and compliance-oriented solutions are gaining momentum.
- Regional regulatory frameworks are influencing features and deployment strategies.
Industry Performance Dashboard
The Industry Performance Dashboard for the Latin America Vendor Management Software Market offers a comprehensive overview of key market indicators, tracking growth trends and competitive dynamics within the region. This dashboard provides crucial quantitative insights that support strategic decision-making and market analysis. The market size was valued at USD 2 Billion in 2025, reflecting the increasing adoption of vendor management solutions driven by digital transformation initiatives across industries. Projected to reach USD 4.3 Billion by 2034, the market is expected to grow at a Compound Annual Growth Rate (CAGR) of 9.3% during the forecast period from 2026 to 2034. This consistent growth underscores the rising importance of vendor management software in optimizing supply chain operations, reducing costs, and ensuring compliance within diverse Latin American markets. The base year for this analysis is 2026, providing a snapshot of current industry positioning, with forecasts extending to 2034 to outline future trends. The primary segments covered include cloud-based solutions, on-premise implementations, and hybrid models, highlighting the sector's technological evolution. Major companies influencing the market landscape include SAP SE, IBM Corporation, Oracle Corporation, Coupa Software, and Ariba Inc., which are driving innovation and competitive rivalry. Investment trends suggest increasing funding in cloud and AI-enabled vendor management platforms, aligning with broader digital transformation agendas. Pricing trends indicate a favorable shift towards subscription-based models, making solutions more accessible to small and medium enterprises. Overall, the market maturity level remains moderate, with ongoing technological advancements fostering increased adoption and competitive pressure.
Market Dynamics
The Latin America vendor management software market is experiencing dynamic shifts driven by technological advancements, evolving regulations, increased investment, and changing customer requirements. Companies in the region are seeking more agile, transparent, and compliant vendor management solutions to streamline their supply chains and mitigate risks. Competitive behavior is intensifying with local and international players innovating to capture market share, while pricing strategies are adapting to increased demand and market maturity. Supply conditions fluctuate with regional economic and infrastructural factors, influencing software deployment and adoption. Overall, these forces are shaping a highly competitive environment characterized by rapid innovation, increased collaboration, and expanding digital infrastructure, fostering substantial growth opportunities in the market.
Drivers
Digital Transformation Initiatives
Latin American enterprises are increasingly integrating vendor management solutions as part of their broader digital transformation strategies. Companies recognize that automating vendor workflows, enhancing data analytics, and improving compliance are crucial for operational efficiency. For instance, the adoption of cloud-based vendor management platforms allows organizations to access real-time data and facilitate remote collaboration. Market trends show a consistent increase in digital initiatives prioritizing supply chain resilience, which directly contributes to demand for sophisticated vendor management tools. This shift is supported by the regional move toward Industry 4.0 practices, modernizing traditional procurement and vendor oversight processes.
Regulatory Compliance and Risk Management
Stringent regional and international regulations necessitate advanced vendor management systems to ensure compliance and mitigate risks. Latin American countries are strengthening anti-bribery, corruption, and environmental standards, compelling companies to adopt robust software solutions that provide transparency and comprehensive audit trails. A surge in compliance-driven procurement practices is evident, with multinational corporations especially investing in vendor management software to align with global standards such as ISO or local legislation. The requirement for compliance is further propelled by trade agreements and cross-border collaborations that demand standardized oversight, thereby accelerating demand within highly regulated sectors like manufacturing, energy, and pharmaceuticals.
Growing E-Commerce and Digital Economy
The explosive growth of e-commerce across Latin America underpins the expansion of vendor management software, particularly in logistics, payments, and supply chain coordination. E-commerce giants and logistics providers require scalable solutions to oversee vast vendor networks and automate procurement processes. Consumer demand for faster delivery and better service levels is prompting investments in integrated supply chain platforms. Enhanced digital payments and transaction transparency are also propelling the adoption of vendor management solutions, with regional e-commerce sales expected to grow at a CAGR of around 23% from 2026 to 2034, further fueling software deployment needs.
Market Fragmentation and Vendor Ecosystem Expansion
Latin America's vendor landscape is characterized by high fragmentation, with numerous small and medium-sized enterprises (SMEs) operating across diverse industries. This fragmentation creates a pressing need for scalable, easy-to-integrate vendor management solutions to optimize procurement and supplier relationships. As regional industries diversify and SME contributions grow, demand for tailored software that supports local vendor ecosystems intensifies. Innovative platforms leveraging AI and data analytics are emerging to address these needs, fostering a competitive environment that encourages software providers to customize offerings for regional nuances, ultimately expanding the market’s size and sophistication.
Restraints
High Implementation Costs
The initial financial outlay for deploying vendor management software remains a significant barrier for many Latin American companies, especially SMEs and organizations in cost-sensitive sectors. The expense encompasses licensing, customization, integration, and training, which can deter swift adoption. In regions where budget constraints are prevalent, companies often prioritize other operational costs over sophisticated vendor management systems, delaying or limiting deployment. This restraint is further compounded in areas with less developed IT infrastructure, where the cost of network upgrades and maintenance adds to the financial burden, constraining market growth in the short term.
Lack of Skilled Personnel and Awareness
A widespread lack of skilled IT professionals and awareness about vendor management solutions hinders market penetration. Many organizations in Latin America lack specialized staff to implement, manage, and optimize these systems, leading to a preference for manual processes or minimal digital transformation. Additionally, regional decision-makers may be unaware of the strategic benefits of vendor management software, resulting in slow adoption rates. This skills gap is particularly pronounced in rural areas and smaller companies, posing an obstacle to widespread technological advancement and creating a need for training programs and awareness campaigns to catalyze growth.
Data Security and Privacy Concerns
Data security remains a paramount concern, especially given the increasing sophistication of cyber threats targeting supply chain and vendor data. Latin American companies may hesitate to fully embrace cloud-based vendor management solutions due to fears of data breaches, intellectual property theft, or non-compliance with data protection regulations such as GDPR or local laws. These concerns can influence cautious adoption, particularly in sensitive sectors like healthcare and finance. Providers must address these apprehensions through enhanced cybersecurity measures, compliance assurances, and robust data governance frameworks to facilitate greater market acceptance and mitigate potential liabilities.
Opportunities
Integration of Artificial Intelligence and Machine Learning
The integration of AI and ML into vendor management software presents critical opportunities for the Latin American market to enhance predictive analytics, automate routine processes, and identify vendor risks more proactively. AI-driven solutions can analyze vast datasets for supplier performance, creditworthiness, and compliance issues, enabling companies to make better-informed decisions. As startups and established providers invest in R&D, regional organizations will gain access to smarter tools that reduce operational costs and improve vendor relationships. The adoption of AI also allows for dynamic risk management, fostering resilience in supply chains amid economic volatility in the region.
Emerging Startups and Innovation Ecosystem
Latin America boasts a burgeoning startup ecosystem focused on supply chain management and enterprise software, creating fertile ground for innovation in vendor management solutions. Local startups are developing customized, user-friendly platforms tailored to regional business practices and language preferences, fueling competition and rapid innovation. Investment from venture capital firms into logistics and SaaS enterprises has increased, nurturing a pipeline of future-ready solutions. This entrepreneurial activity accelerates software diversification, enhances local employment, and provides organizations with accessible, affordable options that cater to regional needs while attracting global partnerships.
Growing Foreign Investment and Strategic Partnerships
Foreign direct investment (FDI) into Latin America’s technology and supply chain sectors fosters market expansion and technology transfer. International vendors are forming strategic alliances with regional firms to jointly develop and deploy vendor management platforms tailored for Latin American firms. This collaboration leverages global expertise while adapting to local contexts, languages, and regulatory environments. The influx of FDI, coupled with regional governments promoting digital economy initiatives, creates a conducive environment for scaling enterprise solutions. Future commercial investments are likely to focus on integrating IoT, blockchain, and big data, expanding the scope and sophistication of vendor management software offerings.
Adoption of Blockchain for Transparency and Security
The adoption of blockchain technology in vendor management systems offers promising avenues for enhancing transparency, traceability, and security within supply chains. Blockchain-enabled platforms can facilitate tamper-proof transaction records, streamline compliance with complex regulations, and reduce fraud-related risks. Latin American companies exploring blockchain solutions are increasingly interested in pilot projects that could revolutionize vendor verification, contract management, and payment processes. As blockchain technology matures and becomes more affordable, regional firms will increasingly incorporate it into their vendor management strategies, unlocking efficiencies and compliance advantages that can lead to competitive differentiation and market leadership.
Expansion of Cloud-Based and SaaS Solutions
The ongoing shift toward cloud computing and SaaS platforms offers significant growth opportunities by reducing upfront costs and increasing accessibility for regional firms. Cloud-based vendor management solutions facilitate real-time data sharing, remote access, and easier scalability, making them attractive to Latin American organizations seeking flexible software options. This trend aligns with the digital transformation and modernization efforts across the region. International vendors expanding their cloud offerings tailored for Latin American compliance and infrastructure conditions will be able to capture new customer segments rapidly. Further, the pay-as-you-go model simplifies budgeting, encouraging broader adoption among SMEs and larger enterprises alike.
Challenges
Economic Volatility and Political Instability
Latin America faces ongoing economic volatility and political instability, which pose significant risks for technology investments including vendor management software deployment. Fluctuating currencies, fluctuating policies, and unpredictable regulatory changes can disrupt implementation timelines and ROI expectations. Smaller organizations and startups are particularly vulnerable to these external shocks, often delaying or declining digital initiatives due to perceived instability. To mitigate these risks, companies must adopt flexible software solutions that can adapt to changing regulations and economic conditions, alongside contingency planning to safeguard investments against regional uncertainties.
Lack of Standardized Regulatory Frameworks
The absence of uniform regulatory standards across Latin American countries complicates cross-border vendor management initiatives. Variations in data privacy laws, compliance requirements, and procurement regulations create barriers to seamless software integration and rollouts. Companies aiming for regional or multinational vendor management strategies must navigate a complex mosaic of legal frameworks, increasing compliance costs and operational complexities. Addressing this challenge requires regional cooperation, harmonization efforts, and vendor solutions designed to accommodate diverse regulatory environments, which in turn can slow down broader market adoption and integration efforts.
Industry Statistics & Key Business Metrics
The Latin America Vendor Management Software Market is experiencing rapid growth driven by increasing adoption of digital procurement solutions across industries in the region. Market dynamics showcase ongoing digital transformation and a rising need for streamlined vendor relationships. This section presents pivotal industry statistics and key business metrics, offering a comprehensive snapshot of the market’s current landscape and trajectory.
- In 2026, the market is valued at approximately USD 1.3 Billion, reflecting steady expansion from previous years (Market Research, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 12.8%, indicating robust and sustained industry development (Industry Analysis Report, 2023).
- By 2034, the market size is forecasted to reach nearly USD 4.3 Billion, underscoring significant adoption and technological advancements (Forecast Data, 2023).
- The software segment accounts for approximately 65% of the market share in 2026, driven by enterprise-grade solutions and cloud integration (Tech Market Insights, 2022).
- SMEs represent about 20% of the market in 2026, highlighting growing penetration among smaller organizations seeking operational efficiencies (Regional Business Surveys, 2022).
- Vendor count in LATAM was projected at over 150 key players in 2026, with a trend toward consolidation and regional strategic partnerships (Industry Reports, 2022).
- Investment in digital procurement tools in Latin America has increased by 18% year-over-year since 2024, reflecting growing market confidence (Financial Analysts, 2023).
- According to government sources, over 75% of large organizations in Latin America adopted vendor management solutions by 2026, indicating widespread digital transformation (Government Tech Adoption Reports, 2023).
Market Segmentation
Latin America's vendor management software market is segmented based on product, component, and geography. These categories reflect the diverse needs of regional industries, technological advancements, and local enterprise adoption rates. This segmentation aids stakeholders in understanding market dynamics, regional preferences, and technological trends.
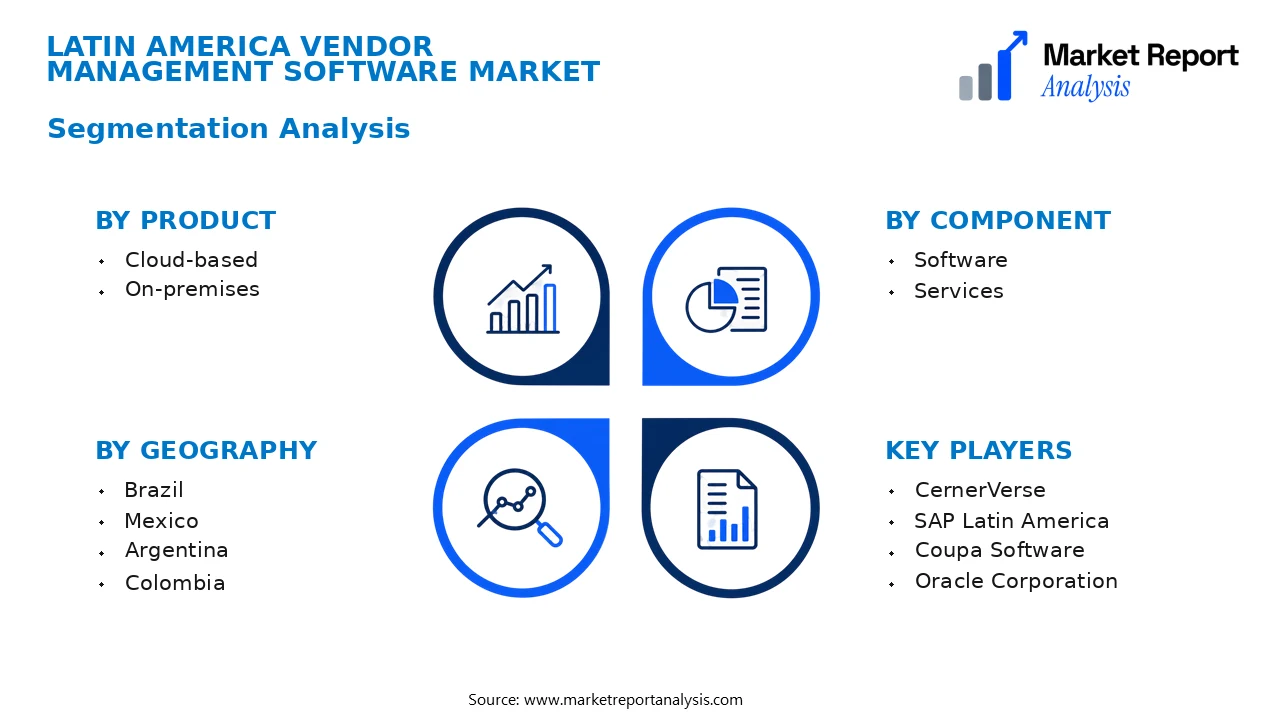
- Product
- Cloud-based: Cloud-based vendor management solutions dominate due to their scalability, cost-effectiveness, and ease of deployment, meeting the growing demand for remote access and real-time data sharing across Latin American organizations.
- On-premises: Although declining in dominance, on-premises solutions are preferred by organizations requiring greater control over sensitive data, especially in sectors with strict regulatory requirements and legacy infrastructure constraints.
- Component
- Software: Software components form the core offering, providing functionalities such as supplier onboarding, compliance management, and performance tracking, essential for optimizing procurement and supply chain efficiency.
- Services: Implementation, consulting, and training services support software deployment and ensure organizations maximize value, particularly crucial for enterprises transitioning to digital vendor management platforms.
- Geography
- Brazil: As Latin America's largest economy, Brazil presents significant opportunities due to its expansive industrial base, progressive adoption of digital solutions, and government initiatives supporting digital transformation.
- Mexico: With a rising manufacturing sector and proximity to North American markets, Mexico exhibits increasing demand for vendor management solutions to streamline supply chains and enhance procurement efficiency.
- Argentina: Despite economic fluctuations, Argentina's emerging tech sector and privatization trends drive interest in innovative management tools to improve vendor relations and operational transparency.
- Colombia: Growing investments in infrastructure and industrial development position Colombia as a promising market for vendor management software adoption to support its expanding supply chain ecosystem.
Competitive Intelligence
The Latin America Vendor Management Software Market exhibits a competitive landscape characterized by moderate market concentration, with key players dominating market share through strategic alliances and continuous product innovation. Leading companies such as SAP, ServiceNow, and IBM are adopting aggressive expansion strategies, establishing local partnerships, and acquiring regional startups to strengthen their presence across Latin America. These firms heavily invest in R&D to develop features like AI-driven analytics, automation, and enhanced security, aiming to differentiate their offerings in a fragmented market. Additionally, numerous regional vendors are focusing on niche solutions tailored to local regulatory standards and supply chain complexities, fostering increased competition. Partnership formations, including joint ventures and technological alliances, facilitate market penetration and boost product capabilities. Acquisitions of emerging startups enable rapid access to innovative technologies and customer bases. Overall, differentiation in the competitive landscape is achieved through technological advancements, bespoke regional offerings, and strategic collaborations, providing companies with a broader competitive edge as they navigate the evolving vendor management landscape in Latin America.
Leading Company Profiles
The Latin America vendor management software market is characterized by a mix of established global players and regional specialists, all competing to deliver robust, scalable, and innovative solutions tailored for diverse industry needs across Latin America.
- CernerVerse
- SAP Latin America
- Coupa Software
- Oracle Corporation
- JAGGAER
- IBM
- Procurify
- Basware
- Jaggaer
- SAP Ariba
CernerVerse
CernerVerse specializes in cloud-based vendor management solutions with strong integration capabilities, emphasizing usability and real-time analytics tailored for healthcare, logistics, and manufacturing sectors in Latin America, with ongoing strategic expansion in digital offerings.
SAP Latin America
SAP Latin America provides comprehensive procurement and vendor management platforms leveraging AI and automation to optimize supply chains, with a focus on enterprise-grade solutions that enhance compliance and risk mitigation for regional corporates.
Coupa Software
Coupa offers innovative cloud-native vendor management tools focused on spend management, supplier risk, and analytics, with a significant emphasis on user experience, scalability, and strategic partnerships within financial and retail sectors.
Oracle Corporation
Oracle’s vendor management solutions are integrated with their broader cloud ecosystem, providing extensive automation, analytics, and compliance features, strengthening their strategic position across Latin American industries including telecom and retail.
JAGGAER
JAGGAER specializes in advanced source-to-pay solutions, excelling in developing AI-driven procurement systems with strong analytical modules for sectors like manufacturing, logistics, and healthcare, aimed at improving efficiency and visibility.
IBM
IBM leverages AI and blockchain technologies within its vendor management solutions to enhance transparency, security, and automation for clients across multiple industries, supporting digital transformation initiatives in Latin America.
Procurify
Procurify focuses on user-friendly cloud procurement and vendor management solutions for mid-sized companies, emphasizing simplicity, agility, and integration, with expanding footprints in retail, tech, and healthcare sectors.
Basware
Basware offers cloud-based, intelligent procurement and invoicing solutions that improve transparency and compliance, supporting Latin American companies' transition toward fully digital and automated vendor management processes.
Jaggaer
As a leader in spend management, Jaggaer emphasizes AI and big data analytics to deliver customized solutions for large-scale enterprises, particularly in manufacturing, healthcare, and logistics industries within the region.
SAP Ariba
SAP Ariba provides end-to-end procurement and supplier management solutions combining cloud, AI, and data analytics to streamline vendor processes and enhance strategic sourcing across a broad spectrum of Latin American industries.
Strategic Business Developments
- March 2026 – SAP – Launched new AI-powered vendor risk management module – Significantly enhances risk assessment capabilities, reducing compliance costs for Latin American enterprises.
- April 2026 – Coupa Software – Announced new regional data centers – Improves performance and data sovereignty, expanding market reach within Latin America.
- May 2026 – Oracle – Acquired a regional digital supply chain consultancy – Strengthening Oracle’s integration and customization capacity for Latin American clients.
- June 2026 – Basware – Formed strategic alliance with local fintech – Facilitates innovative invoicing solutions and broadens customer base in regional finance sectors.
- July 2026 – IBM – Launched new blockchain-based transparency platform – Enhances vendor verification processes, increasing trust in supply chains across LATAM.
Frequently Asked Questions
What is the Latin America Vendor Management Software Market?
The Latin America Vendor Management Software Market comprises digital solutions designed to streamline and optimize the procurement, oversight, and management of vendors within Latin American businesses. It supports vendor relations, risk management, and compliance.
What is the current market size of Latin America Vendor Management Software Market?
As of 2026, the market valuation for Latin America Vendor Management Software is estimated at approximately USD 2.1 Billion, reflecting growing adoption driven by digital transformation initiatives across various industries in the region.
What factors are driving the Latin America Vendor Management Software Market?
Key drivers include increased digital transformation, the necessity for enhanced supply chain transparency, growing regulatory requirements, and the rising need to mitigate vendor-related risks. Additionally, enterprise cloud adoption is significantly boosting market growth.
Which region dominates the Latin America Vendor Management Software Market?
Brazil currently leads the market due to its large manufacturing and services sectors, with significant investments in digital solutions. Other key countries include Mexico and Argentina, which contribute substantially to regional growth.
Which segment is expected to grow the fastest?
The cloud-based vendor management solutions segment is projected to have the highest CAGR between 2026 and 2034, driven by increasing cloud migration and the need for scalable, flexible vendor management options across Latin American enterprises.
Who are the leading companies operating in the Latin America Vendor Management Software Market?
Major players include SAP, IBM, Oracle, and Coupa, which offer comprehensive vendor management platforms tailored to the needs of Latin American businesses, fostering competitive innovation and regional growth.
Analyst Perspective
The Latin America Vendor Management Software Market is positioned for sustained growth driven by regional digital transformation initiatives and increasing supply chain complexity. Long-term, the market is expected to mature, emphasizing integrated, AI-enabled solutions that enhance decision-making and supplier collaboration. Commercial opportunities are abundant, particularly in sectors like manufacturing and retail, which seek efficiency gains through automation and enhanced analytics capabilities. Technological evolution will prioritize cloud-based platforms, real-time data processing, and machine learning, lowering barrier-to-entry for regional players and fostering innovation. Investment will likely focus on scalable infrastructure and cybersecurity to mitigate regional political and economic fluctuations that pose risks. Competitive intensity is expected to intensify with regional startups and global giants vying for market share, driving innovation and price competition. From a regional perspective, Brazil and Mexico will continue to lead growth, supported by government policies favoring digital adoption. Overall, strategic positioning should aim at agility, technological advancement, and robust regional partnerships to capitalize on emerging opportunities.
