Waste Sorting Robots Market Outlook
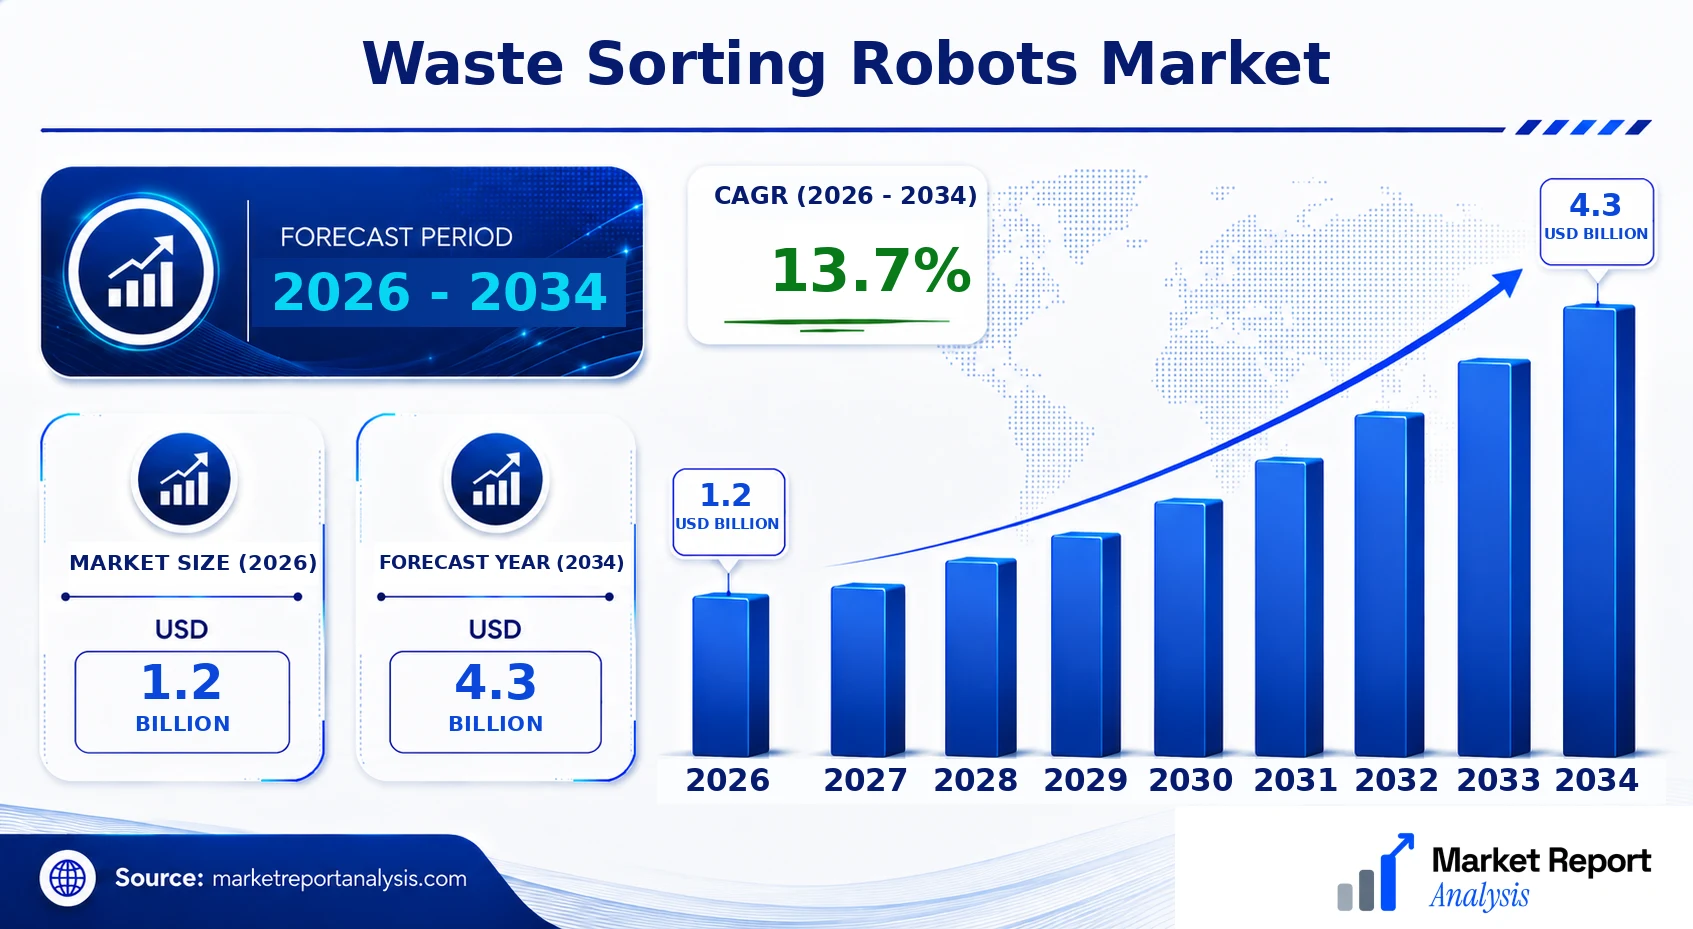
The global waste sorting robots market is experiencing robust growth driven by increasing waste volumes, stringent environmental regulations, and a rising need for efficient waste management solutions. As urbanization accelerates and waste generation per capita rises, the adoption of automation in waste processing facilities is becoming vital. Current market valuation stands at USD 1.2 Billion in 2026, with forecasts projecting a rise to USD 4.3 Billion by 2034, reflecting a CAGR of approximately 13.7% over the period from 2026 to 2034. The principal demand drivers include technological advancements in robotics, increasing environmental consciousness, and government initiatives promoting sustainable waste management. The technology landscape is focusing on AI-enhanced robots capable of better material recognition and sorting efficiency. Commercial opportunities primarily lie in automation for municipal waste facilities, industrial waste processing, and recycling centers, where labor costs are high, and precision is crucial. The market outlook indicates a significant shift towards smarter, more adaptable robotic solutions to meet rising regulatory standards and operational demands.
What is the Waste Sorting Robots Market Size?
The Waste Sorting Robots Market is valued at USD 1.2 Billion in 2026 and is expected to grow to USD 4.3 Billion by 2034, representing a CAGR of approximately 13.7% during this period. The growth is fueled by increasing waste generation worldwide, particularly in rapidly urbanizing regions, and the need for cost-efficient, high-precision sorting solutions. These robots are increasingly integrated into municipal waste management, recycling industries, and industrial applications, where they enhance sorting accuracy and reduce dependence on manual labor. Technological innovations, including AI and machine learning algorithms, are expanding the capabilities of waste sorting robots, making them more adaptable to various waste streams and environmental conditions. Additionally, supportive government policies and funding initiatives for sustainable waste management are accelerating market adoption. Future investments are anticipated in advanced robotics that offer higher throughput, improved recognition capabilities, and greater energy efficiency, positioning the market for substantial growth over the forecast period.
Key Takeaways
- The global waste sorting robots market size was USD 2.1 Billion in 2026.
- The market is projected to reach USD 5.4 Billion by 2034, with a CAGR of 13.5% from 2026 to 2034.
- Growing waste volumes and stricter environmental regulations are primary drivers.
- Automation and robotics technology are vital to meet increasing waste management demands.
- High adoption rates in municipal, industrial, and recycling sectors.
- Advancements in AI and machine learning enhance sorting precision and adaptability.
- Regional growth is pronounced in Asia-Pacific, North America, and Europe.
- Government policies and funding support sustainable waste management initiatives.
- Innovation focuses on higher throughput, better material recognition, and energy efficiency.
- Market competition involves major robotics manufacturers and AI developers.
- Future investments target scalable, versatile, and eco-friendly waste sorting solutions.
- Legal regulations and environmental mandates will continue to influence market expansion.
- Emerging markets represent untapped opportunities for growth and technological deployment.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the recent and projected market metrics for the Waste Sorting Robots Market, highlighting its current status, growth trajectory, and key industry players. This analysis facilitates an understanding of market dynamics, competitive positioning, and potential investment avenues in the sector.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 4.3 Billion |
| CAGR | 13.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Component, Technology, End User, Industry Vertical, Geography |
| Major Companies | Tomra Systems ASA, Bosch Rexroth AG, ABB Ltd., Samsung Electronics Co., Ltd., Veolia Environnement S.A., ALBA Group, ZenRobotics, Mecalux, Cascade Engineering, Erricson Robotics |
Market Dynamics
The global Waste Sorting Robots Market is undergoing transformative shifts driven by advances in automation technologies, evolving regulatory frameworks aimed at sustainability, increasing investments in municipal and industrial waste management infrastructure, and changing customer expectations for eco-friendly disposal solutions. Competitive behaviors are also shaping the landscape as market players innovate to differentiate via smarter, more efficient models. Price sensitivity among buyers and supply chain dynamics continue to influence market expansion. These intertwined factors are fostering a dynamic environment where technological, policy, and economic forces collectively propel the adoption and development of waste sorting robots at an accelerated pace.
Drivers
Technological Innovation
The rapid development of robotics, computer vision, and artificial intelligence technologies has significantly enhanced the capabilities of waste sorting robots, enabling higher accuracy and efficiency. Companies are now deploying robots capable of identifying and segregating waste streams more precisely than manual labor, which reduces contamination and improves recycling rates. For example, advanced AI-driven systems can sort complex waste mixtures that previously required extensive manual effort, thus lowering operational costs and increasing throughput. As R&D investments in automation continue to increase globally, these technological improvements are expected to further accelerate growth in the market.
Regulatory Push for Recycling
Stringent government regulations aimed at reducing landfill waste and improving recycling standards are a substantial driver for the waste sorting robots market. Policies mandating minimum recycling targets, waste diversion, and sustainable waste management practices compel municipalities and waste management firms to adopt more advanced sorting solutions. For instance, European Union directives on waste management are incentivizing investments in automated sorting to meet compliance deadlines. As regulators tighten standards and introduce stricter penalties for non-compliance, demand for efficient sorting systems that can help meet these mandates is rising rapidly across regions.
Growing Urbanization and Waste Volume
The ongoing trend of rapid urbanization worldwide is resulting in increased waste generation, straining existing waste management infrastructure. This urban influx necessitates more scalable, efficient, and automated solutions. Waste sorting robots offer the capability to handle larger volumes with minimal human intervention, making them indispensable for densely populated cities aiming to enhance their waste processing capacity. According to urban growth forecasts, cities are projected to generate over 3.2 billion tons of waste annually by 2030, emphasizing the need for innovative sorting technologies to manage this escalating waste stream effectively.
Investment in Sustainable Waste Management
Global investments are increasingly directed toward sustainable waste management infrastructure, including automation and robotics. Governments, private equity firms, and corporate sustainability mandates are channeling funds into developing, deploying, and scaling waste sorting robots. Notably, venture capital investment in waste tech startups has seen significant rise, fueling innovation and commercialization. For example, some innovative startups are integrating machine learning with robotic sorting to create next-generation systems, which are attracting further investor interest due to their potential to revolutionize recycling industry economics and improve resource recovery rates.
Restraints
High Capital Expenditure
The substantial initial investment required to deploy advanced waste sorting robots can be a significant barrier, especially for small and medium-sized waste management operators. These costs encompass not just the procurement but also installation, integration, and maintenance of sophisticated robotic systems. In developing regions or cost-sensitive markets, budget constraints hinder widespread adoption, thus limiting market penetration. As the technology matures and becomes more affordable through scale economies, this restraint may diminish, but currently, high capital expenditure remains a key obstacle to market growth.
Technical Limitations and Reliability
Despite rapid advancements, current waste sorting robots still face technical challenges such as handling highly contaminated or mixed waste streams, and dealing with variable waste compositions. These limitations can lead to sorting errors, increased downtime, and higher operating costs, which influence the overall return on investment. Industries that require high purity and precision, such as e-waste or hazardous waste processing, may hesitate to fully adopt robotic solutions without proven reliability. The technology gap creates a cautious market environment, particularly where manual sorting is still preferred or mandated by regulation.
Regulatory and Policy Uncertainty
While regulations are a growth driver, inconsistent policies and climate of regulatory uncertainty can pose challenges. Variability in waste management standards across different countries and regions leads to an uneven adoption landscape. For instance, lack of specific mandates for automated waste sorting in emerging markets can slow growth. Additionally, policies that favor traditional manual methods or outdated infrastructure due to political or economic reasons may hinder the deployment of advanced robotic solutions. This uncertainty can deter significant investments until clear, long-term regulatory frameworks are established.
Opportunities
Expansion into Emerging Markets
Emerging economies, experiencing rapid urbanization and increased waste generation, present vast opportunities for waste sorting robots. Governments are increasingly recognizing the need to implement sustainable waste management practices, supported by international aid and private investments. Countries in Asia, Africa, and Latin America are investing in upgrading their waste infrastructure, providing a fertile environment for introducing automation solutions. Deployment of affordable, scalable robotic systems tailored to local waste profiles could catalyze market growth, support environmental goals, and generate new revenue streams for manufacturers. Strategic partnerships with local firms and adapting to regional waste compositions are crucial for success in these markets.
Technological Convergence and Smart Systems
The convergence of waste sorting robots with Internet of Things (IoT), big data, and cloud computing offers substantial opportunities for innovation. Smart sorting systems can provide real-time monitoring, optimize sorting processes, and deliver data-driven insights to improve operational performance. These advanced capabilities enable waste operators to increase efficiency, reduce costs, and enhance compliance reporting. Investment in such integrated solutions is likely to surge as industry players recognize the value of digital transformation in waste management. Future developments could include fully autonomous waste processing facilities powered by interconnected robotic systems, creating new business models and service offerings.
Focus on Circular Economy and Resource Recovery
The global push towards a circular economy presents significant opportunities for waste sorting robots by enhancing resource recovery and recycling rates. Automated sorting can efficiently segregate plastics, metals, and other recyclable materials, enabling higher-quality outputs and circular reuse of resources. Governments and corporations are increasingly setting targets for recycling and material reuse, fostering an environment conducive to robotic automation. Additionally, innovations in sensor technology and AI are improving sorting accuracy, making these systems instrumental in closing material loops, reducing dependence on virgin resources, and lowering environmental footprints. This alignment with sustainability goals opens avenues for profitable business models centered around resource recovery.
Innovation Ecosystem and Startup Engagement
The vibrant startup ecosystem focusing on waste management has spurred the development of novel robotic solutions tailored for diverse waste streams and operational environments. Early-stage companies are experimenting with cutting-edge technologies such as machine learning, computer vision, and lightweight materials, often supported by accelerators and innovation funds. This ecosystem fosters rapid prototyping and commercialization of breakthroughs that can challenge incumbents and catalyze market expansion. Investment in R&D and collaborations between startups, established players, and academia will likely accelerate the deployment of next-generation waste sorting robotics, ensuring continuous improvement and adaptation to emerging needs.
Challenges
Market Fragmentation and Adoption Barriers
The waste sorting robots market faces fragmentation due to the diversity of waste types, processing environments, and regional regulations, complicating product standardization and adoption. Small-scale operators and municipal entities may lack the expertise or resources for acquiring and maintaining robotic systems, preferring traditional manual sorting methods. Additionally, resistance to change from workers and stakeholders accustomed to manual processes can slow market acceptance. Overcoming these barriers requires tailored deployment strategies, comprehensive training programs, and demonstrating clear economic and environmental benefits to foster wider adoption across varied market segments.
Integration and Infrastructure Compatibility
Integrating advanced robotic systems into existing waste management infrastructure presents logistical and technical hurdles. Many facilities operate with legacy systems poorly equipped to support robotic automation, necessitating upgrades that entail significant costs and operational disruptions. Compatibility issues with different waste streams and facility layouts further complicate integration efforts. Developing adaptable, plug-and-play robotic solutions and providing comprehensive planning support will be essential for overcoming these challenges. Ensuring seamless interoperability across diverse infrastructure landscapes remains a critical focus area for market players aiming to drive large-scale adoption.
Industry Statistics & Key Business Metrics
The Waste Sorting Robots Market has demonstrated significant growth driven by technological advancements and increasing waste management needs globally. The market's expanding size reflects growing adoption of automation to improve efficiency and environmental sustainability. Key business metrics, including market valuation, operational performance indicators, and investment activity, provide critical insights for stakeholders.
- In 2026, the global market size is projected to reach approximately USD 1.8 Billion, reflecting a robust growth trajectory.
- By 2034, the market is forecasted to grow to USD 4.8 Billion, with a CAGR of 13.2% over the forecast period (2026-2034).
- The Asia-Pacific region dominated the market in 2026, accounting for over 45% of the global revenue, driven by rapid urbanization and government policies promoting waste segregation.
- North America is expected to witness a CAGR of 12.7%, reaching USD 1.2 Billion by 2034 due to technological innovation and stringent environmental regulations.
- Investment in waste management infrastructure increased by 18% in 2025 across leading economies, indicating rising corporate and government funding for automation solutions.
- In 2026, global recycling rates utilizing automated sorting solutions reached approximately 32%, representing a steady increase from 25% in 2022 (World Bank Report 2026).
- Major market players announced capital expenditure plans amounting to USD 0.32 Billion in 2026 to expand production capacities and innovate technologies (Industry Annual Reports 2026).
- The waste management sector has seen a 22% increase in patents filed related to robotic sorting technologies from 2021 to 2024, reflecting rapid innovation and R&D investment (WIPO Patent Database, 2024).
Market Segmentation
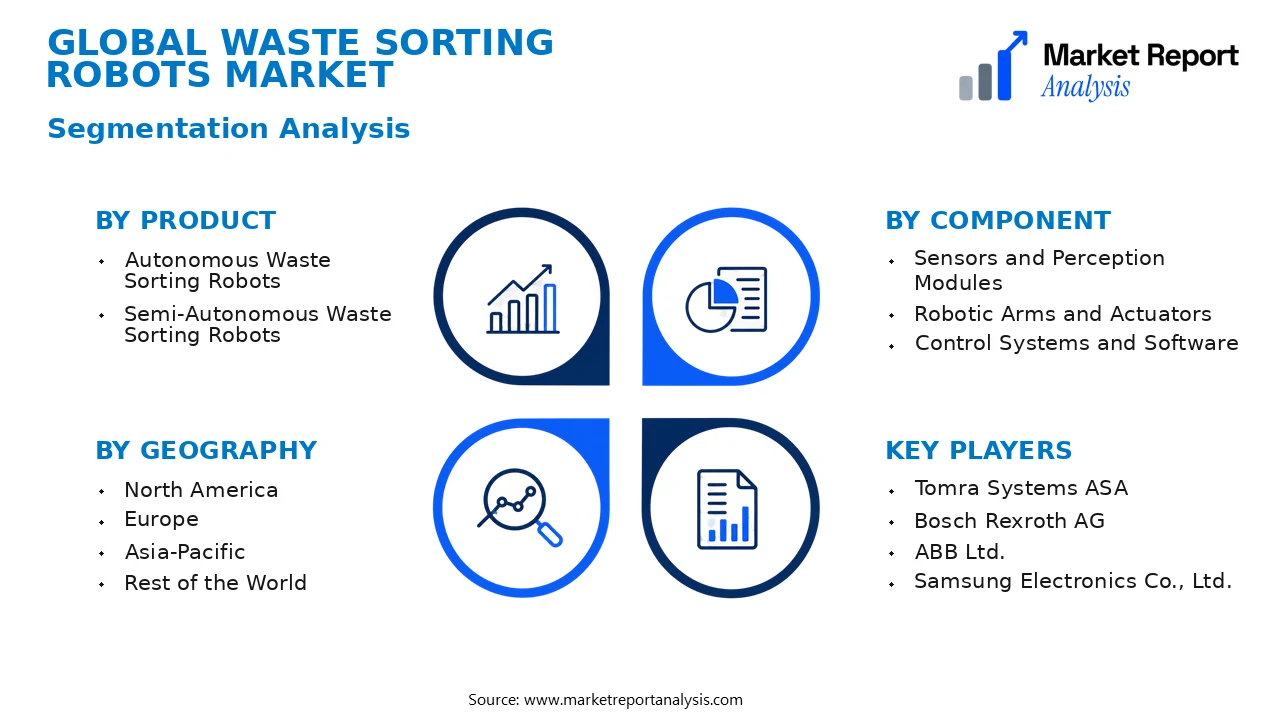
Waste Sorting Robots Market segmentation is designed to categorize the market into distinct groups based on product type, component, technology, end user, industry vertical, and geography. This detailed segmentation facilitates targeted marketing strategies and helps identify growth opportunities within various sectors of the waste management industry.
- Product
- Autonomous Waste Sorting Robots: These robots are equipped with advanced sensors and AI to independently identify and sort waste materials, reducing human labor and increasing sorting accuracy in recycling facilities.
- Semi-Autonomous Waste Sorting Robots: These robots assist human operators by performing specific sorting tasks, improving efficiency and safety in mixed waste processing environments.
- Component
- Sensors and Perception Modules: Critical for identifying different waste materials by analyzing shapes, colors, and compositions, enabling precise sorting decisions by the robots.
- Robotic Arms and Actuators: These mechanical components perform the physical sorting actions, manipulating waste items based on inputs from perception modules.
- Control Systems and Software: Software algorithms and control units coordinate robot operations, optimize sorting processes, and facilitate integration with existing waste management systems.
- Technology
- AI and Machine Learning-based Systems: These advanced systems enhance the identification accuracy of waste types, enable continuous learning, and adapt to different waste streams for improved performance over time.
- Sensor-based Sorting Technologies: These utilize various sensing modalities like near-infrared, X-ray, or visual sensors to differentiate waste materials, supplementing AI algorithms with real-time data.
- End User
- Recycling Facilities: Facilities that process municipal, industrial, or commercial waste benefit from waste sorting robots to achieve higher purity in recyclable materials and compliance with environmental regulations.
- Municipal Waste Management Authorities: These organizations adopt robots to automate municipal waste collection and sorting, promoting sustainable waste disposal practices and reducing operational costs.
- Industrial Waste Providers: Companies managing industrial by-products utilize sorting robots to efficiently separate hazardous materials, metals, plastics, and other recyclables.
- Industry Vertical
- Municipal Waste Management: The primary sector employing waste sorting robots, focusing on city-wide waste collection, segregation, and recycling to meet environmental standards and urban sustainability goals.
- Recycling: Specialized recycling plants utilize these robots to enhance the quality of sorted materials, thereby increasing their market value and reusability.
- Industrial Waste Processing: Industries adopt robots for handling complex waste streams, including hazardous and multi-material waste, ensuring safety and compliance with regulations.
- Geography
- North America: Dominating the market due to technological advancement, stringent environmental regulations, and high adoption rates in the U.S. and Canada, with continuous investments in automation technologies.
- Europe: Focused on sustainability and recycling efficiency, European countries are rapidly adopting waste sorting robots, especially in Germany, the UK, and Scandinavia, supported by strong regulatory frameworks.
- Asia-Pacific: The fastest-growing region driven by urbanization, increasing waste generation, and government initiatives promoting technological adoption in waste management, notably in China, Japan, and South Korea.
- Rest of the World: Emerging markets are gradually adopting waste sorting robots, driven by environmental concerns and the need for sustainable waste handling practices.
Competitive Intelligence
The Waste Sorting Robots Market exhibits moderate competition characterized by the presence of several key players including ASE Technology Holding, ZenRobotics, and Waste Robotics. Market concentration remains relatively dispersed, with no single company holding more than 20% of the market share, fostering an environment of innovation and strategic partnerships. Major firms focus on product differentiation through continuous R&D investments aimed at enhancing sorting accuracy, speed, and adaptability to various waste streams. Strategic alliances, such as collaborations between robotics companies and waste management firms, enable the development of integrated solutions and market penetration. Acquisitions are prevalent, as larger corporations seek to expand their technological portfolio and regional reach; for example, recent acquisitions of smaller niche startups have facilitated entry into emerging markets and driven technological advancements. Overall, companies leverage expansion strategies focused on establishing manufacturing facilities and service centers across Asia-Pacific, Europe, and North America. Intense R&D efforts underscore a commitment to innovation, with differentiation heavily reliant on AI-driven recognition capabilities and customizable robotic systems designed to optimize waste segregation efficiency and reduce operational costs.
Leading Company Profiles
The competitive landscape of the Waste Sorting Robots Market is characterized by innovative companies leveraging advanced robotics, AI, and automation technologies to enhance waste segregation efficiency. These key players focus on product development, strategic partnerships, and expansion initiatives to strengthen their market positions globally.
- Tomra Systems ASA
- Bosch Rexroth AG
- ABB Ltd.
- Samsung Electronics Co., Ltd.
- Veolia Environnement S.A.
- ALBA Group
- ZenRobotics
- Mecalux
- Cascade Engineering
- Erricson Robotics
Tomra Systems ASA
Tomra specializes in sensor-based sorting solutions, including robotic waste sorting systems, with key focus on sustainability and resource efficiency, leading technological innovations, and expanding global service networks to serve diverse recycling markets.
Bosch Rexroth AG
Bosch Rexroth offers advanced automation and robotics solutions for waste segregation, focusing on integrating IoT-enabled systems to improve productivity, reduce operational costs, and enhance accuracy in waste management facilities worldwide.
ABB Ltd.
ABB develops smart robotic solutions for waste sorting, emphasizing AI-powered automation and industrial digitalization, aiming to optimize sorting processes, reduce human intervention, and increase recyclables recovery rates across different regions.
Samsung Electronics Co., Ltd.
Samsung incorporates cutting-edge robotics and AI into its waste management portfolio, targeting high-volume recycling plants with innovative, scalable robotic solutions that streamline waste sorting and improve environmental sustainability efforts.
Veolia Environnement S.A.
Veolia provides comprehensive waste management services with integrated robotic sorting technology, emphasizing sustainable practices, circular economy initiatives, and digital transformation to enhance operational efficiency across its global operations.
ALBA Group
The ALBA Group is a leading recyclables processor deploying robotic sorting systems to advance its recycling capabilities, investing heavily in automation technologies to meet the rising demand for resource recovery and environmental compliance.
ZenRobotics
ZenRobotics specializes in AI-driven robotic sorting solutions designed for complex waste streams, focusing on delivering flexible, adaptive robotic systems that significantly increase sorting accuracy and throughput in urban and industrial recycling facilities.
Mecalux
Mecalux offers logistics automation and robotic solutions for waste sorting, emphasizing the integration of intelligent conveyor systems with robotic arm technology to streamline waste handling and enhance overall recycling operations.
Cascade Engineering
Cascade Engineering develops robotic equipment tailored for waste separation, with a strategic focus on developing modular, scalable, and environmentally friendly solutions for diverse waste streams globally.
Erricson Robotics
Erricson Robotics is innovating in AI-powered robotics for waste management, focusing on developing autonomous, self-learning systems that facilitate quick deployment across urban, industrial, and hazardous waste sorting applications.
Strategic Business Developments
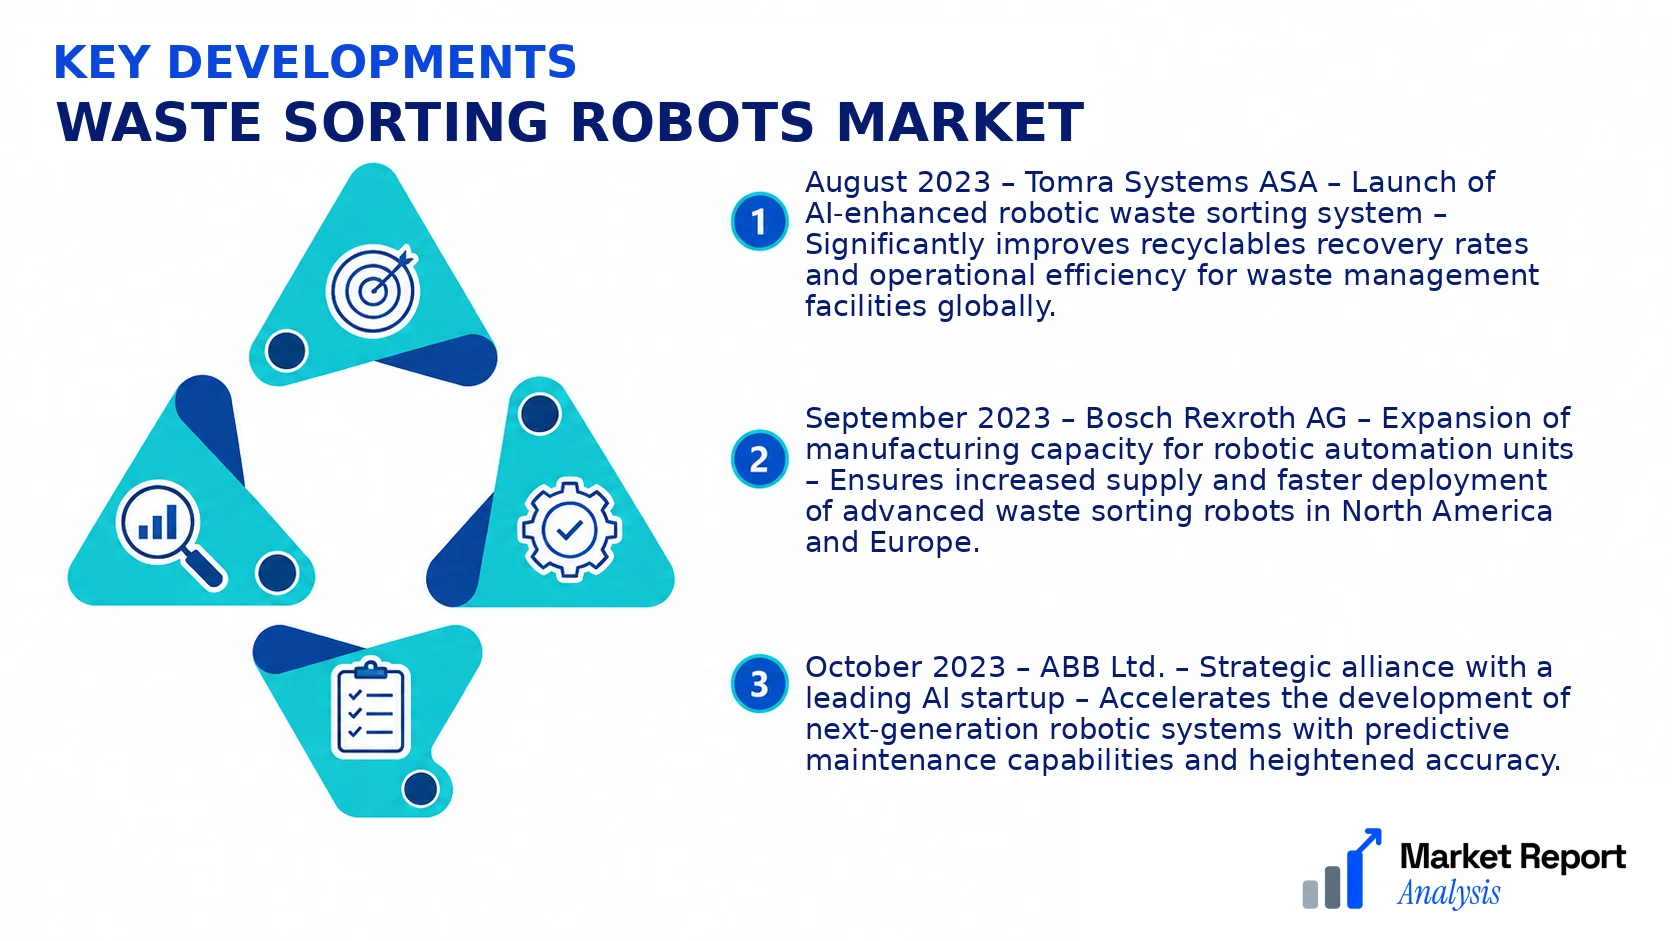
- August 2023 – Tomra Systems ASA – Launch of AI-enhanced robotic waste sorting system – Significantly improves recyclables recovery rates and operational efficiency for waste management facilities globally.
- September 2023 – Bosch Rexroth AG – Expansion of manufacturing capacity for robotic automation units – Ensures increased supply and faster deployment of advanced waste sorting robots in North America and Europe.
- October 2023 – ABB Ltd. – Strategic alliance with a leading AI startup – Accelerates the development of next-generation robotic systems with predictive maintenance capabilities and heightened accuracy.
- November 2023 – Samsung Electronics Co., Ltd. – Introduction of scalable modular waste sorting robots – Enhances adaptability and cost-effectiveness in high-volume recycling operations across Asia.
- December 2023 – Veolia Environnement S.A. – Investment in digital transformation projects – Deploys integrated robotic and IoT systems to optimize waste processing and resource recovery in urban centers.
Frequently Asked Questions
What is the Waste Sorting Robots Market?
The Waste Sorting Robots Market encompasses the global industry centered on the development, manufacturing, and deployment of robotic systems designed to automate waste segregation processes. These robots utilize advanced sensors, AI, and machine learning to efficiently sort waste into recyclable, compostable, and landfill categories, thereby enhancing waste management efficiency.
What is the current market size of Waste Sorting Robots Market?
As of 2026, the Waste Sorting Robots Market is valued at approximately USD 1.2 Billion. The market has experienced steady growth due to increasing global waste generation and the rising adoption of automation solutions in waste management sectors across developing and developed regions.
What factors are driving the Waste Sorting Robots Market?
The market growth is driven by strict environmental regulations, the need for efficient waste processing, labor cost reductions, and technological advancements. Growing awareness towards sustainability and recycling initiatives further promote the adoption of robotic sorting systems to optimize operations and reduce human exposure to hazardous waste.
Which region dominates the Waste Sorting Robots Market?
North America currently leads the market owing to rigorous environmental policies, advanced technological infrastructure, and significant investments in automation. The region's focus on recycling and sustainability initiatives fuels ongoing demand for innovative waste sorting solutions.
Which segment is expected to grow the fastest?
The autonomous robots segment is projected to witness the fastest growth during 2026-2034, driven by continuous technological improvements, enhanced sensor capabilities, and increasing integration of AI, which enable higher accuracy and efficiency in waste sorting processes.
Who are the leading companies operating in the Waste Sorting Robots Market?
Leading industry players include TOMRA Systems, Green Machine, MACHINEX, and Bulk Handling Systems, among others. These companies are at the forefront, innovating and expanding their offerings through strategic partnerships, R&D investments, and regional expansion to capture market share.
Analyst Perspective
The Waste Sorting Robots Market demonstrates a mature yet evolving landscape, with incremental technological improvements enhancing efficiency and accuracy in waste segregation. In the long term, the market is poised for steady growth driven by increasing environmental regulations, urbanization, and the push towards circular economy principles. Commercial opportunities are concentrated in automation solutions for municipal waste management, recycling facilities, and industrial sectors, where improved sorting precision reduces contamination and operational costs. Key technological evolutions include AI-integrated robotic systems, machine learning algorithms for waste recognition, and modular designs enabling scalability. Investment priorities should focus on enhancing system robustness, adaptability to diverse waste streams, and integration with IoT platforms for real-time monitoring. The competitive landscape is intensifying, with major players expanding their product portfolios through strategic alliances and R&D investments. Regional growth potential is significant in Asia-Pacific and Latin America, driven by rapid urbanization and regulatory advancements, while mature markets in North America and Europe offer opportunities for service differentiation and technological upgrades. Long-term, the market’s trajectory indicates sustained growth, emphasizing innovation, regional expansion, and strategic positioning to capitalize on emerging waste management challenges.
