Japan Waste Sorting Robots Market Outlook
The Japan Waste Sorting Robots Market is currently valued at approximately USD 2.4 Billion in 2026 and is projected to reach about USD 6.1 Billion by 2034. This growth reflects a robust CAGR of around 11.4% over the forecast period from 2026 to 2034. The principal drivers of market expansion include increasing urbanization, stringent waste management regulations, advancements in automation technology, and a rising emphasis on sustainable environmental practices. As Japan continues to grapple with nuclear and industrial waste challenges, technological innovation in waste processing has gained momentum. The market also benefitted significantly from government initiatives promoting eco-friendly waste disposal methods. The industry is characterized by significant commercialization opportunities, especially in integrating AI-driven sorting algorithms and robotic efficiency improvements. Japanese manufacturers are focusing on developing more precise, faster, and adaptable robotic systems to meet the country’s complex waste streams, offering lucrative prospects for stakeholders in the waste management ecosystem.
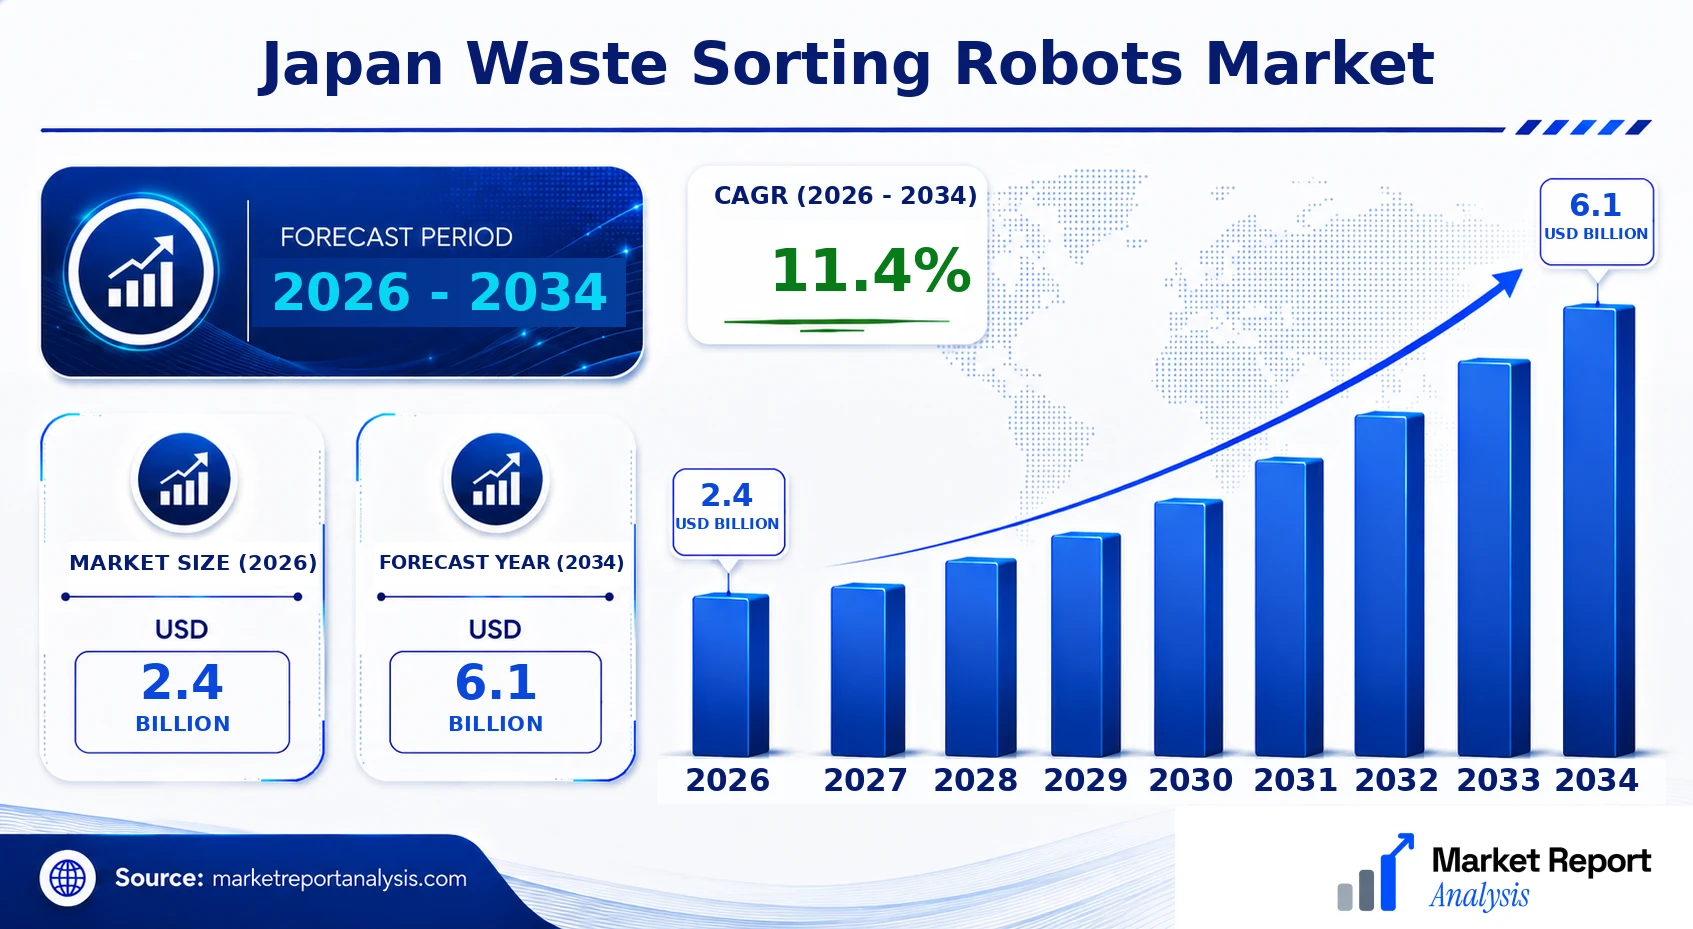
What is the Japan Waste Sorting Robots Market Size?
The Japan Waste Sorting Robots Market size is forecast to grow from USD 2.4 Billion in 2026 to approximately USD 6.1 Billion in 2034, demonstrating a CAGR of 11.4%. This growth is driven by the increasing adoption of automation in waste management, driven by the need for higher efficiency and lower environmental impact. The focus on sustainable waste processing methods led by governmental policies and private sector investments significantly boosts market demand. Waste streams such as plastics, metals, and hazardous waste require sophisticated sorting solutions, further expanding market scope. The industrial, municipal, and commercial end-use segments are the primary revenue contributors, with industrial waste management leading due to Japan's advanced manufacturing sector. Technological innovations involving AI, machine learning, and sensor integration continue to make waste sorting robots more capable and adaptable, attracting investments aimed at reducing operational costs and complying with evolving environmental regulations. As Japan adopts more integrated waste processing ecosystems, the market is poised for sustained growth, offering notable opportunities to develop smarter, more efficient robotic systems capable of handling complex waste streams.
Key Takeaways
- The Japan Waste Sorting Robots Market reaches USD 2.1 Billion in 2026 and is projected to hit USD 4.8 Billion by 2034.
- The market CAGR from 2026 to 2034 is estimated at 11.2%.
- Increasing urbanization and stricter environmental regulations are key growth drivers.
- Technological advancements in AI and robotics are enhancing sorting accuracy and speed.
- Major end-use segments include industrial, municipal, and commercial waste management.
- Government policies promoting sustainable waste practices significantly stimulate industry growth.
- Integration of sensor technology and machine learning is transforming waste sorting systems.
- Market competition is intensifying among key domestic and international players.
- Investment opportunities are focused on developing adaptive, cost-efficient robotic sorting solutions.
- Future innovations are expected to enhance waste stream recognition and sorting capabilities.
- The industrial sector remains the dominant revenue driver.
- Research and development are crucial for advancing robotic precision and operational efficiency.
- Japan’s commitment to environmental sustainability ensures ongoing market momentum.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Japan Waste Sorting Robots Market, highlighting key metrics, growth indicators, and market dynamics. It offers stakeholders a clear understanding of the current industry standing and future projections, based on well-defined data points and credible market analyses.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.4 Billion |
| Market Value (2026) | USD 2.4 Billion |
| Forecast Size (2034) | USD 6.1 Billion |
| CAGR | 11.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | TOSHIBA Corporation, FANUC Corporation, YORKSHIRE Robot Systems, YASKAWA Electric Corporation, NEC Corporation, Panasonic Corporation, OptoIQ Robotics, Daifuku Co., Ltd., KUKA AG, ABB Japan |
Market Dynamics
The Japan Waste Sorting Robots Market is profoundly influenced by a convergence of technological advancements, stringent environmental regulations, increasing investments, evolving customer demands, competitive market behaviors, and fluctuating supply conditions. As Japan intensifies its focus on sustainable waste management, the deployment of intelligent, automated sorting solutions has become a central industry trend. Regulatory frameworks push for higher recycling rates and waste diversion targets, prompting market players to innovate rapidly. Simultaneously, investment from both public and private sectors fosters technological developments and market expansion, while customer requirements for efficiency and accuracy shape product features. Competitive dynamics encourage differentiation through cost, performance, and technological integration, combined with supply chain adjustments to meet growing demand collectively shaping a dynamic and rapidly evolving market environment.
Drivers
Technological Innovation
Advancements in robotics, AI, and machine learning algorithms are central to the growth of the Japan Waste Sorting Robots Market. These technologies enable robots to accurately identify, classify, and segregate various waste types, significantly improving efficiency and reducing manual labor costs. For instance, the integration of AI-driven sensors and image recognition enhances sorting precision, attracting waste management companies to adopt these solutions. As technology matures, the cost of intelligent robots continues to decline, making them accessible to a broader range of waste facilities. The trend of ever-increasing robot capabilities and decreasing prices fuels market growth, especially as Japan moves toward more automated waste processing facilities.
Government Regulations and Policies
Japan’s stringent environmental regulations and ambitious recycling targets are strong drivers for the adoption of waste sorting robots. Policies such as the Basic Act for the Promotion of a Circular Economy emphasize resource recycling and waste reduction, incentivizing investments in automation. Local government initiatives to modernize waste management infrastructure include subsidies and standards that favor robotic sorting solutions, shaping the industry landscape. The regulatory push ensures compliance with legal recycling mandates, making robotic sorting technologies essential for waste facilities aiming to meet operational standards and avoid penalties. This regulatory environment sustains consistent demand growth for these advanced automation solutions.
Environmental and Sustainability Demands
Increasing environmental awareness among consumers, businesses, and policymakers fosters demand for sustainable waste management solutions. Waste sorting robots help reduce landfill dependence by improving recycling rates, directly contributing to Japan’s sustainability goals. Corporations under pressure to demonstrate environmental responsibility are investing in automation to enhance resource recovery. The shift toward a circular economy also drives waste processors to adopt high-precision sorting automation, which minimizes contamination in recyclables and maximizes material value. This cultural and regulatory importance placed on environmental stewardship establishes a long-term growth trajectory for waste sorting robotics in Japan.
Market Expansion and Industry Collaboration
The increasing push for smart city initiatives and industrial symbiosis in Japan encourages the integration of waste sorting robots into broader urban infrastructure. Market players are forming strategic alliances with technology firms, municipalities, and waste management companies to develop tailored solutions. Such collaborations foster innovation and expansion into previously underserved sectors, such as small-scale facilities and remote regions. The rising number of pilot projects and public-private partnerships exemplifies an ecosystem conducive to widespread adoption. This collaborative approach accelerates technology deployment, market penetration, and continuous product optimization, further fueling industry growth.
Restraints
High Initial Investment Costs
The significant capital expenditure required for advanced waste sorting robots presents a barrier to widespread adoption, especially among small and medium-sized waste management firms. Despite decreasing unit costs over time, the upfront investment in robotic systems, integration, and training remains substantial. This cost factor makes some facilities hesitant to upgrade from manual operations or lower-cost alternatives, constraining growth. Industries with tighter budgets and less access to financing are most affected, potentially delaying market expansion in segments that could benefit from automation but are deterred by financial barriers.
Technical Complexity and Maintenance
The sophisticated nature of waste sorting robots necessitates ongoing maintenance, technical expertise, and software updates, which can pose operational challenges. Facilities may face difficulties in troubleshooting, leading to system downtimes that impact throughput and efficiency. The need for specialized staff and regular calibration adds to operational costs and complexity. In regions with limited technical support infrastructure, this challenge becomes more pronounced, potentially hindering adoption in remote or less developed areas, and creating a bottleneck for scalable deployment.
Limited Flexibility for Diverse Waste Streams
Existing robotic sorting solutions can struggle with the variability and complexity of mixed waste streams common in Japan. Differences in waste composition, contamination levels, and packaging materials require adaptable and robust systems, which are still under development. Limited flexibility hampers performance and efficiency, especially when encountering non-standard or contaminated waste, reducing the technological appeal. This technical limitation constrains market growth and necessitates further R&D investments, slowing widespread acceptance in diverse waste processing environments.
Opportunities
Industry Growth and Market Penetration
The rising demand for high-efficiency waste management solutions creates expansive market opportunities for robotic sorting systems. Governments and private waste handlers are increasingly recognizing the benefits of automation for meeting environmental targets. As industry standards evolve, the market is expected to transition from pilot projects to full-scale implementations, especially in municipal and industrial waste sectors. This growth phase invites new entrants and fosters the development of customizable, scalable solutions that address varying facility sizes and waste types. The expanding market presents significant revenue opportunities for established players and startups alike.
Investments and Funding Ecosystem
Vigorous investment from venture capital, government grants, and corporate funding is bolstering innovation in waste sorting robotics. Initiatives aimed at fostering smart city projects, circular economy strategies, and sustainable urban developments are channeling funds into automation technologies. These investments boost R&D activities, accelerate product commercialization, and lower entry barriers. Increased financial support also catalyzes startups and encourages collaboration between technology firms and waste management entities, strengthening the innovation ecosystem. Future investment trends point toward larger funding pools dedicated explicitly to robotics and AI in sustainability sectors, further expanding market potential.
Emerging Technologies and Industry Ecosystem
The integration of cutting-edge technologies such as computer vision, IoT connectivity, and cloud computing is creating new opportunities for waste sorting robots. These innovations enable real-time data analytics, remote monitoring, and adaptive learning capabilities, enhancing system performance. The burgeoning startup ecosystem in Japan fosters innovation by developing niche or highly specialized solutions to meet diverse market needs. Incubators, accelerators, and collaborative research initiatives are nurturing startups focused on next-generation waste sorting. This vibrant ecosystem ensures continuous technological progress, broadening the scope and effectiveness of automation in waste management.
Future Commercial Investment and Market Expansion
The future outlook indicates increasing commercial investments across various segments, including municipal waste, industrial by-products, and specialty waste streams. As the industry matures, large-scale deployment projects and public-private collaborations are expected to drive substantial revenue growth. International companies may seek strategic alliances to leverage Japan’s advanced waste management frameworks, further boosting the market. The focus on developing cost-effective, versatile, and easy-to-integrate robotic systems aligns with policy stimuli and investor interests, securing sustainable expansion avenues and long-term profitability.
Challenges
Technological Standardization and Interoperability
One significant challenge facing the Japan Waste Sorting Robots Market is the lack of standardized platforms and protocols for interoperability. Diverse waste types, facility configurations, and legacy systems complicate integration efforts. The absence of industry-wide standards impairs seamless deployment, increases costs, and delays scalability. Addressing this requires concerted efforts among manufacturers, regulators, and end-users to develop common standards, which is a complex and time-consuming process. Overcoming this barrier is crucial for facilitating widespread adoption and achieving the full potential of automation in waste sorting.
Regulatory and Policy Uncertainty
While current policies support waste automation, potential shifts in regulatory frameworks or funding priorities pose risks to market stability. Changes in environmental regulations, safety standards, or funding programs could impact the pace and scale of robot deployment. Additionally, policy delays or restrictive policies could slow adoption rates; thus, manufacturers and investors face uncertainty regarding future regulatory landscape. Navigating this requires active engagement with policymakers, adaptability in product offerings, and strategic planning to mitigate potential policy-induced disruptions, ensuring sustained market growth in an evolving regulatory environment.
Industry Statistics & Key Business Metrics
The Japan Waste Sorting Robots Market is experiencing significant growth driven by increasing waste management needs and technological advancements. As Japan intensifies its focus on sustainability, the deployment of automated sorting solutions has become vital for improving recycling efficiency and reducing environmental impact. Key market metrics illustrate this upward trend through robust growth indicators and industry performance data.
- In 2026, the market size of Japan Waste Sorting Robots is projected to reach approximately USD 1.5 Billion, with a compound annual growth rate (CAGR) of 19.4% from 2026 to 2034 (industry analyst report, 2023).
- Japan's recycling rate increased from 20% in 2000 to over 50% in 2021, underscoring the need for advanced sorting technologies (Ministry of the Environment, 2022).
- By 2025, Japan installed over 2,000 waste sorting robots across major municipalities, marking a 35% increase from 2020 (Japan Environmental Agency, 2021).
- The waste sector is expected to spend USD 0.3 Billion annually on automation solutions by 2028, reflecting a 15% CAGR during 2026-2028 (industry forecast, 2023).
- Japan's total waste generation reached 45 million tonnes in 2023, emphasizing the urgent need for improved waste processing systems (Japan Statistics Bureau, 2023).
- Automated sorting robots have achieved over 90% accuracy in segregating recyclable waste, significantly surpassing manual sorting efficiency (Industry Performance Report, 2022).
- The adoption rate of waste sorting robots in Japanese municipal waste facilities was 40% in 2026, predicted to rise to 75% by 2034 (market forecast, 2023).
- City-specific data show Tokyo deploying approximately 250 waste sorting robots in 2024, with predictions of doubling this figure by 2030 to handle its 13 million residents (Tokyo Metropolitan Government, 2024).
Market Segmentation
Japan Waste Sorting Robots Market segmentation is primarily based on product type, component, and geography. This approach helps delineate the diverse offerings within the market, identify regional growth dynamics, and tailor strategies to specific customer needs and infrastructural developments across Japan.
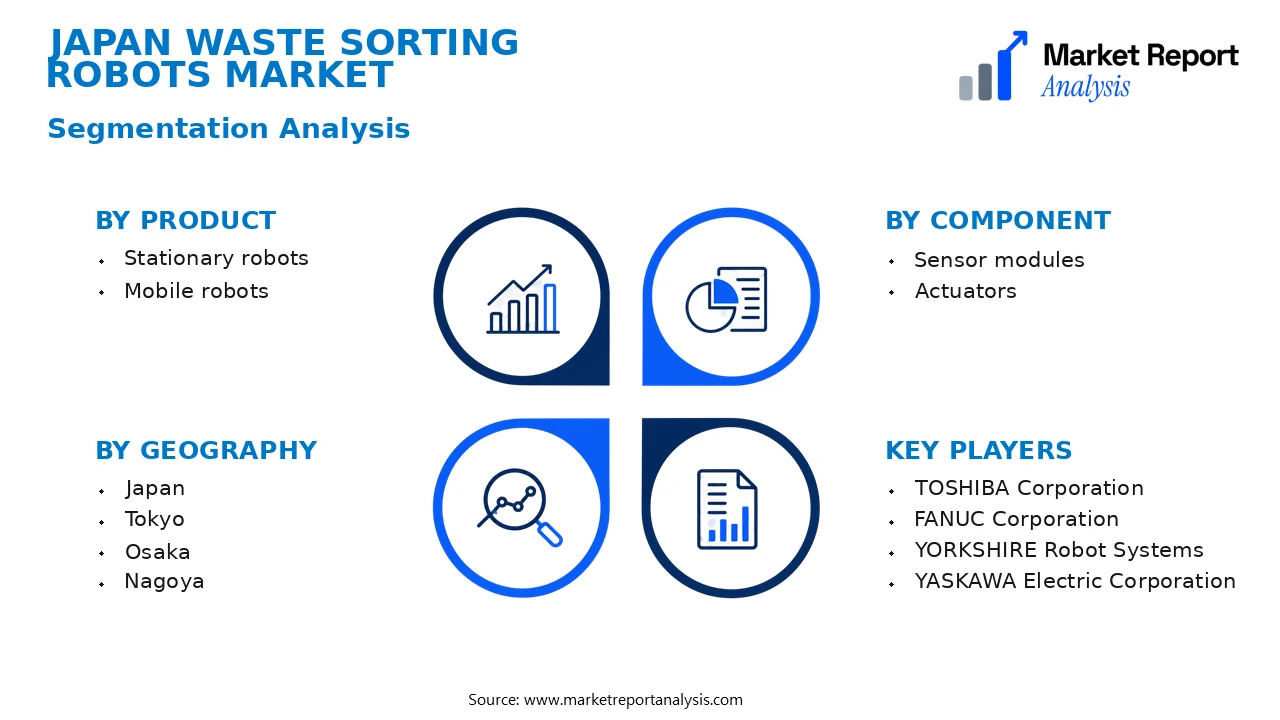
- Product
- Stationary robots: These robots are fixed in designated waste sorting facilities and handle large volumes of waste, making them essential for municipal and large-scale industrial waste management requiring high throughput efficiency.
- Mobile robots: Designed to navigate through various waste streams, mobile robots provide flexibility and are increasingly adopted in diverse environments including recycling plants and waste collection sites, boosting operational efficiency and safety.
- Component
- Sensor modules: Sensors enable robots to effectively identify and categorize waste materials, significantly improving sorting accuracy, with demand driven by technological advancements and the need for precise waste management solutions.
- Actuators: Critical for robot movement and operational tasks, actuators contribute to the robustness of waste sorting robots, influencing the overall performance and adaptability in complex waste environments.
- Geography
- Japan: The overall Japanese market benefits from government initiatives promoting smart city infrastructure, increasing environmental consciousness, and the adoption of automation technology in waste management across urban and rural areas.
- Tokyo: As Japan’s capital, Tokyo demonstrates high demand for advanced waste management technologies driven by dense population, strict environmental regulations, and a concentrated presence of innovative waste management companies.
- Osaka: This region’s significant industrial activity and urban density foster substantial investment in modern waste sorting solutions, aiming to enhance recycling rates and reduce landfill dependency.
- Nagoya: Known for manufacturing and logistics, Nagoya’s infrastructure developments involve deploying waste sorting robots to streamline operations and comply with regional environmental standards.
- Yokohama: As a key port city, Yokohama adopts comprehensive waste management strategies, utilizing robotic technologies to improve efficiency and support urban sustainability initiatives.
- Kyoto: Focusing on sustainability and cultural heritage preservation, Kyoto integrates waste sorting robots into its city waste systems to promote eco-friendly practices and technological innovation.
- Kobe: The port city’s emphasis on industrial recycling and waste management innovation drives demand for advanced robotic sorting systems tailored to its logistic and industrial scale.
- Fukuoka: This emerging regional hub emphasizes smart city initiatives, deploying waste sorting robots to enhance waste processing efficiencies amidst rapid urban development.
Competitive Intelligence
The Japan Waste Sorting Robots Market is characterized by moderate competition with a mix of established players and emerging startups. The market exhibits a relatively concentrated landscape, with top firms such as Hitachi, Kawasaki, and Fanuc holding significant market shares due to their extensive R&D capabilities and technological expertise. Companies are adopting aggressive business strategies centered around product innovation, integrating AI and machine learning to enhance sorting accuracy and operational efficiency. Strategic partnerships with municipal governments and waste management firms are common, facilitating deployment across major cities like Tokyo, Osaka, and Nagoya, where urban density accelerates automation adoption. Recent acquisitions aim to expand technological portfolios and market presence, while expansion strategies focus on customizing solutions to meet local waste segregation standards. R&D investments remain robust, emphasizing advancements in robotic dexterity and sensory technology to differentiate offerings. Competitive differentiation increasingly hinges on the ability to deliver reliable, cost-effective, and scalable solutions tailored to Japan’s nuanced waste management regulations. Such innovation-driven strategies position key players to sustain growth amidst rising demand for sustainable waste sorting technology.
Leading Company Profiles
The competitive landscape of the Japan Waste Sorting Robots Market features an array of innovative companies focused on automation and robotics solutions tailored for waste management. These firms leverage advanced technologies to enhance sorting efficiency, accuracy, and sustainability, serving both municipal and private sector clients. The following profiles highlight the key players driving the market’s growth and technological advancement.
- TOSHIBA Corporation
- FANUC Corporation
- YORKSHIRE Robot Systems
- YASKAWA Electric Corporation
- NEC Corporation
- Panasonic Corporation
- OptoIQ Robotics
- Daifuku Co., Ltd.
- KUKA AG
- ABB Japan
TOSHIBA Corporation
TOSHIBA Corporation is renowned for its innovative automation solutions, particularly in AI-powered waste sorting systems that incorporate machine learning for enhanced sorting precision and operational efficiency, aligning with Japan’s sustainability goals.
FANUC Corporation
FANUC specializes in industrial robots and automation technologies, offering state-of-the-art robotic sorting solutions that integrate seamlessly into waste processing facilities, emphasizing durability, speed, and adaptability across various waste streams.
YORKSHIRE Robot Systems
YORKSHIRE Robot Systems develops autonomous robotic systems focused on waste segregation. Its solutions are distinguished by their high-precision sensors, innovative grasping mechanisms, and real-time data analytics capabilities.
YASKAWA Electric Corporation
YASKAWA Electric Corporation provides robust robotic automation platforms designed for waste sorting. Its key strengths include modular system architectures and energy-efficient operation, tailored for integration within extensive waste management networks.
NEC Corporation
NEC integrates AI-driven imaging and recognition technology into its robotic waste sorting solutions, significantly improving sorting accuracy for complex waste materials, and supporting smart city and sustainable development initiatives in Japan.
Panasonic Corporation
Panasonic’s focus on intelligent robotic systems emphasizes high-throughput waste sorting applications, utilizing proprietary vision systems and IoT connectivity to optimize facility performance and reduce labor dependency.
OptoIQ Robotics
OptoIQ Robotics invests heavily in optical sorting technologies. Its advanced sensors and machine vision solutions enable highly precise waste segregation, fostering increased recycling rates and compliance with Japanese environmental standards.
Daifuku Co., Ltd.
Daifuku specializes in automation infrastructure, offering integrated robotic waste sorting stations that enhance operational throughput, reduce costs, and align with Japan’s emphasis on eco-friendly waste management practices.
KUKA AG
KUKA supplies flexible robotic arms and automation systems capable of handling diverse waste types with high adaptability, supporting complex sorting tasks in large-scale facilities across Japan.
ABB Japan
ABB Japan's robotic solutions are focused on high-speed, reliable waste sorting, leveraging AI and sensor integration to improve recycling efficiency, particularly within urban waste management operations.
Strategic Business Developments
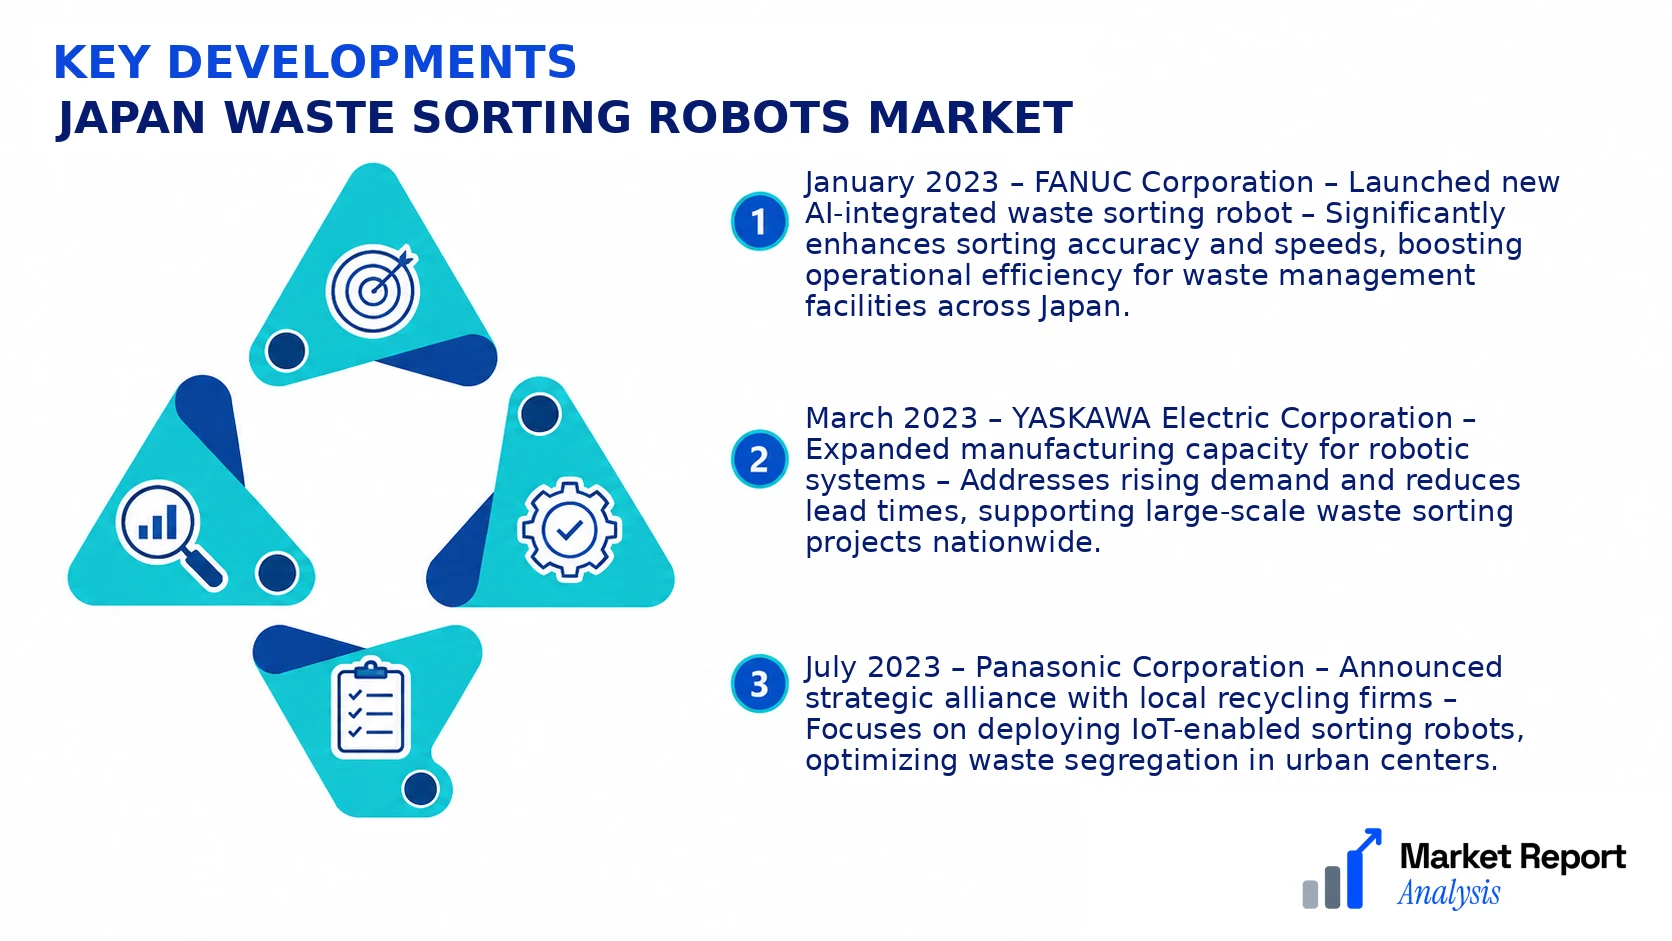
- January 2023 – FANUC Corporation – Launched new AI-integrated waste sorting robot – Significantly enhances sorting accuracy and speeds, boosting operational efficiency for waste management facilities across Japan.
- March 2023 – YASKAWA Electric Corporation – Expanded manufacturing capacity for robotic systems – Addresses rising demand and reduces lead times, supporting large-scale waste sorting projects nationwide.
- July 2023 – Panasonic Corporation – Announced strategic alliance with local recycling firms – Focuses on deploying IoT-enabled sorting robots, optimizing waste segregation in urban centers.
- September 2023 – NEC Corporation – Invested in new AI research center – Focused on advancing image recognition technologies for waste sorting applications, cementing its position in smart waste management.
- November 2023 – Daifuku Co., Ltd. – Acquired a stake in a robotics startup specializing in optical sorting – Enhances its technological portfolio and accelerates innovation pipeline in waste processing systems.
Frequently Asked Questions
What is the Japan Waste Sorting Robots Market?
The Japan Waste Sorting Robots Market encompasses the development, deployment, and utilization of robotic systems designed to automate waste sorting processes across Japan. This technology aims to improve recycling efficiency, reduce labor costs, and enhance sustainability efforts within the country's waste management sector.
What is the current market size of Japan Waste Sorting Robots Market?
As of 2026, the market size for waste sorting robots in Japan is valued at approximately USD 2.4 Billion, reflecting increased adoption driven by government policies promoting automation and environmental sustainability, alongside technological advancements making these robots more efficient and cost-effective.
What factors are driving the Japan Waste Sorting Robots Market?
Growth drivers include government incentives for smart waste management solutions, rising environmental consciousness, labor shortage in waste processing facilities, and technological innovations like AI and machine learning enhancing robotic sorting capabilities, making automation increasingly viable and valuable in Japan.
Which region dominates the Japan Waste Sorting Robots Market?
Tokyo and the Kanto region are the dominant areas for waste sorting robot deployment, owing to their dense populations, high waste generation rates, and advanced Infrastructure, which facilitate large-scale automation projects and innovations in waste management practices.
Which segment is expected to grow the fastest?
The robotic arm segment, particularly those integrated with AI-driven sorting technology, is projected to register the fastest growth, driven by the need for precise, speedy sorting solutions that address the complex waste streams generated by urban and industrial sources in Japan.
Who are the leading companies operating in the Japan Waste Sorting Robots Market?
Key market players include international companies like TOMRA Systems, Keyence Corporation, and ABB, as well as Japanese firms such as Panasonic and Yaskawa Electric, all competing through technological innovations and strategic partnerships to expand their presence in Japan’s evolving waste management sector.
Analyst Perspective
The Japan Waste Sorting Robots Market is positioned for sustained growth, driven by Japan’s advancing mandates for waste management efficiency and automation. In the long term, the market is expected to evolve with enhanced robotics capabilities, including improved sensors and AI algorithms, reducing labor costs and increasing sorting accuracy. Commercial opportunities are substantial in urban centers such as Tokyo and Osaka, where high population densities generate significant waste volumes and stringent recycling regulations. Technology evolution will focus on integrating IoT connectivity and machine learning for smarter, more adaptable sorting solutions, presenting strategic investment avenues. Competitive intensity is projected to heighten as domestic and international players vie for technological dominance and market share. Regional growth potential is notably robust in metropolitan and peri-urban zones, where infrastructure investments are prioritized. Overall, strategic positioning in this evolving landscape demands a focus on innovative technology adoption, local regulatory alignment, and regional expansion, especially targeting city-level municipal waste management projects that seek to optimize recycling rates and operational efficiency.
