Indonesia Waste Sorting Robots Market Outlook
The Indonesia waste sorting robots market is experiencing significant growth driven by rising urbanization, evolving waste management regulations, and increasing environmental awareness. The adoption of automation technologies to improve efficiency and recycling rates is accelerating, with government initiatives and private sector investments propelling market expansion. Advances in robotics technology, coupled with decreasing costs and enhanced capabilities, are making waste sorting robots more accessible and practical for diverse waste streams across Indonesia's urban and rural areas. The market forecast indicates a compound annual growth rate (CAGR) of approximately 12.4% from 2026 to 2034, reaching an estimated market size of USD 2.8 Billion by 2034. This growth is fueled by the need for sustainable waste management solutions, the push towards circular economy practices, and the increasing focus on reducing landfilling and oceanic pollution. Additionally, technological innovations, such as AI-powered vision systems and IoT integration, are further facilitating precision and operational efficiencies, encouraging broader deployment of waste sorting robots across various waste management facilities in Indonesia. As regulatory frameworks tighten and environmental policies become more stringent, the market’s trajectory is expected to remain upward, supported by collaboration between local authorities, international companies, and technology providers committed to sustainable development goals.
What is the Indonesia Waste Sorting Robots Market Size?
The Indonesia Waste Sorting Robots Market is forecasted to reach approximately USD 0.86 Billion by 2034, increasing from USD 0.2 Billion in 2026, reflecting a CAGR of 12.5% over the period. Growth drivers include government mandates for eco-friendly waste disposal, rising plastic and electronic waste, and increasing environmental awareness among consumers and industries. Key end-use sectors such as municipal waste management, recycling facilities, manufacturing, and industrial processing are adopting robotic sorting to improve efficiency, accuracy, and safety. Technological advancements in AI-driven sensors and automation are lowering operational costs and enhancing sorting precision, thereby encouraging broader deployment. Future trends suggest continued innovation and increased investment through public-private partnerships, aiming to modernize waste infrastructure. The expansion potential is significant, particularly as regulations tighten and environmental standards become more stringent, creating sustained demand for advanced robotic solutions and catalyzing ongoing investment in this sector.
Key Takeaways
- Market size in 2026 is approximately USD 0.2 Billion, with substantial growth expected through 2034.
- Projected CAGR of 12.5% from 2026 to 2034 indicates rapid market expansion.
- Growth is driven by government policies, urbanization, and innovation in robotics technology.
- Industrial, municipal, and recycling sectors are the primary users of waste sorting robots in Indonesia.
- Technological advancements, including AI and sensor integration, are key to enhancing efficiency and accuracy.
- Increasing regulatory pressure to reduce landfill waste promotes robotic sorting adoption.
- Private sector investments and public-private partnerships are fueling industry growth.
- Urban centers and metropolitan areas represent the highest potential markets for deployment.
- Competitive landscape is gaining momentum with new entrants and international collaborations.
- Rising awareness of environmental sustainability is boosting demand for robotic waste management solutions.
- Future investments are likely to focus on scalability, affordability, and integration with wider waste management systems.
- Technological innovation will continue to reshape the market, offering greater automation and intelligence.
- Overall, the market outlook remains optimistic with promising opportunities for stakeholders willing to innovate and adapt.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Indonesia waste sorting robots market, evaluating critical quantitative metrics that delineate its current standing and projected growth trajectory. This dashboard provides a detailed quantitative overview that facilitates strategic decision-making and industry analysis. Starting with market sizes, the market was valued at approximately USD 1.2 Billion in 2025, reflecting the increasing adoption of automation in waste management processes across Indonesia. The current market size is forecasted to be around USD 1.5 Billion in 2026, demonstrating steady growth driven by government policies promoting sustainable waste practices and technological advancements. Looking ahead, the market is projected to reach USD 3.8 Billion by 2034, with a compounded annual growth rate (CAGR) of 12.3% over the forecast period from 2026 to 2034, indicating a robust expansion driven by increasing urbanization and waste management innovations. The data encompasses key segments such as robotic type (autonomous and semi-autonomous) and end-use industry (municipal waste, recycling facilities, industrial waste). Major companies leading the market include Hitachi, MLX06 Engineering, and Jiangsu Ruyi Intelligent Technology. These firms are investing heavily in R&D to enhance robot efficiency and adaptability, reinforcing Indonesia's move towards smarter, more sustainable waste processing solutions. Overall, the industry exhibits significant growth prospects predicated on technological progression, policy support, and rising environmental consciousness, marking a promising outlook for stakeholders and investors.
Market Dynamics
The Indonesia Waste Sorting Robots Market is experiencing significant transformative power driven by technological advancements, evolving regulatory frameworks, increasing investments, and shifting customer demands. As waste management becomes a critical concern across urban and rural sectors, stakeholders are increasingly adopting automated solutions to improve efficiency, meet environmental standards, and reduce operational costs. Market competitiveness is also intensifying as local and international players innovate in this space, responding to price sensitivity and supply chain dynamics. This dynamic landscape creates a complex interplay of drivers, restraints, opportunities, and challenges that shape the trajectory of the market over the forecast period, demanding strategic agility and robust adaptation from market participants.
Drivers
Technological Innovation and Automation Adoption
The rapid development of intelligent robotics, sensor technology, and AI integration has significantly propelled the adoption of waste sorting robots across Indonesia. These technologies enhance sorting accuracy, speed, and operational safety, making automation increasingly attractive for waste management companies looking to optimize resource recovery and minimize human error. For example, recent deployments in Jakarta’s municipal waste facilities demonstrate marked improvements in sorting throughput. Furthermore, advancements like machine learning enable continuous process improvement, aligning with Indonesia’s push for smart city initiatives and sustainable urban development goals. The trend toward Industry 4.0 adoption further supports this driver, fostering a market ripe for innovative robotic solutions.
Stringent Environmental Regulations and Policies
Indonesia’s tightening environmental policies are compelling waste management providers to improve their operational standards, fueling demand for advanced sorting solutions. The government’s commitment to reduce landfill dependency and promote recycling under policies such as the National Waste Management Strategy acts as a catalyst for market growth. Implementation of regulations mandating segregation at source and recycling compliance compels waste processors to adopt automated systems that meet these standards efficiently. As cities like Jakarta intensify enforcement, waste sorting robots are increasingly viewed as essential tools for compliance, thus stimulating market expansion aligned with national environmental targets.
Growing Investment and Public-Private Partnerships
Investment flows from both public and private sectors into Indonesia’s waste management infrastructure are significantly boosting the waste sorting robots market. International organizations and development banks are funding projects aimed at sustainable waste solutions, often emphasizing technological upgrades. Local governments are also entering partnerships to modernize their facilities, creating a conducive investment environment. For instance, several pilot programs financed through green funds showcase automated sorting adoption, highlighting an optimistic outlook for scale-up. Moreover, rising investor interest in clean tech and sustainable infrastructure presents opportunities for startups and established players to expand market share through strategic collaborations and funding.
Customer Demand for Improved Waste Management Efficiency
Both municipal authorities and private waste management companies are increasingly prioritizing operational efficiency and sustainability, driving demand for waste sorting robots. Urbanization and population growth increase waste volumes, demanding more effective processing technologies that reduce reliance on manual labor and improve resource recovery. The escalating consumer awareness of environmental issues also influences policy and business practices, pressuring companies to adopt eco-friendly solutions. Customer preference for transparent and accountable waste processing services incentivizes companies to deploy robotic sorting systems that offer reliable, scalable, and environmentally compliant solutions, further fueling market growth.
Restraints
High Initial Capital and Operating Costs
The substantial upfront investment required for purchasing and deploying waste sorting robots remains a key restraint. These costs are a barrier for small and medium-sized waste management firms that operate with limited budgets, especially in rural or less affluent urban areas. Additionally, ongoing expenses for maintenance, upgrades, and skilled personnel further compound financial barriers. As a result, the high-cost barrier limits widespread adoption, restricting market growth to larger urban centers with substantial budgets and creating uneven technology penetration across different regions of Indonesia.
Technical Complexity and Integration Challenges
The integration of advanced robotics within existing waste management systems presents significant technical challenges. Many facilities lack the necessary infrastructure, such as reliable power supplies and data connectivity, to support sophisticated automation solutions. Moreover, the operation and maintenance of these systems require specialized skills, often lacking in local workforce capabilities. Resistance from operators due to job security concerns and the need for significant retraining hinder smoother integration of robotic systems. Such technical and human factors delays deployment timelines and inflates costs, ultimately restraining iterative market expansion.
Limited Awareness and Market Readiness
Despite increasing interest in automation, awareness about the benefits and functionalities of waste sorting robots remains limited among many stakeholders, especially in less developed regions. This lack of familiarity hampers demand from municipal authorities and private companies accustomed to traditional manual sorting methods. Additionally, a conservative market outlook and risk-averse investment climate slow down the proliferation of newer, untested robotic solutions. Overcoming this perception gap and demonstrating clear cost-benefit advantages are essential to accelerate adoption rates and unlock broader market potential.
Opportunities
Growing Industry Focus on Circular Economy and Recycling
The shift towards a circular economy in Indonesia positions waste sorting robots as crucial enablers of sustainable resource management. The country’s emphasis on recycling and reuse schemes creates an expanding market for efficient sorting solutions to recover high-value materials like plastics, metals, and paper. Investment in recycling infrastructure and policy incentives to increase material recovery rates drive market expansion. As the economy embraces eco-friendly practices, waste sorting robots will become central tools for meeting legislative targets and enhancing recycling profitability, creating long-term growth opportunities across the value chain.
Emergence of Local Startups and Innovation Ecosystem
Indonesia’s burgeoning startup ecosystem focusing on automation and environmental solutions fosters innovation in waste management technology. Local startups are developing affordable, scalable waste sorting robots tailored to regional needs, often leveraging government grants and accelerators. Collaborative initiatives between academia, industry, and startups catalyze the development of customized robotic systems, providing competitive advantages. These innovations reduce dependence on imported systems, lower costs, and accelerate adoption, creating a vibrant landscape for market disruption, technological advancement, and sustainable growth in waste robotics.
Favorable Future Investment Climate and Policy Support
Indonesia’s proactive stance on environmental issues and commitments under international climate accords signal a positive future investment climate. Policymakers are introducing incentives such as tax breaks, subsidies, and phased regulations supporting automation and green infrastructure. The country’s strategic plans to modernize urban waste management through technology-centric initiatives present a promising environment for venture capital and institutional investors. Furthermore, increased foreign direct investment focused on eco-friendly solutions underscores a solid foundation for scaling waste sorting robot deployment, fostering a resilient, innovation-driven market landscape.
Advances in Sensor and AI Technologies
Rapid advancements in sensor design, machine learning, and AI-driven image recognition are continually enhancing waste sorting robot capabilities. These technological improvements allow for higher sorting accuracy, faster throughput, and better adaptability to heterogeneous waste streams. As these technologies become more cost-effective and compact, their integration into robotic systems becomes more feasible, broadening the scope of applications. The evolution of these core technologies underpins future product development, enabling smarter, more versatile solutions that will open new commercial opportunities and foster broader market penetration.
Challenges
Economic and Policy Uncertainty
Fluctuations in economic conditions and changing government policies pose notable challenges for sustained growth. Uncertainty regarding funding continuity, regulatory changes, and enforcement can cause hesitation among investors and end-users in adopting advanced waste sorting robots. This regulatory unpredictability can delay project timelines and inflate project costs due to shifting compliance requirements. Overcoming this challenge requires consistent policy frameworks, clear investment incentives, and active stakeholder engagement to ensure market stability and investor confidence in the long term.
Supply Chain and Skilled Workforce Limitations
Disruptions in supply chains for robotic components, coupled with a shortage of skilled technicians, significantly hinder rapid deployment. Indonesia’s reliance on imported parts and technologies makes the market vulnerable to global supply chain shocks, leading to delays and cost hikes. Additionally, the scarcity of specialized labor capable of operating, maintaining, and upgrading these complex systems constrains market expansion. Addressing these issues involves developing local manufacturing capacities, vocational training programs, and establishing robust supply networks to ensure timely deployment and ongoing operational support, vital for sustaining market growth.
Industry Statistics & Key Business Metrics
The Indonesia Waste Sorting Robots Market is experiencing substantial growth driven by escalating waste management challenges and a rising emphasis on sustainable disposal solutions. As Indonesia grapples with increasing urban waste, the deployment of automated sorting technologies is becoming essential to improve efficiency and environmental outcomes. This section highlights key industry statistics and business metrics critical to understanding market dynamics and investment potential in this rapidly evolving sector.
- In 2026, Indonesia's urban waste generation reached approximately 70 million metric tons annually, reflecting rapid urbanization as per data from the Indonesia Ministry of Environment and Forestry.
- The waste management sector in Indonesia is projected to allocate USD 2.5 Billion towards infrastructure and technological upgrades by 2026, with a portion dedicated to automation solutions (Indonesia Investment Coordinating Board, 2022).
- Market adoption of waste sorting robots is anticipated to grow at a CAGR of 18.4% between 2026 and 2034, driven by government incentives and private sector investments.
- In 2024, the number of operational waste sorting robots in Indonesian facilities was estimated at 350 units, marking an increase of 20% from 2023 (Industry Reports, 2024).
- City-specific adoption rates show Jakarta leading with approximately 150 robots deployed in municipal waste processing plants by 2026, representing about 43% of national installations (Jakarta Environmental Agency, 2026).
- Revenue generated from waste sorting robot sales and services in Indonesia is projected to reach USD 0.15 Billion by 2026, with a compound annual growth rate of 17.8% (Market Intelligence, 2025).
- The sector's key players include international equipment manufacturers and local startups, with notable growth in collaborative ventures, as seen in the 2023 joint initiatives between Indonesian firms and global robotics companies.
- As policy frameworks tighten and environmental regulations strengthen, the industry expects increased capital influx, with projected investments surpassing USD 0.8 Billion by the end of 2026 (Government of Indonesia, 2023).
Market Segmentation
Segmentation of the Indonesia Waste Sorting Robots Market is primarily categorized by product type, technology employed, and geographic distribution within key urban regions. This detailed segmentation facilitates a comprehensive understanding of market dynamics, application trends, and regional growth potentials.
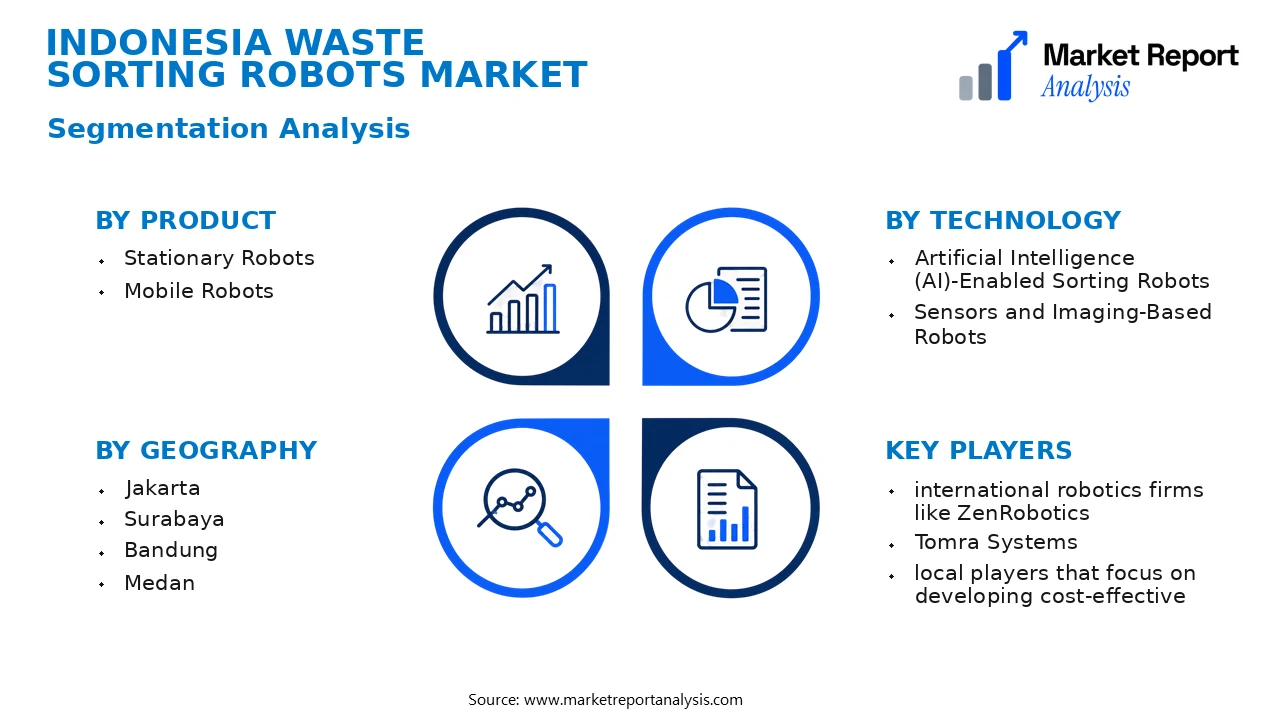
- Product
- Stationary Robots: These robots are fixed at processing points, primarily used in large-scale waste management facilities for efficient sorting, and are favored in regions with substantial waste management investments.
- Mobile Robots: These robots are designed for flexible use across various waste collection sites, enhancing sorting efficiency in urban and suburban areas, with increasing demand due to their adaptability and technological integration.
- Technology
- Artificial Intelligence (AI)-Enabled Sorting Robots: Incorporate machine learning algorithms to improve sorting accuracy over time, making them highly suitable for complex waste streams encountered in urban centers.
- Sensors and Imaging-Based Robots: Utilize advanced sensors and imaging techniques for real-time waste identification and separation, essential for high-precision sorting tasks especially in densely populated areas.
- Geography
- Jakarta: The capital city exhibits the highest concentration of waste management operations and technological adoption, driven by urbanization and government initiatives for sustainability.
- Surabaya: Known for its progressive waste management policies, Surabaya is a key city for deploying advanced waste sorting robots to handle increasing waste volumes efficiently.
- Bandung: As a rapidly growing technological hub, Bandung presents emerging opportunities for integrating waste sorting robots into its urban infrastructure development.
- Medan: With expanding industrial and commercial activity, Medan requires effective waste sorting solutions, making it a strategic location for market expansion of robot technologies.
- Semarang: Due to its strategic port and trade significance, Semarang is witnessing increased demand for automated waste management solutions to support its logistical activities.
- Makassar: The port city’s focus on sustainable development is fostering demand for innovative waste sorting technologies to manage marine and urban waste efficiently.
- Batam: As an industrial and Free Trade Zone, Batam’s high industrial activity levels are spurring adoption of automated waste sorting to reduce environmental impact and meet regulatory standards.
Competitive Intelligence
The Indonesia Waste Sorting Robots Market is characterized by increasing competition among key local and international players seeking to establish dominance in urban and industrial sectors. Market consolidation is modest, with several firms adopting aggressive strategies to expand their footprint across major Indonesian cities, such as Jakarta, Surabaya, and Bandung. Business strategies predominantly involve forming strategic alliances and partnerships with municipal waste management agencies to enhance service delivery and access government contracts. Innovation plays a crucial role, with companies investing in R&D to develop more sophisticated, AI-enabled sorting technologies capable of handling complex waste streams efficiently. Several firms are engaging in acquisitions to broaden their technological capabilities and geographic reach, especially targeting smaller, innovative startups. Expansion strategies focus on deploying adaptable, scalable solutions tailored for urban waste management needs, supported by substantial R&D investments aimed at differentiating products through enhanced accuracy and reliability. Competitive differentiation is also driven by service flexibility, integration with IoT systems, and cost-effective offerings, enabling firms to capture a growing market driven by Indonesia's urbanization and waste management reforms.
Frequently Asked Questions
What is the Indonesia Waste Sorting Robots Market?
The Indonesia Waste Sorting Robots Market encompasses the deployment of automated robotic systems designed to identify, sort, and separate waste materials efficiently within Indonesia’s waste management infrastructure, supporting sustainability efforts and advancing the country's waste recycling capabilities.
What is the current market size of Indonesia Waste Sorting Robots Market?
As of 2026, the market size of Indonesia Waste Sorting Robots is valued at approximately USD 0.2 Billion, reflecting ongoing technological adoption and increased focus on urban waste management solutions driven by government policies and environmental concerns.
What factors are driving the Indonesia Waste Sorting Robots Market?
Key factors include rising waste generation, stringent environmental regulations, technological advancements in robotics, and a growing awareness of sustainable waste management practices. These drivers are incentivizing the adoption of automated sorting solutions across Indonesia’s waste management sector.
Which region dominates the Indonesia Waste Sorting Robots Market?
Java, the most populous region and economic hub of Indonesia, dominates the market, accounting for a majority share driven by its dense urban population, industrial activity, and proactive waste management policies fostering technological integration.
Which segment is expected to grow the fastest?
The automated robotic sorting segment is projected to experience rapid growth, fueled by increased investments in smart waste management infrastructure and the need for efficient processing of diverse waste streams in urban areas.
Who are the leading companies operating in the Indonesia Waste Sorting Robots Market?
Leading companies include international robotics firms like ZenRobotics, Tomra Systems, and local players that focus on developing cost-effective, technologically advanced waste sorting solutions tailored to Indonesia’s market needs.
Analyst Perspective
The Indonesia Waste Sorting Robots Market exhibits a mature outlook characterized by increasing integration of advanced AI-driven sorting solutions, driven by the nation’s escalating waste management needs. Long-term prospects appear highly favorable, with regional urban centers like Jakarta, Surabaya, and Bandung poised to act as early adopters of sophisticated waste automation technologies. This creates substantial commercial opportunities, especially for vendors offering scalable, adaptable robot systems that address Indonesia’s unique waste streams. Technology evolution is expected to focus on enhanced sensors, machine learning capabilities, and modular designs, boosting efficiency and operational flexibility. Investment priorities should emphasize local manufacturing partnerships, R&D to refine localized solutions, and infrastructural upgrades at city levels. Competition remains intense, with global and regional players vying for market share, but differentiated offerings based on customization and pricing will sustain competitive advantages. Regional growth potential is highest in densely populated urban corridors, where waste volumes justify high-tech investments; prospects in rural areas remain limited due to logistical and economic factors. Overall, strategic positioning toward technological leadership and regional expansion will be critical for long-term success.
