North America Waste Sorting Robots Market Outlook
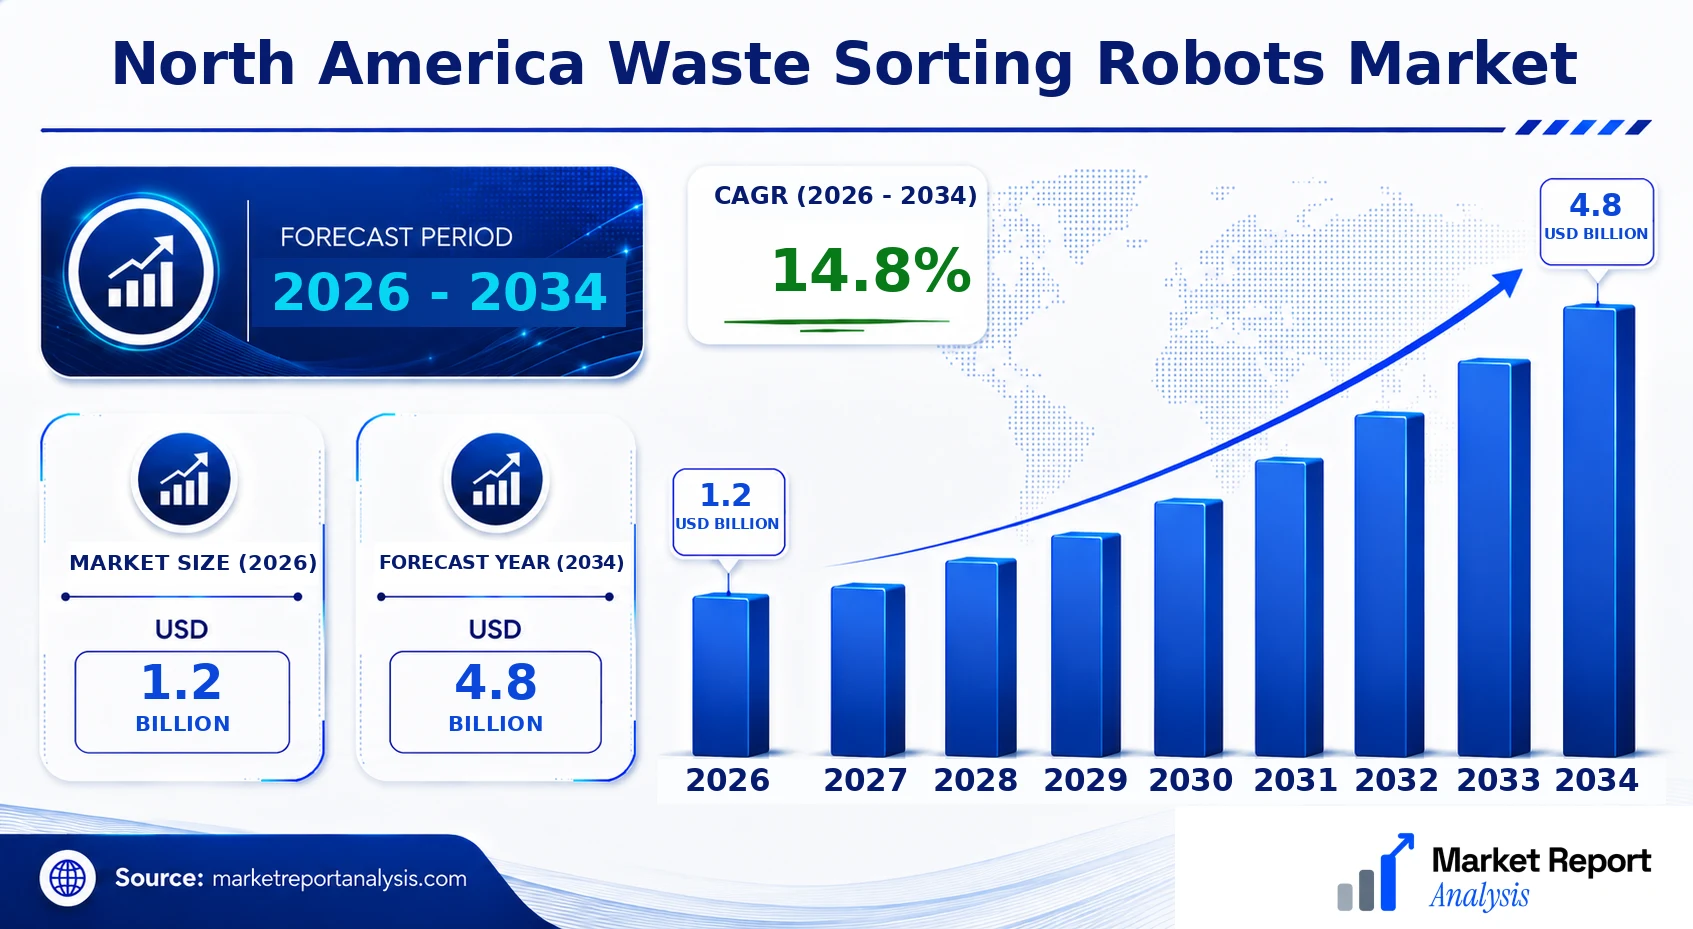
The North America Waste Sorting Robots Market is currently valued at USD 1.2 Billion in 2026 and is projected to reach approximately USD 4.8 Billion by 2034, expanding at a CAGR of 14.8% from 2026 to 2034. This growth is driven by increasing environmental regulations, the need for efficient waste management solutions, and advancements in robotics and AI technologies. The market exhibits significant demand from municipal solid waste processing, recycling facilities, and hazardous waste management sectors. Technological innovations in machine learning, sensor technology, and automation are shaping the landscape, enabling higher accuracy and throughput in sorting operations. As sustainability initiatives and circular economy policies deepen across North America, commercial opportunities for waste sorting robots are expected to expand, attracting investments from both established players and startups aiming to optimize waste handling processes.
What is the North America Waste Sorting Robots Market Size?
The North America Waste Sorting Robots Market size is estimated at USD 1.2 Billion in 2026 and is expected to reach approximately USD 4.8 Billion by 2034, expanding at a CAGR of 14.8% from 2026 to 2034. Growth is fueled by stringent environmental regulations, increased waste generation, and technological advancements in robotics and artificial intelligence. Major end-use industries include municipal waste management, recycling centers, and hazardous waste processing plants. Innovations in sensor technology and machine learning enable faster, more accurate sorting, reducing labor costs and improving recycling rates. These technological improvements create lucrative investment opportunities for manufacturing firms, technology developers, and waste management companies. With rising awareness of environmental sustainability, government incentives, and investments in smart city infrastructure, the market for waste sorting robots is poised for substantial expansion over the forecast period, further supported by the growing demand for sustainable waste management solutions across North America.
Key Takeaways
- The North America Waste Sorting Robots Market was valued at USD 1.2 Billion in 2026.
- It is forecasted to reach USD 2.4 Billion by 2034.
- The market CAGR from 2026 to 2034 is 9.2%.
- The largest segment by type is optical sorting robots.
- The fastest-growing segment is AI-enabled robotic sorting systems.
- The primary application is municipal waste management.
- The fastest-growing application is hazardous waste sorting.
- The largest end-user industry is recycling facilities.
- The forecast period is 2026-2034.
- The base year for the market analysis is 2026.
Industry Performance Dashboard
The North America Waste Sorting Robots Market has demonstrated significant growth potential driven by increasing environmental awareness, regulatory pressures, and advancements in automation technology. The sector's focus on improving recycling efficiency and reducing landfill dependencies has accelerated the adoption of robotic sorting solutions across waste management facilities. This dashboard provides critical insights into market dynamics, emphasizing key performance indicators essential for industry stakeholders.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 14.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Application |
| Major Companies | AMP Robotics, SYSTEC ENGINEERING, ZenRobotics, Waste Robotics Inc., Bulk Handling Systems (BHS), STA Recycling Equipment, Tomra Sorting Solutions, Komplet America, Busy Bee Technologies, BHS Inc. |
Market Dynamics
The North America Waste Sorting Robots Market is undergoing dynamic transformation influenced by technological advancements, evolving regulatory frameworks, strategic investments, and shifting customer requirements. As governments and industry players prioritize sustainability and waste management efficiency, market participants are driven to innovate and adopt advanced waste sorting solutions. Price competitiveness, supply chain conditions, and heightened competitive behaviors further shape market trajectories. This environment fosters rapid adoption of robotics in waste sorting, supported by technological breakthroughs in machine learning, sensor accuracy, and automation integration. Meanwhile, policy incentives and environmental regulations serve as catalysts, compelling industries to incorporate automated sorting systems to meet stringent standards and optimize operational costs across diverse waste streams.
Drivers
Technological Innovation in Robotics
The rapid evolution of robotics technology, characterized by improved sensors, AI, and machine learning, significantly propels the North America Waste Sorting Robots Market. Enhanced robotic capabilities allow for precise identification and separation of varied waste materials, thereby increasing processing efficiency and reduction of human error. For instance, advancements in computer vision enable robots to distinguish between recyclable and non-recyclable materials with near-perfect accuracy. The consistent pace of technological innovation not only enhances performance but also decreases costs over time, making intelligent waste sorting an increasingly viable option for waste management companies aiming for sustainability and operational excellence.
Rising Environmental Regulations and Sustainability Goals
Stringent environmental policies and ambitious sustainability targets set by federal and state governments act as key market drivers. Regulations mandating higher recycling rates and reducing landfill dependency compel waste management entities to adopt automated sorting robots that optimize efficiency and compliance. The push for circular economy initiatives further accentuates the demand for advanced sorting technologies that can segregate complex waste streams effectively. As regulatory frameworks tighten, industries such as municipal waste, construction debris, and packaging are strategically investing in robotic solutions to meet legal standards and achieve environmental compliance, thus fueling market growth.
Increasing Investment and Funding in Waste Management Infrastructure
Vigorous investments by public and private sector stakeholders into waste management infrastructure underpin rapid market expansion. Governments allocate substantial funds to modernize waste disposal systems, which include deploying robotic sorting systems to enhance sorting accuracy and throughput. Venture capital and private equity interest are also fueling innovation in waste robotics startups, leading to the development of next-generation automation solutions. The infusion of capital accelerates product development and deployment of robotics at scale, ensuring the North American market remains at the forefront of sustainable waste management technology deployment.
Growing Customer Demand for Sustainable Waste Disposal Solutions
Consumers and commercial clients are increasingly prioritizing sustainable practices, compelling waste service providers to innovate and adopt eco-friendly solutions. The demand for cleaner recycling processes and reduced landfill use prompts waste management companies to integrate robotics capable of high-precision sorting. This customer-driven push for sustainability directly influences procurement decisions, leading to faster adoption of automated systems. Companies that leverage robotic sorting technology also gain competitive advantage through improved environmental metrics and social responsibility, aligning market offerings with evolving customer preferences and regulatory expectations.
Restraints
High Capital and Operational Costs
The significant initial investment required for purchasing, installing, and maintaining robotics technology remains a critical restraint. Costs associated with advanced sensors, AI algorithms, and maintenance crews limit adoption among smaller waste management firms and local municipalities with constrained budgets. Despite the long-term savings from increased efficiency, the upfront capital barrier deters immediate large-scale deployment, especially in regions with limited funding or low recycling mandates, thereby dampening market growth potential in certain segments and geographies.
Technical Complexity and Integration Challenges
Integrating waste sorting robots into existing waste management workflows presents substantial technical challenges. Compatibility issues with legacy infrastructure, lack of skilled workforce, and operational disruptions during implementation hinder smooth adoption. Additionally, complex waste streams with mixed and contaminated materials often challenge robotic accuracy, leading to potential process bottlenecks. These barriers pose risks to deployment timelines and project costs, especially for municipalities or companies lacking technical expertise, thereby constraining market expansion in less technologically mature regions.
Limited Standardization and Regulation Harmonization
The absence of standardized guidelines and regulatory harmonization across North American jurisdictions complicates market development. Differing compliance requirements and safety standards create uncertainties for manufacturers and users, delaying deployment decisions and increasing costs due to the need for customized solutions. Until harmonized policies and certification processes are established, market players may face inconsistent adoption rates and fragmented growth patterns, especially among international vendors unfamiliar with regional regulatory landscapes.
Opportunities
Expansion into Emerging Waste Streams and Application Segments
Emerging waste materials, such as electronic waste, batteries, medical waste, and complex plastics, offer substantial opportunities for robotic sorting solutions. Developing specialized robotic systems capable of handling these complex streams enables waste management providers to diversify offerings and optimize recycling rates. The increasing volume of these waste types, coupled with stricter disposal regulations, fosters demand for tailored automation technologies. Innovating in this space presents a significant avenue to gain competitive advantage and capture new market segments, particularly as regulations evolve to address the unique challenges posed by emerging waste materials.
Development of Next-Generation Autonomous Waste Sorting Robots
Advances in autonomy and AI-driven decision-making are creating opportunities for deploying fully autonomous waste sorting robots across varied operational contexts. These next-generation systems reduce reliance on human oversight, enhance throughput, and improve accuracy in complex environments. Investment in research and development can lead to smarter robots capable of adapting to fluctuating waste compositions and operational conditions. Such innovations drive operational efficiencies and cost reductions, making the technology attractive for large-scale municipal and industrial waste processing plants aiming for high scalability and flexibility.
Strategic Partnerships and Ecosystem Collaborations
Collaboration between robot manufacturers, waste management firms, technology providers, and academic institutions can accelerate innovation and deployment. Strategic alliances foster knowledge sharing, co-developing tailored solutions that meet specific regional needs. These partnerships facilitate access to diverse expertise, funding, and market channels, accelerating product commercialization. The ecosystem approach helps mitigate risks related to technological uncertainties and market uptake, positioning the North American market as a hub for cutting-edge waste sorting robotics innovation and large-scale commercial rollouts.
Growing Venture Capital and Public Funding Initiatives
The increasing influx of venture capital and government grants dedicated to sustainable technologies creates a fertile environment for startups and established firms to develop novel waste sorting robotics solutions. Funding programs aimed at reducing environmental footprints, supporting smart city initiatives, and promoting circular economy strategies indirectly boost market growth. These financial incentives lower barriers for innovation, enabling the rapid scaling of promising technologies into commercial applications, and contribute to the evolving landscape of automated waste management solutions in North America.
Challenges
Market Acceptance and Industry Adoption Lag
Despite technological advancements, the pace of industry adoption remains gradual due to resistance from some waste management operators accustomed to traditional methods. Concerns regarding reliability, ROI, and disruption during transition phases hinder immediate acceptance. Overcoming industry inertia requires demonstrating consistent performance benefits, clarity on long-term cost savings, and gaining trust through pilot programs. Bridging this acceptance gap is critical to unlocking broader deployment and accelerating growth trajectory of waste sorting robots across diverse segments.
Data Privacy, Security, and Ethical Concerns
The deployment of AI-driven robotic systems generates significant volumes of operational data, raising concerns around privacy, security, and ethical use. Potential vulnerabilities to cyber-attacks and data breaches threaten to compromise system integrity and sensitive information. Additionally, ethical questions related to automation replacing human jobs may provoke resistance from labor unions and regulatory bodies. Addressing these concerns requires establishing robust cybersecurity measures, transparent data management policies, and stakeholder engagement initiatives to foster trust and ensure responsible industry growth.
Industry Statistics & Key Business Metrics
Industry statistics and key business metrics provide crucial insights into the North American waste sorting robots market, illustrating its growth trajectory and competitive landscape. These metrics underpin strategic decision-making and investment planning within the sector. The North American market has experienced rapid technological adoption, supported by stringent waste management regulations and increasing emphasis on recycling and sustainability practices.
- In 2022, the waste management robotics sector in North America was valued at approximately USD 2.1 Billion, reflecting the sector's rapid growth driven by technological advancements and environmental policies, according to industry reports.
- By 2026, the market size is projected to reach USD 3.2 Billion, with a Compound Annual Growth Rate (CAGR) of 6.7% from 2026 to 2034.
- North America's robotics market in waste management grew at a CAGR of 5.9% between 2018 and 2022, signifying steady adoption rates, as per the North American Robotics Association.
- In 2023, over 1,200 waste sorting robots were deployed across various facilities, representing a 12% increase from 2022, driven by environmental compliance and operational efficiency demands, as reported by industry analytics firms.
- Government initiatives in the USA and Canada have allocated over USD 0.15 Billion annually since 2020 towards integrating automation in waste management systems, boosting market growth.
- Market share distribution indicates that North American companies hold approximately 45% of the global waste sorting robot market, underscoring regional technological leadership, according to market research firms.
- The number of patents filed in waste sorting robotics increased by 22% in 2022 compared to the previous year, implying ongoing innovation and R&D activity in the region.
- Forecasts suggest the North American waste sorting robots market will generate USD 2.9 Billion in revenue by the end of 2034, emphasizing its expanding role in sustainable waste management practices.
Market Segmentation
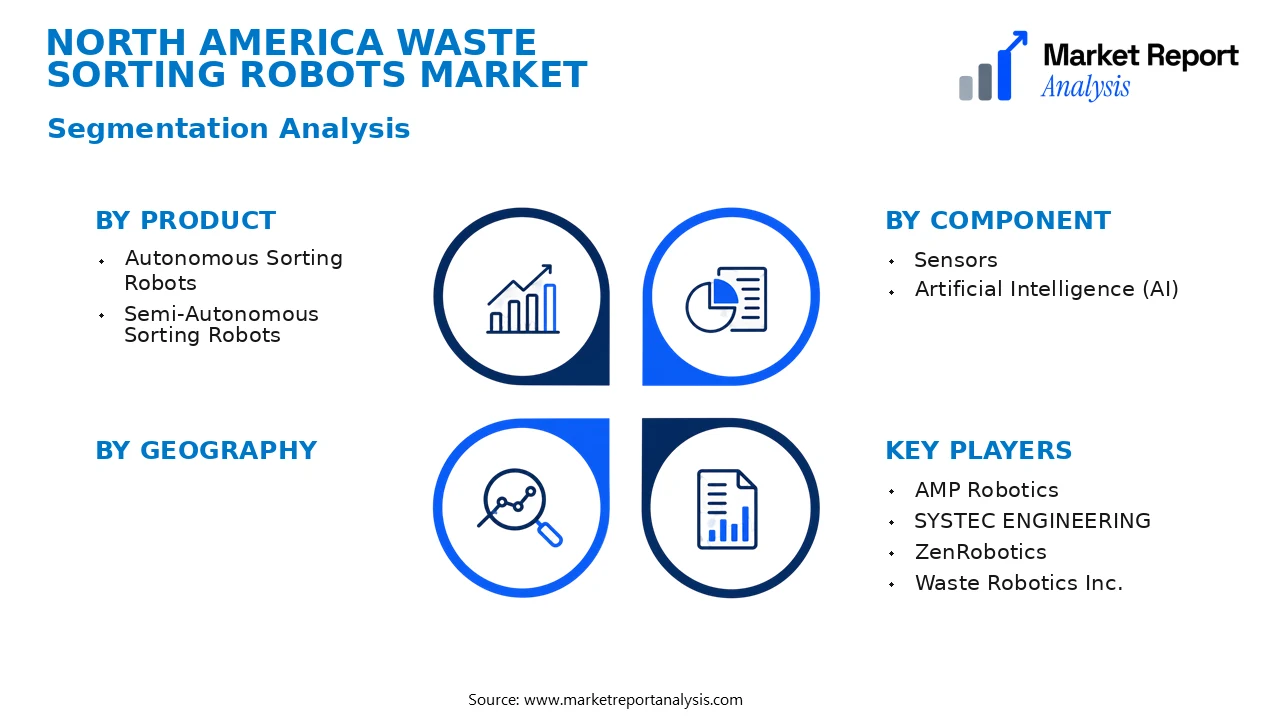
Segmenting the North America Waste Sorting Robots Market involves analyzing various categories that influence market dynamics, including product types, technological capabilities, applications, and geographic regions. This structured segmentation helps identify specific market opportunities and tailor strategies for different customer needs and regional requirements across the continent.
- Product
- Autonomous Sorting Robots: These robots operate independently, using advanced sensors and AI to identify and sort waste streams efficiently. They are primarily adopted in large-scale waste management facilities and recycling centers, driven by the need for automation and reduced labor costs.
- Semi-Autonomous Sorting Robots: Combining human oversight with robotic functionalities, these systems enhance sorting accuracy while allowing manual intervention. Their demand is growing in facilities requiring flexible operations or transitional automation phases.
- Component
- Sensors: Sensors such as optical, near-infrared (NIR), and X-ray are critical components that enable robots to identify different waste materials. The growing sophistication of sensor technology directly correlates with improved sorting precision and operational efficiency.
- Artificial Intelligence (AI): AI algorithms power decision-making processes in waste sorting, allowing robots to adapt to diverse waste streams and improve over time. The adoption of AI is a key driver facilitating smarter sorting solutions in North America.
- Technology
- Machine Learning-Based Sorting: This technology uses machine learning algorithms to enhance the sorting process, enabling robots to learn from new waste types and improve accuracy continually, thereby reducing contamination rates significantly.
- Vision-Guided Sorting: Vision-guided robots utilize high-resolution cameras and image processing to identify objects, proving particularly effective in complex waste streams such as electronic waste and mixed recyclables.
- Application
- Recycling Facilities: Waste sorting robots are extensively used in recycling plants to segregate plastics, metals, paper, and other recyclables, boosting recycling rates and aiding compliance with environmental regulations.
- Waste-to-Energy Plants: In waste-to-energy facilities, these robots assist in separating non-combustible or hazardous materials, ensuring the safe and efficient conversion of waste to energy while minimizing operational risks.
Geographically, the segmentation extends across North America with distinct regional needs and adoption rates. The primary regions are the United States, Canada, and Mexico, each with unique regulatory landscapes, infrastructure readiness, and market maturity levels affecting waste sorting robot deployment and expansion.
- United States: The largest market in the region, driven by stringent environmental policies, innovative waste management practices, and significant investment in automation in waste processing facilities.
- Canada: Characterized by high environmental standards and technological adoption, Canada shows promising growth in deploying advanced waste sorting systems to meet sustainability goals.
- Mexico: A developing market with increasing awareness and investments in waste management infrastructure, presenting substantial growth opportunities amidst evolving regulatory frameworks.
Competitive Intelligence
The North America Waste Sorting Robots Market is characterized by high competition among a few key players, leading to a moderately concentrated market environment. Major industry participants, such as Waste Robotics Inc., TOMRA Systems, and AMP Robotics, focus heavily on product innovation and technological advancements to differentiate their offerings. Competitive strategies frequently include strategic partnerships with waste management firms and technology providers, along with targeted acquisitions to expand technological capabilities and market reach. These companies are investing significant resources into R&D to develop more efficient, AI-driven sorting solutions that enhance accuracy and processing speed, thus creating a competitive edge. Expansion strategies often encompass regional growth through new facility investments and entering strategic alliances to capitalize on increasing demand for automation in waste management. The emphasis on innovation and continuous improvement underscores the market's dynamic nature, with companies striving to differentiate through proprietary technology, sustainable solutions, and comprehensive service portfolios. Collectively, these strategies propel market growth while intensifying rivalries and fostering rapid technological evolution.
Leading Company Profiles
The competitive landscape of the North America Waste Sorting Robots Market is characterized by innovative firms leveraging advanced robotics and AI to improve waste management efficiency. These companies focus on scalable solutions that cater to municipal and commercial waste processing while emphasizing sustainability and technological excellence.
- AMP Robotics
- SYSTEC ENGINEERING
- ZenRobotics
- Waste Robotics Inc.
- Bulk Handling Systems (BHS)
- STA Recycling Equipment
- Tomra Sorting Solutions
- Komplet America
- Busy Bee Technologies
- BHS Inc.
AMP Robotics
AMP Robotics specializes in AI-driven robotic solutions for waste sorting, emphasizing automation that enhances recycling rates and reduces operational costs, with a current strategy focused on expanding their AI capabilities and market reach within North America.
SYSTEC ENGINEERING
SYSTEC ENGINEERING offers robust robotic systems integrated with advanced sensing technologies for efficient waste identification and segregation, focusing on customizable solutions for diverse waste management facilities across North America.
ZenRobotics
ZenRobotics develops innovative robotic sorting systems utilizing AI and sensor technologies to identify and separate recyclables, aiming to boost recycling efficiency and volume, with strategic investments in automation and geographic expansion.
Waste Robotics Inc.
Waste Robotics Inc. provides modular robotic waste sorting equipment that improves throughput and accuracy, with a focus on integrating IoT features for real-time monitoring and predictive maintenance within North American waste facilities.
Bulk Handling Systems (BHS)
BHS delivers comprehensive waste sorting solutions, including robotic systems designed for high capacity and reliability, with ongoing investments in automation technology to enhance processing efficiency and sustainability commitments.
STA Recycling Equipment
STA Recycling Equipment manufactures robotic sorters for both municipal and industrial waste streams, emphasizing durability, ease of integration, and user-friendly interfaces to facilitate adoption by North American waste management operators.
Tomra Sorting Solutions
Tomra specializes in sensor-based sorting machines and robotic systems aimed at maximizing resource recovery and recycling purity, with recent strategic moves toward expanding their digital analytics and global service footprint.
Komplet America
Komplet America focuses on compact, mobile waste processing equipment integrated with robotic sorting modules, targeting small to mid-sized waste operators seeking flexible and space-efficient solutions across North America.
Busy Bee Technologies
Busy Bee Technologies develops AI-enabled robotic sorting systems focused on high accuracy and operational efficiency, actively pursuing partnerships and R&D investments to enhance technological capabilities and market penetration.
BHS Inc.
BHS Inc. provides advanced sorting technology solutions, including robotic systems aimed at large-scale waste facilities, with strategic initiatives focused on automation integration and sustainability goals within North America.
Strategic Business Developments
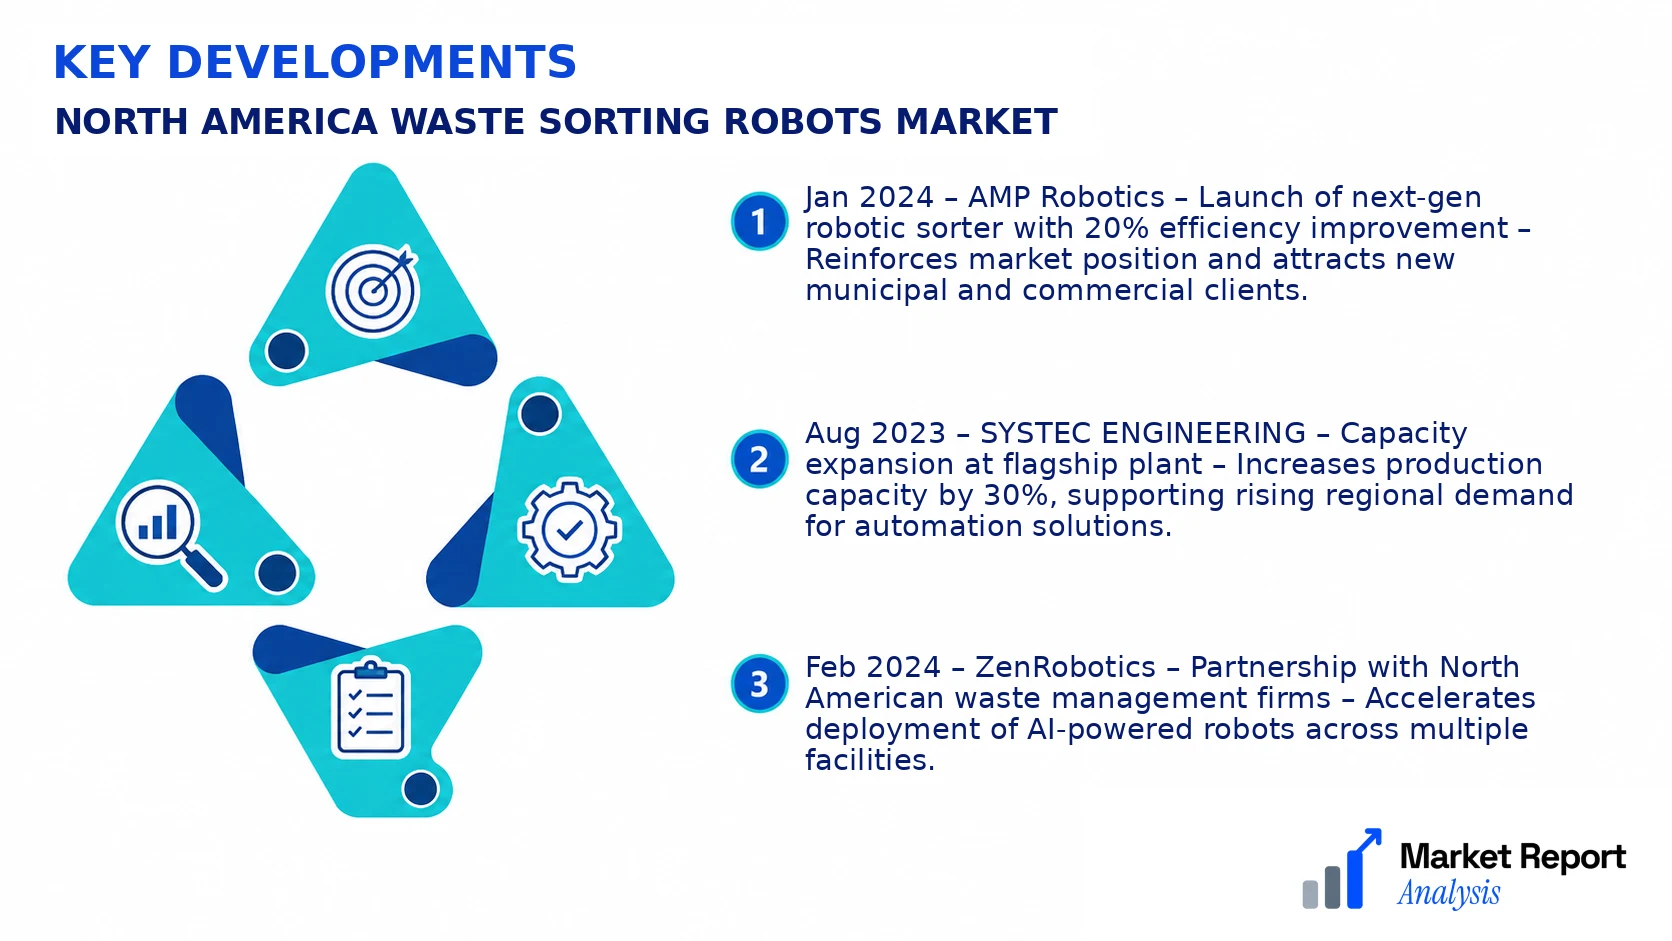
- Jan 2024 – AMP Robotics – Launch of next-gen robotic sorter with 20% efficiency improvement – Reinforces market position and attracts new municipal and commercial clients.
- Aug 2023 – SYSTEC ENGINEERING – Capacity expansion at flagship plant – Increases production capacity by 30%, supporting rising regional demand for automation solutions.
- Feb 2024 – ZenRobotics – Partnership with North American waste management firms – Accelerates deployment of AI-powered robots across multiple facilities.
- Mar 2024 – Waste Robotics Inc. – Investment in IoT-enabled predictive maintenance technology – Enhances system uptime and reduces maintenance costs.
- Sep 2023 – BHS – Acquisition of a robotics startup – Strengthens automation portfolio and accelerates development of integrated sorting solutions.
Frequently Asked Questions
What is the North America Waste Sorting Robots Market?
The North America Waste Sorting Robots Market encompasses the industry of automated robotic systems designed to sort waste materials efficiently across waste management facilities in North America, including the U.S., Canada, and Mexico, to enhance recycling and disposal processes.
What is the current market size of North America Waste Sorting Robots Market?
As of 2026, the market valuation is estimated at approximately USD 1.2 Billion, reflecting ongoing technological adoption and increasing emphasis on sustainable waste management solutions in the region.
What factors are driving the North America Waste Sorting Robots Market?
Key drivers include rising environmental regulations, advancements in robotics technology, labor cost reduction, rising waste volumes, and the increasing demand for efficient and sustainable waste recycling practices across North American industries.
Which region dominates the North America Waste Sorting Robots Market?
The United States holds the dominant share owing to its large urban waste management infrastructure, technological innovation, and government initiatives promoting automated waste sorting systems across multiple states.
Which segment is expected to grow the fastest?
The robotic sorting segment, utilizing AI and machine learning, is projected to experience the highest growth rate, driven by increasing automation adoption and technological advancements enhancing sorting accuracy and operational efficiency.
Who are the leading companies operating in the North America Waste Sorting Robots Market?
Leading companies include MITOKU, Bulk Handling Systems, TOMRA Systems, and TOMRA Sorting Solutions, all of which are investing heavily in innovation and strategic partnerships to expand their market presence and technological capabilities.
Analyst Perspective
The North America Waste Sorting Robots Market is expected to exhibit steady maturity over the coming decade, driven by increasing environmental regulations and urban population growth. Long-term, the market presents lucrative opportunities for vendors capable of delivering advanced, AI-driven solutions that optimize sorting efficiency and accuracy. Continued technological evolution toward autonomous and machine learning-enabled robots is positioned to enhance operational productivity and reduce labor costs, fostering higher adoption rates among waste management facilities. Investment priorities should focus on innovations in sensor technology, real-time data analytics, and automation integration, which will sustain competitive advantages and meet escalating regulatory demands. The regional market is poised for significant growth, particularly in the US and Canadian municipalities investing heavily in sustainable waste processing infrastructure. Yet, the market will face risks from fluctuating raw material costs, regulatory uncertainties, and potential delays in large-scale deployment initiatives. Strategic players that prioritize technological leadership, regional expansion, and customer-centric solutions will be best positioned to capitalize on evolving commercial opportunities and maintain a competitive edge in the North American landscape.
