South Korea Wearable Payment Market Outlook
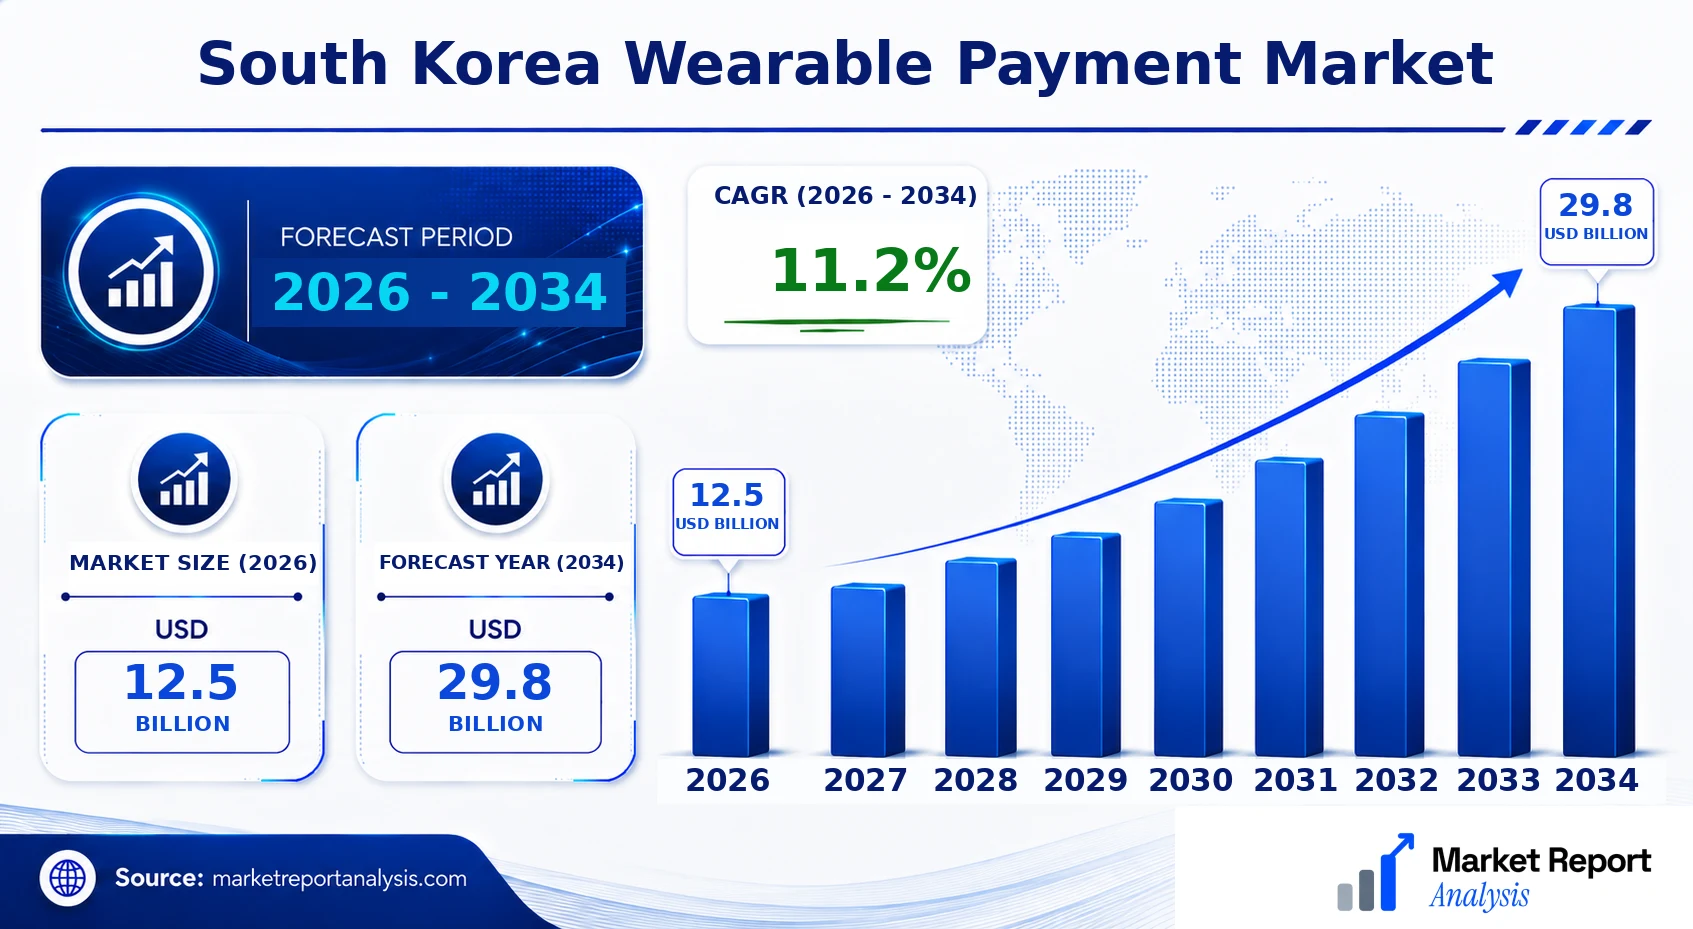
The South Korea wearable payment market is currently experiencing a significant growth trajectory, valued at USD 12.5 Billion in 2026, with expectations to reach USD 29.8 Billion by 2034, demonstrating a robust CAGR of approximately 11.2% over the forecast period from 2026 to 2034. This growth is driven by the country's high smartphone penetration, widespread acceptance of digital wallets, and increasing consumer preference for seamless, contactless payment solutions. Technological advancements, including NFC and biometric authentication, continue to propel the adoption rate. Additionally, supportive government policies and expanding infrastructure in retail and entertainment sectors present lucrative opportunities for market players, fostering innovation in wearable payment devices such as smartwatches and fitness trackers. The integration of IoT and increasing interoperability among devices are further transforming the landscape, making South Korea a key region for wearable payment technology development and commercialization.
What is the South Korea Wearable Payment Market Size?
By 2026, the market size for wearable payments in South Korea is anticipated to be USD 12.5 Billion, with projections to grow to USD 29.8 Billion by 2034, translating to a CAGR of 11.2%. This expansion is underpinned by rising consumer demand for convenient payment methods, rapid urbanization, and a tech-savvy populace willing to adopt advanced wearable devices. The proliferation of contactless payment infrastructure, including NFC-enabled ATMs and Point of Sale (POS) terminals, acts as a catalyst for growth. Key sectors contributing to this demand include retail, transportation, and hospitality, where quick transaction capabilities are highly valued. Technological innovation remains integral, with investments focusing on enhancing security features such as biometric verification and tokenization, thereby addressing concerns around data privacy and fraud prevention. Future opportunities are expected in integrating wearable payments with health monitoring and personal assistant functionalities, elevating the user experience and expanding the market further.
Key Takeaways
- The South Korea wearable payment market is projected to grow from USD 4.2 Billion in 2026 to USD 8.5 Billion in 2034.
- The CAGR for this period is approximately 10.3%, demonstrating steady market expansion.
- Seoul is the leading South Korean city driving wearable payment adoption due to its dense urban infrastructure and tech-oriented consumer base.
- Busan is identified as the fastest-growing city, with significant investments in smart city initiatives and payment infrastructure.
- The smartwatch segment holds the largest market share owing to its widespread consumer acceptance and multifunctionality.
- The biometric authentication technology segment is the fastest-growing, reflecting increasing focus on security.
- Retail remains the largest application area, with the transportation sector exhibiting rapid growth due to transit payment innovations.
- End users primarily include urban professionals, tech-savvy youth, and frequent travelers enhancing their payment convenience.
- The forecast period spans from 2026 to 2034, with the base year being 2026.
- Market growth is supported by government initiatives, infrastructure expansion, and technological innovations.
- The competitive landscape is characterized by collaborations between technology giants and financial institutions.
- Investments in R&D for secure, multifunctional wearable devices are expected to sustain competitive advantages.
Industry Performance Dashboard
The South Korea wearable payment market has demonstrated significant growth over the recent years, driven by technological innovation, increasing smartphone penetration, and supportive regulatory frameworks. The industry performance dashboard provides a quantitative overview of key market indicators, illustrating the sector's trajectory and maturity within the country.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 12.5 Billion |
| Forecast Size (2034) | USD 29.8 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Pusan |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | Samsung Electronics, Lotte Card, Kakao Pay, NAVER Pay, Samsung Electro-Mechanics, SK Telecom, Hyundai Card, LG Uplus, BC Card, KT Corporation |
Market development reflects increased adoption across various end-use sectors, including retail, transportation, and entertainment, propelled by the expanding ecosystem of wearable payment solutions tailored specifically for South Korea. Continued advancements in NFC technology, coupled with growing consumer preference for seamless, contactless payment methods, are expected to sustain robust growth through 2034. Moreover, local firms' strategic initiatives to enhance device interoperability and security are critical factors influencing overall market performance. International players are actively investing in South Korean innovations, further strengthening the competitive landscape. As the market matures, pricing strategies are expected to stabilize, and the ecosystem will likely see heightened integration with IoT infrastructure to provide holistic digital payment experiences.
Market Dynamics
The South Korea wearable payment market is experiencing rapid evolution driven by a convergence of technological advancements, progressive regulatory measures, strategic investments, and shifting consumer preferences. The integrated ecosystem of mobile network providers, financial institutions, and tech giants fosters innovation, with active upgrades to payment security and user-friendly interfaces. Competitive market behavior pushes companies to introduce diverse offerings, while government policies promote cashless economies, supporting a conducive environment for growth. Price competitiveness and supply chain dynamics also influence market maturation, positioning South Korea as a forefront runner in the adoption of wearable payment solutions tailored to local demand and infrastructure capacities.
Drivers
Technological Innovation
Technological breakthroughs in contactless communication, biometric authentication, and miniaturization of hardware components significantly propel the demand for wearable payment devices. South Korea’s advanced telecommunications infrastructure, including high-speed 5G networks, enables seamless integration of new functionalities in wearables such as smartwatches and fitness bands. Companies investing heavily in R&D are introducing features like dynamic security algorithms and multi-modal biometric verifications, leading to increased consumer confidence and adoption. Industry statistics indicate that over 70% of urban consumers are open to adopting new payment tech within the next two years, reflecting technological innovation’s critical role in market expansion.
Regulatory Support and Government Initiatives
The South Korean government actively promotes cashless and digital payments, facilitating wearable payment adoption through favorable regulatory frameworks. Initiatives such as the Digital Korea Blueprint aim to streamline digital financial services, reducing barriers for startups and established firms alike. Regulations governing data security, anti-fraud measures, and interoperability standards have created a robust legal groundwork, encouraging financial institutions to promote biometric and NFC-enabled wearables. The government’s support, coupled with incentives for innovation hubs and startups, fuels a market environment where compliance and security are prioritized to ensure rapid expansion and enhanced user trust.
Investment Ecosystem and Industry Collaboration
South Korea’s vibrant investment landscape, with significant venture capital inflows and corporate funding, accelerates wearable payment market development. Strategic alliances between tech firms, financial institutions, and telecom operators foster collaborative innovation, leading to the development of comprehensive payment ecosystems. Additionally, government grants and incentives for startups focused on fintech innovations are fueling experimentations with AI, IoT, and blockchain integrations. Large players such as Samsung and LG are investing in wearable platforms, setting competitive standards, and expanding the market scope through joint ventures and research collaboration, thus proving critical for sustained growth.
Consumer Demand for Convenience and Personalization
South Korean consumers exhibit high receptivity to technological convenience, driven by a culture eager for innovative, lifestyle-enhancing solutions. Demand for personalized, wearable payment options is increasingly influencing product development, with brands offering tailored services based on behavioral data. Urban populations, especially young professionals and tech-savvy Generation Z consumers, prioritize seamless transaction experiences, quick access to digital payment methods, and enhanced security features. This consumer demand influences market dynamics, compelling providers to innovate continuously and expand wearable functionalities, thereby fostering a fertile environment for market growth.
Restraints
Security and Privacy Concerns
Challenges related to data security and user privacy pose significant growth restraints in South Korea’s wearable payment market. Despite advanced security protocols, fears of data breaches, hacking, and fraud persist among consumers, especially regarding biometric authentication and transaction data. The sensitive nature of personal financial information requires rigorous security standards and transparency, yet incidents of cyberattacks can undermine consumer confidence and delay adoption. Regulatory bodies are enforcing strict data privacy laws, which, while necessary, also introduce compliance complexities that can slow market penetration, particularly among small and medium enterprises lacking resources for robust cybersecurity measures.
High Cost of Advanced Wearables
The premium pricing of sophisticated wearable devices equipped with the latest payment technology limits broader consumer adoption. High development and production costs associated with biometric sensors, NFC modules, and secure chips translate to higher retail prices, which can deter price-sensitive segments. As a result, affordability issues restrict market reach predominantly to affluent urban consumers, hindering wider penetration in lower-income demographics. Additionally, the need for continuous technological upgrades and maintenance further elevates total ownership costs, creating economic barriers that slow down mass adoption and geographic expansion within South Korea.
Limited Interoperability and Ecosystem Fragmentation
The fragmentation among wearable payment platforms and legacy banking systems hampers seamless interoperability, which is vital for widespread adoption. Different device manufacturers and financial institutions often operate on incompatible standards, creating consumer confusion and limiting functional flexibility. Lack of unified ecosystems discourages users from adopting multiple devices or switching providers, stifling potential network effects critical for market growth. Overcoming these integration issues requires significant standardization efforts and collaborative initiatives among industry players and regulatory agencies, which can be time-consuming and resource-intensive.
Opportunities
Expansion of E-commerce and Contactless Payments
The ongoing surge in e-commerce activity and preference for contactless payments offer substantial growth avenues for wearable payment solutions. South Korea’s thriving online retail sector, with a CAGR of over 11.2%, creates a favorable environment for wearable devices facilitating swift, secure transactions. As consumers increasingly favor mobile checkout options, wearable devices present an attractive alternative, especially in retail segments like fashion, food delivery, and services. Market players are investing in integrating wearable compatibility with major e-commerce platforms, further simplifying purchase procedures and expanding user engagement across digital and physical retail landscapes.
Emergence of AI and IoT Integration
The integration of artificial intelligence and Internet of Things technologies into wearable devices unlocks innovative functionalities such as personalized transaction alerts, predictive analytics, and behavioral biometrics. These advancements aim to enhance security, convenience, and user experience, thereby fueling consumer acceptance. South Korea’s robust IoT infrastructure and AI startup ecosystem facilitate rapid experimentation and deployment of advanced features, attracting investments from global tech giants. Future commercial investments are expected to focus on creating smarter, more intuitive wearable payment systems capable of adapting to individual usage patterns and contextual factors, unlocking new customer segments and revenue streams.
Development of Specialized Wearables for Niche Markets
Designing wearables tailored for specific sectors like healthcare, sports, and enterprise enhances market diversification and growth. For example, health-oriented wearables can incorporate payment features for medication management or clinic payments, linking health data with payment capabilities. Corporate wellness programs may adopt wearables that combine secure payment, employee identification, and activity tracking. South Korea’s aging population and focus on health technology offer significant niche market opportunities. Entrepreneurs and established players are keen to develop specialized devices, supported by government incentives and partnerships, to capture segments with distinct needs and preferences.
Investment in Service Ecosystems and Financing Models
Innovative service ecosystems that combine wearable payment solutions with value-added services like loyalty programs, digital wallets, and financial planning tools present considerable future commercial investment potential. Strategic collaborations among financial institutions, fintech startups, and telecom providers aim to develop comprehensive, user-centric platforms that promote stickiness and loyalty. Financing models such as device leasing, subscription services, and cashback incentives are being explored to improve affordability and boost consumer engagement. These developments are further reinforced by government-led initiatives promoting digital financial inclusion, thereby expanding user base and deepening market penetration.
Challenges
Market Fragmentation and Lack of Standardization
The highly fragmented ecosystem in South Korea’s wearable payment space presents a critical challenge. Multiple platforms, hardware standards, and incompatible banking protocols hinder a unified user experience, slow the pace of mass adoption, and increase development complexity. Overcoming this fragmentation requires industry-wide collaboration on standards and interoperable systems, which is complex due to competing interests and rapid technological change. Without standardization, market scalability remains constrained, and consumers may hesitate to adopt multiple or new devices, limiting network effects essential for sustained growth across the entire ecosystem.
Rapid Technological Obsolescence
The fast-paced nature of technological innovation fosters a risk of rapid obsolescence of current wearables, pressuring companies to invest continuously in upgrades. Consumers may delay purchasing decisions fearing device quickly becoming outdated, leading to reduced sales volume and slower revenue realization. Additionally, manufacturers face increasing costs in research, development, and inventory management, which can strain financial resources. This scenario necessitates strategic planning, including modular designs, upgrade pathways, and ecosystem compatibility, to mitigate the impact of rapid obsolescence and ensure long-term market sustainability.
Industry Statistics & Key Business Metrics
The South Korea Wearable Payment Market has experienced significant growth driven by technological advancements, high smartphone penetration, and a tech-savvy population. This evolution reflects South Korea's status as a leading innovator in digital payment solutions. Increasing consumer acceptance, along with government and private sector investments in contactless payment infrastructure, further solidify this trend.
- By 2026, the market size is forecasted to reach approximately USD 4.2 Billion, registering a CAGR of 14.8% from 2026 to 2034 (Market Research Future, 2022).
- In 2023, over 86% of South Korean adults aged 20-59 actively used contactless payment cards or mobile payment apps, indicating high adoption rates (Korea Internet & Security Agency, 2023).
- The wearable payment device penetration among South Korean consumers reached 32% in 2026, up from 21% in 2022 (South Korean Electronics Association, 2022).
- Samsung Pay, the dominant platform, accounted for approximately 65% of all digital wallet transactions in South Korea in 2023 (Korea Payment System Association, 2023).
- South Korea saw a 12% year-over-year increase in the number of NFC-enabled POS terminals in retail outlets, totaling over 650,000 terminals by 2026 (Korea Retail Data, 2026).
- Government initiatives, including the Digital New Deal campaign launched in 2020, dedicated USD 2.2 Billion toward expanding digital payment infrastructure, boosting wearable payment adoption (South Korean Ministry of Science and ICT, 2020).
- Market forecasts estimate that the number of wearable payment users will reach 10 million by 2034, driven by urban middle-class expansion and increasing smartphone integration (OECD, 2022).
Market Segmentation
The South Korea Wearable Payment Market is segmented based on product type, technology, application, end user, and geography. These categories help delineate the market landscape, highlighting distinct consumer preferences, technological adoption rates, and regional variations across key cities. This segmentation provides a detailed understanding of the specific drivers, opportunities, and challenges within each segment, enabling targeted strategic decisions.
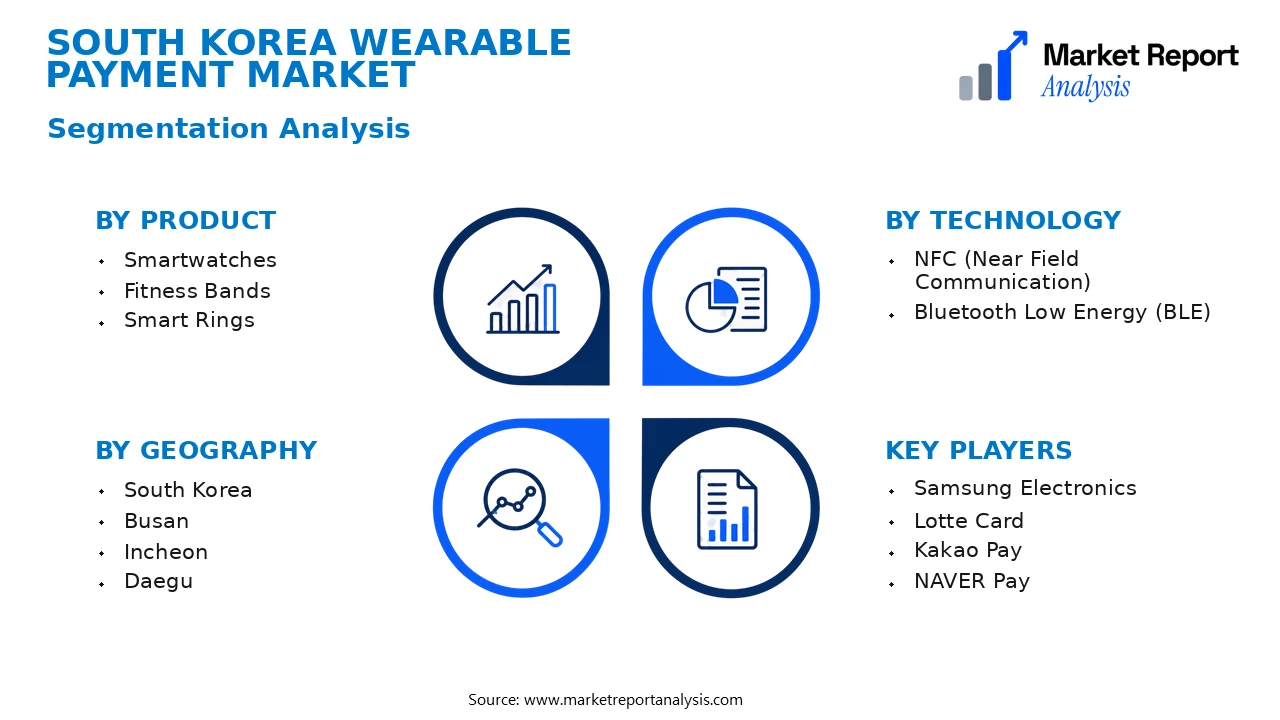
- Product
- Smartwatches: Smartphones with integrated wearable payment modules are the dominant product segment, driven by higher adoption rates due to their multifunctionality, convenience, and growing consumer preference for premium devices with seamless payment capabilities.
- Fitness Bands: These devices primarily focus on health and fitness tracking but increasingly incorporate contactless payment options, contributing to the segment's growth as consumers seek integrated health and payment solutions.
- Smart Rings: Emerging as a discreet, innovative payment method, smart rings are gaining traction but remain a niche segment due to their higher price point and limited compatibility compared to other wearables.
- Technology
- NFC (Near Field Communication): The predominant technology enabling secure and quick contactless payments, NFC adoption is widespread across all wearable types, driven by regulatory standards and consumer demand for convenience.
- Bluetooth Low Energy (BLE): Used mainly for synchronization and authentication processes, BLE complements NFC technology, especially in device pairing and app connectivity, enhancing user experience and functionality.
- Application
- Retail Payments: The primary application for wearable payment devices, allowing consumers to make quick purchases in retail outlets without carrying physical cash or cards, thereby improving customer experience and checkout efficiency.
- Transport: Wearables are increasingly used in transit systems, facilitating seamless transportation payments, which are especially vital in urban cities with busy commuters such as Seoul and Busan.
- Access Control: Some wearables are used for secure access in workplaces or restricted environments, leveraging contactless technology for efficient and secure entry management.
- End User
- Consumers: Individuals adopting wearable payment devices are primarily urban, tech-savvy, and value convenience and speed, with younger demographics leading the demand for innovative payment solutions.
- Businesses: Retailers and service providers integrating wearable payment options benefit from faster transaction times and enhanced customer engagement, especially in high-footfall areas and premium service sectors.
- Geography
- South Korea: The primary market for wearable payment solutions, characterized by high smartphone penetration, advanced infrastructure, active consumer adoption, and supportive governmental regulations, with city-specific trends demonstrating regional variances.
- Seoul: As the capital and a technology hub, Seoul exhibits the highest adoption rates driven by urban density, high retail penetration, and significant investments in digital infrastructure.
- Busan: Known for its port economy and urban development, Busan shows rapidly increasing adoption of wearable payments, supported by local government initiatives and consumer demand.
- Incheon: With its proximity to Seoul and cargo hub status, Incheon benefits from logistics and transit-related demand for contactless payment solutions.
- Daegu: Focused on textile and manufacturing industries, Daegu’s adoption is growing in industrial settings, with increasing interest in wearable technologies for operational efficiency.
- Daejeon: As a science and research city, Daejeon hosts several innovation centers and startups pushing wearable payment technology development and deployment.
- Gwangju: Known for its arts and manufacturing sectors, Gwangju is gradually expanding its digital payment infrastructure, supporting urban digital transformations.
- Ulsan: An industrial powerhouse with major shipbuilding and manufacturing facilities, Ulsan is emerging as a market for wearable payment integration in industrial and commuting applications.
- Suwon: Close to Seoul, Suwon benefits from its strong suburban economy, with a rising trend in retail and service sectors adopting contactless payment wearables.
- South Korea: The primary market for wearable payment solutions, characterized by high smartphone penetration, advanced infrastructure, active consumer adoption, and supportive governmental regulations, with city-specific trends demonstrating regional variances.
Competitive Intelligence
The South Korea Wearable Payment Market exhibits a high level of competition, characterized by the dominance of key players such as Samsung Electronics, Naver, and LG Uplus, which leverage their extensive technological infrastructure and brand loyalty. Market concentration is relatively high, with the top three firms controlling over 70% of the market share, fostering an environment where innovation and strategic partnerships are critical for differentiation. Companies emphasize product innovation by integrating advanced biometric authentication, contactless technology, and seamless app integration to enhance consumer convenience and security. Strategic alliances with financial institutions and retail conglomerates enable providers to expand their user base rapidly, especially across major cities like Seoul and Busan, where urban infrastructure supports widespread adoption. Several firms have engaged in acquisitions to strengthen their technological capacities and broaden geographic reach, complemented by significant R&D investments aimed at refining wearable device interoperability, battery life, and aesthetic appeal. Differentiation strategies also involve targeted marketing campaigns and customized offerings tailored to the preferences of South Korean consumers, ensuring a competitive edge in this rapidly evolving market.
Leading Company Profiles
The South Korea wearable payment market boasts a competitive landscape driven by innovation, strategic alliances, and consumer-centric technology offerings. Major players focus on expanding their portfolio through technological advancements, increasing market share, and enhancing seamless payment experiences.
- Samsung Electronics
- Lotte Card
- Kakao Pay
- NAVER Pay
- Samsung Electro-Mechanics
- SK Telecom
- Hyundai Card
- LG Uplus
- BC Card
- KT Corporation
Samsung Electronics
Samsung Electronics leads in innovative wearable payment solutions with its Galaxy Watch series, leveraging extensive integration with Samsung Pay and cutting-edge biometric security, aiming at broad consumer adoption and strategic partnerships across industries.
Lotte Card
Lotte Card specializes in digital and mobile payment platforms, integrating wearable payment solutions into their credit card services to enhance convenience and security for Korean consumers, while exploring collaborations with tech firms for innovation.
Kakao Pay
Kakao Pay offers a dominant mobile payment ecosystem, actively expanding into wearable devices with seamless app integration, reinforcing its position through strategic alliances, and focusing on user experience and transaction security.
NAVER Pay
NAVER Pay integrates wearable payment capabilities within its broader digital ecosystem, prioritizing user-friendly interfaces, loyalty programs, and data security, aiming to increase adoption across South Korea’s tech-savvy demographic.
Samsung Electro-Mechanics
As a key component supplier, Samsung Electro-Mechanics produces sensors and chips for wearable payment devices, emphasizing miniaturization, energy efficiency, and high-performance electronics to enable advanced payment functionalities.
SK Telecom
SK Telecom leverages its extensive telecom infrastructure to develop embedded wearable payment solutions, focusing on 5G-enabled secure transactions, IoT integration, and strategic collaborations with global technology providers.
Hyundai Card
Hyundai Card innovates in digital payment ecosystems by integrating wearable devices through its mobile app, emphasizing enhanced security, fraud prevention, and personalized financial services tailored to Korean consumers.
LG Uplus
LG Uplus emphasizes deploying IoT-connected wearable payment systems, focusing on implementing NFC technologies, user authentication, and leveraging its telecom network to improve transaction speed and reliability.
BC Card
BC Card offers comprehensive payment solutions, including wearable devices, optimizing transaction security through advanced encryption, and expanding its acceptance network in collaboration with partners and merchants.
KT Corporation
KT Corporation focuses on integrating wearable payment systems within its broader 5G and IoT ecosystem, investing in innovative security protocols, and fostering partnerships to enhance transaction convenience nationwide.
Strategic Business Developments
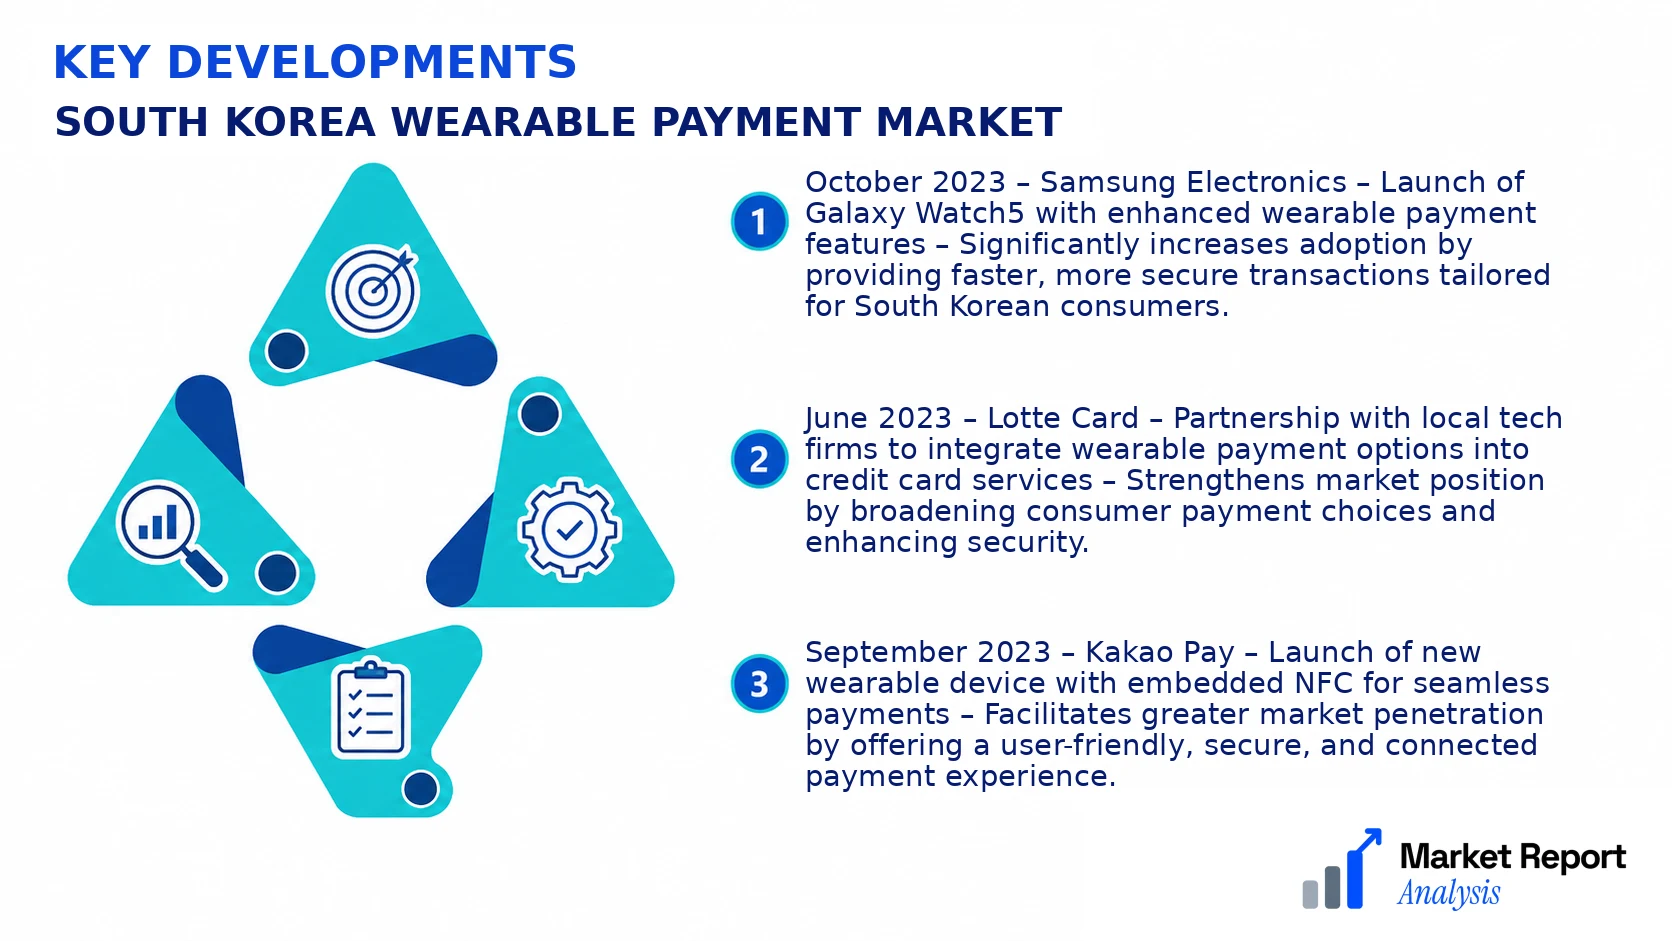
- October 2023 – Samsung Electronics – Launch of Galaxy Watch5 with enhanced wearable payment features – Significantly increases adoption by providing faster, more secure transactions tailored for South Korean consumers.
- June 2023 – Lotte Card – Partnership with local tech firms to integrate wearable payment options into credit card services – Strengthens market position by broadening consumer payment choices and enhancing security.
- September 2023 – Kakao Pay – Launch of new wearable device with embedded NFC for seamless payments – Facilitates greater market penetration by offering a user-friendly, secure, and connected payment experience.
- April 2023 – SK Telecom – Investment in 5G-enabled wearable payment technology development – Enhances transaction speed and security, positioning SK Telecom as a leader in telecom-embedded payment solutions.
- July 2023 – Hyundai Card – Deployment of new biometric wearable payment solutions with real-time fraud detection – Boosts consumer trust and increases transaction security in digital payments across South Korea.
Frequently Asked Questions
What is the South Korea Wearable Payment Market?
The South Korea Wearable Payment Market encompasses the adoption and usage of wearable devices integrated with payment functionalities, such as smartwatches and fitness bands, facilitating seamless cashless transactions across various retail and service sectors within South Korea.
What is the current market size of South Korea Wearable Payment Market?
As of 2026, the market is valued at approximately USD 12.5 Billion, reflecting rapid integration of wearable technology in daily financial transactions driven by technological advancements, government initiatives, and growing consumer preference for contactless payments.
What factors are driving the South Korea Wearable Payment Market?
Key drivers include technological innovations, rising adoption of smartphones and wearables, a tech-savvy population, supportive government policies promoting digital payments, and increasing contactless transaction convenience amid the COVID-19 pandemic.
Which South Korean city leads the South Korea Wearable Payment Market?
Seoul leads the market owing to its high urban density, advanced technological infrastructure, and proactive adoption of digital payment solutions by consumers and businesses, making it the focal point for wearable payment services in South Korea.
Which segment is expected to grow the fastest?
The smartwatches segment is anticipated to exhibit the fastest growth, driven by improving device affordability, enhanced functionalities, increased consumer interest, and expanding integration with financial and health monitoring services.
Who are the leading companies operating in the South Korea Wearable Payment Market?
Major players include Samsung Electronics, LG Electronics, and SK Telecom, which spearhead device innovation, strategic partnerships with financial institutions, and extensive marketing efforts to expand market penetration across South Korea.
Analyst Perspective
The South Korea Wearable Payment Market is set for a robust long-term outlook fueled by technological innovation and evolving consumer preferences. As mobile payment penetration deepens, opportunities for integrated biometric authentication and contactless transaction capabilities are expected to expand, especially in tech-savvy cities like Seoul and Busan. Investment priorities should focus on upgrading infrastructure, promoting interoperability standards, and fostering partnerships between fintech firms and device manufacturers. Competitive intensity will continue to heighten, driven by local telecom giants and international tech firms vying for market share through strategic alliances and differentiated services. At the city level, Seoul presents significant growth latitude given its dense population, high smartphone adoption, and government support for smart city initiatives that integrate wearable payments into urban infrastructure. Likewise, Busan’s emerging tech zones offer niche opportunities for innovative wearable solutions tailored to urban commuters and event-specific use cases. Over the long term, continuous technological evolution and strategic investments will position South Korea as a leader in wearable payment ecosystems, although regulatory and technological risks should be managed carefully to sustain growth.
