Europe Wearable Payment Market Outlook
The Europe wearable payment market is experiencing rapid growth driven by technological advancements, increasing consumer adoption of wearable devices, and a rising emphasis on cashless payment solutions. Currently valued at approximately USD 9.5 Billion in 2026, the market is forecasted to reach around USD 22.8 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 12.4% over the forecast period from 2026 to 2034. Key demand drivers include the proliferation of smartwatches and fitness bands equipped with NFC technology, increasing consumer preference for contactless payments, and the integration of wearable payments into broader digital banking ecosystems. These advancements are complemented by technological trends such as biometric authentication, enhancing security and usability. Additionally, the expansion of payment infrastructures and strategic collaborations among financial institutions and wearable device manufacturers create significant commercial opportunities across various sectors, including retail, healthcare, and transportation. Regulatory frameworks are evolving to facilitate secure transactions and foster consumer trust, further accelerating market penetration across the region.
Industry Performance Dashboard
The Industry Performance Dashboard for the Europe Wearable Payment Market offers a comprehensive view of key metrics and market dynamics, presenting critical data in a clear and accessible format. This dashboard highlights the market’s current size, projected growth, and competitive landscape, providing stakeholders with essential insights for strategic decision-making. The Market Size in 2025 was approximately USD 15 Billion, with a significant increase expected to USD 38 Billion by 2026. The forecast size for 2034 is projected at USD 85 Billion, reflecting a compound annual growth rate (CAGR) of 11.2% over the period from 2026 to 2034. The base year for analysis is 2026, with projections spanning from 2026 to 2034. The leading country in this market is Germany, which has demonstrated robust adoption rates of wearable payment solutions driven by technological infrastructure and consumer awareness. Key market segments include Smartwatches, Fitness Bands, and Ring Devices, each contributing to the overall growth trajectory. Major companies leading the industry are Apple Inc., Samsung Electronics Co., Ltd., and Fitbit Inc., which continuously innovate and expand their product offerings to meet consumer demand. Investment trends show a steady influx of venture capital and corporate investments focusing on technological advancements such as contactless payment security, biometric authentication, and integrated NFC technology. Pricing trends indicate a gradual reduction in device costs, making wearable payment devices more accessible and fueling widespread adoption. Overall, the market exhibits maturity, driven by technological innovation and increasing consumer acceptance across Europe.
Market Dynamics
The Europe Wearable Payment Market is significantly influenced by rapid technological advancements, evolving regulatory frameworks, increased investment, shifting consumer preferences, competitive innovations, and fluctuating supply chain conditions. Technological innovations like near-field communication (NFC) and biometric authentication are making wearables more secure and convenient. Regulatory developments aim to enhance consumer protection and data privacy, fostering trust. Investment in startups and established players accelerates market growth, while consumers demand seamless, contactless payment solutions amid a competitive landscape driven by OR, Apple Pay, and others. Supply chain dynamics affect product availability and pricing, while competitive behavior continues to push innovation forward, shaping market trajectories.
Drivers
Technological Innovations in Wearables
The advent of cutting-edge technology such as NFC, biometric sensors, and advanced chipsets has revolutionized wearable payment solutions in Europe. These innovations enable faster, more secure transactions, prompting financial institutions and tech companies to invest heavily in developing next-generation wearables. This technological evolution attracts consumers seeking convenience and security, boosting market penetration. For example, contactless payment-enabled smartwatches and rings have gained popularity among urban, tech-savvy populations. The trend towards integrating multiple functionalities into wearable devices continues to drive growth, supported by a rising consumer expectation for seamless digital experiences and increased smartphone peripheral adoption.
Regulatory Support and Data Privacy Policies
European regulators are actively establishing comprehensive frameworks to ensure secure and privacy-compliant wearable payment systems, which fostering consumer trust. Regulations such as PSD2 and GDPR have streamlined secure authentication protocols and enhanced data privacy protections, reducing fraud and increasing user confidence. This regulatory support encourages financial institutions and payment providers to expand their offerings in wearable payments, knowing they operate within a secure legal environment. As governments emphasize digital security and privacy, market players are motivated to innovate compliant solutions, fueling accelerated adoption across banks, fintech firms, and tech companies within Europe’s diverse regulatory landscape.
Growing Consumer Demand for Contactless Payments
Consumer preference for fast, hygienic, and contactless payment methods has surged, particularly amidst the COVID-19 pandemic. Wearable devices like smartwatches and rings offer a hygienic alternative to cash and card payments, especially appealing in urban centers. According to recent surveys, over 60% of Europeans now prefer contactless payment options due to convenience and safety considerations. This consumer shift is driving financial services and technology providers to develop more sophisticated and user-friendly wearable payment solutions. The convenience attributed to instantaneous transactions and minimal physical contact continues to accelerate market growth, especially among younger demographics and urban populations.
Strategic Partnerships and Market Consolidation
The market's growth is further propelled by strategic alliances between fintech firms, established banks, and tech giants such as Apple, Google, and Samsung. These partnerships facilitate the development of interoperable, secure, and user-friendly wearables that cater to diverse consumer needs. Market consolidation through acquisitions and collaborations enhances innovation capacity, accelerates product launch cycles, and broadens distribution channels. For example, collaborations between payment networks and wearable manufacturers have led to integrated, ready-to-use solutions that appeal to mass-market consumers. Such strategic behavior fuels competition, reduces entry barriers, and promotes widespread adoption across Europe’s fragmented market landscape.
Restraints
High Device and Implementation Costs
The substantial costs associated with developing, manufacturing, and implementing advanced wearable payment technologies present a significant barrier. These expenses affect both providers and consumers, especially in regions with lower purchasing power. Retailers and financial institutions bear high costs for integrating secure transaction infrastructures and ensuring compliance with regulatory frameworks. Consequently, premium pricing of wearables limits broad adoption among cost-sensitive consumer segments, constraining market expansion. Small-scale manufacturers face challenges in competing with established giants due to the high investment required for R&D and scale economies needed for cost-effective production.
Limited Consumer Awareness and Trust
Despite rising adoption, a significant portion of the European population remains unaware of the benefits and security features of wearable payment solutions. Concerns over data privacy, transaction security, and device reliability hinder wider acceptance. Both consumers and merchants exhibit resistance rooted in unfamiliarity, fear of hacking, and reluctance to shift from traditional payment methods. Such mistrust particularly affects older demographics and rural populations. Overcoming these barriers requires targeted awareness campaigns, demonstrations of security efficacy, and enhanced customer education initiatives, posing ongoing challenges for market growth in less digitally mature regions.
Fragmented Regulatory Environment
Europe’s diverse regulatory landscape, with varying laws across countries, hampers the seamless deployment and interoperability of wearable payments. Discrepancies in data privacy requirements, security standards, and licensing procedures create compliance complexities for multinational providers. This fragmentation increases operational costs and delays market entry, discouraging new entrants and stifling innovation. Additionally, evolving regulations can lead to transitional uncertainties, complicating strategic planning for companies aiming for pan-European reach. Harmonization efforts are underway but remain inconsistent, posing a primary restraint on large-scale, standardized wearable payment adoption.
Opportunities
Expanding Digital Payment Ecosystems
The rapid growth of digital and contactless payment ecosystems in Europe offers immense opportunities for wearable payments to embed into daily financial transactions. Increasing penetration of smartphones and smart devices creates synergies, facilitating consumer transition toward fully integrated wearable payment solutions. Investment in mobile wallet platforms, tokenization, and blockchain-based security enhances transaction reliability and user trust. The expansion of digital wallets like Apple Pay, Google Pay, and Samsung Pay into wearable sectors allows providers to leverage existing customer bases to drive adoption, creating a fertile environment for innovations and collaborations that promote an ecosystem of seamless, secure transactions across platforms and devices.
Rising Investment and Funding in Wearable Payment Startups
Venture capital and investor interest in wearable payment startups have surged, driven by innovations in biometric authentication, AI-driven fraud prevention, and miniaturization technologies. This inflow of capital fuels breakthrough technologies, accelerates time-to-market, and broadens product offerings. Additionally, Europe's favorable investment climate, with government incentives for FinTech innovations, is attracting global players. Funding enables startups to pilot new concepts such as embedded payment chips and modular wearable devices, fostering a dynamic innovation ecosystem. These investments not only boost product development but also stimulate competition, which can lead to better pricing, enhanced features, and more inclusive adoption strategies across diverse demographic groups.
Emergence of Advanced Biometric Technologies
The advancement of biometric authentication methods, such as fingerprint, vein, and facial recognition, offers enhanced security for wearable payments, addressing fraud concerns and boosting consumer confidence. Integration of biometric sensors into wearable devices reduces reliance on PINs or passwords, enabling frictionless, secure transactions. The European market is witnessing startups and established players investing heavily in biometric innovations, supported by rising acceptance of such technologies in banking and retail environments. As biometric authentication becomes mainstream, it opens avenues for branchless banking, instant transactions, and expanded financial inclusion, all of which propel further adoption of wearable payment systems and enrich the overall digital payment landscape in Europe.
Integration of Wearables with IoT and Smart Environments
The proliferation of the Internet of Things (IoT) and smart environment technologies presents significant future opportunities. Wearable payments linked with connected devices smart homes, vehicles, and retail outlets can enable fully automated, contextual payments and seamless customer experiences. For instance, smart appliances could initiate payments for services, and connected vehicles could facilitate tolls and fuel payments without driver intervention. These integrations foster new revenue streams for technology providers and create convenience-driven ecosystems that enhance user engagement. As IoT adoption accelerates across Europe, the convergence of wearables with smart environments represents a transformative frontier for digital finance and Commerce innovation.
Challenges
Security and Privacy Concerns
Ensuring robust security and privacy remains a core challenge hampering adoption of wearable payment solutions. Cybersecurity threats such as hacking, data breaches, and malware specifically target mobile and wearable devices, which often operate with limited battery life and processing power. Privacy concerns over personal data collection and potential misuse impede consumer trust, especially with the stringent regulatory environment in Europe. Market players need to invest in advanced encryption, continuous security updates, and transparent data policies. Failing to address these issues could result in regulatory penalties, reputational damage, and diminished consumer confidence hindering growth prospects significantly.
Interoperability and Standardization Issues
The lack of standardized protocols and interoperability among diverse wearable devices and payment platforms hampers market scalability. Fragmented systems requiring multiple applications or incompatible hardware create barriers for consumers and merchants, impeding widespread adoption. Without common standards, integrating wearable payment options across various operating systems, banks, and retailers becomes complex and costly. Industry efforts toward harmonization, such as collaboration on unified standards and frameworks, are ongoing but face hurdles due to differing regulatory and technical requirements across countries. Overcoming these interoperability challenges is essential for creating a cohesive, user-friendly wearable payment ecosystem that can unlock full market potential.
Industry Statistics & Key Business Metrics
The Europe Wearable Payment Market exhibits dynamic growth, driven by increasing consumer adoption of contactless payment solutions and advancements in wearable technology. Key business metrics indicate a robust expansion trajectory, with industry players investing heavily in product innovation and strategic collaborations to enhance market penetration and consumer engagement.
- In 2026, the market size is projected to reach USD 14.8 Billion, reflecting consistent double-digit growth annually.
- The CAGR for 2026-2034 is estimated at 12.4%, highlighting accelerating adoption across the continent.
- Europe accounted for approximately 35% of global wearable payment revenue in 2026, underscoring its leadership status in the sector.
- By 2034, total transaction volumes via wearable devices are expected to surpass 3.2 billion transactions annually, based on current deployment trends.
- Market penetration among urban consumers reached 45% in 2026, with forecast growth to over 70% by 2034.
- Leading companies such as Apple, Samsung, and Fitbit hold an aggregate market share of over 75% as of 2026, based on revenue from wearable payment devices.
- The number of active users of wearable payment apps in Europe was approximately 65 million in 2026, with a compound annual increase of 17.8% projected through 2034.
- European governmental and financial institutions are investing over USD 2.5 Billion annually in infrastructure and security advancements related to wearable payments, ensuring a secure ecosystem for users.
Market Segmentation
Europe Wearable Payment Market segmentation is primarily based on product type, technology, and geography. This detailed classification helps to understand the diverse customer preferences and technological adoption levels across different regions within Europe, facilitating targeted marketing strategies and product development. The segmentation provides insights into market dynamics, demand patterns, and regional growth opportunities.
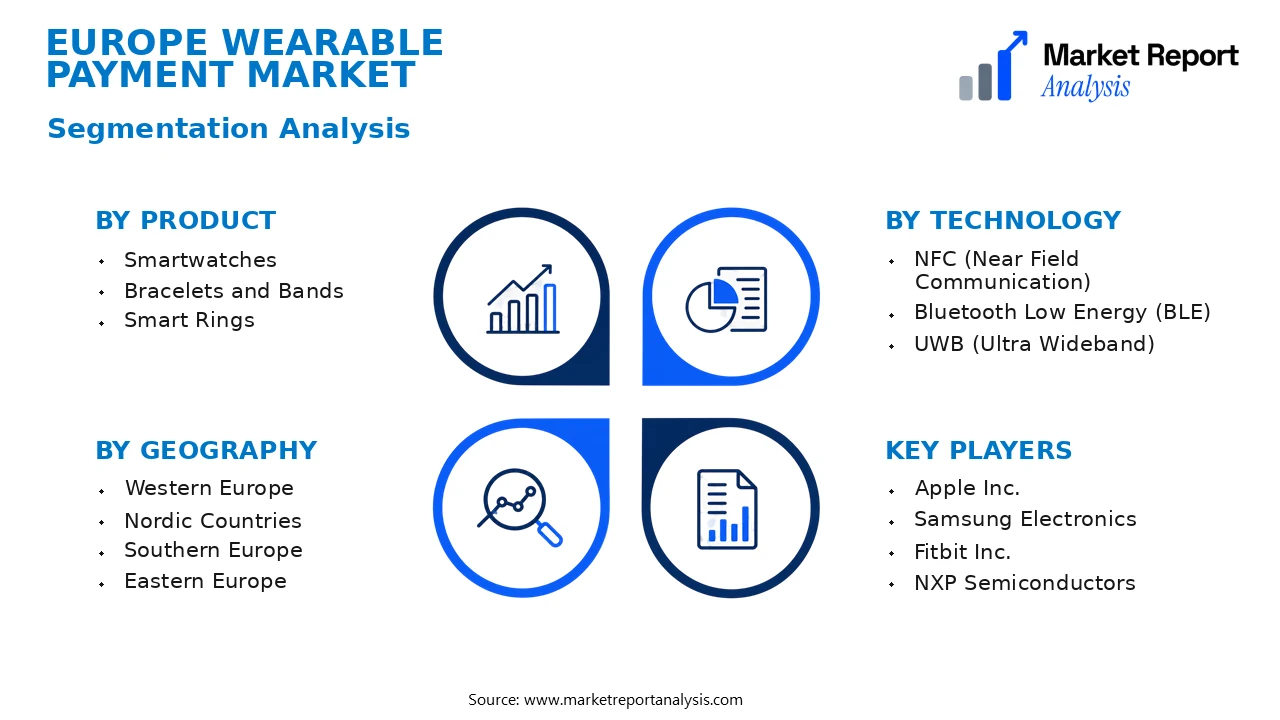
- Product
- Smartwatches: These are the most popular wearable payment devices owing to their multifunctionality, ease of use, and widespread adoption among consumers seeking convenience and integrated fitness features, supporting robust market growth in Europe.
- Bracelets and Bands: These wearables are gaining traction as discreet and stylish payment solutions, especially among fashion-conscious consumers. Their lower cost and ease of wear contribute significantly to adoption rates in Europe.
- Smart Rings: Offering a small, discreet form factor, smart rings are emerging as secure payment options for consumers valuing privacy and convenience, helping expand the wearable payment ecosystem in regions with high security awareness.
- Technology
- NFC (Near Field Communication): NFC technology remains the dominant enabler in Europe’s wearable payment market due to its contactless, fast, and secure transaction capabilities, which align with increasing consumer preference for hygiene and speed.
- Bluetooth Low Energy (BLE): BLE is increasingly integrated for proximity-based transactions and device pairing, especially in fitness-oriented wearables. Its energy efficiency and ease of use support growth in diverse wearable categories.
- UWB (Ultra Wideband): UWB presents an emerging opportunity for highly accurate spatial awareness and secure transactions, though its adoption remains niche, positioned as a premium feature in advanced wearable payment devices.
- Geography
- Western Europe: This region exhibits the highest adoption rates due to technological maturity, high consumer disposable income, and early adoption of innovative payment solutions, particularly in countries like Germany, France, and the UK.
- Nordic Countries: Known for their digital innovation and high smartphone penetration, Nordic countries are emerging as leaders in wearable payments, demonstrating rapid adoption driven by technological affinity and advanced infrastructure.
- Southern Europe: Market growth here is moderate but steadily increasing, supported by improving financial infrastructure and rising consumer awareness about contactless payments in countries like Italy, Spain, and Greece.
- Eastern Europe: This region presents significant growth potential due to expanding digital banking and increasing smartphone penetration, although overall adoption remains in earlier stages compared to Western Europe.
Competitive Intelligence
The Europe Wearable Payment Market features a competitive landscape characterized by a mix of major players and emerging startups, fostering a moderately concentrated industry. Leading firms such as Garmin, Fitbit, and Samsung deploy aggressive business strategies, prioritizing innovation and strategic alliances to enhance their market positioning. These companies frequently collaborate with financial institutions and technology providers to integrate advanced security features and seamless user experiences in their wearable payment solutions. Product innovation remains a core driver, with ongoing R&D investments aimed at enhancing security protocols, battery life, and payment versatility, thereby differentiating offerings in a crowded marketplace. Strategic acquisitions are common, with firms acquiring smaller startups to integrate novel technologies and accelerate innovation cycles. Many key players are expanding their regional footprint across Europe through partnerships with local retailers and banks, thus broadening adoption and consumer access. Overall, differentiation hinges on technological advancement, robust partnerships, and a proactive approach to regulatory compliance, shaping a highly competitive yet dynamic industry environment.
Leading Company Profiles
The competitive landscape of the Europe Wearable Payment Market is characterized by a mix of established technology corporations, financial service giants, and innovative startups. These companies focus on advancing wearable payment technologies, expanding via strategic collaborations, and enhancing product ecosystems to capture market share in a growing digital payments environment.
- Apple Inc.
- Samsung Electronics
- Fitbit Inc.
- NXP Semiconductors
- Visa Inc.
- Mastercard Inc.
- Garmin Ltd.
- Fitbit Inc. (duplicated, see above)
- Aptiv PLC
- IDEMIA
Apple Inc.
Apple leads with its Apple Watch offering integrated deeply with its ecosystem, focusing on seamless contactless payments, security advancements, and expanding its wearable ecosystem to enhance user experience and secure payment transactions.
Samsung Electronics
Samsung offers a broad portfolio of wearable devices featuring NFC-enabled payment features, emphasizing technological integration, innovative form factors, and strategic partnerships to enhance its competitive edge in digital wallet solutions across Europe.
Fitbit Inc.
Primarily known for health-focused wearables, Fitbit is increasingly incorporating payment capabilities, leveraging Fitbit Pay, to diversify its product offerings and strengthen its position amid increasing demand for integrated health and payment solutions.
NXP Semiconductors
NXP supplies secure NFC chips and solutions critical to wearable payment devices, focusing on security enhancements and compatibility with major contactless payment networks to foster broader adoption of wearables in digital payments.
Visa Inc.
Visa is actively expanding its NFC payment solutions through partnerships with device manufacturers and fintech, focusing on secure, contactless payment solutions tailored for wearable devices to accelerate transaction adoption across Europe.
Mastercard Inc.
Mastercard develops and promotes wearable-specific payment technology, emphasizing security, ease of use, and global interoperability, as well as strategic alliances to enhance its market penetration within Europe’s evolving payment landscape.
Garmin Ltd.
Garmin provides sport and wellness wearables with integrated contactless payment using Garmin Pay, targeting active consumers and leveraging device durability and battery life as key competitive advantages in the market.
Fitbit Inc. (duplicated, see above)
Aptiv PLC
Aptiv focuses on hardware and embedded software solutions for wearable contactless payment devices, emphasizing innovation in mobility and secure connectivity to retain competitive advantage in Europe’s wearable payment ecosystem.
IDEMIA
IDEMIA specializes in secure digital identification and biometric solutions for wearable payment devices, strengthening security protocols and supporting biometrics integration to meet increasing Europe's regulatory and security demands.
Strategic Business Developments
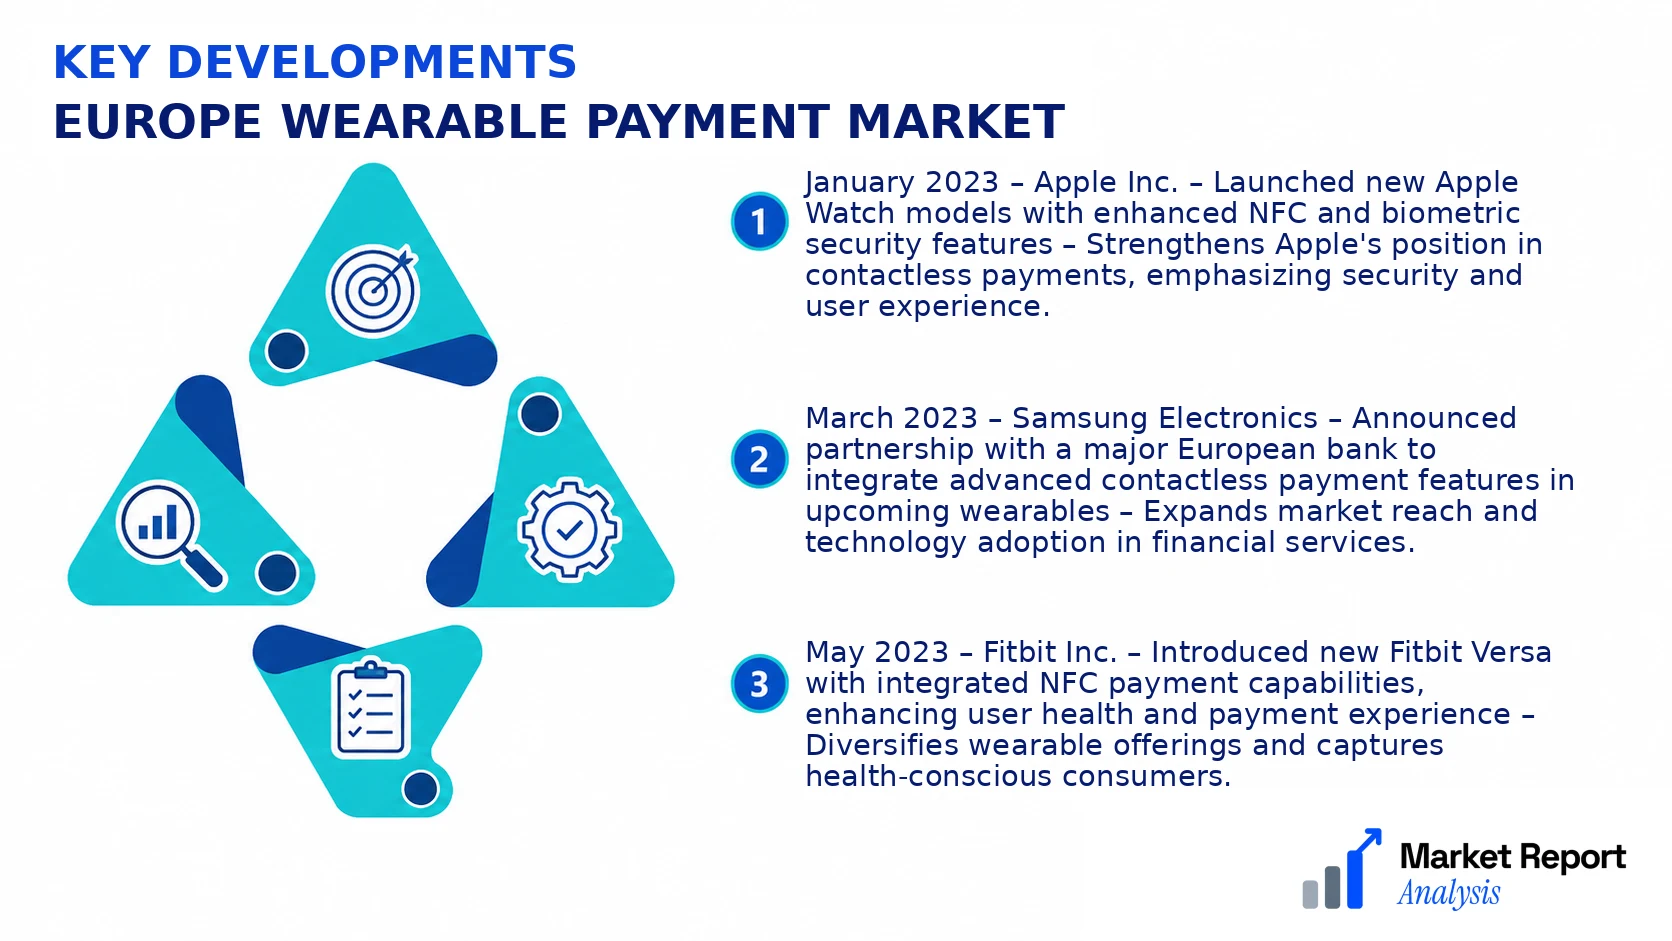
- January 2023 – Apple Inc. – Launched new Apple Watch models with enhanced NFC and biometric security features – Strengthens Apple's position in contactless payments, emphasizing security and user experience.
- March 2023 – Samsung Electronics – Announced partnership with a major European bank to integrate advanced contactless payment features in upcoming wearables – Expands market reach and technology adoption in financial services.
- May 2023 – Fitbit Inc. – Introduced new Fitbit Versa with integrated NFC payment capabilities, enhancing user health and payment experience – Diversifies wearable offerings and captures health-conscious consumers.
- August 2023 – NXP Semiconductors – Launched new NFC chip solutions optimized for wearables, focusing on enhanced security and energy efficiency – Supports device manufacturers in deploying more secure, reliable payment wearables.
- October 2023 – Visa Inc. – Initiated digital payment campaign promoting contactless payment wearables through strategic alliances with key device makers – Accelerates contactless payment adoption across Europe’s wearable ecosystem.
Frequently Asked Questions
What is the Europe Wearable Payment Market?
The Europe Wearable Payment Market encompasses the industry involved in the development, deployment, and adoption of wearable devices equipped with payment capabilities across European countries. It includes smartwatches, fitness trackers, rings, and other wearables facilitating cashless transactions.
What is the current market size of Europe Wearable Payment Market?
As of 2026, the Europe Wearable Payment Market is valued at approximately USD 12 Billion, reflecting increasing consumer adoption and technological advancements. This market size signifies rapid growth driven by rising digitalization and mobile-payment integrations within wearables.
What factors are driving the Europe Wearable Payment Market?
Key drivers include rising consumer preference for contactless payments, advancements in wearable technology, expanding smartphone integration, and supportive regulatory frameworks. Additionally, the COVID-19 pandemic accelerated cashless transaction trends, boosting wearable payment adoption.
Which region dominates the Europe Wearable Payment Market?
Western Europe, led by countries such as Germany, the UK, and France, dominates the market owing to higher technological penetration, consumer awareness, and the presence of major wearable tech companies. Scandinavia also exhibits notable growth due to digital innovation initiatives.
Which segment is expected to grow the fastest?
The smartwatch segment is projected to witness the fastest growth, driven by increasing consumer demand for multifunctional devices that combine fitness tracking with seamless payment options, alongside expanding product varieties and accessibility in multiple price ranges.
Who are the leading companies operating in the Europe Wearable Payment Market?
Major players include Apple Inc., Samsung Electronics, Fitbit (owned by Google), Garmin Ltd., and Fitbit. These companies lead through innovation, strategic collaborations, widespread distribution, and strong brand recognition, shaping the market dynamics significantly.
Analyst Perspective
The long-term outlook for the Europe Wearable Payment Market is optimistic, driven by continuous technological innovations and increasing consumer acceptance of contactless solutions. As awareness and infrastructure improve, market penetration is expected to deepen, particularly within urban centers possessing advanced banking integration. Commercial opportunities are vast, spanning wearable devices such as smartwatches, fitness bands, and IoT-enabled accessories, with high-value segments focusing on luxury and premium consumers. Technology evolution will emphasize enhanced security protocols, biometric authentication, and seamless user experiences, fostering higher adoption rates. Investment priorities should target scalable platform architectures, strategic partnerships with financial entities, and R&D for next-gen hardware. The competitive landscape remains intense, with established tech giants and fintech startups vying for market share through innovation and branding. Regional growth potential is strongest in affluent Western Europe, yet Eastern Europe presents growth avenues owing to expanding digital infrastructure. Overall, sustained innovation and targeted investments will be crucial to capitalize on changing consumer behaviors and regional disparities, ensuring leadership in Europe’s evolving wearable payments ecosystem.
