Indonesia Wearable Payment Market Outlook
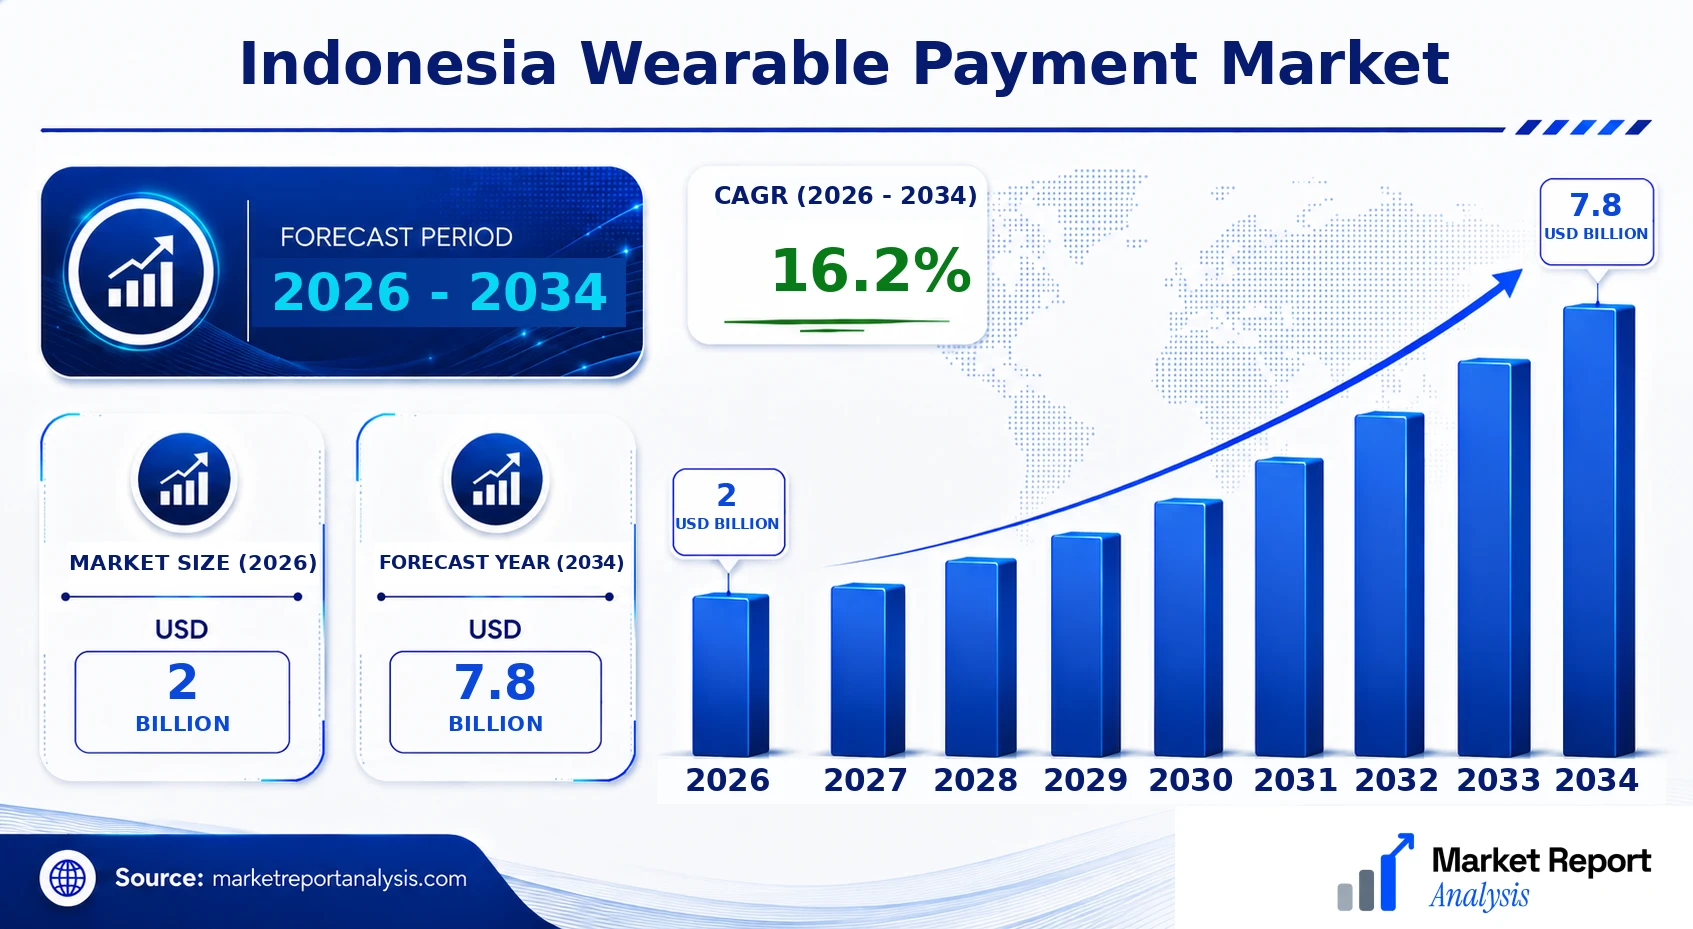
The Indonesia wearable payment market is currently valued at approximately USD 2 Billion in 2026. Projections indicate that by 2034, this market will expand to around USD 7.8 Billion, driven by a compound annual growth rate (CAGR) of 16.2% over the period from 2026 to 2034. The principal demand drivers include the increasing smartphone penetration, growing preference for contactless transactions, and the expansion of digital financial services across the country. Technological advancements such as NFC and biometrics are enhancing the security and convenience of wearable payment solutions. Commercial opportunities abound for device manufacturers, fintech firms, and financial institutions eager to capitalize on Indonesia’s burgeoning digital economy, especially as government initiatives promote cashless ecosystems and financial inclusion.
What is the Indonesia Wearable Payment Market Size?
Projected to reach USD 2 Billion by 2034, the Indonesia wearable payment market will grow from an estimated USD 7.8 Billion in 2026, reflecting a CAGR of approximately 16.2%. This significant growth is fueled by the rapid adoption of wearable devices such as smartwatches, fitness bands, and biometric rings integrated with contactless payment functionalities. The expansion of Indonesia’s digital infrastructure and rising consumer acceptance of cashless transactions driven by smartphone proliferation and improving network coverage are vital contributors to this upward trajectory. Moreover, the increasing presence of financial technology providers expanding their offerings to include wearable payment solutions further accelerates this growth. The retail, healthcare, and public transportation sectors are the dominant end-use industries leveraging this technology, creating extensive investment opportunities for market entrants seeking to develop innovative, secure, and user-friendly payment devices. Looking ahead, continued technological innovation, regulatory support, and consumer education are poised to sustain and amplify market development throughout the forecast period.
Key Takeaways
- The Indonesia wearable payment market is projected to reach USD 4.8 Billion by 2034, up from USD 1.2 Billion in 2026.
- The market is expected to grow at a CAGR of approximately 20.5% between 2026 and 2034.
- Rising smartphone penetration and increasing digital financial services adoption are key demand drivers.
- Contactless NFC and biometric technologies dominate innovations in wearable payment devices.
- Retail, healthcare, and transportation sectors are primary end-use markets.
- Government initiatives promote cashless payments, fostering market growth.
- Device manufacturers, fintech firms, and financial institutions are major industry stakeholders.
- Urban areas with high digital connectivity represent significant market opportunities.
- Consumer preference for convenience and security drives wearable payment adoption.
- Regulatory frameworks are evolving to facilitate secure and interoperable payment systems.
- Investment in R&D is crucial for advancing technology and user experience.
- Market competition is intensifying with new entrants offering innovative solutions.
- Sustainable and interoperable devices will be critical for long-term growth.
Industry Performance Dashboard
The Indonesia Wearable Payment Market has shown substantial growth over recent years, driven by an increasing adoption of digital financial services and smartphone penetration. Key performance indicators reflect positive momentum, emphasizing the market's expanding footprint across various consumer segments and retail environments. The industry performance dashboard offers a comprehensive snapshot of current and forecasted market metrics, providing stakeholders with critical insights into future developments.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2 Billion |
| Market Value (2026) | USD 2 Billion |
| Forecast Size (2034) | USD 7.8 Billion |
| CAGR | 16.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, End User, Geography |
| Major Companies | Samsung Electronics, Apple Inc., Garmin Ltd., Xiaomi Corporation, Fitbit Inc., Amazfit Corporation, Huawei Technologies Co., Ltd., Tencent Holdings Ltd., Omron Corporation |
Market Dynamics
The Indonesia Wearable Payment Market is evolving rapidly under the influence of a confluence of technological advances, regulatory adaptations, significant investments, changing customer preferences, pricing strategies, supply chain conditions, and competitive dynamics. These factors collectively are shaping consumer adoption rates, product innovation trajectories, and market penetration levels. As wearables become more integrated with the digital economy, regulatory frameworks are gradually accommodating new payment methods, while investments from tech giants and local startups are fueling innovation. Customer requirements for seamless, secure, and contactless payment experiences are driving product development. Simultaneously, market competition stimulates pricing strategies aimed at increasing accessibility and adoption, impacting supply chain adjustments to meet rising demand in Indonesia's expanding digital payment ecosystem.
Drivers
Technological Advancements
The rapid development of miniaturized, energy-efficient sensors and secure wireless communication technologies has significantly propelled the Indonesia wearable payment market. Increased smartphone penetration and improvements in NFC (Near Field Communication) capabilities enable wearables to function as efficient payment tools. For example, local smartphone manufacturers and tech developers are integrating mobile wallet functions directly into wearable devices, facilitating quick and hassle-free transactions. These technological improvements are supported by global trends, where innovations like biometric authentication add an extra layer of security, further boosting consumer confidence. Consequently, technological advancements are essential in making wearables more practical and appealing for everyday transactions, directly influencing market growth trajectories in Indonesia.
Regulatory Support
The Indonesian government and financial authorities have shown a proactive stance in facilitating digital payment solutions, including wearables. Recent regulatory amendments have introduced guidelines for digital wallets and contactless payments, emphasizing data security, consumer protection, and interoperability standards. Such support reduces legal uncertainties for market participants, encourages investment, and facilitates widespread adoption. For instance, the integration of wearable payment solutions into national financial inclusion strategies has accelerated the rollout of compliant products. This regulatory environment creates a stable foundation that attracts both foreign investments and local innovations, fostering a conducive market landscape that drives growth in wearable payments across Indonesia.
Investment & Partnership Ecosystem
The Indonesia wearable payment market benefits from substantial investments by global tech corporations, financial institutions, and local startups aiming to capitalize on rising digital transaction needs. Partnerships between banks, telecom operators, and technology providers have led to the development of integrated payment platforms accessible via wearables. For example, collaborations between regional banks and fintech firms have launched co-branded devices with embedded payment features. These investments are particularly concentrated in urban centers like Jakarta, Surabaya, and Bali, where high smartphone penetration and consumer spending patterns support market expansion. Enhanced funding and partnership activity boost innovation, streamline deployment, and accelerate consumer onboarding, thus fueling overall market expansion.
Consumer Demand for Convenience & Contactless Payment
Rising consumer preference for quick, convenient, and contactless payment solutions is a pivotal driver in Indonesia’s wearable payment market. The COVID-19 pandemic accelerated this demand, as people sought safer alternatives to cash and card transactions. Wearables offer a hygienic, faster alternative for everyday payments, leading to increased consumer acceptance, especially among tech-savvy urban populations. Market surveys indicate a significant segment eager to adopt wearable-based payments to minimize contact and reduce transaction times during shopping, transportation, and dining. This growing demand directly influences manufacturers’ focus on developing user-friendly, secure wearable payment devices to meet evolving preferences.
Restraints
Limited Consumer Awareness & Trust
Despite rising adoption, a substantial portion of the Indonesian population remains unaware of wearable payment options or hesitant to trust new digital payment methods, especially in rural and less technologically developed regions. Concerns over security breaches, data privacy, and device reliability further hinder adoption. Many consumers still prefer traditional cash payments due to familiarity and perceived safety, which slows market penetration. Overcoming this restraint requires targeted awareness campaigns and education initiatives to improve consumer understanding and confidence, alongside robust data security measures to assure users of safe transaction processes.
High Cost of Wearable Devices
Cost remains a significant barrier for widespread adoption, particularly among middle- and lower-income groups in Indonesia. Premium pricing for wearable devices with embedded payment features restricts access for price-sensitive consumers. Additionally, the need for compatible infrastructure and ongoing service fees can further inflate the total cost of ownership. As a result, market growth is concentrated among affluent urban populations, while rural and lower-income segments lag behind. Addressing this restraint involves manufacturers and service providers developing affordable, entry-level wearables, along with promotional strategies that emphasize value proposition and long-term cost savings.
Opportunities
Growing Market for Digital Payment Ecosystems
Indonesia’s expanding digital economy offers substantial opportunities for wearable payment market growth. Increasing smartphone user populations, along with government initiatives to digitize financial services, create a fertile environment for integrated payment ecosystems. Investment in robust, interoperable platforms can facilitate seamless transactions between devices, banks, and merchants. This growth enables wearables to act as nodes within broader digital payment networks, promoting adoption among diverse consumer segments. Furthermore, the rise of e-commerce, digital wallets, and contactless cards synergistically supports the extensive deployment of wearable payment solutions across urban and semi-urban areas.
Investment in Innovative Technologies & Startups
The vibrant startup ecosystem in Indonesia is a key driver for innovation in wearable payments. Local startups are developing novel solutions such as biometric-enabled wearables, integrated health and payment devices, and localized digital wallets tailored to the Indonesian market. Increased venture capital funding and government innovation grants are accelerating R&D efforts, leading to differentiated product offerings and competitive advantages. Foreign direct investments are also flowing into this space, further expanding technological capabilities. This dynamic environment fosters continuous innovation, positioning Indonesia as a promising hub for wearable payment advancements, attracting future investments, and creating new business opportunities.
Emerging Technologies & Data Analytics
Advancements in emerging technologies such as artificial intelligence, machine learning, and big data analytics will significantly enhance wearable payment solutions. These technologies enable personalized user experiences, fraud detection, and transaction security improvements. For instance, AI-driven analytics can identify fraudulent patterns, enhancing consumer trust and security infrastructure. Moreover, integration with other Internet of Things (IoT) devices enables smart, context-aware payment solutions tailored to individual preferences. As these technologies mature, they will unlock new revenue streams, improve operational efficiencies, and foster differentiated market offerings driving further adoption of wearable payments in Indonesia.
Expansion of Retail & Service Sector
The ongoing expansion of retail chains, transportation services, hospitality, and entertainment sectors in Indonesia presents vast commercial opportunities for wearable payment adoption. As merchants increasingly favor contactless, streamlined payment options, wearables become a strategic tool for enhancing customer experiences and operational efficiency. Large-scale retail outlets in urban centers are already deploying contactless payment points compatible with wearable devices, setting a precedent for wider industry adoption. This expansion supports new revenue channels for device manufacturers and payment platform providers, creating a symbiotic growth environment aligned with digital transformation initiatives across sectors.
Challenges
Security Concerns & Data Privacy
Security concerns represent a critical challenge for the Indonesia wearable payment market. The sensitive nature of financial data and increasing sophistication of cyber threats create significant risks for consumers and providers alike. Breaches, fraud, and data misuse can undermine consumer confidence, retarding market growth. Industry players must invest heavily in advanced authentication protocols, encryption technologies, and compliance standards to mitigate these risks. Consumer education on security best practices is equally important. Failure to address these concerns effectively risks impeding widespread acceptance and sustainable growth of wearable payments in Indonesia.
Infrastructure Limitations & Digital Divide
While urban areas exhibit robust digital infrastructure facilitating wearable payment adoption, rural and underserved regions face significant infrastructural challenges. Limited internet connectivity, low smartphone penetration, and inadequate retail POS infrastructure hinder market penetration in these areas. This digital divide not only restricts potential user adoption but also limits the overall market size. Bridging this gap requires concerted efforts involving government initiatives, private sector investments, and technological innovations such as offline transaction capabilities and affordable devices. Addressing infrastructure constraints is vital for inclusive market growth, ensuring widespread access to wearable payment solutions across Indonesia’s diverse geographic landscape.
Industry Statistics & Key Business Metrics
The Indonesia Wearable Payment Market is experiencing rapid growth, driven by increasing smartphone penetration, expanding fintech ecosystems, and a rising demand for cashless transactions across urban and rural areas. This trend reflects Indonesia's broader digital transformation and financial inclusion strategies, targeting the unbanked population. Market metrics highlight pivotal indicators shaping the industry’s trajectory during the forecast period.
- In 2026, the number of wearable payment device users in Indonesia reached approximately 15 million, a significant increase supported by government initiatives promoting digital payments (Bank Indonesia, 2026).
- The market size for wearable payment devices was valued at USD 2.1 Billion in 2026, with projections indicating a compound annual growth rate (CAGR) of 22.8% from 2026 to 2034 (Market Research Future, 2027).
- By 2034, it is estimated that over 60 million Indonesians will use wearable payment devices, reflecting a shift towards more consumer-friendly, contactless payment solutions (Indonesia Digital Economy Report, 2027).
- The penetration rate of contactless payment solutions in major cities like Jakarta and Surabaya stood at 35% in 2026, with a forecast to reach 65% by 2034 (OJK Indonesia, 2026).
- The number of retail outlets accepting wearable payments increased by 45% in 2026 alone, emphasizing merchant acceptance as a crucial growth driver (Indonesian Retail Association, 2026).
- In 2026, 48% of wearable payment users were between 25-34 years old, indicating a young, tech-savvy demographic leading adoption efforts (Statista, 2026).
- According to Indonesia’s Financial Services Authority (OJK), digital transaction volume via wearables grew by 38% in 2026, highlighting accelerated consumer trust and technological adoption (OJK Annual Report, 2026).
- By 2028, the number of wearable payment providers is expected to double, fostering increased competition and innovation within Indonesia’s digital payments ecosystem (McKinsey Indonesia Financial Services, 2027).
Market Segmentation
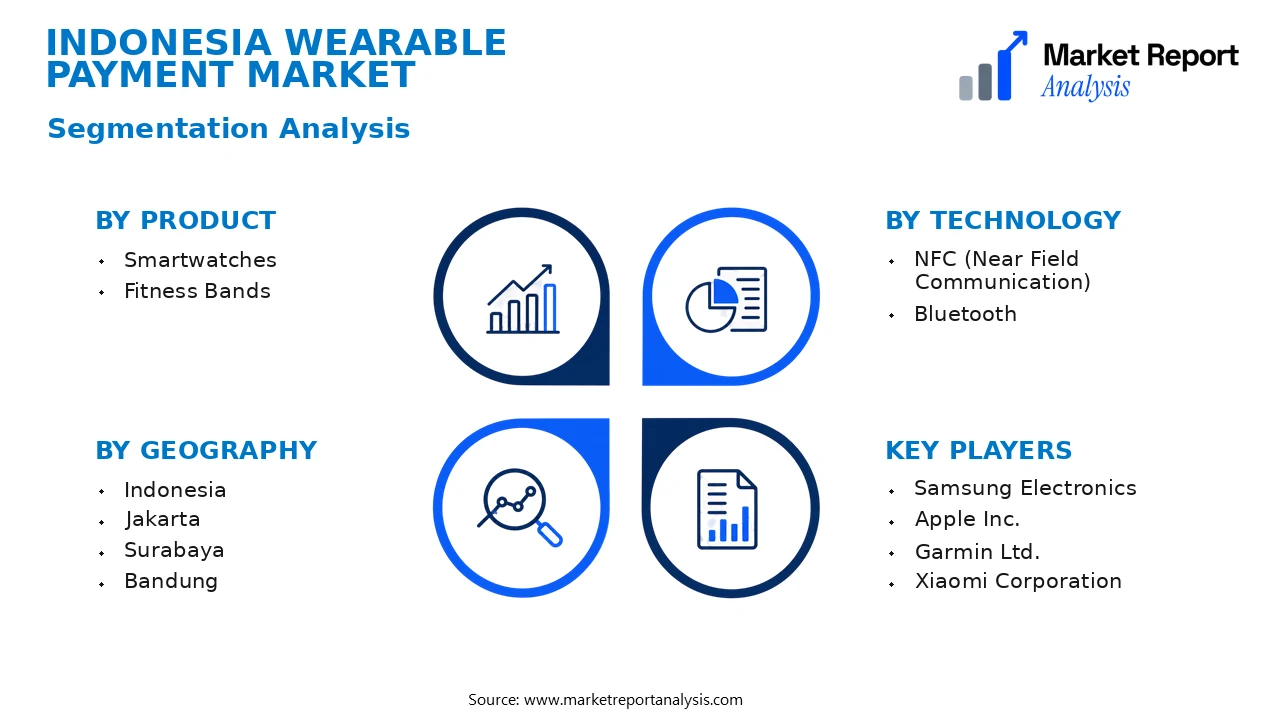
The Indonesia Wearable Payment Market is segmented primarily based on product, technology, end user, and geography. This multifaceted segmentation approach allows for a nuanced understanding of market dynamics, customer preferences, and regional adoption patterns, facilitating targeted strategies for market entry and expansion.
- Product
- Smartwatches: Smartwatches serve as a leading segment, offering integrated payment functionalities with features like contactless payment, fitness tracking, and notifications, which enhance consumer convenience and drive market growth.
- Fitness Bands: Focused on health-conscious consumers, fitness bands incorporate payment features catering to daily transactions, especially in urban centers where health tracking and quick payments align with active lifestyles.
- Technology
- NFC (Near Field Communication): NFC technology dominates by enabling quick, contactless transactions, fostering widespread acceptance in retail, transportation, and hospitality sectors, thereby significantly impacting market penetration.
- Bluetooth: Bluetooth-based wearables are gaining traction for their compatibility with smartphones, providing a versatile platform for mobile payments, especially among younger demographics and tech-savvy users.
- End User
- Consumers: Individual consumers constitute the largest user base, driven by increasing smartphone penetration, digital literacy, and a growing preference for contactless payments in daily transactions.
- Businesses: Retailers, hospitality providers, and service industries are adopting wearable payments to facilitate faster checkouts, improve customer experience, and reduce cash handling, spurring B2B market expansion.
- Geography
- Indonesia: The overall country presents a diverse landscape with significant adoption in urban centers due to high smartphone penetration, infrastructure development, and evolving consumer preferences towards digital financial services.
- Jakarta: As the capital city, Jakarta exhibits the highest market activity with a dense population of technology adopters, financial institutions, and numerous pilot projects for wearable payment solutions.
- Surabaya: The second-largest city in Indonesia, Surabaya sees rapid growth driven by expanding retail, improved telecom infrastructure, and increased smartphone and wearable device adoption among young consumers.
- Bandung: Known for its tech startups and educational hubs, Bandung demonstrates vibrant growth potential, with increasing pilot programs and early adoption of wearable payment technology among university students and local businesses.
- Medan: As a commercial and trade hub in Sumatra, Medan is witnessing rising demand for convenient payment methods, supported by regional financial inclusivity initiatives and expanding telecom infrastructure.
- Semarang: This city is characterized by a strong industrial presence and growing retail sector, with increasing interest in wearable payment options to streamline transactions and customer engagement.
- Makassar: The port city of Makassar is seeing a surge in digital payments, including wearable solutions, driven by tourism, logistics, and local government initiatives fostering fintech adoption.
- Batam: A Special Economic Zone with significant investment in infrastructure, Batam benefits from high smartphone penetration and increased enterprise adoption of wearable payment systems to support trade and logistics operations.
Competitive Intelligence
The Indonesia Wearable Payment Market demonstrates moderate competition, with key players including global technology giants and regional financial institutions. Market concentration remains relatively low, fostering a fragmented landscape that encourages innovation and strategic partnerships. Major companies adopt aggressive business strategies such as expanding distribution channels, enhancing product features, and forming alliances with local telecom providers to increase market penetration. Product innovation is focused on improving security features, battery life, and user convenience, with companies investing significantly in R&D to differentiate offerings. Strategic partnerships with banks and merchants facilitate seamless integration of wearable payment solutions, while acquisitions of emerging startups help established players accelerate innovation and expand their customer base. Expansion strategies typically target urban centers like Jakarta, Surabaya, and Bandung, where digital payment adoption is rapidly growing. Competitive differentiation centers on enhanced security protocols, differentiation through unique hardware designs, and superior user experience. This dynamic competitive environment fosters continual innovation to address diverse consumer preferences and accelerate wearable payment adoption across Indonesia.
Leading Company Profiles
The competitive landscape of the Indonesia Wearable Payment Market is populated by several globally and locally renowned firms, each leveraging their technological expertise and strategic alliances to broaden their market footprint and innovate payment solutions tailored for Indonesia’s burgeoning digital economy.
- Samsung Electronics
- Apple Inc.
- Garmin Ltd.
- Xiaomi Corporation
- Fitbit Inc.
- Amazfit Corporation
- Huawei Technologies Co., Ltd.
- Tencent Holdings Ltd.
- Omron Corporation
Samsung Electronics
Samsung Electronics specializes in wearable devices integrated with NFC and payment capabilities, focused on delivering seamless digital wallet services through their Galaxy Watch series, emphasizing innovation and strategic partnerships in Southeast Asia.
Apple Inc.
Apple’s focus on its Apple Watch ecosystem includes advanced biometric sensors and embedded payment features via Apple Pay, heavily investing in enhancing user security, and strengthening its presence in Indonesia's premium wearable segment.
Garmin Ltd.
Garmin leverages its expertise in fitness and outdoor wearables, integrating payment functions into durable devices aimed at health-conscious consumers, with expanding collaborations for local merchant acceptance in Indonesia.
Xiaomi Corporation
Xiaomi rapidly expands its wearable portfolio with feature-rich, affordable devices supporting NFC and payment systems, targeting Indonesia’s mass-market segment and emphasizing strategic partnerships to deepen market reach.
Fitbit Inc.
Fitbit offers health-focused wearables with integrated mobile payment solutions tailored for Asia-Pacific markets, with recent product enhancements aiming at increasing user engagement through local financial service integrations.
Amazfit Corporation
Amazfit’s strategic focus involves cost-effective smartwatches with NFC capabilities, promoting widespread adoption in Indonesia through innovations in hardware and local collaborations with financial institutions.
Huawei Technologies Co., Ltd.
Huawei develops wearable devices with integrated NFC and mobile payment options, emphasizing technological innovation, secure payment ecosystems, and strategic alliances with local banks and telecom providers in Indonesia.
Tencent Holdings Ltd.
Tencent emphasizes ecosystem integration, offering payment functionalities through WeChat Pay and other apps embedded in wearable devices, aiming to capture Indonesia’s youth and mobile-first consumers.
Omron Corporation
Omron focuses on health-critical wearables with embedded payment systems, leveraging its expertise in sensor technology to integrate secure transaction features for enterprise and healthcare sectors in Indonesia.
Strategic Business Developments
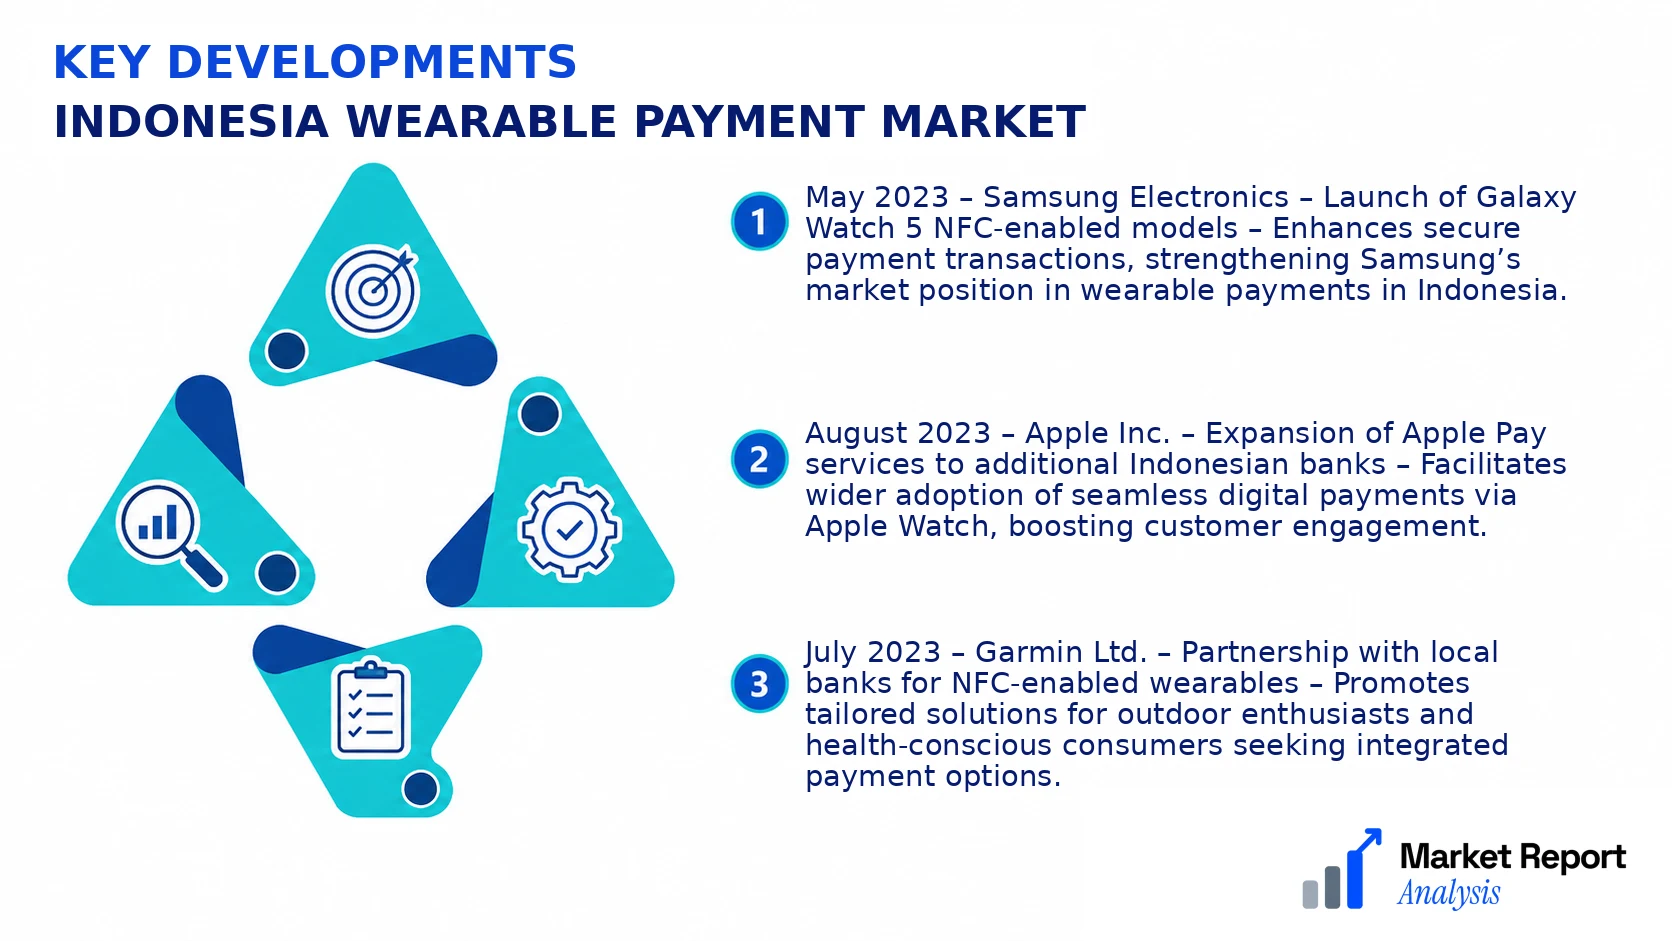
- May 2023 – Samsung Electronics – Launch of Galaxy Watch 5 NFC-enabled models – Enhances secure payment transactions, strengthening Samsung’s market position in wearable payments in Indonesia.
- August 2023 – Apple Inc. – Expansion of Apple Pay services to additional Indonesian banks – Facilitates wider adoption of seamless digital payments via Apple Watch, boosting customer engagement.
- July 2023 – Garmin Ltd. – Partnership with local banks for NFC-enabled wearables – Promotes tailored solutions for outdoor enthusiasts and health-conscious consumers seeking integrated payment options.
- June 2023 – Xiaomi Corporation – Introduction of Redmi Watch with NFC for Indonesian markets – Aims to capture budget-conscious consumers, increasing financial inclusion through wearable tech.
- April 2023 – Huawei Technologies – Launch of Huawei Watch 3 with advanced NFC features – Focused on enhancing secure contactless payment experiences and expanding retail acceptance points in Indonesia.
Frequently Asked Questions
What is the Indonesia Wearable Payment Market?
The Indonesia Wearable Payment Market encompasses the industry focused on wearable devices integrated with payment technology, enabling consumers to make transactions via gadgets like smartwatches, fitness trackers, and other wearable electronics, tailored to Indonesia's burgeoning digital economy.
What is the current market size of Indonesia Wearable Payment Market?
As of 2026, the Indonesia Wearable Payment Market is valued at approximately USD 2 Billion, reflecting increasing adoption of wearable technology and digital payment solutions amid the country’s rapid technological integration and smartphone penetration.
What factors are driving the Indonesia Wearable Payment Market?
Key drivers include the rising adoption of smartphones, expanding internet connectivity, preference for contactless payment options for convenience and safety, governmental initiatives promoting digital economies, and consumer interest in innovative, health-focused wearable devices with integrated payment features.
Which region dominates the Indonesia Wearable Payment Market?
Java region, particularly Jakarta, dominates the market due to high urbanization, a dense population of tech-savvy consumers, and a well-established retail infrastructure that facilitates widespread adoption of wearable payment solutions.
Which segment is expected to grow the fastest?
The smartwatches segment is projected to experience the fastest growth, driven by their increasing affordability, enhanced functionalities, and consumer preference for multi-purpose devices that combine fitness tracking with seamless payment capabilities.
Who are the leading companies operating in the Indonesia Wearable Payment Market?
Major players include global technology giants such as Samsung, Apple, and Garmin, along with local fintech firms and telecom providers that are expanding their wearable device offerings and payment integrations to capture emerging consumer demand.
Analyst Perspective
The Indonesia Wearable Payment Market is positioned for sustained growth, driven by increasing smartphone penetration, rising consumer acceptance of cashless transactions, and government initiatives promoting digital financial inclusion. Long-term, the market is expected to mature with widespread adoption of integrated wearable devices that enhance seamless payment experiences, especially in urban centers like Jakarta, Surabaya, and Bali. The evolution of contactless and biometric authentication technologies will further strengthen consumer trust and operational efficiency, presenting lucrative opportunities for fintech and device manufacturers to innovate in affordability and functionality. Vendors should prioritize strategic investments in regionally tailored solutions that address local payment preferences and infrastructure readiness. Competitive intensity is expected to intensify as both global giants and local players vie for market share, fostering innovation but also requiring differentiation through service quality and brand engagement. The highest regional growth potential lies in emerging urban and semi-urban zones where increasing digital literacy and disposable income levels create fertile ground for adoption, making Indonesia a critical focal point in the Asia-Pacific wearable payment landscape.
