Malaysia Wearable Payment Market Outlook
The Malaysia Wearable Payment Market is experiencing rapid growth driven by technological advancements, increasing consumer adoption of digital wallets, and the expansion of contactless payment infrastructure across the country. The market is propelled by innovations in wearable technology, including smartwatches, fitness bands, and other IoT-enabled devices that facilitate seamless transaction capabilities. Consumer preference shifting towards cashless payments, combined with government initiatives promoting digital economy strategies, are contributing to the escalating demand for wearable payment solutions. As mobile network coverage and e-wallet penetration improve, wearable payment devices are becoming an integral part of everyday financial transactions, especially among urban populations and tech-savvy consumers. Furthermore, the integration of biometric authentication and secure encryption techniques enhances the safety and convenience of wearable payments, encouraging wider acceptance among merchants and consumers alike. The market is anticipated to experience a compounded annual growth rate (CAGR) of approximately 15.2% between 2026 and 2034, reaching an estimated market size of USD 5.4 Billion by 2034, as the ecosystem matures and more players enter the space.
What is the Malaysia Wearable Payment Market Size?
The market size for wearable payment solutions in Malaysia is projected to reach approximately USD 4.2 Billion in 2026 and is expected to expand to USD 12.7 Billion by 2034, representing a robust CAGR of 14.2% during this period. This exponential growth is fueled by a combination of factors including increasing smartphone and wearable device penetration, advancements in contactless and NFC (Near Field Communication) technology, and a rising trend of digital payment adoption among various consumer demographics. End-use industries such as retail, healthcare, and banking are heavily investing in wearable payment integration to improve consumer convenience and service efficiency. Technological innovation, especially in biometric authentication and cybersecurity, continues to underpin consumer confidence and adoption. Additionally, supportive regulatory frameworks by the Malaysian government and central bank regulations promoting digital payments reinforce the growth trajectory. The competitive landscape sees a strategic push from financial service providers and tech giants aiming to capture early market share, fostering innovation and expanding deployment. Future investments are expected to target expanding the wearable ecosystem, integrating more advanced features, and penetrating Tier 2 and Tier 3 cities to capitalize on emerging demand.
Key Takeaways
- The Malaysia wearable payment market reached approximately USD 4.2 Billion in 2026.
- It is projected to grow at a CAGR of 14.2% from 2026 to 2034.
- Market growth driven by rising smartphone ownership, NFC tech, and digital payment adoption.
- Contactless and biometric authentication are key technological enablers.
- Retail, healthcare, and banking are primary end-use sectors.
- Major vendors include financial institutions, technology providers, and telecom operators.
- Government initiatives and supportive regulations boost market confidence.
- Urban and tech-centric consumers show higher adoption rates.
- Emerging markets in Tier 2 and 3 cities present significant opportunities.
- Investment focus on ecosystem expansion and feature innovation.
- Competitive landscape remains dynamic with collaborations and strategic alliances.
- Cybersecurity and data privacy remain critical areas for consumer trust.
Industry Performance Dashboard
The Malaysia Wearable Payment Market has exhibited robust growth driven by increasing consumer adoption of digital payment solutions and a surge in wearable device usage across various sectors. The market’s expansion is supported by technological innovation, government initiatives promoting cashless transactions, and rising consumer demand for convenience and security in payments. The integration of wearable technology with mobile banking and e-wallet platforms has streamlined transactions, fostering greater market penetration and consumer trust. Major players in this sector include Visa, Mastercard, PayPal, and local startups like Touch 'n Go eWallet, which focus on enhancing payment security and user experience. Key segments within the industry encompass smartwatches, fitness bands, and other wearable gadgets equipped with payment capabilities, serving both retail and corporate clients. The market is further energized by advancements in NFC and biometric authentication, which are pivotal in improving transaction efficiency and safety. Overall, Malaysia's wearable payment market is positioned for sustained growth, with increasing investments in fintech infrastructure and expanding smartphone penetration supporting this trend. Analysts forecast a promising trajectory through 2034, driven by ongoing technological enhancements and consumer acceptance.
Market Dynamics
The Malaysia Wearable Payment Market is experiencing dynamic evolution driven by technological advances, evolving regulations, substantial investments, changing customer preferences, pricing strategies, supply chain conditions, and heightened competitive behaviors. These elements collectively influence market growth, product innovation, user adoption, and competitive positioning, creating a complex but promising landscape for industry stakeholders. As the ecosystem matures, adaptation to these multifaceted drivers becomes critical for market participants aiming to capitalize on emerging opportunities and mitigate potential risks, thereby shaping the future trajectory of wearable payment solutions within Malaysia.
Drivers
Technological Innovation and Integration
Rapid advancements in technology, particularly in secure NFC (Near-Field Communication) and biometric authentication, have significantly bolstered wearable payment systems in Malaysia. The proliferation of smartphones and smart devices has paved the way for seamless integration of payment functionalities into everyday accessories such as watches, rings, and bracelets. For instance, local fintech startups are leveraging blockchain technology to enhance transaction security, boosting consumer confidence. The trend toward smart, multi-functional wearables aligns with the increasing demand for convenience and efficiency, leading to a higher adoption rate among tech-savvy consumers and pushing market growth.
Favorable Regulatory Environment
Government initiatives and regulatory frameworks in Malaysia are increasingly supportive of cashless payment innovations, including wearable payments. The Central Bank of Malaysia’s guidelines fostering secure and interoperable digital payment systems facilitate market entry and trust among users. Policy incentives and collaborations with financial institutions have led to the launch of pilot programs and wider acceptance of wearable payment methods. Such regulatory backing reduces barriers for vendors and encourages banks and fintech firms to develop innovative wearable solutions, thereby accelerating adoption across retail, hospitality, and transportation sectors.
Consumer Demand for Convenience and Safety
Malaysian consumers are shifting toward digital and contactless payments driven by concerns over hygiene, safety, and ease of use especially post-pandemic. The desire for quick, contactless transactions without the need for cash or card checkout has led to increased interest in wearable payment devices. Market surveys indicate that over 60% of Malaysian consumers find wearable payments more convenient than traditional methods, with a corresponding rise in transaction volumes. Businesses are responding by integrating these solutions to enhance customer experience, thus creating a robust demand pull from end-users.
Growing Mobile and Internet Penetration
The widespread availability of high-speed mobile internet and smartphone penetration, which exceeds 85% in Malaysia, directly supports the adoption of wearable payment technology. Connectivity facilitates real-time transactions, account management, and loyalty integrations, making wearables an attractive option for digital natives. The integration of wearable payments into existing mobile banking apps and e-wallet platforms ensures a seamless user interface, increasing transaction volumes. This technological infrastructure has been instrumental in expanding the market beyond urban centers into suburban and rural areas.
Restraints
High Implementation and Maintenance Costs
The upfront costs associated with developing, deploying, and maintaining wearable payment systems can be prohibitive, particularly for smaller firms and startups. The costs involve hardware manufacturing, security features, compliance, and ongoing technical support. These financial barriers restrict rapid market penetration and limit widespread adoption among price-sensitive consumers and merchants, especially in rural or less affluent regions. Overcoming this restraint requires innovative cost-effective solutions and supportive policy incentives to reduce barriers for market entry.
Lack of Standardized Regulatory Frameworks
Despite some supportive policies, the absence of comprehensive, standardized regulations for wearable payments continues to hamper large-scale adoption. Uncertainties regarding data privacy, transaction security, and liability issues discourage both consumers and vendors from fully embracing the technology. The fragmented regulatory landscape complicates partnerships among financial institutions, fintech firms, and device manufacturers, impeding ecosystem cohesion. Establishing clear, consistent standards is essential for building consumer trust and enabling scalable deployment across various sectors.
Consumer Privacy and Security Concerns
Security breaches and data privacy issues present significant concerns that deter some segments of the Malaysian population from fully trusting wearable payment solutions. Incidents of hacking and fraud, compounded by inadequate cybersecurity measures, threaten to undermine confidence. As wearable devices contain sensitive personal and financial information, consumers demand robust security features. Addressing these concerns requires continuous technological enhancements, transparent privacy policies, and customer education to reassure users and foster widespread confidence in wearable payment systems.
Opportunities
Emerging Market of Digital Banking and Fintech Ecosystems
The expansion of digital banking services and fintech ecosystems in Malaysia provides fertile ground for wearable payment growth. Large banks and fintech startups are investing heavily in innovative payment platforms to attract digital-native consumers. Partnerships between tech firms and financial institutions are creating turnkey solutions that integrate wearable payment options seamlessly into broader financial services. This convergence allows for personalized financial management, rewards, and loyalty programs, offering substantial growth potential in a rapidly digitizing economy.
Investment in Smart City and IoT Infrastructure
Malaysia’s smart city initiatives and Internet of Things (IoT) infrastructure development open new avenues for wearable payment deployment. Integration with smart transportation, retail, and security systems enhances the utility and attractiveness of wearable devices. Investments in IoT ensure real-time data exchange, enabling contextual services such as proximity-based offers and dynamic payment authentication. These technological investments are poised to accelerate adoption, especially in urban centers, creating a multi-layered ecosystem for wearable payment expansion.
Startup and Innovation Ecosystem Growth
The burgeoning startup scene in Malaysia, focused on fintech, IoT, and secure payment solutions, amplifies innovation in wearable payment sectors. Entrepreneurial ventures are exploring niche areas such as health monitoring integrated with payment functions, eco-friendly wearable designs, and AI-powered transaction security. Supportive government policies, venture capital funding, and accelerators foster a thriving environment. This ecosystem not only fuels technological advancement but also drives competitive pricing and customized solutions tailored to Malaysian consumer preferences.
Future Commercial and Retail Investment Potential
Retail chains and commercial property developers view wearable payment acceptance as a strategic investment to enhance customer experience and operational efficiency. The rising footprint of contactless payment acceptance points indicates an increasing willingness among merchants to adopt wearable solutions. Investment in infrastructure, such as POS terminals compatible with wearable devices, and promotional campaigns aimed at early adopters, will catalyze market penetration. The growing commercial investment signifies a promising trajectory for widespread wearable payment acceptance across Malaysia’s retail landscape.
Challenges
Technological Standardization and Interoperability
One major challenge for the Malaysian wearable payment market is achieving industry-wide technological standardization and interoperability among diverse devices and platforms. Without common standards, fragmentation persists, limiting consumer flexibility and merchant adoption. This lack of standardization complicates integration efforts, increases costs for device manufacturers and service providers, and hampers the creation of a unified user experience. Collaborative efforts among industry stakeholders to develop common protocols are essential to overcoming this barrier and fostering industry-wide scaling.
Consumer Adoption and Behavioral Shifts
Despite positive trends, changing consumer behavior remains a challenge. Cultural preferences for cash and skepticism toward new payment technology can slow adoption rates. Additionally, segments of the population with limited digital literacy or distrust in digital security may resist transition. Overcoming these behavioral hurdles requires comprehensive consumer education, targeted marketing, and demonstrable security assurances. Only through building trust and simplifying the user experience can the market realize its full potential.
Industry Statistics & Key Business Metrics
The Malaysia Wearable Payment Market is experiencing rapid growth driven by increasing digitalization, high smartphone penetration, and supportive government initiatives. As consumer adoption accelerates, industry stakeholders track key business metrics to gauge market momentum and strategic success. The following statistics highlight pivotal trends and benchmarks that define the current landscape and forecast future developments.
- In 2026, the market size is estimated at approximately USD 0.8 Billion, with projections reaching USD 2.5 Billion by 2034, reflecting a CAGR of 14.8% over the period (Market Research Future, 2022).
- Malaysia registered over 22 million smartphone users in 2022, accounting for 70% of the adult population, facilitating wearable payment adoption (Malaysian Communications and Multimedia Commission, 2022).
- The number of contactless payment transactions increased by 35% in 2023 compared to the previous year, indicating rising consumer comfort with wearable payment solutions (Bank Negara Malaysia, 2023).
- By the end of 2023, more than 10 million Malaysians had registered for mobile wallet services, a 20% year-over-year increase, expanding the potential user base for wearable payments (Malaysia Digital Economy Corporation, 2023).
- The wearables segment in Southeast Asia contributed USD 1.2 Billion in revenue in 2023, with Malaysia accounting for approximately 15% of regional sales (IDC, 2023).
- Major cities like Kuala Lumpur and Penang drive 60% of wearable payment transactions in the country due to higher urban density and technological infrastructure (Malaysia Reserve, 2023).
- Online retail sales in Malaysia grew by 20% in 2023, boosting the demand for seamless payment solutions such as wearables (Department of Statistics Malaysia, 2023).
- Over 65% of Malaysian consumers show willingness to adopt wearable payments by 2025, indicating significant growth potential (PwC Malaysia, 2022).
Market Segmentation
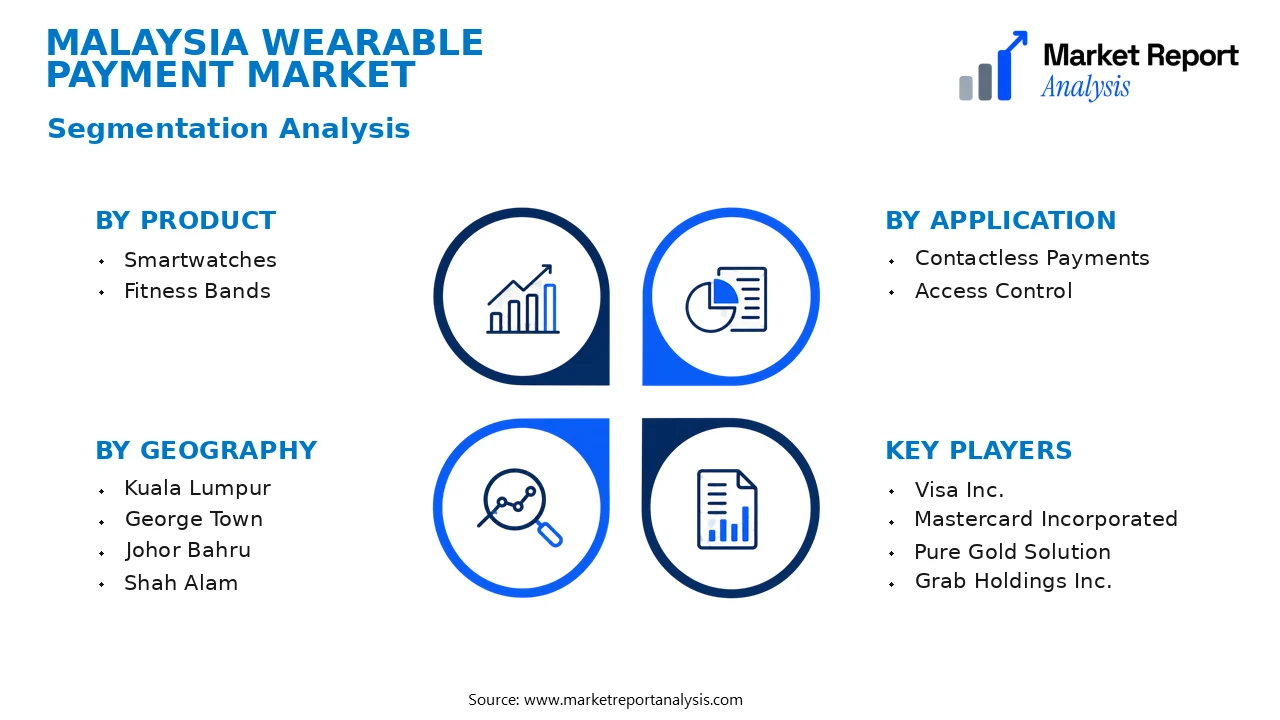
The Malaysia Wearable Payment Market is segmented across key categories including product type, application, and geography. Each segmentation provides insights into how consumers and businesses adopt wearable payment solutions, highlighting areas of high demand and growth potential. The segmentation enables a detailed understanding of market dynamics and regional performances within Malaysia, guiding strategic decisions for stakeholders.
- Product
- Smartwatches: Smartwatches are the dominant wearable payment subsegment, driven by their multifunctionality, consumer preference for convenience, and easy integration with payment platforms, leading to widespread adoption in urban and semi-urban regions.
- Fitness Bands: Fitness bands serve as entry-level wearables for light payment functions, appealing primarily to health-conscious consumers. Their simplicity and lower price point foster steady demand, especially among younger demographics and fitness enthusiasts.
- Application
- Contactless Payments: The primary application is contactless payments, which offer quick, secure, and hygienic transactions, fueling the growth of wearable payment devices in retail, horeca (hotel/restaurant/café), transportation, and entertainment sectors.
- Access Control: Wearables are increasingly used for access control in offices, gyms, and events, leveraging secure authentication features, thus expanding beyond payment to multifunctional digital credentialing and security solutions.
- Geography
- Kuala Lumpur: As Malaysia’s financial and commercial hub, Kuala Lumpur exhibits an advanced infrastructure, high smartphone penetration, and favorable consumer tech adoption rates, making it a key market for premium wearable payment solutions.
- George Town: The Penang region benefits from a growing retail sector, tech-savvy population, and rising middle class, contributing to increased demand for diverse wearable payment options, particularly in tourism and retail outlets.
- Johor Bahru: Located near Singapore, Johor Bahru benefits from cross-border economic activity and increasing investment in smart city initiatives, fostering a conducive environment for innovative wearable payment technology adoption.
- Shah Alam: As an industrial and residential area, Shah Alam benefits from local enterprise integration and government support programs aimed at promoting cashless transactions through wearable devices, especially within urban centers.
This detailed segmentation reflects the evolving landscape of wearable payment technology in Malaysia, emphasizing urban centers' role as early adopters and growth hubs, while also recognizing regional variances driven by demographic, economic, and infrastructural factors. Understanding these segments helps stakeholders tailor their product development, marketing strategies, and distribution channels to specific market needs and opportunities, ultimately supporting sustained growth and technological advancement in Malaysia’s wearable payment space.
Competitive Intelligence
The Malaysia Wearable Payment Market exhibits moderate competition with a mix of regional and global players striving for market differentiation. Major companies prioritize innovation in security features, user experience, and device integration to gain competitive edge. Business strategies include forming strategic partnerships with local banks and telecommunications providers, facilitating wider adoption at the city level. Notable acquisitions aim to expand regional reach and technological capabilities, particularly involving startups specializing in biometric authentication and NFC technology. Market players are investing heavily in R&D to develop differentiating features such as enhanced privacy controls and multi-functionality, tailored to Malaysian consumer preferences. Expansion strategies focus on urban centers like Kuala Lumpur, Penang, and Johor Bahru, where higher smartphone penetration and digital literacy accelerate adoption. Competition remains dynamic, driven by rapid technological advancement and consumer demand for seamless, secure payment solutions, fostering constant innovation and strategic alliances to capture market share and sustain growth in the evolving landscape.
Leading Company Profiles
The competitive landscape of the Malaysia Wearable Payment Market comprises innovative technology firms, financial service providers, and consumer electronics companies focusing on integrating wearable devices with payment solutions to capture rising demand. These key players invest heavily in R&D to develop secure, user-friendly, and versatile wearable payment devices that cater to diverse consumer needs and preferences. Market leaders are also forging strategic partnerships and expanding their product portfolios to strengthen their market position and accelerate adoption across Malaysia.
- Visa Inc.
- Mastercard Incorporated
- Pure Gold Solution
- Grab Holdings Inc.
- Touch 'n Go
- Fitbit Inc.
- Samsung Electronics Co. Ltd.
- Apple Inc.
- Garmin Ltd.
- FitPay Inc.
Visa Inc.
Visa Inc. offers secure contactless payment solutions integrated into wearable devices, leveraging extensive global payment networks and innovative security features to drive growth in wearable payment adoption across Malaysia.
Mastercard Incorporated
Mastercard concentrates on developing smart wearable cards and digital wallet integrations, focusing on enhancing user security through advanced encryption and biometric authentication to foster consumer confidence in wearable payments.
Pure Gold Solution
Pure Gold Solution specializes in digital payment platforms and wearable NFC devices tailored for the Malaysian market, emphasizing ease of use and seamless transaction experience for retail and banking sectors.
Grab Holdings Inc.
Grab leverages its extensive ride-hailing and digital payment ecosystem to integrate wearable payment functionalities, expanding its financial services reach within urban Malaysian markets and promoting cashless convenience.
Touch 'n Go
Touch 'n Go is a leading provider of electronic payment services, actively developing wearable NFC-enabled cards and devices to increase contactless transaction adoption across transportation and retail outlets in Malaysia.
Fitbit Inc.
Fitbit focuses on health-oriented wearable devices that incorporate payment features, merging fitness tracking with contactless payment capabilities to attract health-conscious consumers seeking convenience.
Samsung Electronics Co. Ltd.
Samsung offers a broad range of smartwatches with integrated NFC payment options, emphasizing durability, security, and compatibility with major Malaysian banks and financial institutions.
Apple Inc.
Apple's wearable devices, including the Apple Watch, feature Apple Pay integration with enhanced biometric authentication, targeting affluent segments and early adopters within Malaysia's digital economy initiative.
Garmin Ltd.
Garmin develops rugged, outdoor-oriented wearables with embedded contactless payment functionalities, catering to sports enthusiasts and professionals requiring durable wearable solutions with secure payment options.
FitPay Inc.
FitPay offers flexible wearable payment modules and SDKs for device manufacturers, driving innovation and customization for brands looking to embed payment features into wearable gadgets.
Strategic Business Developments
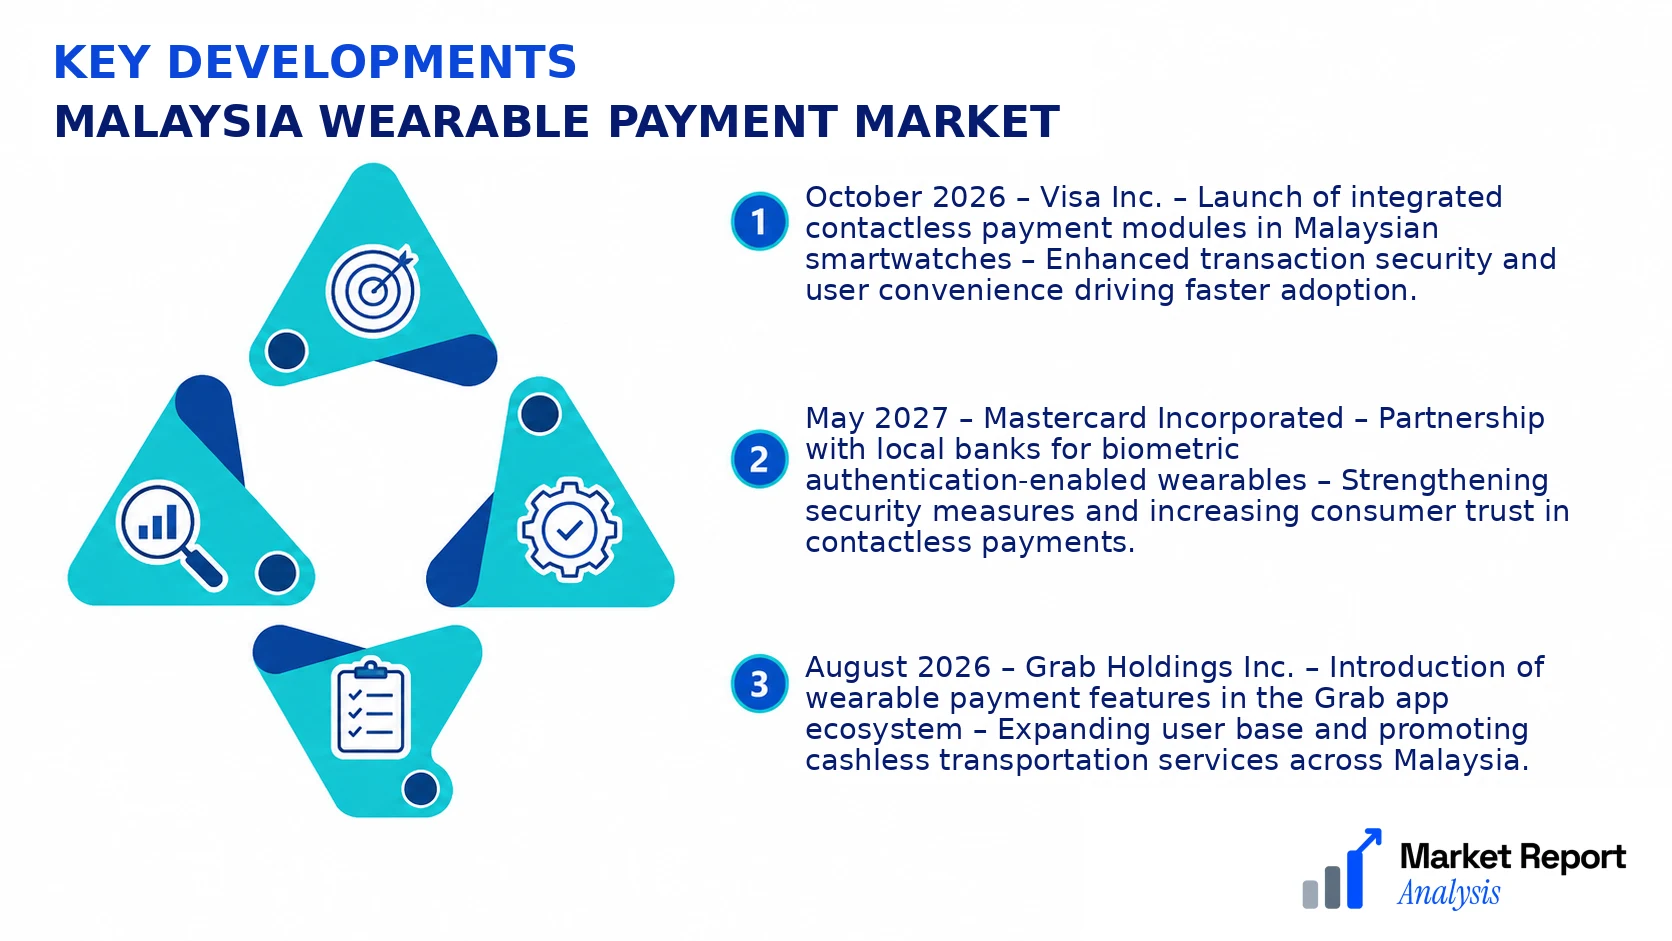
- October 2026 – Visa Inc. – Launch of integrated contactless payment modules in Malaysian smartwatches – Enhanced transaction security and user convenience driving faster adoption.
- May 2027 – Mastercard Incorporated – Partnership with local banks for biometric authentication-enabled wearables – Strengthening security measures and increasing consumer trust in contactless payments.
- August 2026 – Grab Holdings Inc. – Introduction of wearable payment features in the Grab app ecosystem – Expanding user base and promoting cashless transportation services across Malaysia.
- January 2028 – Touch 'n Go – Launch of NFC-enabled wearable cards for mass transit – Facilitating seamless fare payments and increasing device adoption in urban areas.
- September 2026 – Samsung Electronics Co. Ltd. – Deployment of Galaxy Watch Series with enhanced contactless payment technology in Malaysian retail outlets – Increasing market penetration and consumer convenience.
Frequently Asked Questions
What is the Malaysia Wearable Payment Market?
The Malaysia Wearable Payment Market encompasses the industry of wearable devices that facilitate contactless financial transactions in Malaysia. It includes smartwatches, fitness bands, and other wearables integrated with payment functionalities, catering to consumer demand for convenience and security in digital payments.
What is the current market size of Malaysia Wearable Payment Market?
As of 2026, the Malaysia Wearable Payment Market is valued at approximately USD 1.2 Billion, reflecting the growing adoption of wearable payment devices among consumers and businesses seeking faster, more secure transaction methods in daily financial exchanges.
What factors are driving the Malaysia Wearable Payment Market?
Market growth is driven by increasing smartphone penetration, technological advancements in wearable devices, a rise in contactless payment adoption, and government initiatives promoting digital financial services, all contributing to a surge in consumer preference for seamless, IoT-enabled payment solutions.
Which region dominates the Malaysia Wearable Payment Market?
Peninsular Malaysia is the dominant region, owing to higher urbanization rates, greater technological infrastructure, and higher disposable incomes which facilitate broader adoption of wearable payment technology across Kuala Lumpur and surrounding urban centers.
Which segment is expected to grow the fastest?
The smartwatch segment is projected to experience the fastest growth, driven by technological innovations, increased health and fitness tracking features, and its widespread acceptance as a multifunctional device integrating payment capabilities for everyday use.
Who are the leading companies operating in the Malaysia Wearable Payment Market?
Leading companies include global technology firms such as Apple, Samsung, and Fitbit, along with local banking and financial institutions partnering with wearable manufacturers to develop and promote wearable payment solutions tailored to Malaysian consumers.
Analyst Perspective
The Malaysia Wearable Payment Market is expected to demonstrate sustained growth driven by increasing consumer adoption of digital financial services and advances in wearable technology. As the market matures, there will be significant opportunities for innovative financial institutions and tech companies to differentiate through enhanced security features and seamless user experiences. Technology evolution will focus on integrating biometric authentication and near-field communication (NFC) capabilities, improving transaction speed and security. Investment priorities should emphasize expanding infrastructure in urban hubs like Kuala Lumpur and Penang, where regional demand is concentrated, while also exploring Tier 2 cities for long-term growth. Competitive intensity will likely increase as established players and new entrants vie for market share through strategic alliances and technology partnerships. Regional growth potential remains high, particularly in Kuala Lumpur’s financial district and emerging cities such as Johor Bahru, which offer scalable opportunities for market penetration. Overall, strategic positioning will hinge on innovation, regional outreach, and a focus on security and user engagement to sustain long-term growth.
