South Korea Adaptive Front Lighting Systems Market Outlook
The 2026 market size is USD 4.2 Billion. The South Korea Adaptive Front Lighting Systems Market demonstrates rapid technological advancements driven by stringent safety regulations, increasing consumer awareness, and OEM investments in innovative vehicle lighting solutions. The market is critically influenced by the automotive industry’s shift toward autonomous and connected vehicles, where sophisticated lighting systems enhance driver safety and vehicle visibility. South Korea's highly developed automotive manufacturing infrastructure, combined with government initiatives to promote eco-friendly and smart mobility, propels the adoption of advanced lighting technologies. Regulatory frameworks mandating improved visibility standards and crashworthiness further stimulate market growth. The region’s automakers are investing in R&D for intelligent lighting features, including matrix LED and laser lighting systems, aiming to differentiate their offerings in competitive markets. The rise of electric vehicles (EVs) in South Korea also influences the segment, as EV manufacturers integrate sophisticated lighting systems to align with sustainability goals and innovative branding. Amid such dynamics, the adaptive front lighting market is projected to expand at a CAGR of 9.80% from 2026 to 2034, reaching a market size of approximately USD 8.5 Billion by 2034. Local automakers’ strategic alliances with global technology providers catalyze technology transfer and innovation, further fueling market expansion. Additionally, the increasing penetration of ADAS features and the OEM focus on safety-centric vehicle design are key drivers shaping the evolution of this sector within South Korea.
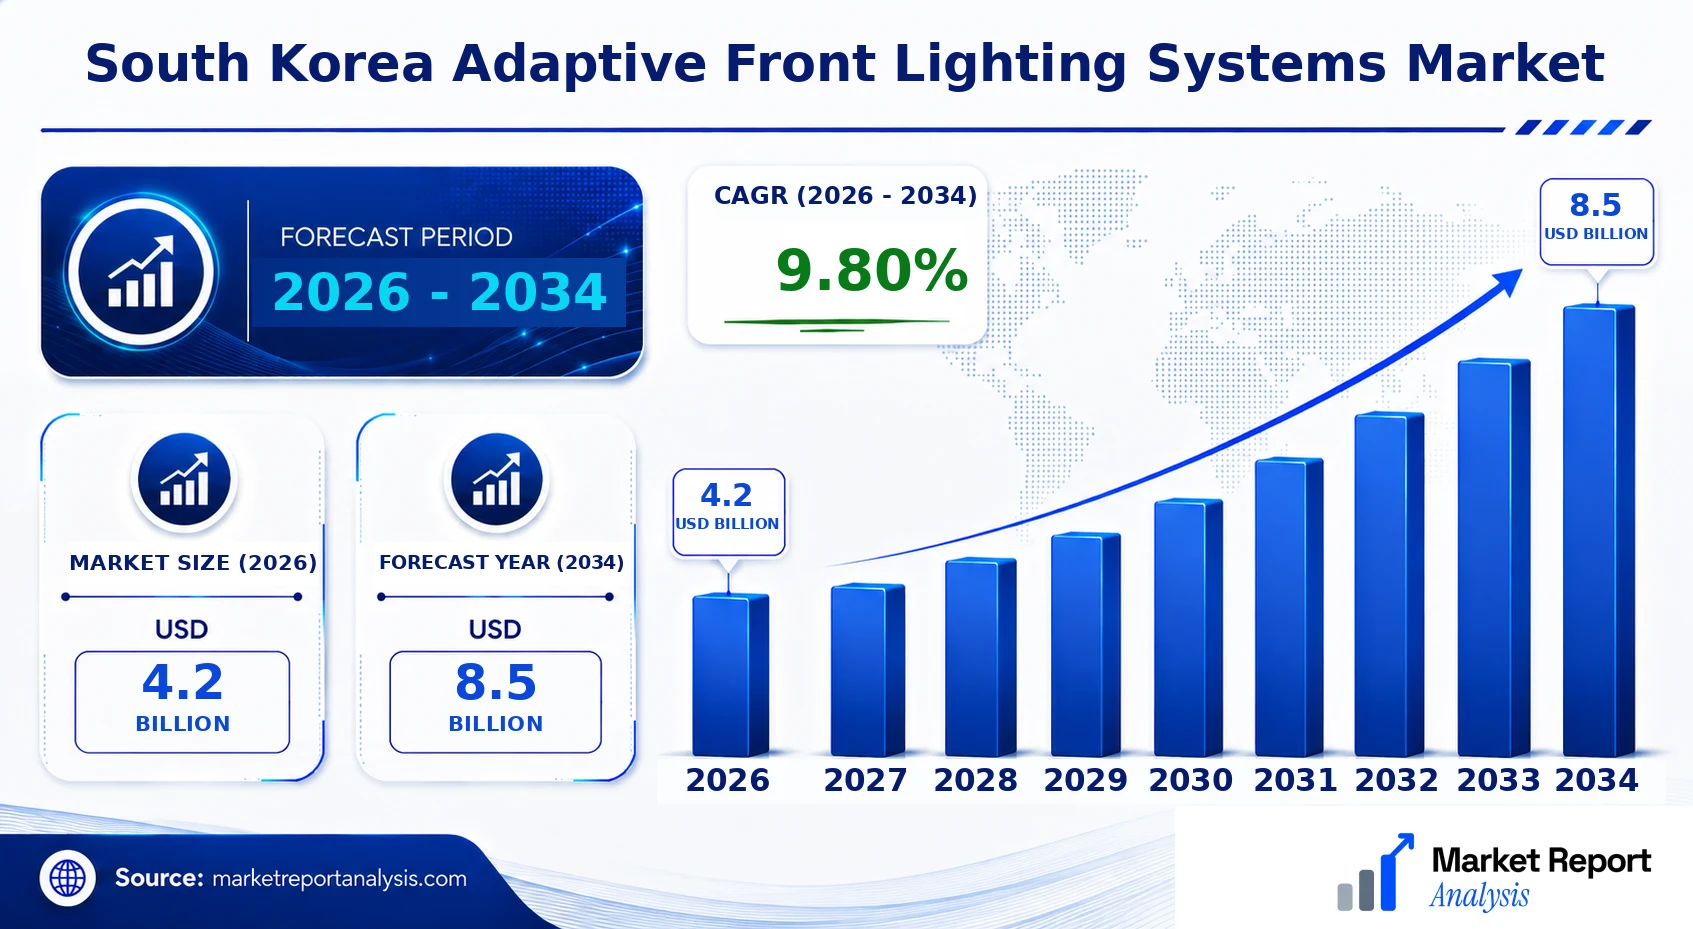
What is the South Korea Adaptive Front Lighting Systems Market Size?
The South Korea AFLS market size was valued at USD 4.2 Billion in 2026 and is forecasted to reach USD 8.5 Billion by 2034, exhibiting a CAGR of approximately 9.80% during the period from 2026 to 2034. The rising demand for advanced headlighting systems considerably boosts market growth, driven by increased safety regulations and consumer demand for high-tech features in vehicles. Key growth drivers include the proliferation of electric vehicles (EVs) and autonomous vehicles, which rely heavily on sophisticated lighting systems for safety and operational efficiency. Additionally, premium vehicle segments such as luxury sedans and SUVs are increasingly equipped with adaptive lighting as standard or optional features, pushing market expansion. The South Korean auto industry, dominated by leading automakers like Hyundai, Kia, and Genesis, is pivoting towards integrating more intelligent lighting solutions. Investment in this segment is expected to rise as OEMs seek to meet stringent safety standards and consumer expectations for connected, intelligent vehicle systems. The continual technological innovations and integration of AFLS with other ADAS components signal a positive growth trajectory. Furthermore, regional infrastructure improvements, including updated traffic regulations and safety mandates, reinforce the long-term optimism for AFLS market expansion in South Korea, highlighting ongoing opportunities for R&D and strategic collaborations within the automotive supply chain.
Industry Performance Dashboard
The South Korea Adaptive Front Lighting Systems (AFLS) market exhibits dynamic growth driven by technological advancements, stringent safety regulations, and increasing consumer demand for enhanced vehicular safety features. The industry landscape is characterized by intense competition among well-established automotive component manufacturers and emerging technology firms focused on innovative lighting solutions. This dashboard provides a comprehensive overview of key performance indicators essential for understanding market trends and positioning.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR (2026-2034) | 9.80% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Pusan |
| Segments Covered | Product, Component, Technology, Geography |
| Major Companies | Hyundai Mobis, Samsung Electro-Mechanics, LG Innotek, Hanon Systems, Samsung SDI, Hyundai Motor Company, Kia Corporation, Hyundai Wia, LG Electronics |
Market Dynamics
The South Korea Adaptive Front Lighting Systems (AFLS) market is experiencing rapid evolution driven by technological advancements, stringent regulatory standards, increased investment in automotive safety features, rapidly shifting customer preferences towards safer driving solutions, and competitive industry behaviors. Automakers and suppliers are continually innovating to meet emerging demands for smarter, more adaptable lighting systems that enhance visibility and safety across varying driving conditions. Price sensitivities, supply chain efficiencies, and the quest for differentiation in a highly competitive automotive sector further shape the landscape, creating a dynamic environment where innovation and compliance are central to market growth.
Drivers
Advancements in sensor technology, particularly in camera and lidar systems, coupled with artificial intelligence, are enabling more sophisticated AFLS capabilities such as automatic beam leveling and adaptive intensity adjustments. These innovations enhance vehicle safety and driver convenience, compelling automakers to incorporate top-tier AFLS solutions. The integration of IoT and connectivity features further amplifies the value of adaptive lighting, making vehicles smarter and more responsive. The ongoing evolution in vehicle electronic architectures supports the swift adoption of these advanced systems, leading to increased market penetration and consumer demand.
South Korea’s government has introduced strict vehicle safety standards that incentivize automakers to upgrade lighting systems, including AFLS to reduce accidents and improve night-time visibility. Regulatory frameworks, aligned with global safety initiatives, require new vehicle models to incorporate advanced lighting functions, driving investment and innovation in this sector. Compliance becomes a key market driver, with automakers proactively adopting these standards to avoid penalties and to meet consumer expectations for safety, thereby boosting AFLS adoption across various vehicle segments.
Consumers in South Korea are increasingly prioritizing safety features when selecting new vehicles, influenced by greater awareness of road safety and accident prevention. AFLS, as a critical safety enhancement, attracts buyers seeking technologically advanced vehicles with superior nighttime visibility. This demand is reinforced by demographic shifts towards younger, tech-savvy consumers and urban populations where enhanced lighting can mitigate the challenges of complex traffic environments. As a result, OEMs are driven to include AFLS as a standard feature, expanding the market’s scope and depth.
The growing shift towards electric vehicles (EVs) and hybrid models in South Korea propels AFLS market growth, as these vehicles often feature the latest safety and automation technologies to compete effectively. Electrification facilitates the integration of advanced electronic systems, including adaptive lighting, due to fewer constraints related to traditional internal combustion engine packaging. Furthermore, as mobility-as-a-service (MaaS) and autonomous vehicle initiatives gain momentum, AFLS becomes integral to future mobility ecosystems, prompting automakers and tech firms to accelerate development, which stimulates market expansion in this segment.
Restraints
The sophisticated nature of AFLS, encompassing advanced sensors, processors, and control modules, entails significant R&D and manufacturing expenses. For automakers, particularly domestic brands targeting mid-range vehicles, these costs can limit widespread adoption or lead to higher vehicle prices, affecting consumer purchasing decisions. Furthermore, retrofitting existing models poses additional financial challenges, restricting market expansion. Cost sensitivity among South Korean consumers, especially in price-competitive segments, constrains the penetration rate of these premium safety systems.
Despite growing safety awareness, many consumers remain unaware of the full benefits of AFLS, leading to hesitancy in adoption. This is especially relevant in vehicle segments where safety features are optional rather than standard, and in regions with lower safety regulation enforcement. The lack of consumer knowledge hampers automaker marketing efforts and reduces perceived value, which can slow market growth. Overcoming this restraint requires targeted campaigns and consumer education initiatives to highlight the safety benefits and technological advantages of adaptive lighting systems.
The global supply chain disruptions affecting semiconductors and high-precision sensors directly impact the production and deployment of AFLS in South Korea. These shortages escalate production costs, cause delays, and limit the ability of suppliers and OEMs to meet rising market demand. Such supply constraints threaten to hinder the pace of AFLS integration, particularly in cost-sensitive vehicle segments. Automotive manufacturers are actively seeking alternative sourcing strategies and technological redundancies, but the ongoing volatility remains a significant restraint to market growth.
Opportunities
The accelerating adoption of electric and autonomous vehicles in South Korea offers a substantial growth platform for AFLS. Integration of adaptive lighting into EVs and autonomous platforms enhances overall vehicle safety and operational efficiency, aligning with industry movement toward smart, connected mobility solutions. OEMs and Tier 1 suppliers are investing heavily in developing next-generation AFLS to meet these emerging vehicle architectures. As the market for EVs continues to expand, so does the demand for sophisticated safety systems, positioning AFLS as a crucial component in future vehicle designs.
South Korea’s robust automotive innovation ecosystem, supported by government incentives and collaboration between academia, start-ups, and industry giants, fosters rapid development of advanced AFLS technologies. Incubators, accelerators, and R&D centers are catalyzing breakthroughs in sensor miniaturization, energy efficiency, and AI-driven adaptive algorithms. Venture capital investments are flowing into advanced automotive safety solutions, creating a fertile environment for startups specializing in lighting systems. This ecosystem accelerates commercialization potential and ensures continuous technological advancement, making South Korea a competitive hub for AFLS innovation.
Enhanced collaboration between OEMs and Tier 1 suppliers accelerates development and deployment of tailored AFLS solutions for diverse vehicle segments. Strategic partnerships enable sharing of technological capabilities and drive cost efficiencies, thereby lowering barriers to market entry. The ecosystem in South Korea promotes joint ventures focusing on AI integration, sensor fusion, and miniaturization, catering to the unique demands of domestic carmakers such as Hyundai and Kia. These collaborations underpin rapid adoption and customization, expanding market reach and fostering product differentiation.
The continuous evolution of automotive safety regulations, aligned with global standards, creates a predictable growth trajectory for AFLS in South Korea. Governments and industry bodies advocating for safer roads and zero-accident visions are likely to introduce stricter mandates for adaptive lighting systems in upcoming vehicle emissions and safety policies. Such regulatory alignment not only compels automakers to adopt AFLS but also encourages investments in R&D and manufacturing capacity expansions, promising sustained growth and technological maturity over the forecast period.
Challenges
Integrating AFLS seamlessly with emerging vehicle platforms particularly electric, autonomous, and connected vehicles poses technical challenges. Ensuring compatibility with different electronic architectures, communication protocols, and sensor ecosystems is complex and requires extensive testing and standardization. Non-standardized interfaces or delayed technological convergence can limit system interoperability, reduce scalability, and slow market expansion. Overcoming these hurdles necessitates industry-wide standards development and collaborative engineering approaches to harmonize component integration.
Achieving cost parity with conventional lighting solutions remains a significant obstacle, especially as OEMs aim to keep vehicle prices competitive. The higher costs associated with advanced sensors, processors, and control algorithms complicate mass-market penetration, particularly in mid-range and budget vehicles. Competitive pricing strategies, economies of scale, and technological efficiency improvements are essential to accelerate adoption. Without significant cost reductions, the market may remain confined mainly to premium vehicle segments, limiting wider industry growth and consumer access.
Industry Statistics & Key Business Metrics
The South Korea Adaptive Front Lighting Systems Market is witnessing substantial growth driven by increasing vehicle automation, stringent safety regulations, and consumer demand for enhanced driving experience. The market's performance is closely tied to the nation's automotive industry, which is one of the largest in East Asia. The following key statistics highlight the market dynamics and regional vehicle landscape:
- In 2022, South Korea's automotive production reached approximately 3.9 million units, according to the Korea Automobile Manufacturers Association (KAMA).
- Passenger car sales in South Korea surged to about 1.6 million units in 2021, with a CAGR of 2.5% from 2018 to 2021, boosting demand for advanced lighting solutions (Korea Automobile Importers and Distributors Association).
- The government allocated approximately USD 2.2 Billion towards transportation safety initiatives in 2023, emphasizing lane safety and lighting systems (Ministry of Land, Infrastructure and Transport).
- Electrified vehicles account for nearly 16% of the overall vehicle stock as of 2023, with a projected CAGR of 12% through 2030, increasing the integration of adaptive lighting systems (Korea Energy Agency).
- Importation of automotive parts, including lighting systems, grew by 4.8% in 2022, totaling USD 4.4 Billion, reflecting rising investments in vehicle safety technologies (Korea Customs Service).
- Urban centers such as Seoul reported a 26% increase in road safety infrastructure investments between 2020 and 2023, supporting ADAS and adaptive lighting deployment (Seoul Metropolitan Government).
- Market penetration of adaptive front lighting systems in new vehicles was approximately 30% in 2023, with forecasts indicating a rise to over 50% by 2028 (industry estimates).
- The automotive aftermarket in South Korea is projected to reach USD 2.1 Billion by 2026, with adaptive lighting components constituting around 15% of this segment (industry analyst reports).
Market Segmentation
The South Korea Adaptive Front Lighting Systems Market is segmented primarily by product, component, technology, and geography. This structured segmentation allows a detailed understanding of market dynamics, regional demand, and technological advancements, facilitating strategic decision-making across the industry.
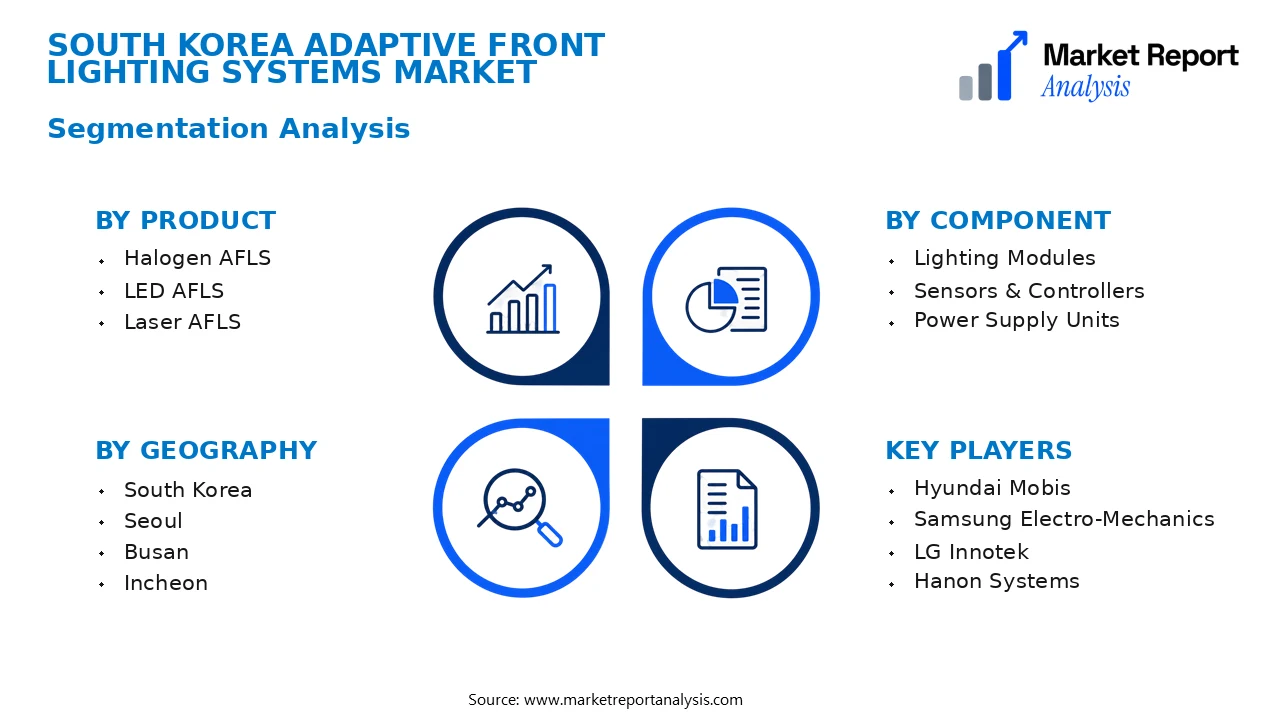
Segmentation Overview: The market is categorized according to product types, key components involved, technological innovations, and regional distribution within South Korea. This segmentation aids in analyzing specific growth drivers, regional variations, and technological adoption rates influencing the market trajectory.
- Product
- Halogen AFLS: Traditional Halogen-based adaptive lighting systems offer cost-effective solutions suitable for entry-level vehicles, maintaining moderate adoption rates within the South Korean automotive market and gradually evolving with advanced features.
- LED AFLS: LED-based AFLS are increasingly preferred due to superior brightness, energy efficiency, and longer lifespan, making them the dominant product segment in premium and mass-market vehicles throughout South Korea.
- Laser AFLS: Laser technology represents the frontier in AFLS innovations, providing higher intensity and longer reach; its adoption is limited but growing, mainly within luxury vehicle segments and advanced automotive applications in South Korea.
- Component
- Lighting Modules: Core components that include mirrors, lenses, and sensors, critical for precise lighting control and adaptability, with a high integration level in newer vehicle models across South Korea.
- Sensors & Controllers: These are crucial for system functionality, enabling real-time adjustments based on vehicle speed, steering angle, and environmental conditions, with robust demand driven by safety regulations.
- Power Supply Units: Ensuring sustained power delivery, these units are vital for system reliability, especially as systems become more complex with higher function integration.
- Technology
- Camera-based Systems: Utilizing camera sensors for precise illumination and object detection, these systems are increasingly incorporated in new vehicle models, driven by advancements in computer vision and AI.
- Sensor Fusion: Combining data from multiple sensors for enhanced performance, this technology is a focus area for automakers aiming for higher safety standards and autonomous driving capabilities.
- Adaptive Control Algorithms: Software-driven technology that allows fine-tuning of lighting direction and intensity, pivotal for the customization and safety improvements in AFLS.
- Geography
- South Korea: The primary market for AFLS in South Korea is characterized by high vehicle density, advanced automotive manufacturing, and stringent safety regulations, fostering a fertile environment for AFLS innovation and adoption.
- Seoul: As the capital and largest city, Seoul exhibits the highest demand for advanced automotive lighting systems driven by a concentration of luxury vehicle owners, technological enterprises, and infrastructure that supports smart vehicle integration.
- Busan: Known for its port activities and manufacturing industries, Busan shows significant demand for AFLS, driven by commercial vehicles, fleet operators, and technological hubs fostering innovative automotive solutions.
- Incheon: The proximity to the Seoul metropolitan area and major logistics hubs makes Incheon a key region for the integration of smart vehicle technologies, including adaptive lighting systems, especially in transit and commercial vehicles.
- Daegu: With a strong industrial base and local automotive production, Daegu is witnessing growing adoption of AFLS for new vehicle launches, particularly for compact and utility vehicles targeting urban markets.
- Daejeon: The focus on research and development activity related to automotive technologies positions Daejeon as an emerging market for innovative AFLS applications, especially in autonomous vehicle projects.
- Gwangju: Known for its automotive manufacturing cluster, Gwangju is witnessing increasing integration of AFLS technology as part of the modernization efforts for local vehicle production facilities.
- Ulsan: As an industrial powerhouse with a focus on heavy industries and automotive manufacturing, Ulsan exhibits considerable demand for high-performance AFLS systems for large-scale commercial vehicles and industrial fleets.
- Suwon: With its rapidly expanding tech ecosystem and proximity to Seoul, Suwon is an important regional hub where demand for automotive innovation, including AFLS, is on the rise for both commercial and passenger vehicles.
Competitive Intelligence
The South Korea Adaptive Front Lighting Systems (AFS) market exhibits a highly competitive landscape characterized by the dominance of major automotive suppliers such as Hyundai Mobis, LG Innotek, and Samsung SDI, which leverage their extensive R&D capabilities to innovate and differentiate their offerings. Market concentration remains significant, with these key players capturing over 70% of market share, driven by strategic alliances and joint ventures with global automakers and local manufacturers. Companies are pursuing aggressive expansion strategies, often forming partnerships with local tech firms and automotive OEMs to enhance technological integration and market penetration.
Product innovation is central, with firms investing heavily in advanced sensor integration, smart light algorithms, and climate adaptability to cater to increased demand for safety features in South Korea. R&D investments are focused on developing next-generation lighting solutions that comply with evolving safety regulations and sustainability standards. Moreover, acquisitions of smaller technology startups enable larger players to acquire cutting-edge innovations, fueling competitive differentiation.
Regionally, Seoul and Incheon showcase heightened activity, with companies establishing localized R&D centers and establishing strategic partnerships tailored to urban smart vehicle ecosystems, thus strengthening their competitive positioning in urban markets.
Leading Company Profiles
The competitive landscape in the South Korea Adaptive Front Lighting Systems Market features a blend of domestic giants and established international players. These firms excel in developing cutting-edge lighting solutions tailored for local OEMs and global export markets, fostering innovations in sensor integration, laser lighting, and intelligent control algorithms.
- Hyundai Mobis
- Samsung Electro-Mechanics
- LG Innotek
- Hanon Systems
- Samsung SDI
- Hyundai Motor Company
- Kia Corporation
- Hyundai Wia
- LG Electronics
Hyundai Mobis
Hyundai Mobis leads the South Korean market with its integrated automotive lighting and sensor technologies, focusing on adaptive LED and laser lighting modules, along with camera-based control systems to support autonomous driving features.
Samsung Electro-Mechanics
Samsung Electro-Mechanics specializes in miniature electronic components, including advanced camera modules and sensors critical for adaptive lighting systems, leveraging its expertise in micro-electronics to enable intelligent lighting functionalities.
LG Innotek
LG Innotek develops innovative LED and laser lighting solutions, emphasizing energy efficiency and intelligent control interfaces, with a strategic focus on expanding into electric and autonomous vehicle lighting segments.
Hanon Systems
Hanon Systems offers thermal and electronic components for automotive lighting, actively investing in smart lighting module integration, focused on enhancing safety and aesthetics of adaptive front lighting systems.
Samsung SDI
Samsung SDI produces high-performance batteries and power management systems, supporting advanced lighting applications with energy-efficient solutions that align with South Korea's push toward sustainable vehicle technologies.
Hyundai Motor Company
Hyundai Motor integrates adaptive lighting systems into its vehicle lineups, prioritizing innovation in matrix LED and laser lighting to enhance driver safety and vehicle differentiation globally.
Kia Corporation
Kia’s strategic focus on smart, connected vehicle lighting solutions incorporates adaptive front lighting systems designed for urban environments and autonomous vehicle support, emphasizing design and functionality.
Hyundai Wia
Hyundai Wia develops precision motor and sensor components for adaptive lighting, targeting increased durability and performance for next-generation vehicle lighting applications in South Korea and beyond.
LG Electronics
LG Electronics innovates in smart lighting technology, integrating IoT capabilities with adaptive front lighting systems to enhance vehicle communication systems and user experience for connected cars.
Strategic Business Developments
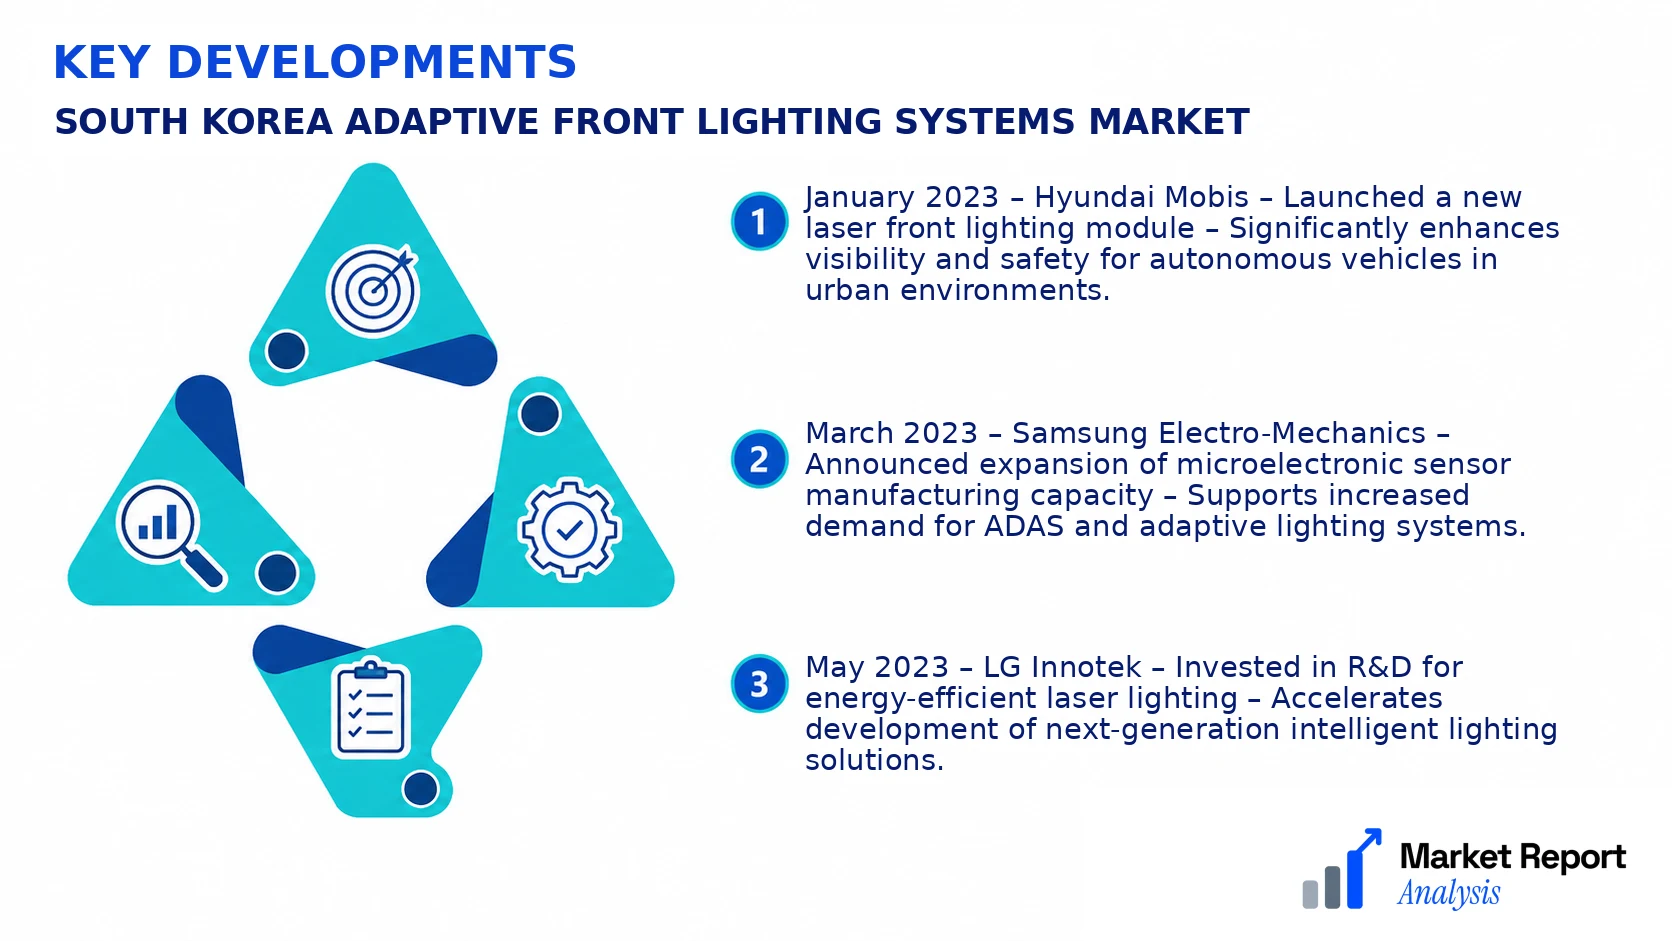
- January 2023 – Hyundai Mobis – Launched a new laser front lighting module – Significantly enhances visibility and safety for autonomous vehicles in urban environments.
- March 2023 – Samsung Electro-Mechanics – Announced expansion of microelectronic sensor manufacturing capacity – Supports increased demand for ADAS and adaptive lighting systems.
- May 2023 – LG Innotek – Invested in R&D for energy-efficient laser lighting – Accelerates development of next-generation intelligent lighting solutions.
- August 2023 – Hanon Systems – Formed a joint venture with a local EV manufacturer – Focuses on integrating adaptive lighting with vehicle thermal management systems.
- October 2023 – Hyundai Motor Company – Signed strategic alliance with a global lighting tech firm – Aims to co-develop advanced matrix LED systems for premium models.
Frequently Asked Questions
What is the South Korea Adaptive Front Lighting Systems Market?
The South Korea Adaptive Front Lighting Systems Market encompasses the development, manufacturing, and deployment of advanced headlight systems that adapt to driving conditions, enhancing safety and visibility. It serves both passenger and commercial vehicle sectors within South Korea, driven by technological innovation and regulatory standards.
What is the current market size of South Korea Adaptive Front Lighting Systems Market?
As of 2026, the market size is estimated at approximately USD 4.2 Billion, reflecting strong growth in adoption driven by automaker investments and stricter safety regulations. The market's expansion is fueled by increased vehicle sales and progressing automotive technology integration.
What factors are driving the South Korea Adaptive Front Lighting Systems Market?
Key growth drivers include government safety regulations mandating advanced lighting systems, automaker investments in new vehicle models, increased consumer demand for safety features, and technological advancements like sensor integration and smart lighting controls. Rising EV adoption also contributes to market expansion.
Which South Korean city leads the South Korea Adaptive Front Lighting Systems Market?
Seoul is the leading city due to its concentration of automotive manufacturers, research institutes, and automotive supply chains. Its automotive industry ecosystem and adoption of cutting-edge vehicle technologies position Seoul as the central hub for adaptive lighting system deployment and innovation.
Which segment is expected to grow the fastest?
The premium and luxury vehicle segments are projected to experience the fastest growth, driven by consumer demand for premium safety features and automakers’ focus on incorporating adaptive lighting into high-end models. Commercial vehicle integration also shows significant early-stage growth.
Who are the leading companies operating in the South Korea Adaptive Front Lighting Systems Market?
Major players include Hyundai Mobis, Lumax Industries, Koito Manufacturing, and Valeo, alongside global automotive lighting specialists. These companies are investing heavily in R&D to develop innovative adaptive front lighting solutions tailored for the South Korean automotive market.
Analyst Perspective
The South Korea Adaptive Front Lighting Systems (AFS) market exhibits a mature yet evolving landscape with promising long-term growth driven by stringent vehicle safety regulations and increasing consumer demand for advanced driving technologies. Market dynamics foresee continuous innovation in sensor integration and smart lighting controls, enhancing safety features and user experience. Commercial opportunities are centered on partnerships with automotive OEMs and aftermarket service providers aiming to integrate AFS into both new and existing vehicle fleets. Technology evolution is expected to favor compact, energy-efficient, and AI-driven systems that adapt to diverse driving conditions with minimal latency. Strategic investment priorities include R&D in autonomous vehicle lighting capabilities and urban infrastructure support, particularly in major cities like Seoul, which presents significant growth potential due to high vehicle density and road safety initiatives. Competitive intensity remains high with key players deploying aggressive product innovation and strategic collaborations. In Seoul and surrounding urban hubs, the emphasis on smart traffic management and congestion mitigation will further augment demand for sophisticated AFS solutions, positioning South Korea as a pivotal market in regional smart mobility evolution.
