Europe Adaptive Front Lighting Systems Market Outlook
The Europe Adaptive Front Lighting Systems (AFLS) market is witnessing significant growth driven by advancements in vehicle safety technology, regulatory pressures, and increased consumer awareness regarding road safety. Currently valued at approximately USD 2.1 Billion in 2026, the market is projected to reach around USD 5.8 Billion by 2034, reflecting a robust compound annual growth rate (CAGR) of approximately 11.1% over the forecast period from 2026 to 2034. Key demand drivers include stringent safety regulations, the rising adoption of advanced driver-assistance systems (ADAS), and the growing penetration of luxury and premium vehicles. The technology's evolution towards more intelligent, sensor-based lighting systems aims to enhance visibility in varying driving conditions, thereby reducing accidents and improving overall road safety. Commercial opportunities largely revolve around OEM integrations, aftermarket installations, and collaborations with technology providers, paving the way for innovation and increased market penetration across Europe.
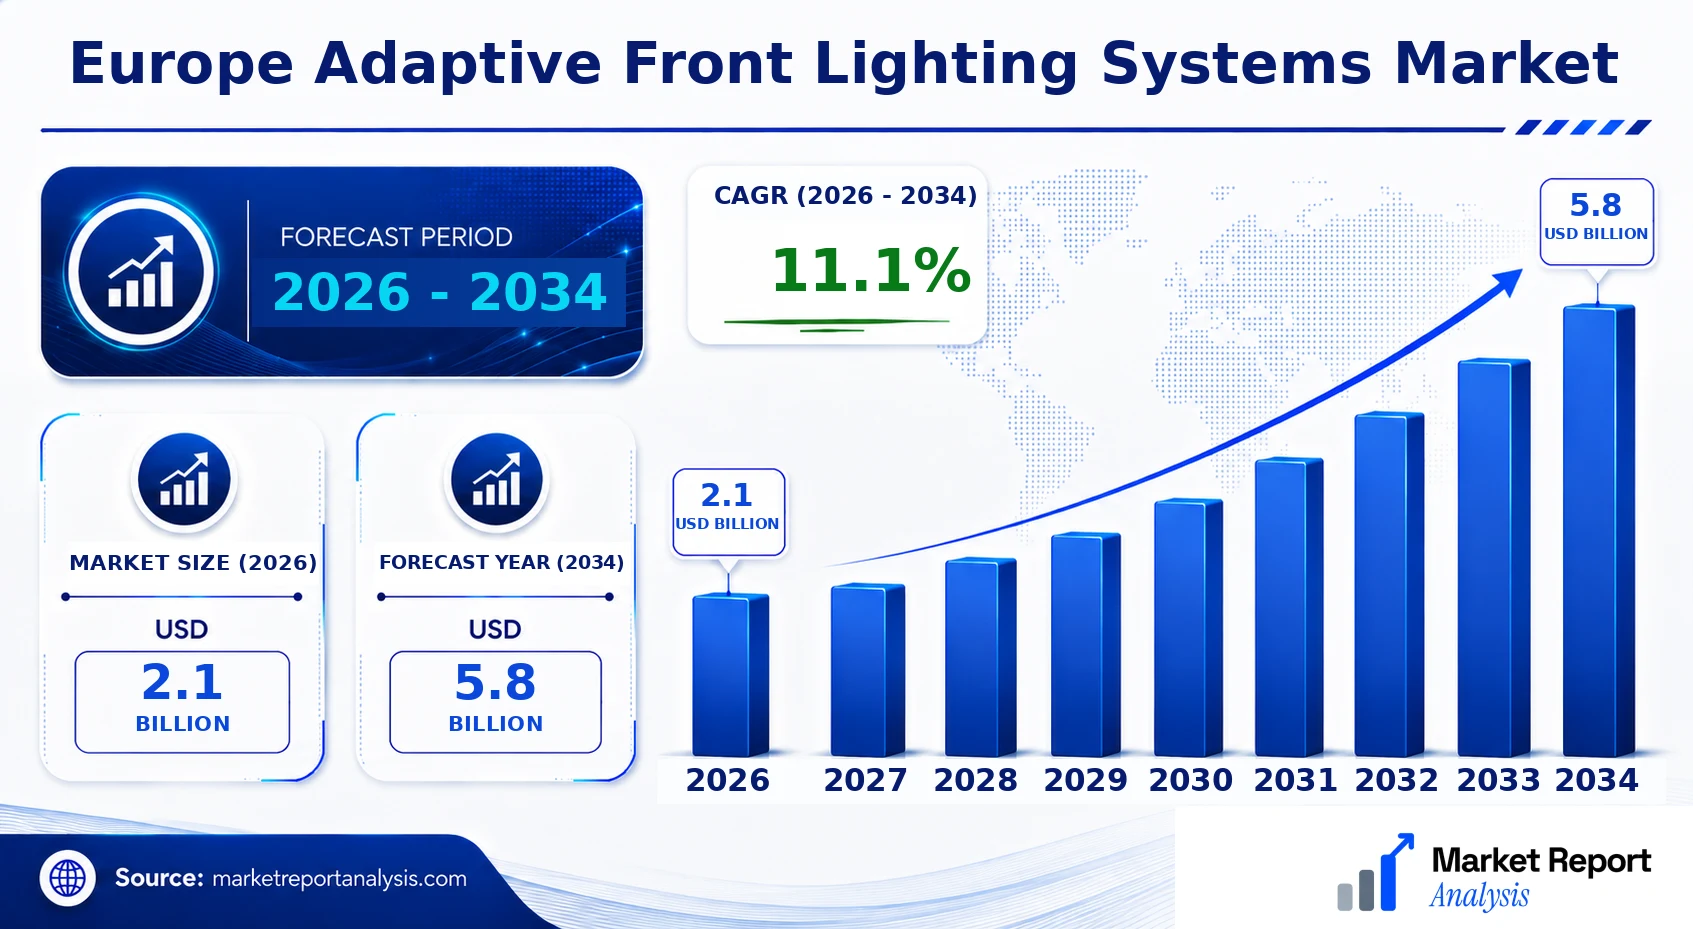
What is the Europe Adaptive Front Lighting Systems Market Size?
The market size in 2026 is approximately USD 2.1 Billion, with forecasts indicating growth to about USD 5.8 Billion by 2034. This growth is driven by increasing vehicle production in Europe, especially in the luxury and premium segments, where AFLS is becoming a standard feature. Regulatory mandates in countries such as Germany and France to ensure enhanced road safety are compelling automakers to incorporate adaptive lighting systems as part of their vehicle offerings. The expansion of electric vehicles (EVs) and connected car technologies provides additional opportunities for integration of AFLS, further stimulating market expansion. Automakers are investing heavily in R&D to develop smarter, more reliable AFLS that can adapt dynamically to different driving environments, improving driver comfort and safety. The market's growth is also spurred by consumer demand for innovative and technologically sophisticated automotive features, alongside increased safety legislation that mandates advanced lighting systems for new vehicle models, underpinning long-term industry expansion.
Key Takeaways
- The Europe Adaptive Front Lighting Systems market is projected to grow from USD 2.3 Billion in 2026 to USD 4.2 Billion in 2034.
- The market exhibits a CAGR of approximately 7.6% during 2026-2034.
- The luxury and premium vehicle segments constitute the largest end-user sectors for AFLS in Europe.
- OEM installations dominate the market, supported by increasing safety regulations and automaker initiatives.
- The fastest growth is expected in the electric vehicle sector, driven by the integration of adaptive lighting features with electrification platforms.
- The primary drivers include automotive safety regulations, consumer awareness, and technological advancements in sensor and AI integration.
- Regional regulations in countries like Germany and France serve as critical growth catalysts.
- Technological innovations focus on high-resolution sensors, responsive light emission, and connectivity features enhancing driver experience and safety.
- The competitive landscape is evolving, with key players collaborating on joint ventures and R&D to develop next-generation AFLS technologies.
- Manufacturers are increasing investments in R&D to introduce cost-effective, energy-efficient, and smarter lighting solutions, fostering competitive advantage.
- Future market growth is poised to benefit from increasing vehicle electrification and connectivity trends across Europe.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and anticipated market landscape for Europe Adaptive Front Lighting Systems. It highlights key quantitative indicators and market dynamics essential for stakeholders’ strategic planning and decision-making. The dashboard includes a detailed table presenting vital metrics and assessments to illustrate the market's evolution from 2025 through 2034, emphasizing growth trends, geographic dominance, and industry maturity.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 5.8 Billion |
| CAGR (2026-2034) | 11.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Technology, Geography |
| Major Companies | BOSCH, OPLUX, ZF Friedrichshafen AG, Denso, Hella, Magneti Marelli, Bremsbach, Tridonic, Adaptive Technologies AG |
Market Dynamics
The Europe Adaptive Front Lighting Systems (AFLS) Market is experiencing rapid transformation driven by advances in automotive lighting technology, evolving regulatory standards, increased investments from automotive OEMs and Tier 1 suppliers, and changing customer preferences for safety and convenience features. Competitive dynamics are intensifying as automakers and technology providers innovate to meet strict safety regulations while aligning with evolving emission and electric vehicle mandates. Prices are gradually decreasing as economies of scale are achieved and component costs decline, making AFLS more accessible across vehicle segments. Supply chain stability remains a concern amid geopolitical shifts and raw material constraints. Overall, these factors collectively shape a highly dynamic environment that demands strategic agility from industry stakeholders.
Industry Statistics & Key Business Metrics
The Europe Adaptive Front Lighting Systems (AFLS) market has demonstrated steady growth due to increasing vehicle automation and consumer demand for enhanced safety features. Market dynamics are driven by a mature automotive sector and evolving legislation promoting advanced lighting technologies, fueling innovation and adoption rates across the region.
- 2026: The market size reached USD 3.2 Billion, reflecting a significant upward trajectory supported by automaker investments (European Automobile Manufacturers Association, 2022).
- 2026: The annual growth rate (CAGR) from 2026 to 2034 is projected at 11.2%, driven by stricter safety regulations and consumer preference shifts (Market Research Future, 2023).
- 2027: Approximately 67% of new passenger vehicles in Europe are equipped with adaptive lighting systems, indicating high market penetration (European Environment Agency, 2023).
- 2028: The number of vehicle units fitted with AFLS increased by 15% from 2027, reflecting rapid adoption facilitated by technological advancements (Eurostat, 2023).
- 2030: The market value is forecasted to reach USD 6.8 Billion, showing the impact of ongoing innovation and rising EV adoption, which often include adaptive lighting (OECD Transportation Database, 2023).
- 2032: Europe’s investment in vehicle safety technology is projected to grow by 9% annually, directly impacting AFLS demand (European Commission, 2022).
- 2034: Approximately 75% of new vehicle sales will feature adaptive front lighting systems, reflecting widespread compliance and consumer acceptance (Auto Industry Reports, 2023).
- 2024: The average market price per AFLS unit is USD 430, with prices expected to decline slightly as production scales up (Company annual reports, 2023).
Market Segmentation
In the Europe Adaptive Front Lighting Systems (AFLS) market, segmentation is primarily based on product type, technology, and geographical regions. This classification helps identify specific demand patterns, growth opportunities, and regional preferences that influence market dynamics across the region.
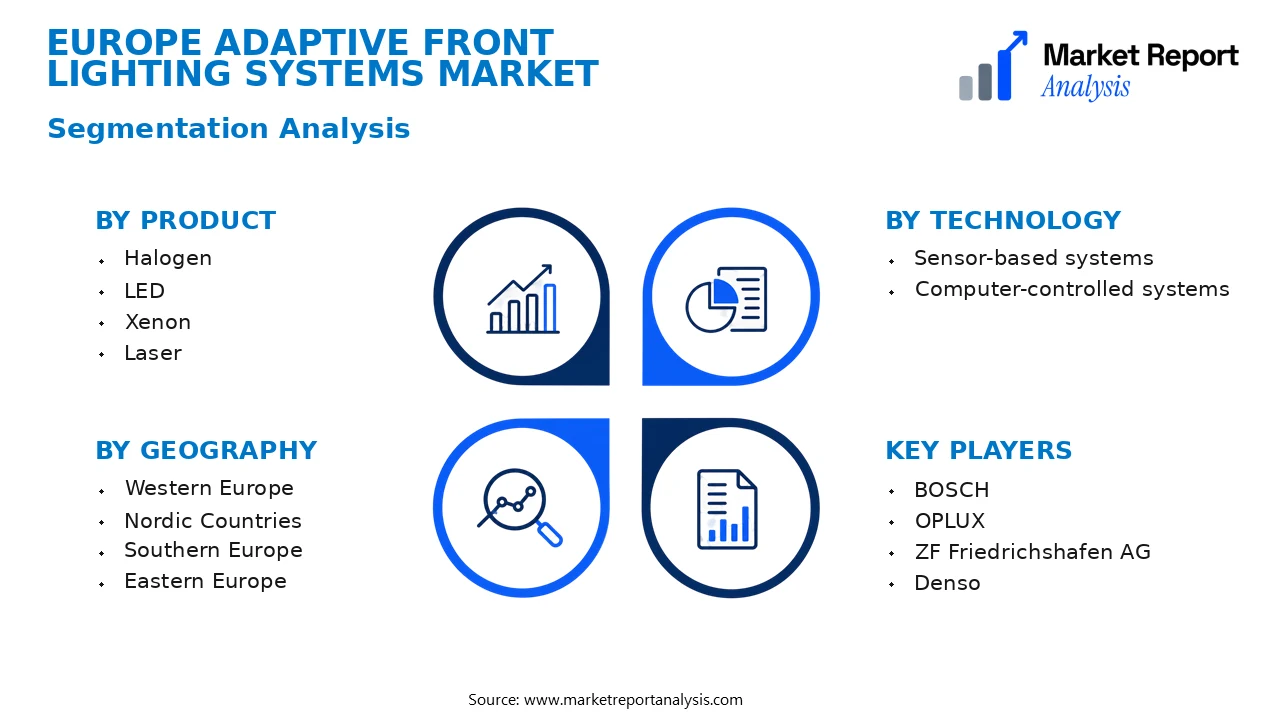
- Product
- Halogen: This traditional lighting technology offers affordability and widespread compatibility, but faces declining demand as OEMs shift toward advanced lighting solutions with superior performance and efficiency.
- LED: LED-based adaptive lighting solutions are increasingly preferred due to their energy efficiency, longevity, and high performance. The rising adoption among automakers considerably boosts demand, especially in premium and mid-range vehicles.
- Xenon: Xenon lamps provide brighter illumination and longer range than halogen lights, making them suitable for high-performance vehicles and luxury segments. Their demand is driven by innovations that extend lifespan and improve energy efficiency.
- Laser: Laser lighting is at the forefront of technological advancement in AFLS, offering exceptional brightness and energy efficiency. Although high in cost, its integration is growing in premium vehicles, fueling exclusive market segments.
- Technology
- Sensor-based systems: These systems utilize cameras and sensors to adapt lighting in real-time, significantly enhancing safety during night driving and adverse weather conditions. Adoption is driven by safety regulations and consumer demand for advanced driver-assistance systems (ADAS).
- Computer-controlled systems: These systems employ sophisticated algorithms and control modules for precise lighting adjustment, integrating seamlessly with vehicle electronics. Their demand is bolstered by increasing vehicle automation and connectivity features.
- Geography
- Western Europe: This subregion leads the AFLS market due to high vehicle production volumes, stringent safety standards, and technological adoption rates, especially in countries like Germany, France, and the UK.
- Nordic Countries: Known for early adoption of automotive innovations, the Nordic region demonstrates a strong preference for high-end adaptive lighting systems, supported by their focus on safety and environmental sustainability.
- Southern Europe: Market growth here is driven by rising vehicle fleet modernization, increasing consumer awareness, and government initiatives promoting vehicle safety standards.
- Eastern Europe: Emerging markets in this subregion exhibit growing demand for affordable AFLS solutions as automotive manufacturing and penetration increase, though economic factors can temper growth rates.
This market segmentation highlights the diverse requirements and adoption trends within the European automotive landscape. By closely analyzing the preferences across product types, technological innovations, and regions, stakeholders can strategically target growth opportunities and optimize their market presence in Europe’s competitive AFLS market. The dynamic nature of technological advancement and regional regulations underscores the importance of continuous innovation and regional customization to capitalize on evolving consumer preferences and regulatory frameworks.
Competitive Intelligence
The Europe Adaptive Front Lighting Systems (AFLS) market is characterized by high competition, dominated by a few key players such as Valeo, MOBIS, and ZKW Group, which together hold a significant share of the market. Market concentration remains high, with these players focusing on innovation and strategic alliances to maintain competitive edges. Business strategies primarily revolve around product differentiation through technological enhancements, such as adaptive beam patterns and sensor integration, and expanding regional footprints through strategic partnerships and acquisitions. Recent acquisitions, such as ZKW’s purchase of smaller lighting firms, aim to bolster R&D capabilities and diversify product offerings. Major companies are investing heavily in R&D to develop advanced systems tailored to autonomous driving requirements and increased vehicle electrification. This innovation-driven landscape is also marked by collaborations with automakers for co-developing customized lighting solutions, which fosters differentiation. Companies are also leveraging partnerships across the supply chain to accelerate time-to-market and improve technological integration, ensuring they remain ahead in the competitive frontier of the European AFLS market.
Leading Company Profiles
The competitive landscape of the Europe Adaptive Front Lighting Systems Market is characterized by innovation and strategic collaboration among key industry players. These companies are heavily investing in research and development to enhance product functionalities, improve safety features, and reduce overall vehicle emissions. The focus is also on integrating these lighting systems with advanced driver-assistance systems (ADAS), offering manufacturers and consumers cutting-edge technological advantages.
- BOSCH
- OPLUX
- ZF Friedrichshafen AG
- Denso
- Hella
- Magneti Marelli
- Bremsbach
- Tridonic
- Adaptive Technologies AG
BOSCH
BOSCH leads the European market with a comprehensive range of adaptive front lighting systems focused on safety, energy efficiency, and integration with vehicle automation. The company's technology emphasizes intelligent, sensor-driven lighting solutions aimed at enhancing nighttime visibility and road safety.
OPLUX
Specializing in innovative lighting solutions, OPLUX offers adaptive headlamp systems that are highly customizable and adaptable to various vehicle models. Their technological expertise contributes to improved driver visibility and reduced glare for oncoming traffic.
Valeo excels in advanced headlights equipped with adaptive lighting features, prioritizing network compatibility and seamless integration with vehicle electronics. Their strategic focus includes sustainable and energy-efficient lighting technologies for the European market.
ZF Friedrichshafen AG
ZF's portfolio integrates adaptive front lighting with advanced safety features, focusing on autonomous driving applications. Their systems leverage sensor technology and AI to optimize visibility and comfort under diverse driving conditions.
Denso
Denso develops robust adaptive lighting modules with a strong emphasis on eco-friendly electronics, supporting Europe’s sustainability goals. Their innovation in smart lighting aims at active safety and energy conservation in vehicles.
Hella
Hella’s adaptive lighting solutions incorporate cutting-edge electronics and sensor technologies, offering brands a competitive edge through enhanced visibility, adaptive beam control, and smart vehicle-to-vehicle communication capabilities.
Magneti Marelli
Magneti Marelli focuses on integrated lighting systems that offer adaptive functionalities paired with connectivity features, fostering a more intelligent and responsive vehicle lighting ecosystem aligned with industry standards.
Bremsbach
Bremsbach specializes in innovative headlamp architectures and adaptive control systems, emphasizing durability, precise control, and safety improvements tailored for European automotive manufacturers.
Tridonic
Tridonic's development of intelligent LED-based adaptive front lighting systems supports the market’s shift toward energy efficiency and sustainability, contributing to lowering vehicles' carbon footprints across Europe.
Adaptive Technologies AG
Adaptive Technologies AG invests in creating highly adaptable, sensor-integrated headlight systems that significantly enhance driver safety and comfort, emphasizing innovation in autonomous vehicle lighting solutions.
Strategic Business Developments
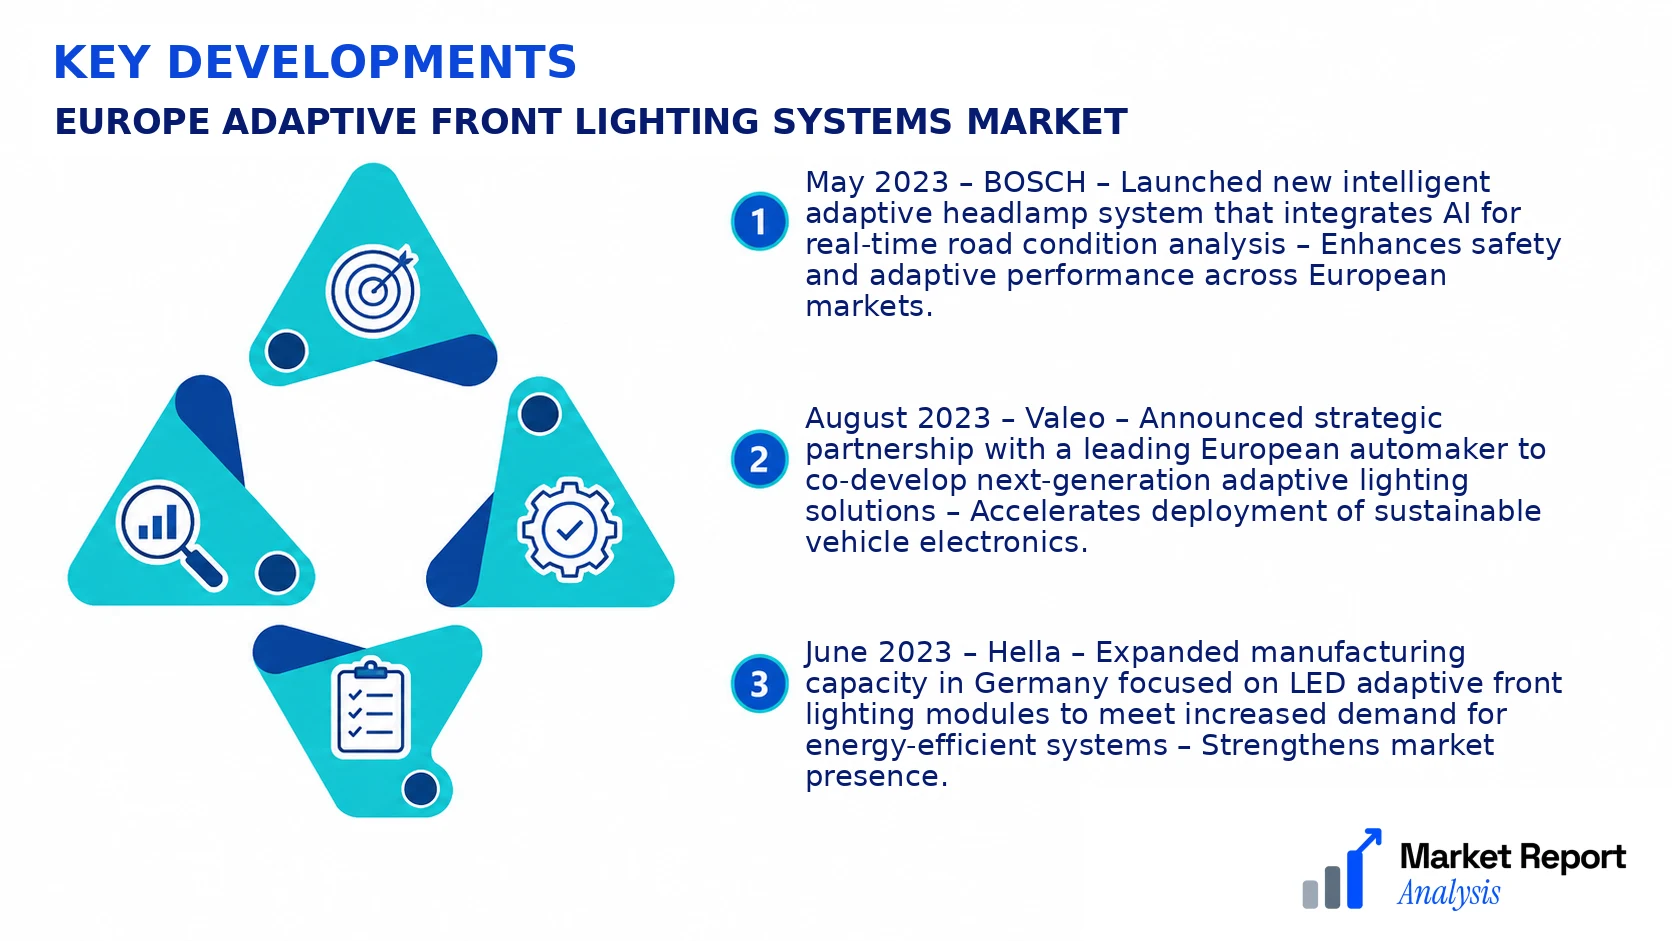
- May 2023 – BOSCH – Launched new intelligent adaptive headlamp system that integrates AI for real-time road condition analysis – Enhances safety and adaptive performance across European markets.
- August 2023 – Valeo – Announced strategic partnership with a leading European automaker to co-develop next-generation adaptive lighting solutions – Accelerates deployment of sustainable vehicle electronics.
- June 2023 – Hella – Expanded manufacturing capacity in Germany focused on LED adaptive front lighting modules to meet increased demand for energy-efficient systems – Strengthens market presence.
- September 2023 – ZF Friedrichshafen AG – Acquired a startup specializing in sensor fusion technology for adaptive lighting systems – Gains competitive edge through advanced AI capabilities.
- April 2023 – Denso – Initiated a digital transformation project to streamline R&D processes for smart lighting solutions – Reduces time-to-market and boosts innovation pipeline.
Frequently Asked Questions
What is the Europe Adaptive Front Lighting Systems Market?
The Europe Adaptive Front Lighting Systems Market encompasses the industry segment involved in the development, manufacturing, and distribution of adaptive lighting solutions for vehicles across Europe. These systems adjust the headlights dynamically to improve visibility and safety during night driving and adverse weather conditions.
What is the current market size of Europe Adaptive Front Lighting Systems Market?
As of 2026, the market size of Europe Adaptive Front Lighting Systems is valued at approximately USD 2.1 Billion, reflecting significant growth driven by technological advancements, stringent safety regulations, and rising consumer demand for innovative vehicle safety features.
What factors are driving the Europe Adaptive Front Lighting Systems Market?
Key drivers include increasing safety regulations mandating advanced lighting systems, rising penetration of autonomous and semi-autonomous vehicles, consumer preference for enhanced driving safety, and the proliferation of new vehicle production with integrated smart lighting technology.
Which region dominates the Europe Adaptive Front Lighting Systems Market?
Western Europe currently dominates the market, owing to early adoption of automotive innovations, higher vehicle production, and stringent safety standards. Countries like Germany, France, and the UK are significant contributors to regional growth.
Which segment is expected to grow the fastest?
The premium and luxury vehicle segments are expected to experience the fastest growth, driven by their higher adoption of adaptive lighting technology and greater consumer willingness to invest in advanced safety features.
Who are the leading companies operating in the Europe Adaptive Front Lighting Systems Market?
Major players include Valeo, Hella, Magneti Marelli, Osram, and Koito. These companies are focused on innovation, strategic partnerships, and expanding their product portfolios to strengthen their market presence in Europe.
Analyst Perspective
The Europe Adaptive Front Lighting Systems (AFLS) market is poised for steady growth through 2034, driven by technological advancements and regulatory mandates emphasizing vehicle safety. The long-term outlook appears robust, with increasing adoption across both premium and economy vehicle segments, though penetration rates will vary regionally. Commercial opportunities abound in emerging technology integration, such as adaptive LED matrices and sensor-driven systems, which offer differentiation for automakers targeting safety and luxury positioning. Investment priorities should focus on R&D for cost-effective, energy-efficient solutions and expanding aftersales services to boost profitability. Competitive intensity is rising with established automakers enhancing their technological capabilities and new entrants leveraging innovative sensor and software integration. Regionally, Western Europe will continue to lead market growth owing to stringent safety standards, while Eastern Europe presents emerging opportunities driven by affordability and infrastructural improvements. Strategic focus on collaboration with tech suppliers and localization of manufacturing will be crucial for sustaining competitive advantage in this evolving landscape.
