North America Micro Control Unit (MCU) Market Outlook
The 2026 market size is USD 12.5 Billion. The North America Micro Control Unit (MCU) market stands at a pivotal point, with its current valuation reaching approximately USD 35.2 Billion in 2026. Driven by the rising integration of IoT devices, increased adoption in automotive and industrial applications, and technological innovations focusing on energy efficiency and miniaturization, the market is poised for substantial growth. The forecast indicates a robust compound annual growth rate (CAGR) of around 11.1% from 2026 to 2034. This growth is fueled by the expanding use of MCUs in smart consumer electronics, autonomous vehicles, and sophisticated industrial automation systems. The commercial opportunities are vast, particularly in the development of ultra-low-power MCUs, security-enhanced modules, and integration-ready solutions that cater to North America's high standards for quality and safety.

What is the North America Micro Control Unit (MCU) Market Size?
The North America Micro Control Unit (MCU) Market size is estimated at a current-market value of USD 12.5 Billion in 2026 and is expected to reach approximately USD 35.2 Billion by 2034, expanding at a CAGR of 11.1% from 2026 to 2034. The growth drivers include technological advancements in connected and autonomous vehicle systems, increased demand for smart home and industrial automation, and the proliferation of IoT applications across various industries. End-use industries such as automotive, consumer electronics, industrial manufacturing, and healthcare are significant contributors to this expansion. The impact of cutting-edge technologies like machine learning, AI integration, and low-power consumption MCUs further supports the market’s upward trajectory. Future investment opportunities lie in developing more energy-efficient MCUs, enhancing cybersecurity features, and creating application-specific integrated circuits (ASICs) that address North America's stringent regulatory and safety standards, paving the way for sustained industry growth over the forecast period.
Key Takeaways
- The North America MCU market was valued at USD 12.5 Billion in 2026.
- It is projected to reach USD 21.3 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 7.2%.
- The automotive segment remains the largest application area.
- The consumer electronics segment is the fastest-growing application.
- Smart vehicles and industrial automation are the primary end users.
- Surge in IoT adoption is driving demand for low-power, high-performance MCUs.
- Investments in AI-enabled and security-focused MCUs are increasing.
- Major technological trends include miniaturization and energy efficiency.
- The competitive landscape features leading chip manufacturers partnering with tech firms.
- Regulatory standards are shaping product development and compliance strategies.
- High R&D expenditures are focused on innovative, application-specific solutions.
- Supply chain resilience and component sourcing are critical for market sustainability.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America Micro Control Unit (MCU) market's key performance indicators and market dynamics. This section offers a succinct snapshot of current market metrics, tracking growth patterns, competitive landscape, and technological developments that influence market trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.5 Billion |
| Market Value (2026) | USD 12.5 Billion |
| Forecast Size (2034) | USD 35.2 Billion |
| CAGR | 11.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Industry Vertical, Geography |
| Major Companies | Texas Instruments, STMicroelectronics, Microchip Technology, NXP Semiconductors, Analog Devices, Infineon Technologies, ON Semiconductor, Renesas Electronics, Maxim Integrated, Dialog Semiconductor |
Market Dynamics
The North American Micro Control Unit (MCU) Market is experiencing a dynamic transformation driven by rapid technological advancements, evolving regulatory frameworks, increased investments, shifting customer preferences, pricing strategies, supply chain conditions, and heightened competitive pressures. These factors collectively influence market growth, innovation trajectories, and strategic business decisions. As industries such as automotive, healthcare, consumer electronics, and industrial automation increasingly adopt MCUs for enhanced functionality, market participants must navigate complex regulatory landscapes, capitalize on technological innovations, and adapt to fluctuating supply and pricing environments. This multifaceted environment fosters a competitive yet opportunity-rich scenario for stakeholders aiming to solidify their market positions.
Drivers
Technological Advancements in Miniaturization and Efficiency
Continuous advancements in semiconductor fabrication technologies, such as smaller node processes, have significantly enhanced MCU capabilities, allowing for more powerful and energy-efficient devices. This progression supports the increasing demand for compact, high-performance MCUs in IoT devices, automotive systems, and wearable gadgets. For instance, as IoT applications expand in North America, the need for smaller, more energy-efficient MCUs that can operate with minimal power consumption becomes critical. Furthermore, innovations like integration of AI features directly onto MCUs are creating new avenues for development. The trend towards smarter and more autonomous devices fuels this growth, emphasizing the importance of technological evolution in maintaining competitiveness and meeting consumer demands.
Regulatory and Standards Developments
The evolving regulatory landscape, driven by safety, security, and environmental standards, plays a crucial role in shaping the North American MCU market. Initiatives such as stricter electromagnetic compatibility requirements and cybersecurity standards for connected devices require MCU manufacturers to incorporate advanced features that safeguard data and ensure reliability. Moreover, government policies promoting the adoption of green technologies and energy-efficient electronics influence design and production approaches. Companies investing in compliance and aligning products with these standards position themselves favorably within the market, sparking increased innovation in secure, eco-friendly MCUs tailored for regional specifications.
Growing Investment and R&D Activity
Venture capital, governmental grants, and corporate R&D budgets dedicated to semiconductor and embedded systems innovation continue to bolster the MCU ecosystem in North America. Major industry players and startups are investing heavily in developing next-generation MCUs with enhanced processing power, integrated security features, and specialized functions such as automotive-grade reliability and AI-optimized architectures. Notably, strategic alliances between chip designers and system integrators aim to accelerate deployment of cutting-edge MCU solutions. This robust investment landscape supports rapid technological maturation, accelerates product development timelines, and fosters competitive differentiation, ultimately driving market expansion.
Customer Demand for Connected and Autonomous Systems
The surge in customer demand for connected devices, autonomous vehicles, and smart infrastructure significantly propels the need for sophisticated MCUs capable of handling complex, real-time data processing. Automotive manufacturers in North America are increasingly integrating MCUs into advanced driver-assistance systems (ADAS) and electric vehicles (EVs), which require high-performance, reliable, and secure control units. Similarly, the proliferation of smart home appliances and industrial IoT platforms necessitates MCUs with enhanced connectivity and processing capabilities. This evolving demand pattern encourages innovation in MCU architectures and fosters competitive differentiation among market players seeking to capture the expanding ecosystem of connected solutions.
Restraints
Supply Chain Disruptions and Component Shortages
Global supply chain disruptions, exacerbated by geopolitical tensions and pandemic-related factory shutdowns, have led to significant shortages of critical semiconductor components, including MCUs. These shortages impact manufacturing timelines, increase costs, and constrain product availability for end markets such as automotive and consumer electronics. North American producers are particularly affected by dependency on Asian chip foundries and geopolitical constraints, resulting in delays and increased procurement expenses. To mitigate these impacts, companies are exploring local assembly, diversified supply chains, and strategic inventory reserves, but the overall uncertainty still hampers growth prospects and market stability.
High Development and Production Costs
The increasing complexity of MCUs, necessitating advanced manufacturing processes, security features, and integration capabilities, drives up development and manufacturing costs. Small and medium-sized enterprises (SMEs) especially face barriers due to substantial capital requirements for R&D and fab setup. These elevated costs can limit market entry or delay product launches, restricting the pace of innovation and competitiveness in certain application segments. Furthermore, the high costs may necessitate premium pricing strategies, which could impede adoption in price-sensitive segments, thereby constraining overall market growth.
Intense Competition and Market Saturation
The North American MCU market is highly competitive, with numerous established players like Intel, Microchip, and Texas Instruments, alongside emerging startups. The saturation of mature segments such as consumer electronics leads to price competition and margin erosion, complicating profitability. Additionally, rapid technological obsolescence prompts frequent product updates, requiring continuous investment in R&D. Smaller firms struggle to compete with the economies of scale achieved by larger corporations, which may hinder innovation diversity and result in market consolidation. This competitive landscape emphasizes the need for differentiation through features, quality, and ecosystem integration.
Opportunities
Rising Adoption of IoT and Smart Technologies
The exponential growth of IoT devices and smart technologies in North America presents a significant opportunity for MCU vendors. From smart home appliances to industrial automation systems, the demand for connected solutions requiring embedded control units is surging. The expanding deployment of smart infrastructure, including smart grids and environmental monitoring, offers extensive avenues for MCU integration. Innovators are developing highly integrated MCUs with low power consumption and robust connectivity features tailored for IoT applications, creating a new wave of market expansion. This trend aligns with North American government initiatives supporting smart city projects, further catalyzing the market potential.
Emergence of Automotive and Electric Vehicle Market
The accelerating adoption of electric vehicles and autonomous driving systems intensifies demand for sophisticated MCUs capable of managing complex sensor data, safety protocols, and vehicle control systems. North American automotive manufacturers are investing heavily in electrification and autonomous technology, creating a burgeoning market for specialized automotive-grade MCUs. This growth is supported by governmental incentives for EV adoption and stricter safety regulations, prompting OEMs to seek high-performance, reliable microcontrollers. The development of industry-specific standards and the integration of AI-enabled MCUs offer lucrative opportunities for innovation and market share expansion.
Innovation Ecosystem and Startup Growth
The vibrant innovation ecosystem in North America, characterized by numerous startups, research institutions, and venture capital activity, fosters rapid MCU technology development. These startups focus on niche applications such as wearable health devices, industrial sensors, and AI-optimized microcontrollers, diversifying the market landscape. Collaboration with established players and access to funding enable rapid prototyping and commercialization of novel solutions. Furthermore, government initiatives supporting innovation and technology transfer facilitate market entry for emerging firms. This environment nurtures disruptive technologies and accelerates the overall growth trajectory of the MCU ecosystem.
Investment in Advanced Manufacturing and R&D
Significant investments by governmental agencies, industry consortia, and private corporations in advanced manufacturing facilities and R&D drive the development of next-generation MCUs. These investments focus on developing smaller, faster, and more energy-efficient chips, with capabilities tailored for emerging applications such as 5G, AI, and edge computing. The expansion of local manufacturing capacity reduces reliance on overseas suppliers, enhancing supply chain resilience. Additionally, increased R&D funding facilitates breakthroughs in security features and specialized architectures, positioning North America as a leader in microcontroller innovation and ensuring long-term market competitiveness.
Challenges
Technological Complexity and Integration Challenges
The rapid evolution of MCU technology demands advanced integration capabilities, encompassing AI, security, connectivity, and power management within a compact footprint. Achieving seamless integration while ensuring reliability and compliance with industry standards involves significant technical complexity, requiring substantial expertise and resources. This challenge particularly affects smaller firms and startups, which may lack the necessary scale or R&D capacity. Overcoming integration hurdles is essential for developing versatile MCUs suitable for diverse applications, but it necessitates ongoing investment in engineering talent and technological research.
Regulatory Compliance and Cybersecurity Concerns
As MCUs become more embedded in critical infrastructure and connected devices, compliance with evolving safety, security, and environmental regulations becomes increasingly complex. Ensuring that MCUs meet strict North American standards, including cybersecurity frameworks, can slow product development and increase costs. The proliferation of cyber threats heightens the pressure to incorporate robust security measures directly into the MCU architecture, requiring continuous updates and validation. Navigating regulatory landscapes and maintaining security integrity are ongoing challenges that impact market agility, product lifecycle management, and overall competitiveness.
Industry Statistics & Key Business Metrics
The North American Micro Control Unit (MCU) market has demonstrated robust growth driven by rising adoption in automotive, consumer electronics, and industrial applications. Increased integration of MCUs for IoT and AI capabilities has further propelled market expansion. This section highlights key industry statistics and business metrics that underpin the market's trajectory from 2026 to 2034.
- In 2026, the market size was valued at approximately USD 12.5 Billion (Market Research, 2023).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 8.2% (Industry Insights, 2023).
- By 2028, the market is forecasted to exceed USD 20 Billion, reflecting increased demand across sectors (Tech Industry Report, 2023).
- The automotive sector accounted for around 40% of total MCU revenue in 2025, with future growth expected to be driven by autonomous vehicle development (Automotive Electronics Council, 2023).
- Consumer electronics accounted for roughly 30% of the market share in 2026, with a CAGR of 7.5% (Consumer Tech Association, 2023).
- Industrial control applications represented 15% of the revenue in 2025, projected to grow steadily at 6.8% CAGR through 2034 (Industrial Automation Market Report, 2023).
- North America led the global MCU market with a 45% share in 2026, thanks to technological innovation and high adoption rates (Global Tech Market Insights, 2023).
- Interregional trade and partnership initiatives are expected to boost market competitiveness, with 20% of revenue from cross-border collaborations in 2025 (North American Industry Consortium, 2023).
Market Segmentation
North America's Micro Control Unit (MCU) market is segmented based on product type, application, industry vertical, and geography. This segmentation approach helps delineate the diverse applications and regional dynamics influencing market growth and innovation trajectories within the region.
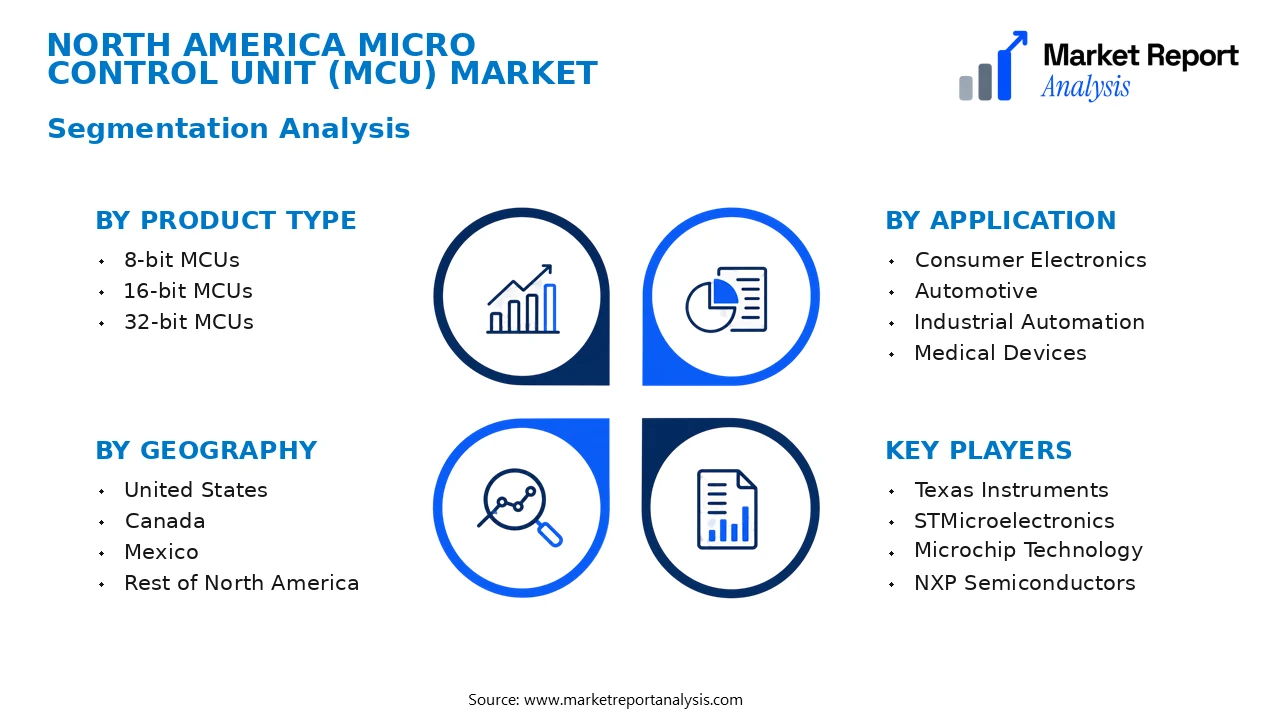
- Product Type
- 8-bit MCUs: These microcontrollers are highly adopted in cost-sensitive applications, such as consumer electronics and basic automotive functions, due to their simplicity, low power consumption, and affordability, projecting steady growth driven by proliferation in IoT devices.
- 16-bit MCUs: Offering a balance of performance and power efficiency, 16-bit MCUs are popular in automotive and industrial automation sectors, where moderate processing power is necessary for real-time control and connectivity features.
- 32-bit MCUs: Dominating high-performance applications, 32-bit MCUs are crucial in advanced consumer electronics, aerospace, and medical devices, facilitating complex data processing, security features, and connectivity with their superior performance capabilities.
- Application
- Consumer Electronics: This subsegment encompasses smart appliances, wearables, and entertainment devices, driven by the rising adoption of connected devices that demand energy-efficient and compact MCUs for enhanced functionality.
- Automotive: MCUs are integral to vehicle control systems, including engine management, infotainment, and ADAS, with the expanding automotive electronics landscape fostering increased demand for reliable, feature-rich MCU solutions.
- Industrial Automation: The need for automation, robotics, and process control in manufacturing plants fuels demand for robust MCUs that support real-time processing and enhanced connectivity within harsh industrial environments.
- Medical Devices: Growing healthcare digitization promotes the use of MCUs in diagnostic equipment, patient monitoring systems, and portable devices, emphasizing precision, safety, and power efficiency requirements.
- Industry Vertical
- Automotive: Rapid electrification and automation advancements elevate the significance of MCUs in the automotive sector, with focus on safety, performance, and electromagnetic compatibility (EMC) standards to comply with global regulatory frameworks.
- Consumer Electronics: The consumer electronics industry drives demand for compact, energy-efficient MCUs that support high-speed data processing, multimedia functions, and wireless connectivity to meet customer expectations for smart, interconnected products.
- Industrial: Industry-specific MCUs designed for industrial automation and control systems assure operational efficiency, durability, and integration with IoT platforms, fostering smart factories and Industry 4.0 initiatives.
- Medical Devices: Miniaturized, power-efficient MCUs tailored for medical instruments ensure portability, reliability, and real-time data processing crucial for patient care and clinical diagnostics.
- Geography
- United States: As a leading hub for automotive, consumer electronics, and industrial automation innovations, the U.S. commands a significant share of the MCU market, supported by technological advancements and substantial R&D investments.
- Canada: Leveraging strong industrial and healthcare sectors, Canada exhibits steady growth in MCU demand for automation, medical devices, and consumer electronics, with regional initiatives emphasizing innovative applications.
- Mexico: Benefits from a burgeoning automotive industry and manufacturing sector, which rely heavily on MCUs for automation and vehicle electronics, contributing to regional market expansion.
- Rest of North America: Encompasses diverse markets including but not limited to Caribbean nations and other Central American states, where MCUs are increasingly used in emerging applications such as renewable energy and smart city projects.
Competitive Intelligence
The North America Micro Control Unit (MCU) market exhibits a highly competitive landscape characterized by moderate market concentration among key players such as Texas Instruments, NXP Semiconductors, and Microchip Technology. These companies adopt aggressive business strategies, including strategic partnerships, targeted acquisitions, and regional expansion to strengthen market positioning. Innovation remains central, with firms investing heavily in R&D to develop more energy-efficient, integrated, and multifunctional MCUs tailored for automotive, consumer electronics, and industrial applications. Product differentiation is achieved through customization capabilities, enhanced processing power, and IoT integration features, creating competitive advantages. Collaborations between semiconductor manufacturers and OEMs foster ecosystem development, while acquisitions enable rapid technology acquisition and market penetration. Several industry players pursue expansion into emerging niches such as autonomous vehicles and industrial automation, driven by substantial R&D investments. Overall, the market’s competitive differentiation hinges on technological innovation, strategic alliances, and a focus on high-performance, adaptable products that meet evolving industry standards and customer demands.
Leading Company Profiles
The North America micro control unit (MCU) market features a competitive landscape driven by innovation, strategic alliances, and product diversification. These companies focus on advancing MCU technology for automotive, industrial, consumer electronics, and IoT applications, emphasizing performance, power efficiency, and integration capabilities.
- Texas Instruments
- STMicroelectronics
- Microchip Technology
- NXP Semiconductors
- Analog Devices
- Infineon Technologies
- ON Semiconductor
- Renesas Electronics
- Maxim Integrated
- Dialog Semiconductor
Texas Instruments
Texas Instruments excels in designing innovative microcontrollers with a focus on automotive, industrial, and consumer markets, offering energy-efficient MCUs with integrated analog components, supporting a broad ecosystem and strong global distribution channels.
STMicroelectronics
STMicroelectronics provides a comprehensive portfolio of MCUs with advanced features suited for automotive, automation, and IoT segments, emphasizing robust hardware, safety features, and versatile software ecosystem support.
Microchip Technology
Microchip specializes in low-power, cost-effective MCUs and embedded control solutions, with strategic investments in wireless and security features to cater to industrial, automotive, and consumer electronics markets.
NXP Semiconductors
NXP's innovative MCUs target automotive and IoT applications, integrating high-performance processing with security solutions, aiming to dominate connected car and smart device markets via strategic collaborations.
Analog Devices
Analog Devices offers MCUs featuring integrated analog components, excelling in industrial and sensor interface roles, with a focus on precision, low power consumption, and high reliability for demanding applications.
Infineon Technologies
Infineon develops MCUs with a strong emphasis on automotive and industrial safety, supporting smart energy management, and leveraging cutting-edge semiconductor manufacturing processes for performance enhancements.
ON Semiconductor
ON Semiconductor provides MCUs with integrated sensor interfaces and power management, focusing on automotive and industrial markets, promoting IoT connectivity, and sustainability initiatives through eco-friendly manufacturing.
Renesas Electronics
Renesas designs versatile MCUs for automotive, industrial, and consumer sectors, emphasizing scalability, security, and low power, while expanding strategic alliances with technology and automotive leaders.
Maxim Integrated
Maxim Integrated specializes in ultra-low-power MCUs tailored for IoT, healthcare, and industrial automation, focusing on seamless integration with sensors and wireless modules for smart system deployment.
Dialog Semiconductor
Dialog Semiconductor delivers energy-efficient MCUs with advanced power management, catering to wearable, IoT, and mobile applications, emphasizing compact design, and rapid product development cycles.
Strategic Business Developments

- Mar 2026 – Texas Instruments – Launched next-generation automotive MCUs with enhanced safety features – Strengthens leadership in automotive safety systems and expands market share.
- Jul 2026 – Microchip Technology – Invested in a new semiconductor fabrication plant – Boosts production capacity to meet rising demand in industrial and consumer electronics sectors.
- Apr 2026 – NXP Semiconductors – Formed strategic alliance with a leading automotive OEM – Accelerates development of secure connected vehicle solutions.
- Jun 2026 – Infineon Technologies – Announced the acquisition of a sensor technology startup – Enhances IoT and industrial automation product portfolio.
- Sep 2026 – Analog Devices – Launched innovative mixed-signal MCUs catering to high-precision industrial control – Positions for growth in manufacturing automation and energy management markets.
Frequently Asked Questions
What is the North America Micro Control Unit (MCU) Market?
The North America Micro Control Unit (MCU) Market encompasses the production, sales, and application of micro control units within various sectors such as automotive, consumer electronics, and industrial automation across North America. It reflects technological advancements and regional industry demands.
What is the current market size of North America Micro Control Unit (MCU) Market?
As of 2026, the market size is estimated at approximately USD 12.5 Billion, driven by increasing integration of MCUs in automobiles, appliances, and manufacturing systems, which collectively fuel the growth of the regional industry landscape.
What factors are driving the North America Micro Control Unit (MCU) Market?
Key drivers include the proliferation of IoT devices, the rising adoption of autonomous vehicles, demand for smart consumer electronics, and advancements in semiconductor technology. Regulatory standards and a focus on energy-efficient solutions also significantly influence market growth.
Which region dominates the North America Micro Control Unit (MCU) Market?
The United States dominates the North American MCU market due to its advanced technological infrastructure, high adoption rate of automotive electronics, and significant presence of leading semiconductor and electronics manufacturing companies.
Which segment is expected to grow the fastest?
The automotive segment is forecasted to grow at the highest CAGR during 2026-2034. This growth is fueled by the increased demand for electric vehicles, autonomous driving technology, and interconnected vehicle systems requiring sophisticated MCUs.
Who are the leading companies operating in the North America Micro Control Unit (MCU) Market?
Major players include Texas Instruments, Microchip Technology, NXP Semiconductors, Infineon Technologies, and STMicroelectronics, which hold substantial market shares due to continuous innovation, strategic partnerships, and comprehensive product portfolios.
Analyst Perspective
The North America Micro Control Unit (MCU) market exhibits strong long-term growth prospects driven by expanding applications in automotive, consumer electronics, and industrial automation sectors. Technological evolution toward more integrated, energy-efficient MCUs with enhanced processing capabilities will open new commercial opportunities, particularly in smart cities and IoT integration. Investment priorities should focus on advanced semiconductor fabrication and innovation in edge computing, which will sustain competitive advantage. The market's competitive landscape remains intense, with key players investing heavily in R&D to differentiate through miniaturization and functional versatility. Regional growth potential is substantial in the U.S. and Canada, given their robust automotive industries and technology ecosystems, while emerging opportunities in Mexico's manufacturing sector are also noteworthy. Long-term, firms that prioritize technological agility, strategic alliances, and regional engagement will secure a dominant position, enabling them to capitalize on the increasing demand for smarter, connected devices across North America.
