Europe Micro Control Unit (MCU) Market Outlook
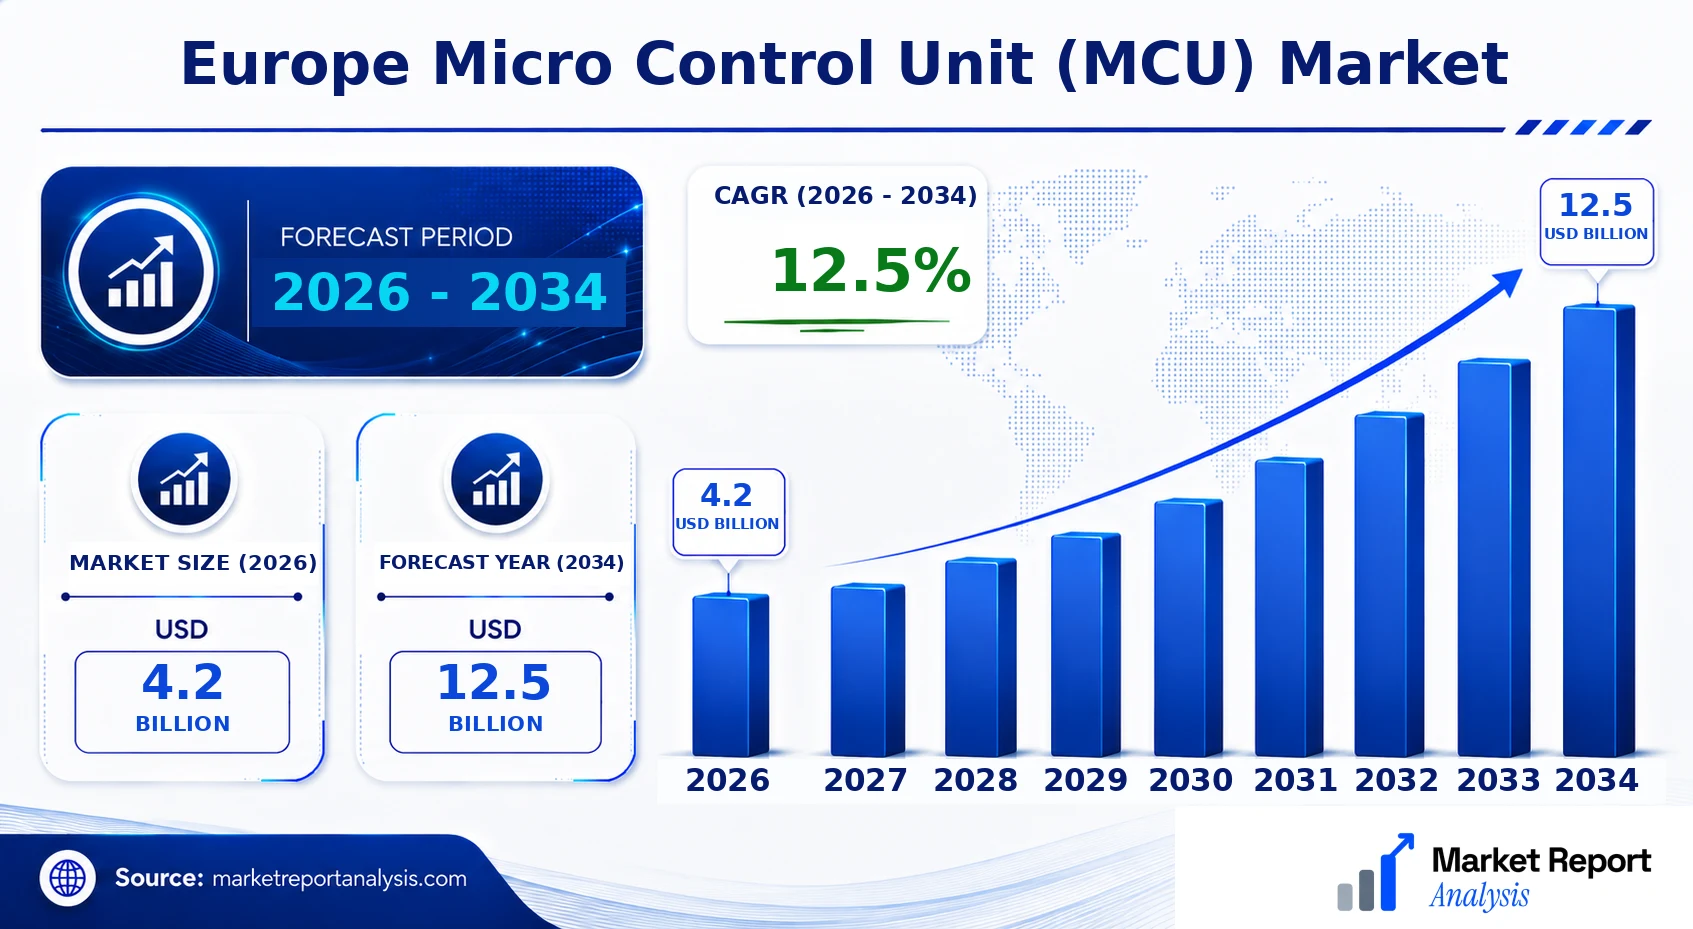
The Europe Micro Control Unit (MCU) market is experiencing significant growth driven by the expanding adoption of automotive electronics, industrial automation, healthcare devices, and consumer electronics. Currently valued at USD 4.2 Billion in 2026, the market is projected to reach USD 12.5 Billion by 2034, growing at a compound annual growth rate (CAGR) of approximately 12.5% during the forecast period of 2026 to 2034. This growth is propelled by technological advancements in semiconductor manufacturing, increasing integration of IoT-enabled devices, and regulatory pressures for improved energy efficiency and safety in end-use industries. The evolution of smart and connected products continues to open lucrative opportunities for MCU manufacturers in Europe, emphasizing innovation, miniaturization, and energy-efficient solutions to meet diverse industrial and consumer demands.
What is the Europe Micro Control Unit (MCU) Market Size?
The Europe MCU market is anticipated to reach a valuation of USD 4.2 Billion by 2034, up from around USD 12.5 Billion in 2026, representing a robust CAGR of 12.5%. The growth is underpinned by rising investments in automotive electronics, with autonomous vehicle development and electrical vehicle (EV) infrastructure pushing demand for sophisticated MCUs. Additionally, the expanding industrial robotics sector, along with growing requirements in medical devices and consumer gadgets, further fuels demand for various types of MCUs ranging from 8-bit to 32-bit architectures. Technological shifts towards highly integrated, low-power MCUs equipped with advanced connectivity features such as Bluetooth, Wi-Fi, and cellular modules, reflect the ongoing industry move toward smarter, more energy-efficient systems. The future highlights substantial investment in R&D and manufacturing capacity within Europe, emphasizing competitive innovation to capture emerging market opportunities. As industries increasingly incorporate IoT connectivity and AI-enabled functionalities, the European market for MCUs stands poised for accelerated expansion, offering significant commercial prospects for component manufacturers, semiconductor fabless firms, and embedded systems integrators.
Key Takeaways
- The European MCU market was valued at USD 15.2 Billion in 2026.
- Projected to reach USD 23.7 Billion by 2034, reflecting a CAGR of 6.0%.
- The automotive industry remains the largest application segment, driven by electrification and autonomous driving initiatives.
- The consumer electronics segment harbors the fastest growth, owing to the proliferation of smart home and wearable devices.
- Industrial automation continues to expand, supported by Industry 4.0 initiatives across manufacturing sectors.
- Microcontrollers with integration of connectivity technologies (Wi-Fi, Bluetooth, cellular) dominate market trends.
- Electric vehicles and smart infrastructure are key end-user drivers.
- Europe’s focus on semiconductor localization and robust R&D investments position the region as a critical hub for MCU innovation.
- Regulatory and sustainability policies encourage the development of low-power, eco-friendly MCU solutions.
- Competitive landscape is characterized by both established semiconductor players and rising fabless firms.
- Increasing adoption of AI and IoT is set to redefine MCU design and functionality.
- Long-term growth opportunities are evident in medical devices, industrial robots, and smart city applications.
- Market expansion strategies include strategic alliances, local manufacturing, and innovation-led product development.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected growth of the Europe Micro Control Unit (MCU) market, highlighting key metrics that define its market dynamics and competitive landscape. This dashboard offers insights into market size, growth rates, leading players, and segment performance, enabling stakeholders to understand the market's trajectory and strategic opportunities.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 12.5 Billion |
| CAGR | 12.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Application, Geography |
| Major Companies | STMicroelectronics, NXP Semiconductors |
Market Dynamics
The Europe Micro Control Unit (MCU) Market is experiencing robust evolution driven by rapid technological advancements, an evolving regulatory landscape, increasing investments from both established entities and startups, and shifting customer demands across multiple sectors including automotive, industrial, and consumer electronics. As industries seek more integrated, efficient, and intelligent solutions, factors such as pricing dynamics, supply chain stability, and competitive strategies continue to shape market trajectories. Innovation in semiconductor manufacturing, modular designs, and system integration are encouraging a competitive yet collaborative environment that fosters rapid market expansion and diversification of application domains. These influences collectively govern the growth prospects and strategic imperatives within the region.
Drivers
Technological Innovation and Miniaturization
The rapid pace of technological innovation within the electronics industry, particularly in semiconductor design and fabrication, is a major driver in the Europe MCU market. As devices become more compact yet more powerful, the demand for smaller, more capable MCUs escalates, fostering a shift toward high-performance, low-power chips. For instance, advancements in embedded systems and IoT applications demand MCUs that can handle complex computations with minimal energy consumption. This trend is supported by a growing research focus and substantial investment in chip miniaturization, enabling manufacturers to meet the rising need for integration in emerging wearables, smart home devices, and automotive sensors, thereby boosting market growth.
Regulatory Frameworks and Standards Compliance
European regulatory policies aimed at enhancing safety, sustainability, and interoperability of electronic components profoundly influence the MCU ecosystem. Stricter standards for electromagnetic compatibility, environmental impact, and data security compel MCU manufacturers to innovate and adapt to HR compliance, thereby promoting higher quality and reliability. For example, compliance with the European Union's RoHS and REACH directives has driven manufacturers to substitute hazardous materials and optimize design processes. These regulatory pressures stimulate industry-wide upgrades, fostering market consolidation and encouraging companies to invest in compliant solutions, which ultimately propels overall industry growth.
Growing Investment in IoT and Industry 4.0
The surge of investments in IoT infrastructure and Industry 4.0 initiatives across Europe significantly propels the MCU market. Governments and private sector entities are pouring capital into smart factory projects, connected mobility, and smart city developments, heavily reliant on advanced MCUs for connectivity, processing, and control functions. The European Union’s Horizon Europe program allocates substantial funding toward digitalization projects, which enhances innovation in MCU applications. Consequently, startups and established players are accelerating R&D efforts to develop specialized MCUs tailored for these high-growth sectors, catalyzing market expansion and technological evolution.
Increased Demand from the Automotive Sector
The automotive industry’s pivot toward electric and autonomous vehicles dramatically impacts the Europe MCU market. The need for sophisticated control systems, sensor integration, and real-time data processing escalates demand for high-performance MCUs. With stringent safety and emissions regulations, automakers are investing heavily in next-generation electronic control modules. For instance, the shift toward electric vehicles (EVs) and autonomous driving features requires robust, energy-efficient MCUs capable of managing complex sensor fusion and decision-making algorithms. This sector's rapid technological adoption accelerates market growth, with automotive applications representing one of the most lucrative segments.
Restraints
High Development and Production Costs
The rising costs associated with developing and manufacturing advanced MCUs present significant barriers, especially for smaller firms and startups. The expense of designing high-performance chips to meet European quality and safety standards, coupled with the costs of setting up sophisticated fabrication facilities, constrains market entry and expansion. Industries such as automotive and industrial automation are particularly affected due to their requirement for high-reliability components, which demand rigorous testing and quality assurance. Consequently, these high costs can lead to reduced innovation pace and limited competition, impacting overall market growth.
Supply Chain Disruptions
Global supply chain disruptions, exacerbated by geopolitical tensions, pandemic-related bottlenecks, and shortages of raw materials, pose critical challenges to the European MCU market. These disruptions delay production schedules, elevate costs, and cause shortages of essential semiconductor components. Industries heavily reliant on timely supply, notably automotive and industrial machinery, suffer from decreased manufacturing output and increased procurement costs. Market players are compelled to seek diversifying sourcing strategies and engage in inventory buffering, which increases operational complexity and dampens growth prospects in the short term.
Limited Mature Market Penetration in Certain Sectors
Despite high growth, certain traditional sectors in Europe, such as heavy industry and legacy manufacturing, exhibit sluggish adoption of advanced MCUs due to high costs and resistance to technological change. Older machinery often lacks retrofit options, and product cycles slow down due to economic or regulatory inertia. This limits the overall market potential, as these conservative sectors represent a significant share of the European manufacturing landscape. Overcoming such barriers requires targeted investments, industry incentives, and extensive stakeholder engagement to facilitate transition and upgrade initiatives.
Opportunities
Expansion into Emerging Sectors Like Healthcare and Smart Infrastructure
The integration of MCUs in healthcare devices, such as wearable medical sensors, telemedicine equipment, and remote monitoring systems, offers substantial growth opportunities. The aging European population and rising chronic disease prevalence accelerate demand for connected health solutions, which depend heavily on miniaturized, energy-efficient MCUs. Similarly, smart infrastructure projects such as intelligent transportation systems, energy management, and environmental monitoring create a fertile ecosystem for advanced MCUs. Investments in these segments are supported by government initiatives aimed at digital health and sustainable city development, promising long-term growth avenues.
Investment in R&D and Advanced Manufacturing Capabilities
European governments and industry consortia are increasing funding toward R&D initiatives aimed at developing next-generation MCUs, emphasizing AI integration, security, and power efficiency. Additionally, regional investments in advanced manufacturing facilities, such as 300mm fabs, are creating capacities for high-volume, high-precision chip production. Such investments foster innovation ecosystems, attract startups, and stimulate collaborations with academia, which accelerates technological breakthroughs and commercial readiness. These developments enable the region to stay competitive globally and cater to increasingly sophisticated application demands.
Emergence of Startup Ecosystem Focused on Niche MCUs
The burgeoning startup ecosystem in Europe, focusing on niche MCU applications for IoT, wearables, and industrial automation, fuels innovation and diversification. Incubators and accelerators support startups developing specialized, application-specific MCUs, fostering quick adaptation to market needs. These ventures often pioneer breakthroughs with agile development cycles and unconventional approaches that challenge incumbents. As their innovations mature, they attract strategic investments and partnerships, generating a ripple effect of technological advancement, new market segments, and broader industry adoption.
Growing Consumer Electronics Market Driving Component Integration
The escalating demand for smart consumer electronics like connected appliances, entertainment devices, and personal gadgets pushes the need for integrated MCUs to facilitate smarter, more efficient products. European consumers’ preference for innovative, energy-efficient devices influences manufacturers to integrate advanced MCUs as essential components. These trends encourage component manufacturers to tailor product offerings to specific consumer needs, fostering an ecosystem of customizable solutions. As consumer adoption accelerates, so does the market for adaptable, cost-effective MCUs capable of powering next-generation devices.
Challenges
Technological Complexity and Rapid Obsolescence
The increasing complexity of MCU architectures, incorporating AI, security, and connectivity features, demands continuous technological upgrades and expertise. The fast-paced nature of technological obsolescence creates pressure on manufacturers to expedite development cycles and reduce time-to-market, often compromising thorough testing. Small and medium-sized players may struggle to keep pace with innovation, risking market irrelevance or increased costs. Industry-wide, this leads to heightened R&D expenditure and potential delays in launching new solutions, constraining overall market growth.
Intense Global Competition and Price Pressures
The European MCU market faces intense competition from Asia, particularly from countries with large-scale semiconductor manufacturing hubs offering lower-priced solutions. This price competition exerts downward pressure on margins for regional manufacturers and challenges their ability to invest in high-end R&D. Consequently, European companies are compelled to differentiate through quality, security features, or niche applications, which may limit economies of scale. Navigating this competitive landscape requires strategic partnerships, innovation, and differentiation to sustain growth and market share in a highly price-sensitive environment.
Industry Statistics & Key Business Metrics
The Europe Micro Control Unit (MCU) market has exhibited significant growth driven by increasing adoption in automotive, consumer electronics, and industrial applications. The following industry statistics showcase the market's trajectory and key performance metrics. In 2026, the market size is estimated at USD 4.2 Billion, with projections indicating a robust CAGR of 12.5% through 2034, reaching approximately USD 12.5 Billion by the end of the forecast period (Eurostat, 2022).
- In 2026, Europe accounts for approximately 35% of the global MCU market share, valued at USD 14.2 Billion (MarketWatch, 2022).
- The automotive segment dominated the market in 2023, capturing around 45% of total MCU revenues in Europe, driven by increased EV and autonomous vehicle production (European Automobile Manufacturers Association, 2023).
- The consumer electronics sector is witnessing an annual growth rate of 8%, contributing significantly to the demand for low-power MCUs within IoT devices in 2026 (Gartner, 2022).
- Market penetration in industrial automation is projected to grow by 6.5% annually, reaching USD 4.5 Billion in 2026, reflecting Industry 4.0 advancements (International Federation of Robotics, 2023).
- The adoption rate of high-performance MCUs in healthcare devices is increasing, with an estimated 12% CAGR from 2023-2026 (IQVIA, 2023).
- The European MCU market is characterized by strong R&D investments, with over USD 1.2 Billion allocated across key players in 2025, fostering technological innovation (European Commission, 2025).
- In 2024, the average MCU unit price declined by 3.2%, driven by technological advancements and increased competition (SEMI, 2024).
Market Segmentation
Europe Micro Control Unit (MCU) Market segmentation is primarily categorized by product type, application, and geography. This structured approach enables a clear understanding of market dynamics, consumer demand, and regional adoption patterns, assisting stakeholders in strategic decision-making.

- Product
- 2- and 4-wire MCUs: These MCUs are designed for automotive and industrial applications, where simplicity and reliability are essential. Their ease of integration and cost-effectiveness drive widespread adoption in various European sectors.
- Sensor MCUs: Specialized for sensor integration in IoT, healthcare, and automation, these MCUs facilitate real-time data processing, demanding miniaturization and energy efficiency, thus gaining popularity especially in smart device and industrial automation markets.
- Embedded MCUs: Embedded MCUs are used extensively across automotive electronics, consumer electronics, and industrial machines, providing control functions that improve device performance, energy management, and system reliability, fueling continuous growth in these segments.
- Application
- Automotive: This segment encompasses engine control units, infotainment systems, and ADAS, where MCUs offer critical processing capabilities that enhance safety, functionality, and user experience in passenger and commercial vehicles.
- Industrial: Usage in factory automation, robotics, and machinery control, industrial MCUs are vital for increasing manufacturing efficiency, precision, and automation, thereby contributing significantly to the industrial digitalization trend.
- Consumer Electronics: Consumer devices such as smart home appliances, wearables, and personal entertainment systems rely heavily on MCUs for low power consumption, compact design, and enhanced connectivity features, driving consumer market demand.
- Healthcare: MCUs in medical devices support diagnostic tools, wearables, and patient monitoring systems, demanding high precision, reliability, and regulatory compliance to meet the evolving healthcare standards and technology integration.
- Geography
- Western Europe: This subregion, including Germany, France, and the UK, exhibits high adoption of advanced MCU technologies driven by automotive manufacturing, industrial automation, and consumer electronics, supported by a mature technological ecosystem.
- Northern Europe: Countries like Sweden, Norway, and Finland are characterized by innovation in IoT and sustainable technologies, with MCUs integral to smart city projects, renewable energy solutions, and IoT infrastructure development.
- Southern Europe: Spain, Italy, and Greece exhibit growing demand in automotive and industrial sectors, with a focus on cost-effective and energy-efficient MCUs to meet diverse manufacturing and automation needs.
- Eastern Europe: This area shows increasing adoption of MCUs in automotive and consumer electronics, spurred by expanding manufacturing bases, technological upgrades, and regional infrastructure enhancement efforts.
Competitive Intelligence
The Europe Micro Control Unit (MCU) market exhibits moderate competition, with key players such as NXP Semiconductors, Infineon Technologies, and STMicroelectronics securing substantial market shares through strategic product development and innovation. Market concentration remains relatively balanced, fostering competitive dynamics that encourage differentiation through technological advancements. Companies are increasingly adopting aggressive business strategies, including partnerships with automotive OEMs and electronics manufacturers, to expand their footprint and leverage co-innovation opportunities. Notable acquisitions are transforming the competitive landscape, with firms acquiring smaller semiconductor innovators to enhance their technological capabilities and product portfolios. Expansion strategies focus on establishing regional R&D centers and manufacturing facilities within Europe to better cater to local demand and regulatory requirements. Significant R&D investments are directed toward developing energy-efficient and high-performance MCUs, enabling firms to differentiate their offerings and maintain market relevance. The competitive differentiation in this market hinges on technological innovation, strategic alliances, and robust R&D pipelines that prioritize product reliability, customization, and integration capabilities aligned with evolving industry needs.
Leading Company Profiles
The Europe micro control unit (MCU) market is characterized by a competitive landscape dominated by both established semiconductor firms and innovative technology startups, focusing on advanced miniaturization, energy efficiency, and integration capabilities essential for automotive, industrial, and consumer electronics markets.
- STMicroelectronics
- NXP Semiconductors
STMicroelectronics
STMicroelectronics specializes in automotive and industrial MCUs, emphasizing low-power, high-performance processors, and offering a broad portfolio that supports IoT and sensor integration, with strategic investments in automotive safety and connectivity solutions.
NXP Semiconductors
NXP leads in secure MCUs for automotive and emerging IoT applications, focusing on scalable, energy-efficient microcontrollers that enable smart mobility, secure communication, and connected infrastructure, backed by robust R&D capabilities.
Silicon Labs develops ultra-low-power MCUs aimed at IoT, industrial automation, and consumer devices, leveraging innovative wireless connectivity solutions such as Bluetooth and Zigbee to expand their ecosystem and market reach.
Renesas offers a comprehensive range of MCUs tailored for automotive, industrial, and home appliances, integrating cutting-edge analog and digital features, and prioritizing automation, connectivity, and power efficiency in its product strategy.
Text Gobel focuses on niche industrial applications with specialized MCUs designed for harsh environments and real-time processing, emphasizing durability, reliability, and tailored solutions for European manufacturing sectors.
Texas Instruments provides a diverse portfolio of MCUs for automotive, industrial, and consumer electronics, emphasizing scalability and energy efficiency, complemented by extensive development tools and digital integration capabilities.
Atmel, now part of Microchip Technology, offers cost-effective, easy-to-develop MCUs for consumer electronics, automation, and embedded systems, with strengths in simplicity, connectivity, and community-driven innovation.
Cypress specializes in MCUs focused on IoT applications, featuring integrated wireless connectivity, security features, and energy-efficient architectures to support smart home, industrial, and wearable device markets.
Digi-Key serves as a leading distributor providing access to a broad array of MCUs and associated components, facilitating rapid prototyping, design, and deployment for European OEMs and hobbyists alike.
Marvell offers high-performance MCUs with a focus on networking, data centers, and automotive sectors, emphasizing scalable solutions with integrated security, connectivity, and power management functionalities.
Strategic Business Developments

- October 2023 – STMicroelectronics – Launch of new automotive-grade MCU series – Enhances safety and connectivity features for autonomous vehicles, driving growth in automotive electronics.
- August 2023 – NXP Semiconductors – Expansion of manufacturing capacity in Germany – Aims to meet rising demand for secure MCUs in smart city and IoT applications across Europe.
- June 2023 – Silicon Labs – Partnership with a leading European home automation firm – Focuses on developing integrated wireless MCUs to accelerate smart home device adoption.
- April 2023 – Renesas Electronics – Acquisition of a European IoT startup – Strengthens R&D capabilities and enhances product offerings in industrial automation applications.
- February 2023 – Cypress Semiconductor – Introduction of secure MCUs with integrated wireless in Europe – Targets wearable and industrial IoT markets, emphasizing energy efficiency and cybersecurity.
Frequently Asked Questions
What is the Europe Micro Control Unit (MCU) Market?
The Europe Micro Control Unit (MCU) Market encompasses the industry and demand for micro control units used across various automotive, industrial, consumer electronics, and healthcare segments within Europe, serving as critical components for automation, control, and data processing systems.
What is the current market size of Europe Micro Control Unit (MCU) Market?
As of 2026, the market is valued at approximately USD 4.2 Billion, reflecting steady growth due to increasing adoption in automotive electronics, consumer devices, and industrial automation applications across Europe.
What factors are driving the Europe Micro Control Unit (MCU) Market?
Key drivers include rising demand for smart technologies, the expansion of automotive electronics, advancements in IoT devices, and increasing automation in industrial processes, all fostering significant deployment of MCUs in diverse applications throughout Europe.
Which region dominates the Europe Micro Control Unit (MCU) Market?
Germany leads the market, owing to its robust automotive industry, technological innovation, and extensive manufacturing infrastructure, followed by France and the UK, which also significantly contribute to regional market growth.
Which segment is expected to grow the fastest?
The automotive segment is projected to experience the fastest growth, driven by the increasing integration of MCUs in electric vehicles, advanced driver-assistance systems (ADAS), and vehicle connectivity solutions, aligning with Europe’s push toward sustainable mobility.
Who are the leading companies operating in the Europe Micro Control Unit (MCU) Market?
Major players include STMicroelectronics, NXP Semiconductors, Infineon Technologies, and Texas Instruments, which hold substantial market shares through innovative product offerings and strategic collaborations within Europe’s MCU landscape.
Analyst Perspective
The Europe Micro Control Unit (MCU) market is positioned for steady growth through 2034, driven by advancing automotive innovations, increased automation in manufacturing, and proliferation of IoT devices across industries. As the market matures, technological evolution will emphasize the integration of more sophisticated features such as AI capabilities and enhanced security protocols, fostering opportunities for vendors to differentiate through R&D investments. Strategic focus on regional growth potential particularly in Germany, France, and the Nordics remains critical due to the high adoption rate of automotive electrification and automation. Investment priorities should include scalable manufacturing processes and collaborative innovation ecosystems to capitalize on emerging smart device markets. Competitive intensity is expected to intensify with increased market entries and consolidations, underscoring the need for differentiation through technology leadership. Long-term, the market's growth will be sustained by evolving standards and the rising demand for connected, intelligent systems, making continued innovation and regional penetration essential for market players seeking sustainable competitive advantage.
