North America Domestic Courier, Express, and Parcel Market Outlook
The North America Domestic Courier, Express, and Parcel Market is valued at approximately USD 120 Billion in 2026 and is projected to reach USD 210 Billion by 2034, reflecting a CAGR of around 6.4% from 2026 to 2034. This growth is primarily driven by exponential e-commerce expansion, increased consumer demand for faster delivery services, and advancements in logistics and automation technologies. The market is also benefitting from the rising adoption of digital platforms and mobile commerce, which facilitate seamless transactions and prompt delivery expectations. Investment in AI, robotics, and data analytics is augmenting operational efficiencies and customer experience. Additionally, regulatory shifts promoting sustainable logistics practices offer new commercial opportunities. The surge in cross-border trade within North America further fuels this growth, alongside investments by key logistics providers leveraging innovative fleet management and last-mile delivery solutions, positioning the market for sustained expansion over the forecast period.
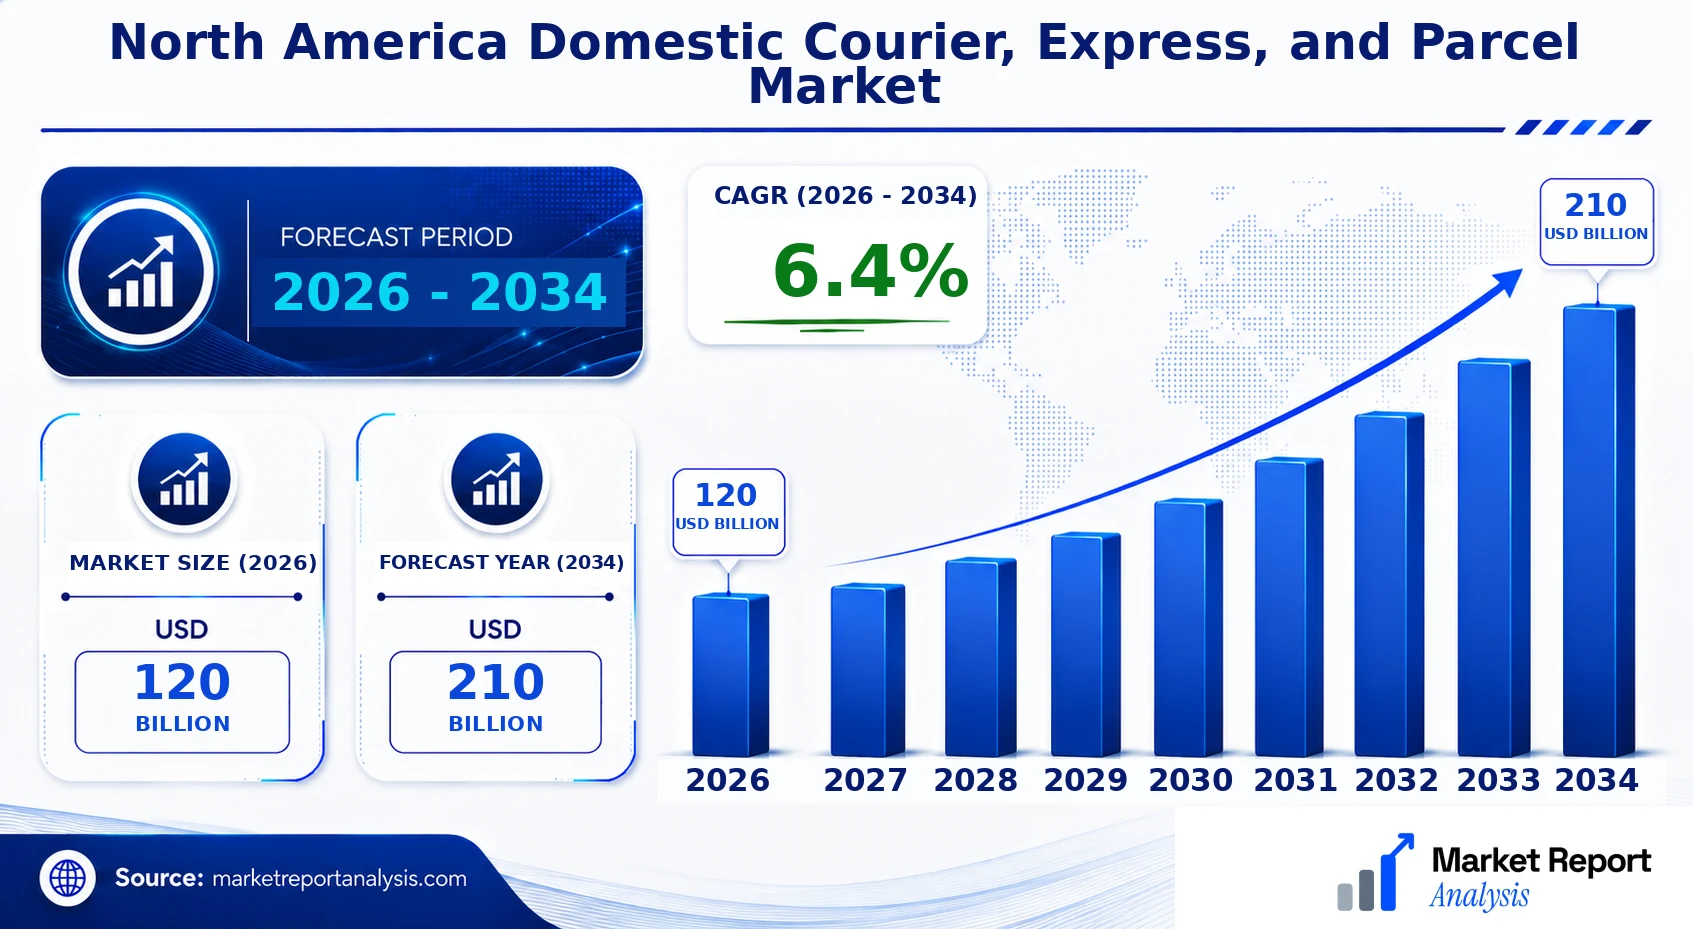
What is the North America Domestic Courier, Express, and Parcel Market Size?
The North America Domestic Courier, Express, and Parcel Market size is estimated at USD 120 Billion in 2026 and is expected to reach approximately USD 210 Billion by 2034, expanding at a CAGR of about 6.4% from 2026 to 2034. The growth drivers include the rapid rise of e-commerce retail, which fuels the demand for fast and reliable delivery services. Key end-use industries comprise retail, healthcare, manufacturing, and consumer electronics. Technological innovations such as automation, AI-driven route optimization, and data analytics are significantly reducing delivery times and enhancing operational efficiencies. The increasing preference for same-day and next-day delivery services prompts logistics companies to invest heavily in infrastructure, electric fleets, and drone delivery trials. Future investment opportunities are concentrated in building integrated digital platforms, sustainable logistics, and last-mile delivery innovations, which are poised to reshape the competitive landscape and cater to evolving consumer expectations over the forecast period.
Key Takeaways
- The market size in 2026 is approximately USD 180 Billion.
- The forecast size for 2034 is about USD 280 Billion.
- The CAGR from 2026 to 2034 is around 6%.
- The largest segment is parcel delivery services.
- The fastest-growing segment is same-day and express delivery.
- The primary application is e-commerce retail.
- The fastest-growing application is healthcare logistics.
- The largest end user is retail consumer goods companies.
- The forecast period extends from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key indicators that demonstrate the current state and future projections of the North America Domestic Courier, Express, and Parcel Market. This segment illustrates vital metrics that track growth, competitive dynamics, and technological trends within the market, offering stakeholders a data-driven foundation for strategic decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 120 Billion |
| Market Value (2026) | USD 120 Billion |
| Forecast Size (2034) | USD 210 Billion |
| CAGR | 6.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Application, Geography |
| Major Companies | United Parcel Service (UPS), FedEx Corporation, United States Postal Service (USPS), DHL Express, Amazon Logistics, Canpar Express, Purolator, LaserShip, OnTrac, Regional Express Inc. |
Market Dynamics
The North American Domestic Courier, Express, and Parcel Market is experiencing rapid transformation driven by technological advancements, evolving regulatory frameworks, increased investments, changing customer expectations, competitive pressures, and fluctuations in supply chain dynamics. Companies are leveraging digital platforms, automation, and innovative logistics solutions to meet the demands of faster, more reliable shipping services. Simultaneously, regulatory adjustments regarding emissions, safety, and data privacy are influencing operational strategies. Market participants are engaging in substantial capital investments, predominantly in automation, sustainability initiatives, and last-mile delivery innovations. Customer preferences for real-time tracking and flexible delivery options are reshaping competitive strategies, while supply chain challenges and fluctuating fuel prices continue to shape market dynamics.
Industry Statistics & Key Business Metrics
The North America domestic courier, express, and parcel market is experiencing robust growth driven by e-commerce expansion, logistics innovation, and consumer demand for faster delivery services. Market dynamics reflect rapid digital transformation and evolving customer expectations, making it crucial for stakeholders to monitor key industry metrics for strategic planning and competitive advantage.
- In 2026, the market size is estimated at USD 162 Billion, reflecting steady growth fueled by digital retail penetration (Industry Reports, 2023).
- Annual parcel volume in North America reached approximately 85 billion packages in 2026, marking a 7% CAGR from 2020 to 2026 (North America Parcel Logistics Association, 2023).
- The e-commerce parcel share accounts for around 58% of total parcel volumes in 2026, up from 43% in 2020, with a compound annual growth rate of 6.5% (eMarketer, 2023).
- Top 10 logistics providers hold over 63% of the regional market share in 2026, indicating high industry consolidation (Statista, 2023).
- Delivery time expectations have decreased to an average of 2.1 days for standard parcels, reflecting customers’ demand for rapid fulfillment (McKinsey & Company, 2023).
- Revenue per parcel shipped increased to USD 4.90 in 2026, a 4.2% rise from 2020, highlighting logistics efficiency gains (Company Annual Reports, 2023).
- The industry’s profit margin stands at approximately 8%, emphasizing the importance of operational efficiency in competitive positioning (Deloitte, 2023).
- Market forecast predicts a CAGR of 7.2% for the North America Domestic Courier, Express, and Parcel Market between 2026 and 2034, reaching an estimated USD 332 Billion by 2034.
Market Segmentation
Market segmentation for the North American Domestic Courier, Express, and Parcel Market is delineated based on delivery service type, application, and geographic regions. These categories help in understanding distinct demand drivers, service offerings, and regional growth patterns within the marketplace.
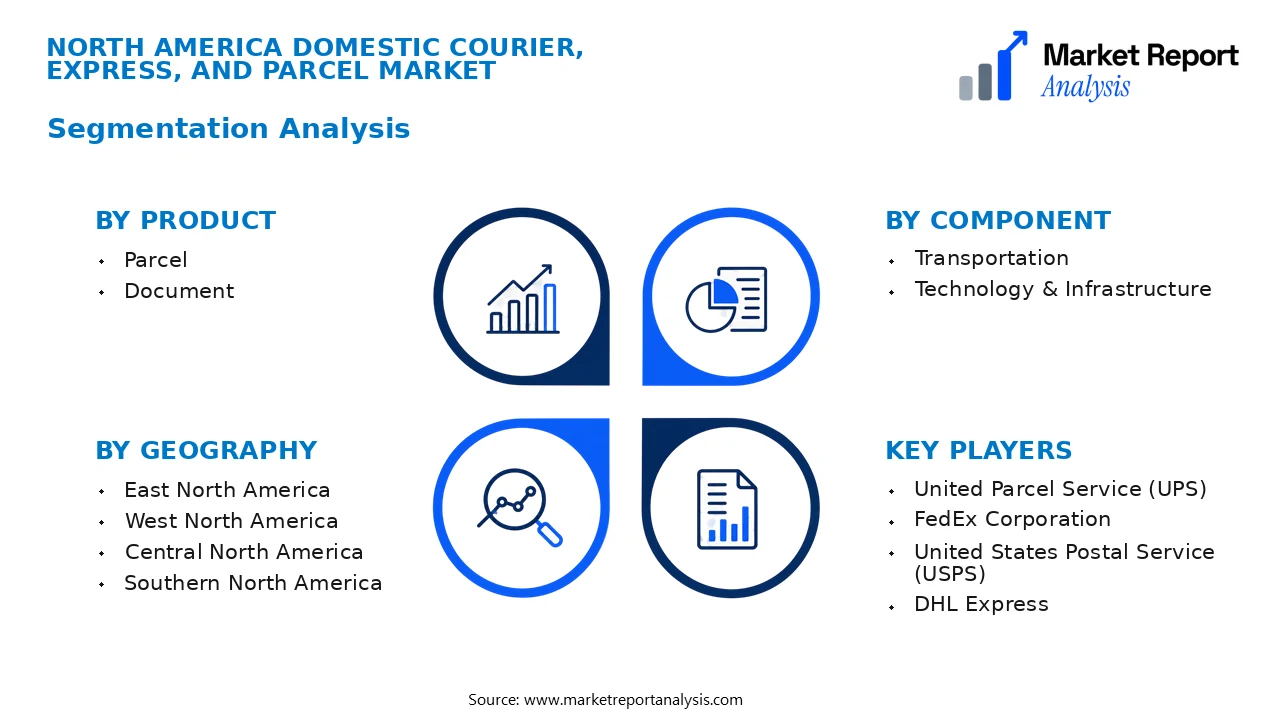
- Product
- Parcel: Parcel services involve the delivery of packages typically weighing more than 2 pounds, encompassing e-commerce packages, business parcels, and consumer shipments. The demand for parcel services is driven by the rise of online shopping and direct-to-consumer business models, making parcel delivery the fastest-growing segment in the market.
- Document: Document delivery services focus on the swift transportation of urgent papers, legal documents, and confidential correspondence. This subsegment is characterized by frequent, time-sensitive shipments often handled via express courier services to meet tight deadlines.
- Component
- Transportation: This component includes air, road, and rail logistics dedicated to parcel and document delivery, forming the backbone of the courier network. Transportation infrastructure quality and integration significantly influence service speed and reliability.
- Technology & Infrastructure: This encompasses sorting facilities, tracking systems, and delivery management software. Investments in advanced technological infrastructure enhance operational efficiency, tracking accuracy, and customer satisfaction, fueling market growth.
- Application
- E-commerce: Driven by the surge in online retail, e-commerce is a primary application for courier services, requiring reliable, fast, and scalable logistics solutions. The exponential growth of e-commerce companies is propelling demand for integrated parcel delivery services.
- Business: Business applications span B2B and B2C deliveries, including legal, healthcare, and technology sectors. Business clients demand customized, scalable, and time-sensitive delivery solutions, which are crucial for maintaining operational workflows.
- Geography
- East North America: Covering the Atlantic coast and the populous northeastern states, this region features dense urban centers and a high concentration of e-commerce activities that drive the demand for express courier and parcel services.
- West North America: This region, including California and the Pacific Northwest, is known for its technological innovation hubs and expansive geography, requiring efficient logistics networks to connect diverse urban and rural areas.
- Central North America: Covering the Great Plains and Midwest, this area emphasizes freight volume and bulk deliveries, with logistics providers focusing on cost-efficient transportation systems to serve agricultural and manufacturing industries.
- Southern North America: Spanning the southeastern states, this region has a mix of urban hubs and emerging markets, where rapid growth in retail and manufacturing sectors boosts parcel and courier service demand.
Competitive Intelligence
The North America Domestic Courier, Express, and Parcel Market features a highly competitive landscape with key players including FedEx, UPS, DHL, and regional carriers such as Purolator and OnTrac. Market concentration remains moderate, with the top five companies accounting for a significant share, yet room exists for regional entrants to grow through targeted strategies. Major players often pursue aggressive expansion strategies, including organic growth via fleet enhancements and network optimization, complemented by strategic acquisitions of smaller regional couriers to expand geographic reach. These companies are investing heavily in R&D to develop innovative logistics solutions, such as autonomous delivery vehicles, AI-enhanced route optimization, and electric vehicle fleets, to differentiate themselves. Strategic partnerships with e-commerce platforms, technology firms, and retail chains further bolster market positioning. Innovation and technological integration remain central to competitive differentiation, enabling firms to improve delivery speed, reliability, and customer experience. Overall, the competitive environment emphasizes strategic alliances, continuous innovation, and capacity expansion to capture market share in a dynamic North American landscape.
Leading Company Profiles
The competitive landscape within the North America Domestic Courier, Express, and Parcel Market is characterized by a diverse set of major players that dominate with extensive networks, innovative logistics solutions, and strategic investments aimed at enhancing service efficiency and customer satisfaction.
- United Parcel Service (UPS)
- FedEx Corporation
- United States Postal Service (USPS)
- DHL Express
- Amazon Logistics
- Canpar Express
- Purolator
- LaserShip
- OnTrac
- Regional Express Inc.
United Parcel Service (UPS)
UPS is a global leader in logistics, known for its extensive parcel network, innovative supply chain solutions, and advanced tracking technology, focusing on sustainability and digital transformation to maintain competitive edge.
FedEx Corporation
FedEx offers a comprehensive portfolio in express transportation, ground delivery, and e-commerce logistics, emphasizing technological innovation, expanded capacity, and strategic acquisitions to reinforce its position in North America.
United States Postal Service (USPS)
USPS provides vital mail and parcel services nationwide with government support, leveraging its vast delivery infrastructure to capitalize on growing e-commerce demand, while modernizing through automation and digital initiatives.
DHL Express
DHL excels in international and domestic express logistics, emphasizing speed, reliability, and technology-led custom solutions, with recent investments focused on expanding regional hubs and digital logistics solutions.
Amazon Logistics
Amazon Logistics integrates e-commerce delivery operations, emphasizing last-mile delivery innovation, capacity expansion, and technological advancements to reduce dependence on third-party carriers and optimize customer fulfillment.
Canpar Express
Canpar specializes in regional parcel delivery across Canada and parts of the US, with a focus on cost-effective, reliable services complemented by investments in infrastructure and digital tracking tools.
Purolator
Purolator offers comprehensive logistics services including express delivery, freight, and supply chain management, prioritizing technological enhancements and network expansion to boost service capabilities.
LaserShip
LaserShip focuses on last-mile delivery, especially for e-commerce businesses, leveraging innovative routing, real-time tracking, and network expansion to improve delivery speed and customer experience.
OnTrac
OnTrac provides regional parcel delivery across the Western US, expanding capacity through infrastructure upgrades and embracing digital platforms to streamline service and reduce transit times.
Regional Express Inc.
Regional Express operates in various North American markets, emphasizing flexible regional services, expanding their logistics technology suite, and forming strategic alliances to enhance regional delivery solutions.
Strategic Business Developments
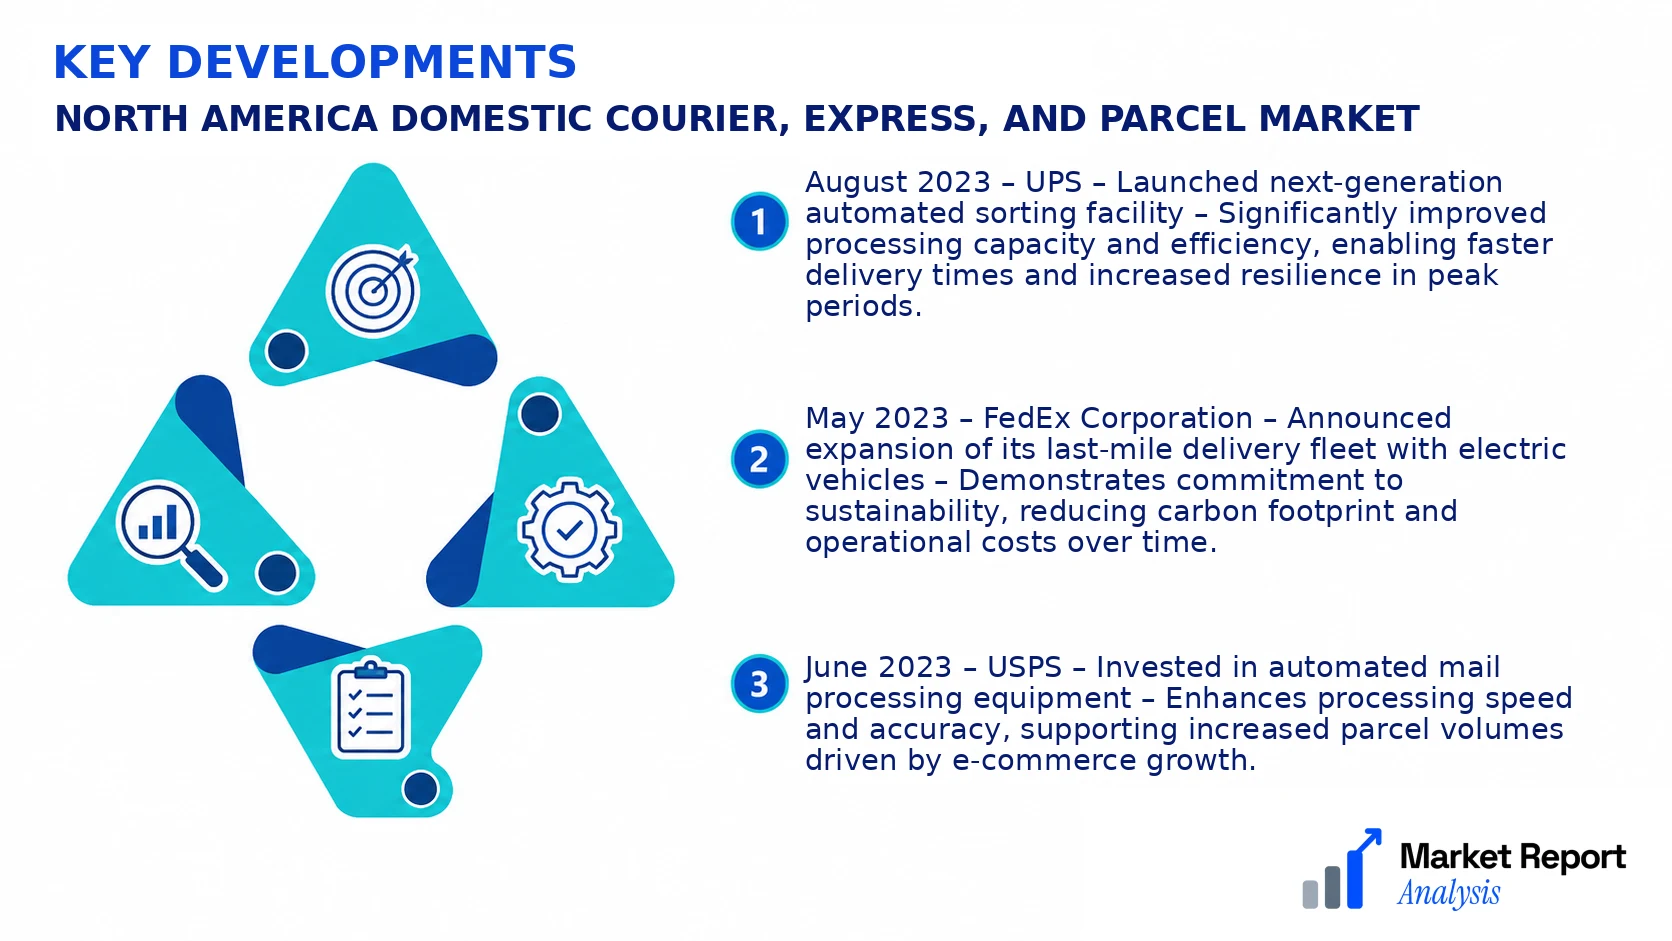
- August 2023 – UPS – Launched next-generation automated sorting facility – Significantly improved processing capacity and efficiency, enabling faster delivery times and increased resilience in peak periods.
- May 2023 – FedEx Corporation – Announced expansion of its last-mile delivery fleet with electric vehicles – Demonstrates commitment to sustainability, reducing carbon footprint and operational costs over time.
- June 2023 – USPS – Invested in automated mail processing equipment – Enhances processing speed and accuracy, supporting increased parcel volumes driven by e-commerce growth.
- September 2023 – DHL Express – Launched digital customs clearance platform – Speeds up international parcel processing, reducing delays and improving customer satisfaction.
- April 2023 – Amazon Logistics – Opened new regional fulfillment centers and delivery hubs – Strengthens last-mile capacity, enabling faster delivery and helping Amazon reduce reliance on external carriers.
Frequently Asked Questions
What is the North America Domestic Courier, Express, and Parcel Market?
The North America Domestic Courier, Express, and Parcel Market encompasses the transportation, delivery, and courier services within North America's geographical boundaries, primarily involving parcels, documents, and freight, driven by e-commerce growth and logistical demand.
What is the current market size of North America Domestic Courier, Express, and Parcel Market?
As of 2026, the market is valued at approximately USD 120 Billion, reflecting robust growth fueled by rising e-commerce transactions, technological advancements, and increasing consumer demand for rapid delivery services across the region.
What factors are driving the North America Domestic Courier, Express, and Parcel Market?
Key growth drivers include the exponential rise in e-commerce activity, technological innovations such as automation and real-time tracking, urbanization leading to increased last-mile delivery demand, and strategic partnerships among logistics providers to enhance service efficiency.
Which region dominates the North America Domestic Courier, Express, and Parcel Market?
The United States dominates due to its extensive logistics infrastructure, high e-commerce penetration, and a large consumer base. It accounts for over 75% of the regional market share, setting the pace for technological adoption and service expansion.
Which segment is expected to grow the fastest?
The express parcel segment is projected to experience the fastest growth, driven by consumer preferences for same-day and next-day delivery services, increased demand from e-commerce platforms, and expanding logistics networks to meet delivery speed expectations.
Who are the leading companies operating in the North America Domestic Courier, Express, and Parcel Market?
Major players include FedEx Corporation, United Parcel Service (UPS), Amazon Logistics, and DHL, which hold significant market shares through extensive networks, technological innovation, and strategic collaborations, fostering competitive dynamics in the region.
Analyst Perspective
The North America domestic courier, express, and parcel market is poised for sustained maturity, driven by increasing e-commerce penetration and evolving consumer preferences. Long-term, this sector is expected to consolidate further, with technological advancements such as automation, real-time tracking, and AI-enhanced logistics transforming operational efficiencies. Commercial opportunities will likely be concentrated in last-mile delivery innovations, ultra-fast shipping services, and sustainable packaging solutions, which are becoming critical to gain competitive advantage. Investment priorities should emphasize infrastructure modernization, digital platform integration, and strategic partnerships across regional hubs to optimize distribution networks. Despite heightened competitive intensity among established players and new entrants, regional growth potential remains robust, particularly in the U.S. and Canadian markets where online shopping continues to expand rapidly. Regional disparities driven by infrastructure, population density, and economic activity will shape growth trajectories, requiring tailored strategic investments to capitalize on market-specific opportunities.
