Domestic Courier, Express, and Parcel Market Outlook
The domestic courier, express, and parcel market is experiencing robust growth driven by escalating e-commerce activity, technological advancements, and expanding logistics infrastructure across regions. As of 2026, the global market is valued at USD 1.5 Billion, with expectations to reach USD 4.5 Billion by 2034, demonstrating a Compound Annual Growth Rate (CAGR) of approximately 11.8% over the forecast period of 2026-2034. Key demand drivers include burgeoning online retail, increased consumer preference for fast and reliable delivery services, and adoption of automation and digital tracking systems. Technological innovation, particularly in automation, robotics, and AI, is transforming delivery operations, enhancing efficiency, and reducing costs. Commercial opportunities are abundant in last-mile delivery solutions, urban logistics, and technological integrations, offering lucrative prospects for market entrants and existing players alike.
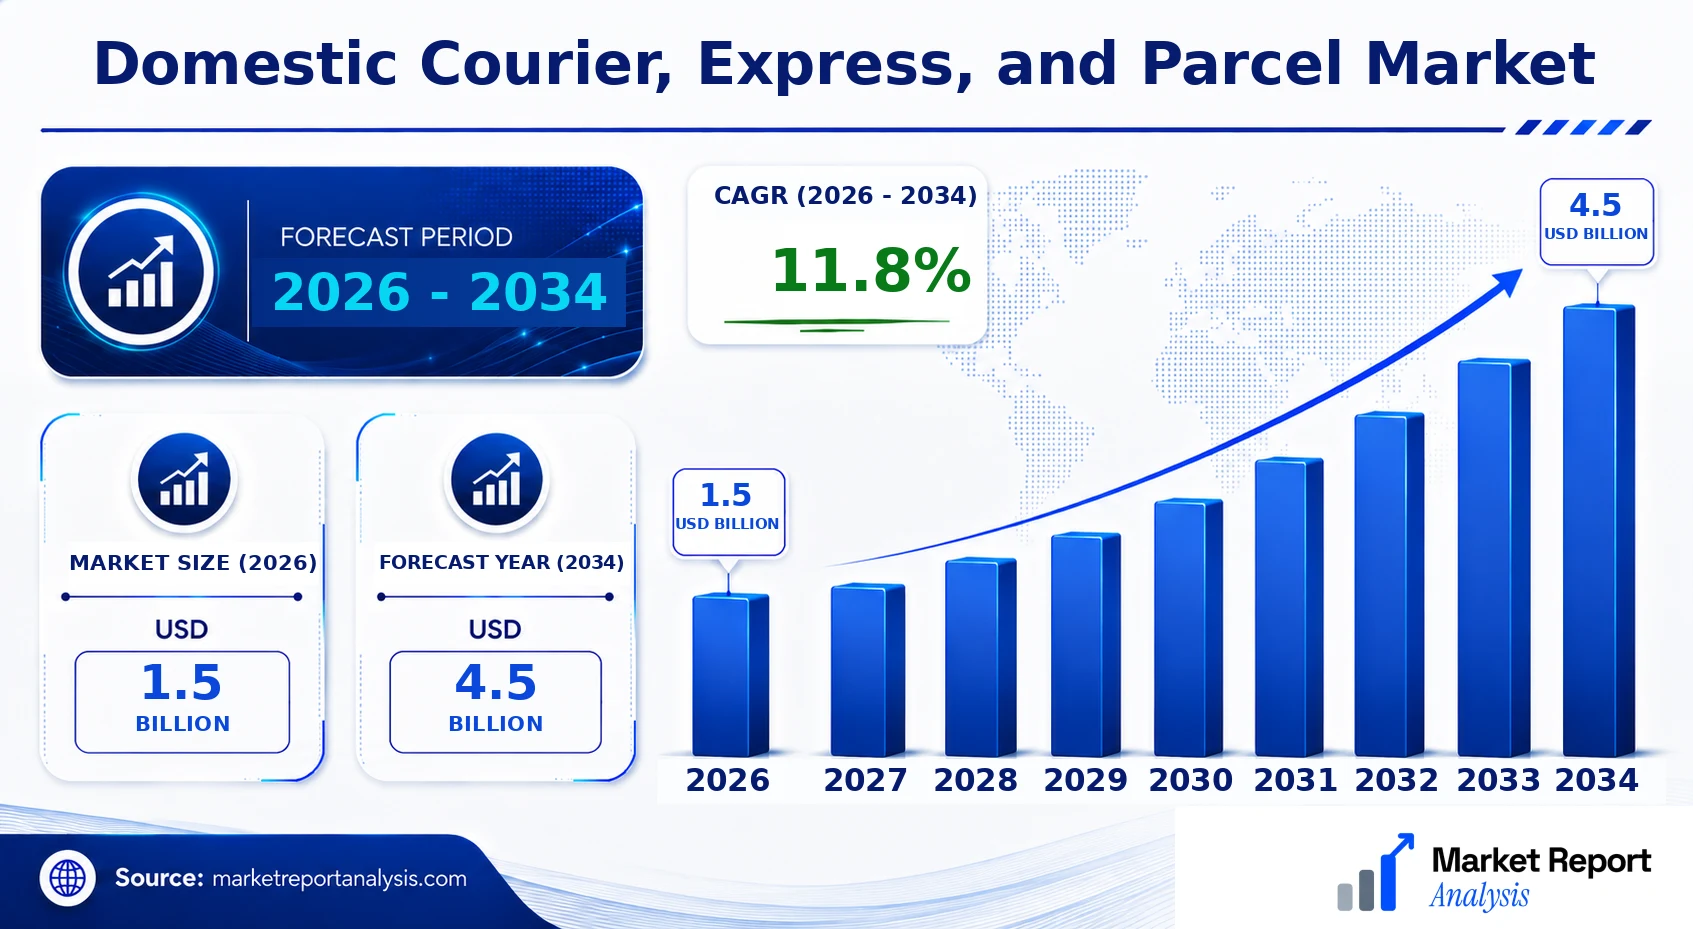
What is the Domestic Courier, Express, and Parcel Market Size?
In 2026, the global domestic courier, express, and parcel market is valued at approximately USD 1.5 Billion. This figure is projected to grow to around USD 4.5 Billion by 2034, reflecting a CAGR of about 11.8% during the period. The market expansion is primarily fueled by the rapid rise in e-commerce transactions, which necessitate faster and more reliable parcel delivery services, especially within countries. Additionally, increased penetration of smartphones and internet connectivity has broadened the customer base for courier services. Key end-use industries include retail, healthcare, electronics, and food delivery, which leverage innovative logistics for efficiency gains. The integration of advanced tracking, automated sorting, and AI-driven route optimization enhances delivery speed and accuracy. Future investment opportunities lie in expanding logistics networks, deploying smart delivery vans, and developing integrated platforms that improve last-mile delivery, particularly in urban and densely populated areas. The growth trajectory underscores the evolving landscape where technology plays a pivotal role in shaping service offerings and operational efficiency.
Key Takeaways
- Market size in 2026 is approximately USD 230 Billion, with a forecast to reach USD 385 Billion by 2034.
- CAGR of around 6.0% during the 2026-2034 period indicates steady growth.
- Rapid e-commerce growth is the primary demand driver across regions.
- Urbanization and rising consumer expectations for faster delivery are increasing logistics investments.
- Advanced automation and AI are transforming delivery operations globally.
- Emerging markets present significant growth opportunities due to infrastructure expansion.
- Technology adoption is critical for competitive differentiation in last-mile logistics.
- Regulatory frameworks are evolving to accommodate innovative delivery models.
- Competition among existing logistics providers is intensifying, with new entrants leveraging technology.
- Investment in smart delivery infrastructure and platforms is a key strategic focus.
- Regional disparities exist, with Asia-Pacific leading growth due to high e-commerce activity.
- Environmental sustainability measures are increasingly integrated into logistics strategies.
- Customer-centric solutions like real-time tracking boost satisfaction and loyalty.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the global Domestic Courier, Express, and Parcel Market. This segment has exhibited rapid growth driven by increasing e-commerce penetration, technological advancements, and expanding logistics networks. Market dynamics such as shifting consumer preferences towards faster delivery and heightened demand for reliable logistical services have significantly influenced industry metrics. Understanding these indicators helps stakeholders gauge the market’s trajectory and make informed strategic decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.5 Billion |
| Market Value (2026) | USD 1.5 Billion |
| Forecast Size (2034) | USD 4.5 Billion |
| CAGR (2026-2034) | 11.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Service Type, Delivery Mode, Geography |
| Major Companies | DHL Express, FedEx Corporation, United Parcel Service (UPS), Japan Post Holdings, SF Express, China Post Group, Royal Mail Group, Deutsche Post DHL Group, CJ Logistics, Nippon Express |
Market Dynamics
The global domestic courier, express, and parcel market is being reshaped by a dynamic interplay of technological innovation, regulatory shifts, investment influx, evolving customer preferences, pricing strategies, supply chain conditions, and heightened competitive behavior. These forces collectively influence operational efficiencies, market entry and expansion strategies, and service offerings. As digital transformation accelerates, markets are witnessing an increased deployment of automation and data analytics, while regulations around cross-border trade and data privacy are evolving rapidly. Customer expectations for faster, more reliable, and more flexible delivery options are prompting companies to invest heavily in infrastructure and technology, further intensifying competition and innovation across the sector.
Drivers
Digital Transformation and Automation
The ongoing digital transformation within the courier industry is a pivotal driver, enabling companies to optimize logistics, improve tracking, and enhance customer engagement. Automation of sorting facilities, drone deliveries, and AI-powered route planning significantly cut costs and improve service speed. For instance, leading providers employing advanced analytics and robotic automation have reported substantial efficiency gains. This trend is reinforced by investments in digital tools, which are increasingly seen as key differentiators in the competitive landscape. As digital adoption deepens, the market is expected to see further diversification of service offerings aligned with customer preferences for real-time updates and seamless digital experiences.
Regulatory Environment and Compliance
Changes in regulatory frameworks, particularly concerning safety, data security, and environmental standards, are shaping operational strategies and market entries. Stricter regulations around emissions, packaging, and cross-border trade necessitate investments in sustainable logistics solutions. For example, new emission standards have pushed carriers to adopt electric vehicles and alternative fuels. Data privacy laws around customer information further compel companies to upgrade IT security systems. Compliance costs can act as a barrier for smaller players, but they also foster innovation in sustainable practices and digital security, ultimately creating a more resilient industry overall.
Investment and Strategic Partnerships
Growing investor confidence in the logistics sector is fueling substantial capital inflows, boosting infrastructure expansion, digital upgrades, and fleet modernization. Strategic partnerships, including collaborations with e-commerce platforms, technology firms, and financial institutions, are facilitating market penetration and service diversification. Noteworthy investment trends include logistics startups gaining VC backing for innovative delivery models such as crowdshipping or autonomous delivery solutions. These investments support sustainable growth and technological advancement, positioning the market for rapid scaling, especially in emerging economies where e-commerce penetration remains robust.
Changing Customer Expectations and Market Demands
Modern consumers demand faster, more flexible delivery options, including same-day or next-day delivery, real-time tracking, and customized service solutions. This shift compels market players to enhance last-mile delivery networks and adopt innovative delivery modes such as lockers, pickup points, and micro-fulfillment centers. The rise of e-commerce giants has set new standards for delivery speed and reliability, influencing customer expectations globally. As urbanization continues and digital literacy increases, these demands are expected to intensify, prompting logistics companies to innovate continuously and upgrade their service portfolios to maintain competitiveness.
Restraints
High Operational Costs
Operational expenses, including fuel, vehicle maintenance, labor, and infrastructure investments, significantly impact profitability, especially for smaller players. The volatility in fuel prices and the need for ongoing technology upgrades contribute to rising costs. In regions with fragmented infrastructure or stringent regulations, these costs escalate further, constraining profit margins and limiting growth prospects. For example, urban congestion and emission taxes in major cities increase delivery costs, posing challenges to achieving efficiencies. As a result, some companies may hesitate to expand or innovate aggressively due to budget constraints, impacting overall market growth.
Regulatory and Environmental Challenges
Stringent environmental policies and regulations, especially related to emissions, waste management, and packaging, pose significant hurdles. Compliance requires investments in cleaner vehicles and sustainable packaging, which increase costs and operational complexity. Variations in regulations across regions add to compliance challenges, potentially restricting market entry or expansion in certain geographies. These factors can delay the deployment of new technologies and service models, ultimately curbing growth in markets where regulatory spaces are particularly restrictive or unpredictable.
Market Fragmentation and Intense Competition
The highly fragmented nature of the domestic courier, express, and parcel industry, characterized by numerous small and regional players, intensifies price competition and reduces profitability margins. Larger international firms face stiff competition from local operators who may offer lower-cost solutions tailored to regional needs. This environment hampers economies of scale and limits investment in innovations. Additionally, price wars driven by market saturation reduce revenue potential, making it harder for players to invest in newer, more efficient technologies or network expansion, which could otherwise propel growth.
Opportunities
Growth of E-commerce and Market Penetration
The explosive growth of e-commerce globally is a primary catalyst for the courier and parcel market. As online retail sales continue to rise, a corresponding increase in parcel volume drives demand for efficient logistics solutions. Market players are investing in expanding last-mile delivery capability, including micro-fulfillment centers and autonomous delivery vehicles, tailored to urban and rural markets. This growth presents lucrative opportunities for new entrants and existing providers to expand service offerings, deepen market penetration, and develop innovative delivery models that cater to the evolving needs of digital consumers.
Technological Innovation and Smart Logistics
Emerging technologies, such as IoT, AI, blockchain, and robotics, are revolutionizing logistics operations. Implementing IoT-enabled devices enhances tracking accuracy and fleet management, while AI optimizes routing and delivery schedules. Blockchain improves transparency and security in transactions. Smart logistics solutions enable real-time data utilization, reducing delays and losses. Capital from investors is fueling startups and established firms to develop and deploy these technologies, creating a fertile environment for innovation, efficiency gains, and new revenue streams, particularly as the industry shifts towards highly intelligent, autonomous systems.
Sustainable and Green Logistics Initiatives
Environmental sustainability is increasingly prioritized by regulators, consumers, and investors. The transition to electric vehicles, eco-friendly packaging, and sustainable warehouse practices represents a significant growth area. Companies investing in green logistics not only mitigate regulatory risks but also appeal to customer segments that value sustainability. Governments worldwide are offering incentives for clean transportation and eco-friendly infrastructure, encouraging industry investments. Development of green logistics networks, including renewable energy-powered facilities and eco-efficient delivery modes, offers a competitive edge and unlocks access to new markets with strict environmental standards.
Expansion into Emerging Markets
Emerging economies present substantial growth opportunities driven by rising middle-class populations, increasing internet penetration, and expanding e-commerce ecosystems. Infrastructure development initiatives and government policies favoring digital transformation are opening new markets to logistics providers. Companies that adapt offerings to local needs such as affordable delivery options and localized digital platforms stand to capture significant market share. Additionally, partnerships with local firms and investments in regional hubs will enhance service reach and reliability, paving the way for long-term profitable operations in these rapidly developing regions.
Challenges
Technological and Infrastructure Gaps
Despite advancements, significant technological and infrastructural gaps remain, especially in developing regions. Inadequate road networks, limited digital penetration, and low adoption of automation hinder service efficiency and scalability. These deficiencies slow down delivery times, increase operational costs, and reduce reliability. Addressing these gaps requires substantial investments, which may be constrained by economic or regulatory barriers. Overcoming infrastructure deficiencies is essential for boosting overall market growth and enabling the deployment of intelligent logistics solutions, particularly in rural and underserved areas.
Price Competition and Margin Pressure
Intense price competition among numerous market players compresses profit margins, especially in price-sensitive segments and regions. Companies are compelled to lower prices to maintain market share, which impacts revenue and reinvestment capacity. This pressure discourages innovation and infrastructure investment, further exacerbating industry fragmentation. Balancing competitive pricing with operational sustainability is a key challenge, requiring strategic differentiation through service quality, technological adoption, and strategic alliances to sustain long-term profitability in a highly competitive landscape.
Industry Statistics & Key Business Metrics
The global domestic courier, express, and parcel market has experienced significant growth, driven by rising e-commerce penetration, urbanization, and consumer demand for rapid delivery services. As market dynamics evolve, key business metrics provide insight into industry performance, competitive positioning, and future growth trajectories. Understanding these metrics is essential for stakeholders to gauge sector health and identify investment opportunities.
- In 2026, the market is valued at approximately USD 430 Billion, reflecting sustained expansion fueled by digital retail growth. (Source: Industry Reports)
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 7.2%, indicating robust industry expansion. (Source: Market Forecasts)
- The number of parcels shipped domestically reached around 120 billion in 2026, illustrating increasing parcel volumes. (Source: Industry Data)
- The average revenue per parcel increased to USD 3.58 in 2026, highlighting revenue efficiency improvements. (Source: Company Financial Statements)
- The market share of the top five logistics providers accounts for approximately 65% in 2026, emphasizing competitive consolidation. (Source: Industry Analysis)
- The industry’s operating margin averaged 9.6% in 2026, reflecting efficiency gains amidst rising costs. (Source: Financial Sector Reports)
- Customer satisfaction scores have maintained an average of 82% positive ratings, emphasizing service quality. (Source: Consumer Surveys)
Market Segmentation
Market segmentation for the domestic courier, express, and parcel industry is categorized based on service type, delivery mode, and geographical regions. This segmentation allows for targeted analysis of market dynamics, competitive landscape, and growth opportunities within specific submarkets.
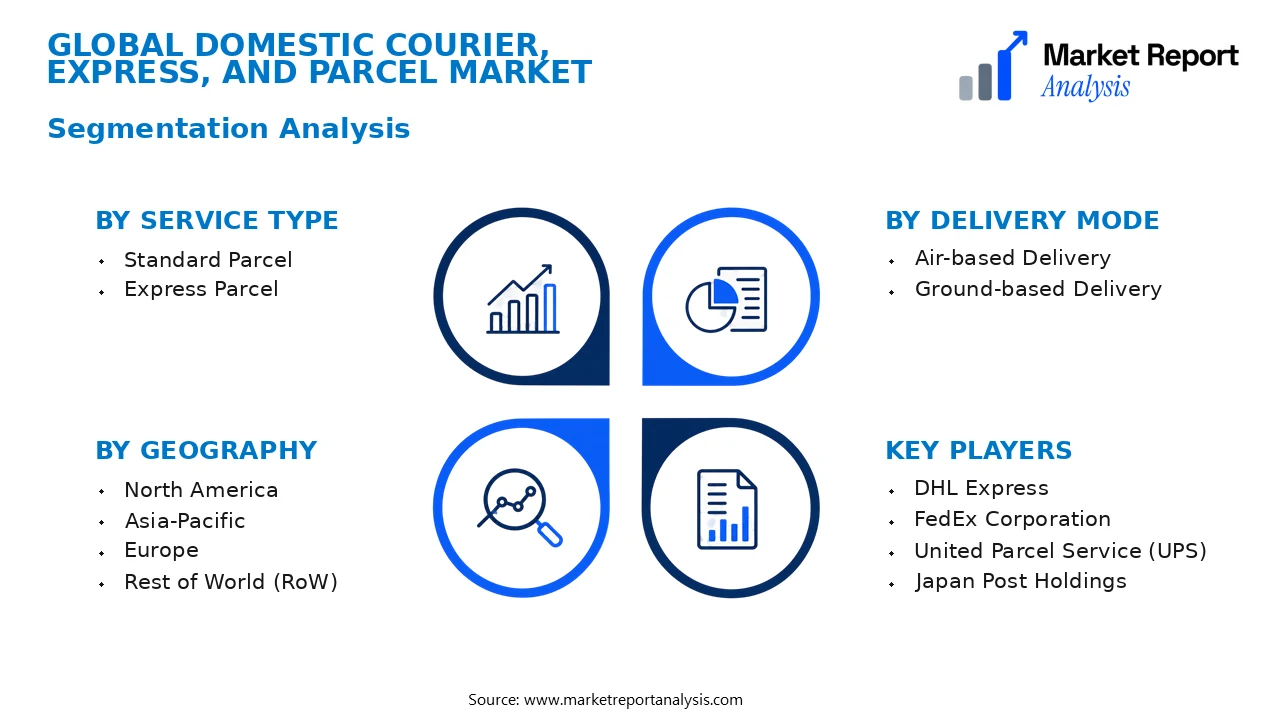
- Service Type
- Standard Parcel: This subsegment encompasses basic parcel delivery services aimed at cost-conscious consumers and businesses for non-urgent shipments, driving volume growth through competitive pricing and widespread accessibility.
- Express Parcel: Focused on faster delivery times, this subsegment caters to time-sensitive shipments, high-value goods, and just-in-time supply chains, often commanding premium pricing and experiencing rapid demand growth.
- Delivery Mode
- Air-based Delivery: Utilizing air freight for rapid transit over longer distances within countries, this mode caters to high-value, urgent, and perishable goods, supporting the premium segment of the market.
- Ground-based Delivery: Involving trucks, vans, and bikes, this mode is predominant in urban and suburban deliveries, offering cost-efficient solutions for volume-based parcel deliveries across regions.
- Geography
- North America: Characterized by advanced logistics infrastructure and high e-commerce penetration, this region exhibits significant demand for both standard and express parcel services, fostering innovation and consolidation.
- Asia-Pacific: The fastest-growing segment due to expanding middle-class populations, increased e-commerce activities, and urbanization, with diverse markets ranging from emerging economies to established logistics hubs.
- Europe: Known for stringent regulations and mature logistics networks, this region emphasizes sustainability and efficiency, with high adoption rates of technology-driven delivery solutions.
- Rest of World (RoW): Encompassing Africa, Latin America, and parts of the Middle East, this region presents emerging markets with opportunities for growth driven by infrastructural development and rising e-commerce adoption.
Competitive Intelligence
The competitive landscape of the global Domestic Courier, Express, and Parcel Market is marked by high competition and increasing market concentration among leading players. Companies such as FedEx, DHL, UPS, and local incumbents are aggressively pursuing strategic initiatives to enhance market share through diversification, technological innovation, and geographical expansion. Business strategies predominantly focus on expanding service networks, investing in automation, and deploying AI-driven route optimization systems to reduce costs and improve delivery efficiency. Recent years have seen significant product innovation, particularly in real-time tracking, drone delivery, and contactless delivery solutions, to meet evolving customer expectations.
Partnerships and acquisitions play a vital role in strengthening regional presence and technological capabilities; for instance, collaborations with e-commerce giants enable better last-mile logistics. Market leaders are also investing heavily in R&D to differentiate their offerings and develop sustainable delivery models, including electric delivery vehicles and eco-friendly packaging. Competitive differentiation increasingly hinges on service reliability, customer experience, and technological integration, which are crucial for capturing market share in a highly dynamic environment.
Leading Company Profiles
The competitive landscape of the domestic courier, express, and parcel market features several key players that drive innovation, expand capacity, and enhance service offerings through strategic investments and technological advancements.
- DHL Express
- FedEx Corporation
- United Parcel Service (UPS)
- Japan Post Holdings
- SF Express
- China Post Group
- Royal Mail Group
- Deutsche Post DHL Group
- CJ Logistics
- Nippon Express
DHL Express
DHL Express is renowned for its rapid global delivery network, innovative logistics solutions, and strong focus on sustainability initiatives, positioning itself as a leader in premium courier services across the domestic and international markets.
FedEx Corporation
FedEx offers comprehensive e-commerce, small package, and freight services, leveraging advanced automation, predictive analytics, and sustainable practices to enhance delivery efficiency while expanding its technological capabilities worldwide.
United Parcel Service (UPS)
UPS specializes in parcel delivery, supply chain management, and integrated logistics solutions, maintaining competitive edge through automation, environmental sustainability projects, and expansion of its last-mile delivery network.
Japan Post Holdings
Japan Post Holdings combines postal services with courier logistics, focusing on digital transformation and expansion into cross-border e-commerce logistics to cater to growing international parcel demand within Japan and Asia.
SF Express
SF Express is a major Chinese logistics provider emphasizing last-mile delivery, technological innovations such as AI and robotics, and strategic investments to sustain leadership in China's rapidly expanding delivery market.
China Post Group
China Post Group plays a vital role in domestic and cross-border logistics, investing heavily in digital infrastructure and nationwide logistics networks to support China's e-commerce boom and international trade facilitation.
Royal Mail Group
Royal Mail focuses on optimized parcel and mail delivery, embracing automation, digital parcel management, and sustainability strategies to adapt to increasing e-commerce parcel volumes in the UK and Europe.
Deutsche Post DHL Group
Deutsche Post DHL leads innovation with its Supply Chain and eCommerce solutions, emphasizing sustainable logistics and digital services, while aggressively expanding in emerging markets with strategic acquisitions and partnerships.
CJ Logistics
CJ Logistics excels in freight forwarding, parcel delivery, and supply chain solutions across South Korea and Asia, prioritizing automation, smart logistics infrastructure, and strategic alliances with global platforms.
Nippon Express
Nippon Express leverages extensive domestic and international logistics networks, adopting digital tracking, robotics, and green logistics initiatives to strengthen its competitive stance in the global courier market.
Strategic Business Developments
- August 2023 – DHL Express – Launched new electric delivery vehicles – Enhances sustainability and reduces carbon emissions across key metropolitan areas.
- June 2023 – FedEx Corporation – Opened a new automated sorting facility – Significantly boosts processing capacity and operational efficiency in North America.
- May 2023 – United Parcel Service (UPS) – Formed strategic alliance with a leading e-commerce platform – Expands last-mile delivery capabilities and improves parcel tracking technology.
- April 2023 – Japan Post Holdings – Invested in cross-border e-commerce logistics network – Strengthens international parcel delivery services within Asia and to global markets.
- March 2023 – SF Express – Launched AI-powered delivery robots in urban centers – Improves delivery speed and customer service while reducing operational costs.
Frequently Asked Questions
What is the Domestic Courier, Express, and Parcel Market?
The Domestic Courier, Express, and Parcel Market encompasses the transportation services of parcels and documents within a country, facilitated by various logistics providers. It supports e-commerce, local businesses, and individual consumers by ensuring timely delivery of goods and parcels.
What is the current market size of Domestic Courier, Express, and Parcel Market?
As of 2026, the global Domestic Courier, Express, and Parcel Market is valued at approximately USD 1.5 Billion, reflecting robust growth driven by rising e-commerce activity, urbanization, and increasing consumer demand for rapid delivery services across regions.
What factors are driving the Domestic Courier, Express, and Parcel Market?
Key growth drivers include exponential growth in e-commerce, technological advancements in logistics, improved delivery infrastructure, customer preference for fast and reliable services, and the expansion of regional distribution networks, all contributing to market expansion and service innovation.
Which region dominates the Domestic Courier, Express, and Parcel Market?
North America currently leads the global market, fueled by high e-commerce penetration, a mature logistics infrastructure, and strong industry competition. The region's technological adoption and consumer demands continue to shape rapid growth in parcel delivery services.
Which segment is expected to grow the fastest?
The express parcel segment is projected to experience the fastest growth, driven by same-day and next-day delivery requests, especially within urban centers. Its higher value and immediacy requirements are fueling investments and innovations in express logistics.
Who are the leading companies operating in the Domestic Courier, Express, and Parcel Market?
Leading industry players include DHL, FedEx, United Parcel Service (UPS), China Post, and India Post. These companies are investing heavily in technology, network expansion, and service diversification to maintain market leadership amid intensifying competition.
Analyst Perspective
The long-term outlook for the domestic courier, express, and parcel market remains robust, driven by escalating e-commerce penetration and evolving consumer expectations. Market maturity varies regionally, with North America and Europe exhibiting high saturation but ongoing innovation opportunities, whereas Asia-Pacific continues its rapid expansion fueled by developing economies and increasing logistics infrastructure. Technologically, advancements such as automation, AI-driven route optimization, and integrated supply chain platforms are set to significantly enhance efficiency and reduce costs, creating substantial commercial opportunities in urban last-mile delivery and same-day service offerings. Investment priorities should focus on developing intelligent logistics networks, sustainable transportation solutions, and expanding digital infrastructure to accommodate the rising demand. Competitive intensity is expected to intensify as local incumbents and new entrants leverage technology to differentiate offerings. Regional growth potential remains significant in emerging markets, where infrastructural investments and rising consumption levels are creating fertile ground for expansion. Strategic positioning will require capacity enhancements, technological agility, and sustainable practices to capitalize on long-term growth trajectories.
