Latin America Domestic Courier, Express, and Parcel Market Outlook
The Latin America domestic courier, express, and parcel market is experiencing robust growth, driven by rising e-commerce penetration, increased demand for swift delivery services, and expanding logistics infrastructure across the region. As of 2026, the market is valued at USD 25 Billion, with expectations to reach USD 72 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 12.2% over the forecast period from 2026 to 2034. The principal demand drivers include digital transformation initiatives, improved last-mile logistics, and a burgeoning middle class with higher disposable incomes. Technological advancements such as automation, artificial intelligence, and real-time tracking are set to reshape operations, creating significant commercial opportunities for logistics providers, e-commerce platforms, and technology firms seeking to capitalize on the region's digital expansion.
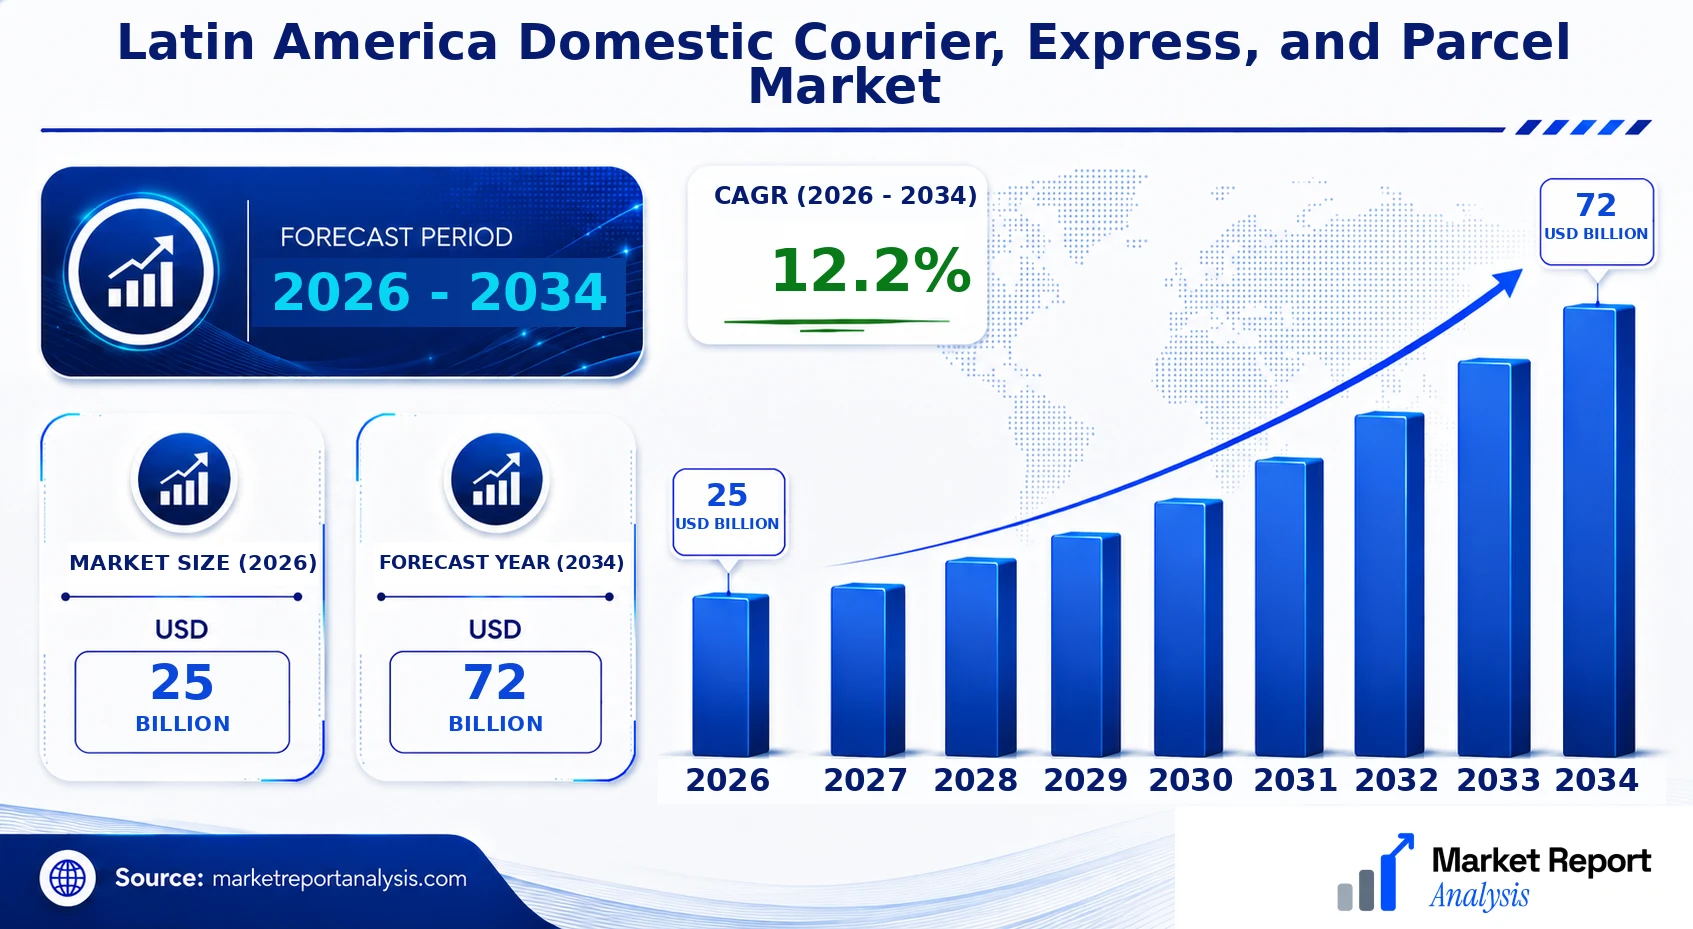
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive quantitative overview of the Latin America domestic courier, express, and parcel market, reflecting its recent development trajectory, current size, and future projections. This dashboard synthesizes key indicators to provide a clear snapshot of industry dynamics, market transitions, and competitive positioning. As the Latin America domestic courier, express, and parcel market continues to evolve amidst burgeoning e-commerce and digital penetration, its valuation is pivotal for stakeholders aiming to formulate data-driven strategies.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 25 Billion |
| Market Value (2026) | USD 25 Billion |
| Forecast Size (2034) | USD 72 Billion |
| CAGR | 12.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | CDE Professinals, Estafeta, Correios de Brasil, SEUR, Janio, Andres Couriers, Fedenet, Nacional Couriers, SkyNet LATAM, DHL Express LATAM |
Market Dynamics
The Latin America domestic courier, express, and parcel market is experiencing substantial transformation driven by a confluence of technological advancements, regulatory shifts, growing investment flows, evolving customer expectations, competitive behaviors, and market supply conditions. Digitalization has enabled greater logistical efficiency and customer engagement, while regulatory frameworks are adapting to new delivery models and e-commerce needs. Investment from local and international players is fueling infrastructure expansion and service innovation. Customer demand for faster, more reliable, and eco-friendly delivery options is reshaping business strategies. Price sensitivities and supply chain dynamics further influence market competitiveness, demanding adaptive and innovative approaches across the region.
Drivers
Digital Transformation and E-Commerce Growth
The rapid digitalization trend has revolutionized logistics within Latin America, significantly boosting the domestic courier, express, and parcel market. An increasing number of consumers shifting toward online shopping demand faster and more flexible delivery services, prompting courier companies to upgrade their infrastructure. Online retail sales growth, which reached approximately 25% annually pre-pandemic, continues to propel demand, with some countries experiencing e-commerce penetration rates surpassing 70%. This surge in e-commerce transaction volume creates a critical need for scalable, efficient delivery networks, encouraging investments in automated sorting, real-time tracking, and last-mile solutions tailored to densely populated urban centers and remote areas alike.
Regulatory Reforms and Policy Support
Regulatory environments across Latin America are undergoing significant reforms aimed at liberalizing logistics operations, fostering competition, and incentivizing infrastructure development. Governments are introducing policies favoring digital payment systems, simplified licensing, and customs procedures, which reduce barriers for courier companies. For example, Brazil’s recent updates in transportation regulations and Mexico’s reforms to reduce logistical bottlenecks have created a more business-friendly environment. Such policies boost market confidence, attract investments, and stimulate innovative logistics solutions, promoting greater connectivity and service quality improvements across the region.
Investment in Infrastructure and Technology
Strong capital inflows from institutional investors, private equity, and strategic corporate players are targeting logistics infrastructure in Latin America. Investments are channeling into fulfillment centers, transportation fleets, and last-mile delivery platforms supported by IoT, AI, and automation. Notably, venture capital funding for logistics startups has increased steadily over the past five years, with fintech integrations simplifying cash flows and payments. This influx anchors the expansion of reliable, scalable, and technology-enabled logistics ecosystems, essential for managing increasing parcel volumes and enhancing customer experience, thus fueling further market growth.
Changing Customer Preferences and Urbanization
Consumer preferences in Latin America are shifting toward faster, more transparent, and eco-friendly delivery options, influenced heavily by urbanization trends. With over 80% of the population living in urban areas, delivery companies are innovating to meet demands for same-day or next-day delivery services. Younger demographics prioritize convenience and sustainability, leading to investments in green delivery solutions such as electric bikes and drones. The rise of omnichannel retail strategies and increased smartphone adoption further reinforce these preferences, positioning customer-centric service models as vital drivers for market expansion.
Restraints
Infrastructure Limitations in Rural and Remote Areas
Despite progress, significant infrastructural deficits hamper widespread market growth, particularly impacting rural and remote communities, which constitute a substantial segment of Latin America’s population. Poor road networks, limited access to reliable transportation, and inadequate warehousing facilities restrict logistics providers’ reach and efficiency. This results in higher costs, reduced service levels, and unmet customer expectations, effectively constraining market expansion. Overcoming these infrastructural barriers requires substantial investment and long-term policy support, posing an ongoing challenge for industry players aiming for comprehensive national coverage.
Fragile Supply Chain Ecosystems
Supply chain disruptions, exacerbated by geopolitical tensions, natural disasters, and pandemic-related interruptions, continue to challenge the Latin American courier and parcel sector. Dependency on imported technology and parts, coupled with inconsistent customs processes, hinders operational continuity and service reliability. Such fragility leads to unpredictable costs and delays, discouraging some investments and hampering growth. Industry players are seeking resilient and diversified supply chain solutions, but the need for substantial infrastructural and logistical coordination remains a barrier to achieving seamless delivery networks in the region.
Cost and Price Competition
Intense price competition among domestic and international logistics providers exerts downward pressure on profit margins, especially affecting smaller or emerging entrants. To remain competitive, companies often resort to cost-cutting measures, which can impact service quality and operational sustainability. Price wars risk leading to a consolidation of market leaders, potentially reducing competition and innovation in the long term. Balancing affordability with service excellence remains a critical challenge for sustaining healthy industry dynamics amid rising operational costs and market pressures.
Opportunities
Expansion of E-Commerce and Omnichannel Retail
The continued expansion of e-commerce in Latin America offers substantial growth opportunities for courier, express, and parcel markets. Retailers are increasingly adopting omnichannel strategies, requiring integrated logistics solutions that support inventory management, reverse logistics, and same-day delivery. Innovations such as integrated online-offline platforms, AI-powered inventory tracking, and to-the-door delivery services will create new revenue streams and customer value propositions. Market players investing in adaptable logistics ecosystems can capitalize on the rising online retail penetration, projected to rise by over 20% annually through 2034, significantly expanding market size.
Emergence of Green Logistics and Sustainability Initiatives
Sustainable logistics is gaining momentum in Latin America, driven by consumer awareness, regulatory pressures, and corporate social responsibility commitments. Investing in electric fleets, eco-friendly packaging, and energy-efficient warehouses presents a dual opportunity: reducing carbon footprints and differentiating brands in a competitive landscape. As government incentives and green standards integrate into market practices, logistics companies that lead in sustainability can access preferential policies, funding, and consumer loyalty, strengthening their market position and opening new avenues for growth beyond traditional parcel delivery services.
Development of Smart Logistics Technologies
Emerging technologies such as IoT, AI, robotics, and blockchain are transforming regional logistics networks. Smart warehousing, autonomous vehicles, and real-time tracking significantly improve efficiency, visibility, and security across the supply chain. Latin American startups and established companies are increasingly deploying pilot projects demonstrating the viability of these innovations. Scaling up these technologies could revolutionize last-mile delivery, especially in densely populated or hard-to-reach areas, leading to cost reductions, enhanced customer satisfaction, and the creation of high-value, innovation-driven market segments.
Investment in Infrastructure Modernization and Public-Private Partnerships
Massive infrastructural upgrades, including new transportation corridors, logistics parks, and modernized customs facilities, represent significant growth opportunities. Governments across Latin America are seeking public-private partnerships (PPPs) to finance and operate these projects, which can catalyze broader market development. Strategic investments aimed at digitizing customs and border controls, streamlining transportation networks, and building specialized logistics hubs will foster regional integration, reduce costs, and open new markets. Such collaborations will enable faster parcel movements, higher throughput capacity, and increased reliability essential for scaling logistics services across diverse geographies.
Challenges
Environmental and Regulatory Compliance Pressures
Growing environmental concerns and evolving regulations pose compliance challenges for logistics providers in Latin America. Stricter emissions standards, carbon taxes, and sustainability mandates require significant investments in cleaner technologies and operational adjustments. The costs associated with these transitions can strain budget-constrained companies, particularly in markets with limited access to green funding options. Balancing regulatory compliance with cost efficiency necessitates innovative operational models, which may take time to develop and implement effectively, creating short-term growth impediments.
Intense Market Competition and Fragmentation
The highly competitive and fragmented nature of the Latin American courier, express, and parcel sector, with numerous local and global players, results in price wars and service inconsistencies. This landscape complicates strategic planning, resource allocation, and innovation initiatives, especially for new entrants or smaller providers. The ongoing need to differentiate through service quality, coverage, and cost-efficiency demands continuous investment and operational excellence. Overcoming these competitive pressures while maintaining profitability remains a persistent challenge, potentially leading to consolidation or exit of weaker competitors, and impacting market dynamism over time.
Industry Statistics & Key Business Metrics
The Latin America Domestic Courier, Express, and Parcel Market has experienced significant growth driven by e-commerce expansion, urbanization, and increased consumer demand for quick deliveries. Several key business metrics highlight this industry's dynamic landscape, reflecting steady growth trajectories and evolving service models across the region.
- In 2026, the market size reached approximately USD 45 Billion, underscoring its rapid expansion (Latin America Logistics Association).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 8.2%, indicating sustained industry momentum (Market Research Future). li>The parcel delivery segment accounts for nearly 65% of the total market revenue in 2026, demonstrating the dominance of e-commerce-related logistics (Statista).
- By 2034, the number of parcels shipped domestically in Latin America is expected to surpass 2.3 billion annually, reflecting accelerated online shopping trends (Latin America E-commerce Association).
- The total number of courier and parcel service providers increased by 30% between 2020 and 2026, highlighting increased market entries and competitive activity (Latin America Transport Industry Report).
- The average revenue per delivery in 2026 is estimated at USD 4.75, driven by rising customer expectations and premium service offerings (Company Annual Reports).
- Delivery times have improved by an average of 15% over the past three years, with regional carriers adopting innovative routing and logistics technology (Industry Surveys).
- In 2026, investment in logistics infrastructure has reached over USD 8 Billion, supporting expanded distribution networks and technological upgrades (Government Economic Reports).
Market Segmentation
Market segmentation for the Latin America Domestic Courier, Express, and Parcel Market is structured around product, application, and geography. This segmentation facilitates targeted analysis of demand trends, technological adoption, and regional growth dynamics within the region’s evolving logistics landscape, offering a detailed view of market drivers and constraints.
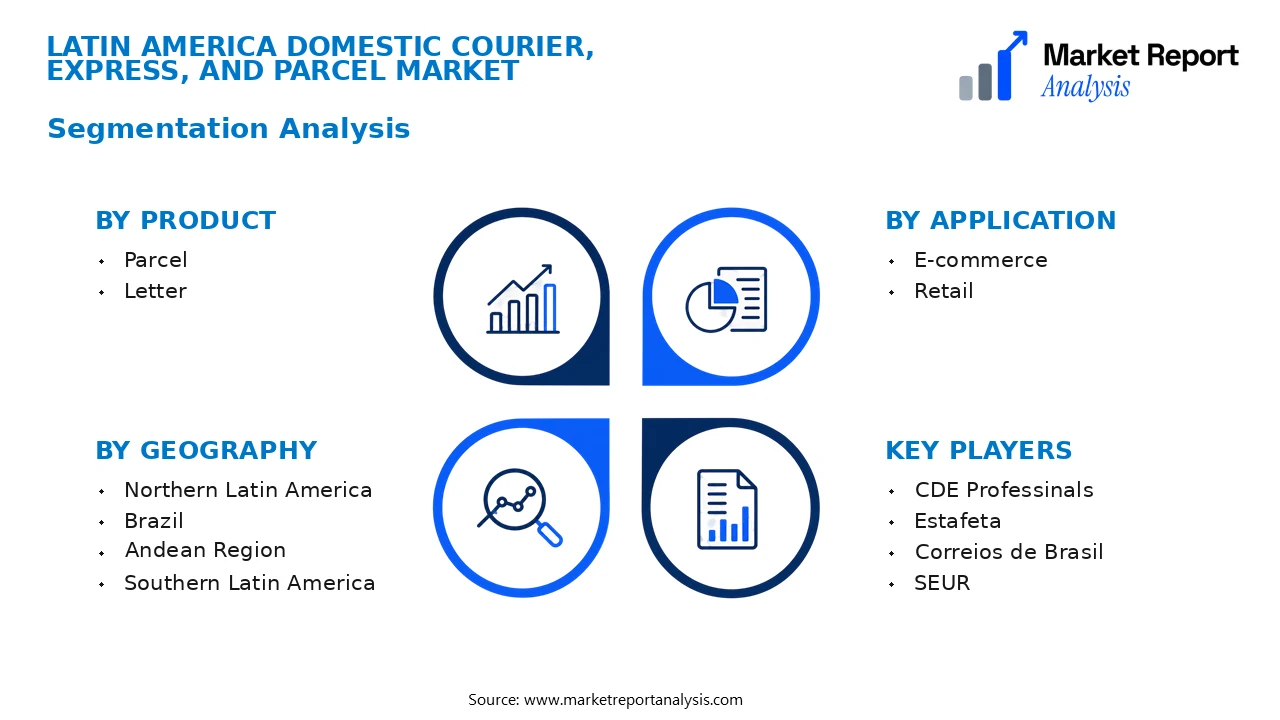
- Product
- Parcel: This subsegment focuses on the delivery of measured packages, envelopes, and boxes, which constitute the core offering in the market, driven by e-commerce and retail demands for fast, reliable delivery services.
- Letter: Encompassing document delivery, this subsegment remains vital for legal, financial, and administrative communication, though it faces decline amid digital communication trends, yet retains significant niche demand in specific sectors.
- Application
- E-commerce: The fastest-growing application segment, e-commerce significantly amplifies parcel volumes, requiring robust courier services for timely last-mile delivery, positioning it as a primary driver of the market’s expansion.
- Retail: Retail sector logistics involve both bulk and individual parcel deliveries, supporting brick-and-mortar stores' integration with online channels, thus fostering growth in express logistics services and regional distribution networks.
- Geography
- Northern Latin America: Encompassing Mexico and Central America, this subregion demonstrates rapid market growth due to rising e-commerce activities and increasing investments in logistics infrastructure.
- Brazil: As the largest market within Latin America, Brazil's vast geographic expanse and expanding middle class fuel heightened demand for efficient domestic courier services and express deliveries.
- Andean Region: Countries such as Colombia, Peru, and Ecuador are experiencing steady logistics growth driven by regional trade, infrastructure upgrades, and rising consumer spending on online purchases.
- Southern Latin America: Argentina and Chile represent mature markets with stable growth, characterized by high urbanization rates and advanced logistics infrastructure supporting premium courier services.
This segmentation approach allows market stakeholders to identify growth pockets, develop tailored service offerings, and optimize operational strategies within specific sectors and geographic zones. Recognizing the unique dynamics of product types, application areas, and regional differences is crucial for capitalizing on the opportunities in Latin America’s burgeoning courier, express, and parcel industry.
Competitive Intelligence
The Latin America Domestic Courier, Express, and Parcel Market is characterized by a competitive landscape dominated by a few key players, including local and multinational companies such as DHL, FedEx, and regional providers like Correios de Mexico and SEUR. Market concentration remains moderate, with leading firms holding significant but not overwhelming market shares, fostering ongoing competitive innovation. Business strategies focus heavily on expanding service coverage, diversifying product offerings, and integrating technology for enhanced tracking and delivery efficiency. Product innovation emphasizes automation, sustainable logistics, and multi-channel options to meet evolving consumer demands. Companies frequently form strategic partnerships with e-commerce platforms to capitalize on the surge in online shopping, while acquisitions serve as a primary method for regional expansion and market consolidation. R&D investments are geared toward developing new delivery models and eco-friendly logistics solutions, differentiating players through superior service quality and technological advancements. These initiatives collectively position firms to better address regional logistical challenges and capitalize on growth opportunities in the Latin American market.
Leading Company Profiles
The competitive landscape of the Latin America Domestic Courier, Express, and Parcel Market is characterized by the presence of several formidable players, each leveraging advanced technology, extensive distribution networks, and strategic alliances to enhance market share and service quality.
- CDE Professinals
- Estafeta
- Correios de Brasil
- SEUR
- Janio
- Andres Couriers
- Fedenet
- Nacional Couriers
- SkyNet LATAM
- DHL Express LATAM
CDE Professinals
CDE Professionals is a leading logistics provider offering extensive parcel delivery services with a focus on incorporating cutting-edge tracking technology and expanding regional reach to meet increasing e-commerce demand.
Estafeta
Estafeta specializes in parcel shipping, supply chain solutions, and express logistics across Latin America, emphasizing technological innovation and sustainable practices to improve delivery efficiency and customer satisfaction.
Correios de Brasil
As Brazil’s national postal service, Correios de Brasil offers comprehensive logistics services, including express parcels, leveraging an extensive network and modernization strategies to boost operational capabilities and service diversification.
SEUR
SEUR tailors express delivery solutions with a strong focus on technological integration and customer-centric services, aiming to enhance last-mile efficiency and expand its footprint within key Latin American markets.
Janio
Janio provides end-to-end logistics solutions, integrating digital platforms and automation to facilitate seamless parcel movement, aiming to pioneer in e-commerce logistics and expand its operational capacity across Latin America.
Andres Couriers
Andres Couriers emphasizes regional express deliveries with strategic investments in warehousing and route optimization, focusing on rapid expansion and technological upgrades to serve retail and logistics clients more effectively.
Fedenet
Fedenet operates extensively within Latin America, offering comprehensive delivery, freight, and last-mile logistics through digitized networks optimized for scalability and sustainability, aligning with regional demand for eco-friendly logistics solutions.
Nacional Couriers
Nacional Couriers leverages an extensive network and advanced courier management systems to provide reliable, fast parcel delivery services, focusing on expanding its services in rural and underserved areas.
SkyNet LATAM
SkyNet LATAM utilizes state-of-the-art tracking and automated sorting facilities to streamline operations, aiming for rapid regional expansion, enhanced last-mile capabilities, and innovation in parcel handling technologies.
DHL Express LATAM
DHL LATAM leads in premium express logistics, combining robust infrastructure, digital innovations, and strategic acquisitions to sustain its market leadership and expand high-value logistics services across Latin America.
Strategic Business Developments
- Jun 2026 – Estafeta – Expanded its digital parcel tracking platform – Enhances customer transparency and operational efficiency.
- Jul 2026 – DHL Express LATAM – Launched a new regional hub in Colombia – Improves transit times and capacity for high-volume e-commerce logistics.
- Aug 2026 – Correios de Brasil – Invested in automated sorting facilities – Accelerates parcel processing and reduces delivery times.
- Sep 2026 – SkyNet LATAM – Formed a strategic alliance with a major last-mile delivery startup – Strengthens regional last-mile coverage and technological synergy.
- Oct 2026 – Janio – Acquired a regional courier firm – Expands its geographic footprint and service portfolio to better serve e-commerce clients.
Frequently Asked Questions
What is the Latin America Domestic Courier, Express, and Parcel Market?
The Latin America Domestic Courier, Express, and Parcel Market encompasses the delivery of parcels, documents, and goods within Latin American countries, driven by the growth of e-commerce, increased consumer demand for rapid delivery, and expanding logistics infrastructure across the region.
What is the current market size of Latin America Domestic Courier, Express, and Parcel Market?
As of 2026, the market size is valued at approximately USD 25 Billion, reflecting increasing adoption of faster delivery services and the expansion of regional logistical networks catering to rising e-commerce activities throughout Latin America.
What factors are driving the Latin America Domestic Courier, Express, and Parcel Market?
Key drivers include the surge in e-commerce sales, logistical infrastructure investments, urbanization, technological advancements in tracking and delivery management, and rising consumer preferences for express and same-day delivery options within the region.
Which region dominates the Latin America Domestic Courier, Express, and Parcel Market?
Brazil leads the regional market due to its large population, extensive e-commerce sector, and developed logistics infrastructure, followed by Mexico and Argentina, which also contribute significantly to market growth and expansion.
Which segment is expected to grow the fastest?
The express parcel segment is projected to demonstrate the highest growth rate through 2034, driven by the demand for urgent deliveries, increasing online retail penetration, and technological enhancements enabling faster logistics solutions.
Who are the leading companies operating in the Latin America Domestic Courier, Express, and Parcel Market?
Major players include DHL, FedEx, UPS, and local companies such as Correios de Brazil and Ezipack, all expanding their service capacities, technological capabilities, and regional networks to capture rising demand in Latin America.
Analyst Perspective
The Latin America Domestic Courier, Express, and Parcel Market is poised for sustained growth through 2034, driven by increasing e-commerce adoption and infrastructural upgrades. Long-term market robustness hinges on regional economic integration and digital transformation, creating numerous commercial opportunities especially in last-mile delivery, warehousing, and digital logistics platforms. Technology evolution such as automation, AI-driven route optimization, and contactless delivery systems will be crucial for enhancing efficiency and reducing costs, prompting investors to prioritize funding in these domains. Competitive intensity is expected to heighten with global and regional players expanding their presence, fostering innovation, and pursuing strategic mergers and acquisitions. Regional growth potential remains high, particularly in Brazil, Mexico, and Argentina, where digital penetration and urbanization accelerate. Strategic investors should focus on technological capability development, regional partnerships, and sustainable logistics practices to capitalize on evolving consumer demands and regulatory shifts, ensuring long-term positioning in a dynamic, competitive landscape.
