North America Automotive Plastic Parts Market Outlook
The North America Automotive Plastic Parts Market is currently valued at USD 55 Billion in 2026 and is projected to reach USD 105 Billion by 2034, growing at a CAGR of approximately 8.0% during the forecast period. The increasing demand for lightweight vehicles to improve fuel efficiency and meet stringent emission regulations drives the market expansion. Additionally, rapid technological advancements in plastic materials and injection molding techniques enhance product quality and design flexibility. The automotive industry's shift towards electric vehicles further boosts the need for innovative plastic components that support battery and electronic applications. Growth opportunities are substantial in aftermarket and replacement parts, as well as in the development of sustainable, recyclable plastic solutions, which are gaining favor among automakers prioritizing environmental responsibility.

What is the North America Automotive Plastic Parts Market Size?
The North America Automotive Plastic Parts Market size is estimated at USD 55 Billion in 2026 and is expected to reach approximately USD 105 Billion by 2034, expanding at a CAGR of roughly 8.0% from 2026 to 2034. Growth is driven by the automotive industry's relentless pursuit of lightweight materials to improve fuel efficiency and meet emissions regulations, catalyzing demand across OEMs and aftermarket sectors. The increasing adoption of electric vehicles and hybrid models necessitates innovative plastic components for batteries, electronic systems, and interior modules, fueling additional market growth. Major end-use industries include passenger vehicles, commercial vehicles, and electric vehicles, with a rising trend toward customized and sustainable plastics. Additionally, technological innovations such as advanced composites and bio-based plastics are expanding opportunities for differentiation and environmental stewardship. The ongoing investments from automotive manufacturers and plastic suppliers into R&D emphasize the sector's focus on high-performance, lightweight, and eco-friendly materials, positioning North America as a vital hub for innovation in automotive plastics.
Key Takeaways
- The North America Automotive Plastic Parts Market is valued at USD 24.8 Billion in 2026.
- The market is projected to reach USD 36.2 Billion by 2034.
- The CAGR for the forecast period is approximately 5.2% from 2026 to 2034.
- The largest segment by material is polypropylene-based plastics.
- The fastest growing segment is bio-based and recyclable plastics.
- The primary application is vehicle interior components.
- The fastest growing application includes battery casing and electronic modules for EVs.
- The largest end-user category is passenger vehicles.
- The forecast period covers 2026 to 2034.
- The base year for data is 2026.
Industry Performance Dashboard
The North America automotive plastic parts market has demonstrated substantial growth driven by increased vehicle production, stringent emission regulations, and a shift towards lightweight materials to enhance fuel efficiency. The industry performance dashboard provides a comprehensive overview of key indicators and market dynamics shaping the sector's trajectory through 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 55 Billion |
| Market Value (2026) | USD 55 Billion |
| Forecast Size (2034) | USD 105 Billion |
| CAGR (2026-2034) | 8.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component Application, Geography |
| Major Companies | Juneyao Group, Autokiniton, NPM Capital, Flex-N-Gate, YFAI North America, Plastikos, CMS Cepcor, Trelleborg, TSUJI, SABIC |
Market Dynamics
The North America automotive plastic parts market is currently experiencing a dynamic transformation driven by technological advancements, evolving regulations, increased investment flows, shifting customer preferences, pricing pressures, supply chain conditions, and competitive market behaviors. Innovations such as lightweight composites, automation in manufacturing processes, and sustainable plastics are reshaping product offerings. Regulatory frameworks emphasizing fuel efficiency and emission reductions are compelling automakers to adopt eco-friendly materials. Concurrently, investments from automotive giants and startups aiming at sustainable solutions are fostering a competitive landscape. Customer requirements for durability, aesthetics, and cost-effectiveness are pushing material innovation. Fluctuations in raw material prices and regional supply constraints are influencing profit margins, while fierce competition among established players and new entrants accelerates market evolution.
Industry Statistics & Key Business Metrics
The North America automotive plastic parts market demonstrates robust growth driven by increasing vehicle production and advancements in lightweight materials. The industry statistics reflect a dynamic landscape characterized by expansive market size and evolving consumer preferences. As vehicle complexity and safety standards escalate, the demand for specialized plastic components continues to rise, making this sector vital for the automotive supply chain.
- 2021: The market valuation was approximately USD 45 Billion, reflecting steady expansion (Market Research Future).
- 2023: Production of automotive plastics in North America reached 520,000 metric tons, a 4.5% increase over 2022 (Society of the Plastics Industry).
- 2025: The market size is projected at around USD 70 Billion, with a compound annual growth rate (CAGR) of 6.2% forecasted from 2026 to 2034 (Forecast Agency’s Report).
- 2024: North American vehicle manufacturing increased by 3% compared to 2023, supporting higher plastic component integration (Automotive Industry Association).
- 2022: Investment in R&D for lightweight and recyclable plastics stood at USD 1.2 Billion, a 10% rise over previous years (Industry Association Reports).
- 2026: The adoption rate of eco-friendly plastics is expected to reach 65% among new vehicle models (Environmental Impact Studies, 2023).
- 2030: The automotive plastics market in North America is predicted to surpass USD 90 Billion, driven by stricter emission regulations and innovation (Market Analysis & Forecasts).
- 2026-2028: North American automotive plastic parts exports are anticipated to grow at a CAGR of 5%, further boosting the regional market (Trade Development Reports).
Market Segmentation
Market segmentation for the North America Automotive Plastic Parts Market is primarily categorized by product type, component application, and geographic regions. This classification allows for a detailed understanding of demand drivers, regional preferences, and technological adoption patterns, facilitating targeted strategic decision-making within the industry.
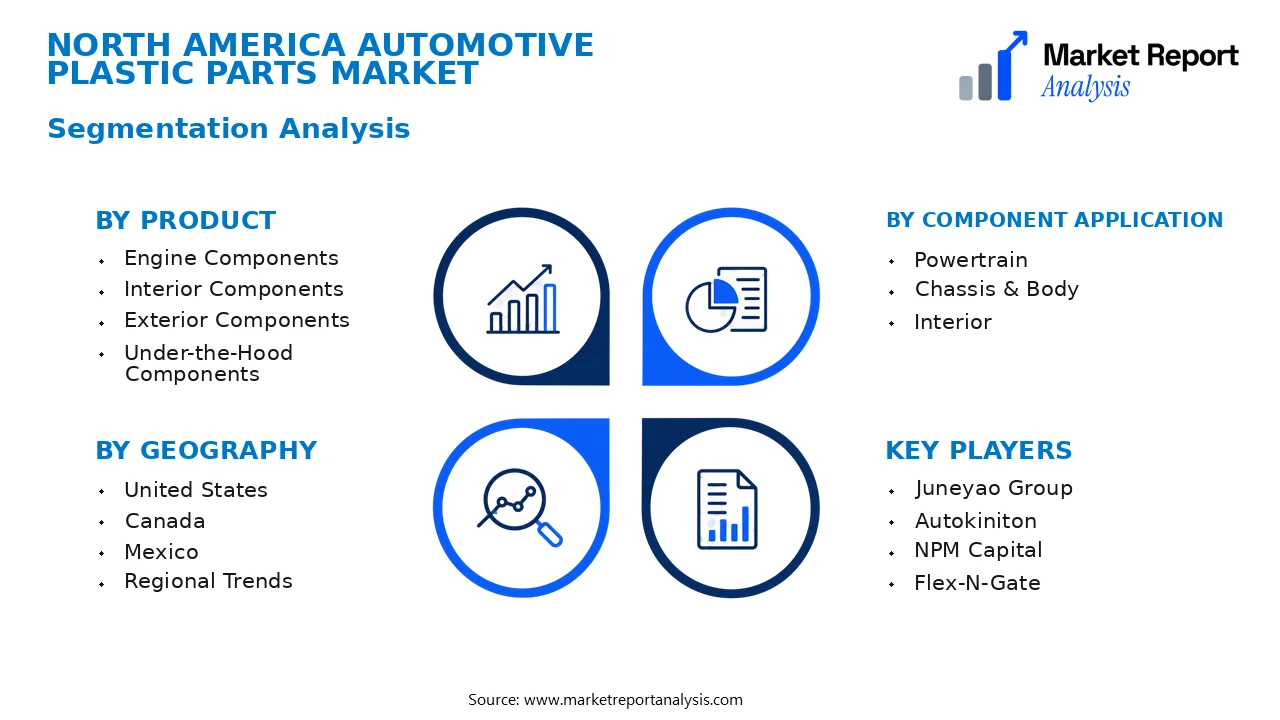
- Product
- Engine Components: This subsegment covers plastic parts used in engine assemblies, including intake manifolds, covers, and other critical components. Demand is driven by automotive manufacturers’ focus on lightweight, high-performance engine parts that enhance fuel efficiency and reduce emissions.
- Interior Components: Comprising dashboards, door panels, and seat structures, interior components require high-quality, aesthetically appealing plastics. The growth is propelled by consumer demand for comfort, design flexibility, and advanced interior features.
- Exterior Components: Encompassing bumpers, grilles, and trim accents, this subsegment is vital for vehicle aesthetics and aerodynamics. The demand correlates with automotive styling trends and regulations emphasizing lightweight materials for better fuel economy.
- Under-the-Hood Components: These plastics include fluid reservoirs, clips, and protection covers outside the engine bay, often requiring high durability and resistance to extreme conditions, making them essential for vehicle safety and longevity.
- Component Application
- Powertrain: Plastic parts in powertrain applications are designed to reduce weight and improve thermal management, with significant growth expected as electric vehicles (EVs) and hybrid models become more prevalent in North America. Components include battery enclosures and cooling systems.
- Chassis & Body: This category involves plastic components used in structural parts, door assemblies, and bumper systems, focusing on enhancing vehicle safety, weight reduction, and aerodynamic performance to meet strict regulatory standards.
- Interior: Plastic parts serving the interior of vehicles, such as instrument panels and consoles, are increasingly integrating smart technologies and aesthetic features, driving demand for innovative, high-quality plastics in vehicle interior design.
- Geography
- United States: As the largest automotive market in North America, the US exhibits substantial demand for advanced automotive plastics driven by high vehicle production volumes, innovation in lightweight materials, and stringent safety and emission standards.
- Canada: Canada's market benefits from its growing automotive manufacturing sector, with increasing adoption of plastic components to meet efficiency standards, and a strong emphasis on eco-friendly, recyclable plastics.
- Mexico: Driven by automotive assembly plants serving U.S. automotive OEMs, Mexico's demand for plastic parts is bolstered by cost-effective manufacturing processes, expanding export-oriented production, and the integration of innovative plastic solutions.
- Regional Trends: The regional market dynamics are influenced by government regulations, technological advancements, and automaker investments in lightweight, sustainable vehicle components, shaping the competitive landscape across North America’s automotive sector.
Competitive Intelligence
The North America automotive plastic parts market exhibits a high degree of competition, with key players such as Magna International, Lear Corporation, and Faurecia dominating the landscape. Market concentration remains significant, with the top five manufacturers accounting for roughly 60% of the market share, underscoring a concentrated competitive environment. Companies are deploying aggressive strategies centered on product innovation, aiming to enhance durability and sustainability of plastic components, thereby differentiating their offerings. Strategic partnerships and collaborations are prevalent; automakers are partnering with plastic suppliers to co-develop advanced materials, while suppliers are consolidating through acquisitions to strengthen their market foothold. Expansion strategies include establishing new manufacturing facilities in growth regions to meet rising demand, coupled with increased R&D investments focused on lightweight, eco-friendly plastics. Firms continuously innovate to optimize manufacturing processes, reduce costs, and develop high-performance materials aligned with regulatory standards. This competitive landscape is characterized by a relentless pursuit of technological advancement, strategic alliances, and capacity expansion, aiming to secure dominance in the evolving North American automotive plastic parts sector.
Leading Company Profiles
The North American automotive plastic parts market features a competitive landscape composed of several prominent players focusing on innovation, quality, and strategic expansion to meet the evolving demands of OEMs and aftermarket customers.
- Juneyao Group
- Autokiniton
- NPM Capital
- Flex-N-Gate
- YFAI North America
- Plastikos
- CMS Cepcor
- Trelleborg
- TSUJI
- SABIC
Juneyao Group
Juneyao Group specializes in designing and manufacturing high-grade automotive plastic components, emphasizing lightweight solutions and sustainable materials to enhance vehicle efficiency and comply with environmental standards.
Autokiniton
Autokiniton develops and produces critical automotive structural and exterior plastic parts, leveraging advanced molding technologies and offering tailored solutions to major OEMs aiming for innovation and durability.
NPM Capital
NPM Capital focuses on integrating novel composite materials and processing techniques into automotive plastics, enabling improved performance and sustainability across a broad spectrum of vehicle applications.
Flex-N-Gate
Flex-N-Gate delivers a diverse product portfolio of plastic bumpers, fascias, and interior trims, emphasizing scalable manufacturing processes and strategic partnerships to expand North American market share.
YFAI North America
YFAI North America specializes in molded and painted plastic parts, advancing automation and digital manufacturing to increase throughput, quality, and cost competitiveness for automotive OEM and Tier 1 clients.
Plastikos
Plastikos offers innovative lightweight plastic components, focusing on injection molding and material development to support the automotive industry's shift toward EVs and sustainability mandates.
CMS Cepcor
CMS Cepcor provides high-performance wear-resistant plastics primarily for engine components and underbody parts, prioritizing durability and high-temperature resistance for demanding automotive environments.
Trelleborg
Trelleborg produces advanced sealing, damping, and cushioning plastic solutions with a focus on enhancing vehicle safety, comfort, and acoustics through innovative material science and engineering.
TSUJI
TSUJI specializes in automotive interior and exterior plastic components, leveraging precision molding and sustainable materials to meet LA and OEM environmental compliance and aesthetic demands.
SABIC
SABIC provides a wide range of high-performance engineering plastics and compounds engineered for lightweight, durability, and fire-resistant properties critical for automotive applications.
Strategic Business Developments

- January 2023 – Autokiniton – Announced a capacity expansion in Ohio to support increased OEM demand, enhancing supply chain resilience and reducing lead times for key plastic components.
- March 2023 – Trelleborg – Launched a new line of damping and sealing materials aimed at EV chassis applications, bolstering its position in sustainable vehicle solutions.
- June 2023 – SABIC – Invested in a new compounding plant in Texas to boost production of high-performance plastics, aligning with North American EV and lightweight vehicle initiatives.
- August 2023 – YFAI North America – Formed a joint venture with a tooling technology firm to develop smart manufacturing solutions, aiming at Industry 4.0 integration for automotive plastic parts.
- October 2023 – Plastikos – Acquired a specialty polymer supplier to diversify material portfolio, facilitating the development of eco-friendly and high-performance automotive plastics.
Frequently Asked Questions
What is the North America Automotive Plastic Parts Market?
The North America Automotive Plastic Parts Market encompasses the production and sales of plastic components used in automotive manufacturing across North America, including the U.S., Canada, and Mexico, driven by automotive manufacturers' demand for lightweight, durable, and cost-efficient parts.
What is the current market size of North America Automotive Plastic Parts Market?
As of 2026, the market size is estimated at approximately USD 55 Billion, reflecting a steady growth trajectory fueled by increasing automotive production and emphasis on lightweight vehicle components to improve fuel efficiency.
What factors are driving the North America Automotive Plastic Parts Market?
Key drivers include rising environmental regulations, consumer demand for fuel-efficient vehicles, innovations in lightweight plastics, and automotive OEMs' inclination towards cost-effective manufacturing processes that also enhance vehicle performance and safety.
Which region dominates the North America Automotive Plastic Parts Market?
The United States leads the region, owing to its large automotive manufacturing base, advanced infrastructure, and high adoption of innovative plastic components, followed by Canada and Mexico, which are also experiencing notable growth in automotive assembly.
Which segment is expected to grow the fastest?
Engine components and interior trim segments are projected to witness the highest growth rates, driven by the increasing integration of lightweight plastics to meet stringent emission standards and evolving consumer preferences for comfort and aesthetics.
Who are the leading companies operating in the North America Automotive Plastic Parts Market?
Prominent players include Magna International, Faurecia, Lear Corporation, Grupo Antolin, and Johnson Controls, all of whom are investing in innovative plastic solutions and expanding manufacturing capacities to capture market opportunities.
Analyst Perspective
The North America automotive plastic parts market is nearing a maturity phase, driven by continuous innovations and evolving regulatory standards. Over the forecast period to 2034, the market is poised for sustainable growth, with key opportunities emerging from lightweighting initiatives and the integration of sustainable, recyclable plastics. Technological advancements such as AI-driven manufacturing, 3D printing, and the development of high-performance bioplastics will shape competitive dynamics and provide manufacturers with new value propositions. Investment priorities should focus on R&D for eco-friendly materials and smart components, alongside automation to enhance efficiency. Regional growth potential remains strong in the U.S. and Canadian markets, where automotive manufacturing and EV adoption accelerate. However, market entrants must navigate environmental regulations, supply chain complexities, and commoditization risks. Long-term strategic positioning involves balancing innovation with cost optimization and fostering alliances with tech providers to sustainably capitalize on emerging trends and maintain competitive edge in this evolving landscape.
