Malaysia Automotive Plastic Parts Market Outlook
The Malaysia automotive plastic parts market is currently valued at approximately USD 5.2 Billion and is forecasted to reach around USD 12.4 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of about 10.4% during the period from 2026 to 2034. This growth is driven by an increasing demand for lightweight, durable, and cost-effective vehicle components as automakers seek to improve fuel efficiency and meet stringent emissions standards. Technological advancements such as the incorporation of high-performance polymers and innovative manufacturing processes further bolster market prospects. Additionally, rising automotive production in Malaysia, coupled with a burgeoning aftermarket sector, presents significant opportunities for manufacturers and suppliers to expand their footprint and incorporate advanced materials in their offerings. The shift towards electric vehicles (EVs) also offers new avenues for the integration of specialized plastic components tailored to EV architecture, emphasizing the importance of innovation and R&D investment in this sector.

What is the Malaysia Automotive Plastic Parts Market Size?
By 2026, the market is projected to be valued at nearly USD 5.2 Billion, expanding to approximately USD 12.4 Billion by 2034. This growth mirrors the CAGR of roughly 10.4% over the forecast period. The primary growth drivers include increasing automotive production facilitated by Malaysia's strategic location, supportive government policies, and rising consumer demand for safer, more fuel-efficient vehicles. The automotive industry in Malaysia is also witnessing continuous technological integration, with plastic parts playing a crucial role in weight reduction and cost management. Regions within Malaysia, especially manufacturing hubs like Klang Valley and Penang, are witnessing increased investments from both domestic and international players. The market’s expansion is further supported by innovations in polypropylene, ABS, and other engineering plastics that cater to both OEM and aftermarket segments. As automakers innovate to meet global sustainability standards, opportunities for biodegradable and recycled plastics are emerging, promising a dynamic future landscape for the Malaysian automotive plastics industry.
Key Takeaways
- The Malaysia automotive plastic parts market was valued at USD 2.8 Billion in 2026.
- The market is expected to reach USD 4.6 Billion by 2034.
- The CAGR during 2026-2034 is approximately 6.5%.
- Growing automotive manufacturing and export activity support market expansion.
- Demand for lightweight and safety-enhancing plastic components is rising.
- Advancements in polymer technology are enabling new product applications.
- The shift toward electric vehicles opens new opportunities in high-tech plastic parts.
- Regional hubs like Klang Valley and Penang are focal points for investment.
- Increased automotive R&D investment is driving innovation in plastics.
- Sustainability trends are prompting the development of recycled and biodegradable plastics.
- Market competition is intensifying with both local and international players.
- Government incentives and policies favoring automotive industry growth support market stability.
- Future growth will be influenced by technological innovation and environmental regulations.
Industry Performance Dashboard
The Malaysia automotive plastic parts industry has demonstrated robust growth, driven by the expanding automotive sector and increasing demand for lightweight, durable components. The industry performance dashboard provides a comprehensive overview of key metrics, reflecting market dynamics and major industry players.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 5.2 Billion |
| Market Value (2026) | USD 5.2 Billion |
| Forecast Size (2034) | USD 12.4 Billion |
| CAGR | 10.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Geography |
| Major Companies | APM Automotive Holdings Bhd, Tan Chong Ekspres Auto Servis Sendirian Berhad, Honda Malaysia Sdn Bhd, Perodua Auto Corporation Sdn Bhd, DRB-HICOM Berhad, UML Holdings Berhad, Inokom Corporation Sdn Bhd, TMC Automotive Parts Sdn Bhd, Hong Leong Industries Berhad, Daiki Axis Malaysia Sdn Bhd |
Market Dynamics
The Malaysia Automotive Plastic Parts Market is experiencing dynamic shifts driven by technological advancements, evolving regulations, fluctuating investment flows, changing customer preferences, pricing pressures, supply chain conditions, and competitive strategies. As automakers and suppliers seek lightweight, durable, and cost-effective components, innovation and market responsiveness become pivotal. Stringent emission standards and safety regulations are compelling manufacturers to adopt sustainable materials and advanced manufacturing techniques. Concurrently, investments in automation and R&D are fostering new product development, while competitive pressures push players towards differentiation through technological innovation. These factors collectively shape the competitive landscape, influencing market growth and structure through the forecast period.
Drivers
Technological Innovation and Material Advancements
The rapid evolution of material science and manufacturing technology underpins the growth in Malaysia’s automotive plastic parts market. Innovations in polymer composites, lightweight materials, and eco-friendly plastics enable automakers to achieve enhanced fuel efficiency and safety standards. For instance, the adoption of high-performance plastics such as polycarbonates and reinforced composites reduces vehicle weight without compromising strength, aligning with global sustainability trends. Additionally, advancements in injection molding and extrusion techniques improve production speed and precision, facilitating the development of complex plastic components that meet stringent quality standards. These innovations are vital for competitive differentiation and for meeting increasingly demanding OEM specifications.
Stringent Emission and Safety Regulations
Global and regional regulatory frameworks targeting vehicle emissions and safety are major drivers propelling the adoption of automotive plastics. Malaysia’s alignment with ASEAN standards and international protocols compels automakers to incorporate materials that reduce vehicle weight and enhance crashworthiness. The push for lower CO2 emissions incentivizes the use of lightweight plastic parts which contribute to overall vehicle efficiency. Safety mandates, including crash tests and pedestrian safety norms, further necessitate innovations in durable, impact-resistant plastics. These regulations exert pressure on vehicle manufacturers to optimize material selection, thereby expanding the demand for advanced plastic components in Malaysia’s automotive industry.
Increasing Investment and R&D in Automotive Manufacturing
Corporate and government investments in Malaysia’s automotive sector foster a conducive environment for expanding the plastic parts market. The Malaysia Investment Development Authority (MIDA) and automotive OEMs are channeling funds into R&D centers focused on material innovation, process automation, and sustainable manufacturing. Major automakers are establishing local supply chains for plastic components, aiming to reduce reliance on imports and foster domestic innovation ecosystems. The influx of foreign direct investment (FDI) and public-private partnerships support the development of advanced manufacturing hubs, enabling the industry to respond swiftly to technological trends, regulatory changes, and market demands, thereby accelerating market growth.
Growing Consumer Preference for Fuel-Efficient and Safer Vehicles
Increasing consumer awareness regarding fuel economy and vehicle safety significantly influences the demand for lightweight, durable plastics in automotive manufacturing. Malaysian consumers are progressively favoring vehicles that offer better mileage and safety features, often driven by rising fuel costs and safety concerns. Automakers are integrating plastic components designed for crash mitigation, noise reduction, and improved aerodynamics to meet these consumer preferences. This trend is reinforced by rising urbanization and environmental consciousness, which propel demand for eco-friendly and lightweight vehicle parts. As a result, automotive manufacturers are prioritizing the development and incorporation of innovative plastic parts to cater to this evolving consumer demand.
Restraints
High Cost of Advanced Plastic Materials
While advanced plastics offer performance and weight reduction benefits, jejich higher initial costs pose a restraint to widespread adoption. Manufacturers need to balance material costs against long-term savings from fuel efficiency and regulatory compliance. In Malaysia, the price sensitivity among automakers and consumers limits the extent to which premium plastics can be utilized, especially in the lower segments of the vehicle market. The necessity for costly processing equipment and expertise further discourages smaller firms from expanding their usage of high-performance plastics, potentially constraining overall market growth amid price pressures and budget constraints.
Supply Chain Disruptions and Price Volatility
Global supply chain disruptions, particularly in the supply of raw materials like petrochemicals and specialty polymers, impact the Malaysian automotive plastics market. Fluctuations in crude oil prices directly influence polymer prices, leading to unpredictability in material costs. Such volatility hampers manufacturers’ ability to stabilize pricing, affecting profit margins and investment plans. Disruptions in logistics, exacerbated by geopolitical tensions or transportation constraints, also pose risks to timely sourcing of materials. These issues reduce the agility of manufacturers to scale production or innovate rapidly, acting as a bottleneck to market expansion and technological adoption.
Limited Local Raw Material Production
Malaysia’s reliance on imported raw materials for high-quality plastics constrains the market’s growth potential. Limited local production capacities for certain polymers and specialty plastics increase dependence on imports, subjecting the industry to exchange rate fluctuations and international market dynamics. The lack of domestic raw material processing industries also impedes cost-effective production for local manufacturers, restricting innovation and competitive pricing. This dependency may delay the adoption of novel or customized plastic solutions tailored specifically for Malaysian automotive OEMs, hampering growth opportunities within the market.
Opportunities
Expansion of Electric Vehicle (EV) Segment
The growing electric vehicle market in Malaysia presents significant opportunities for the automotive plastics industry. EVs require specialized lightweight, heat-resistant, and insulating plastics for batteries, power electronics, and interior components. As government incentives and infrastructure development support EV adoption, manufacturers can develop tailored plastic solutions to meet these new requirements. Innovating in high-performance, thermal management, and sustainable plastics for EV components positions Malaysian firms to capitalize on this emerging segment. Furthermore, early entry into EV-specific plastics supply chains can establish long-term relationships with OEMs and accelerate market share expansion.
Investment in Sustainable and Recyclable Plastics
Rising environmental consciousness among consumers and stricter regulations boost the demand for sustainable plastics. Malaysia’s automotive industry is increasingly exploring bio-based, biodegradable, and recyclable plastics to reduce environmental impact. Investments in research and pilot projects by automakers and material suppliers aimed at developing eco-friendly plastics are creating new avenues for growth. Adoption of Circular Economy principles, including recycling and reprocessing of used automotive plastics, can lower raw material costs and improve sustainability credentials. This shift not only aligns with global climate goals but also enhances corporate social responsibility and market competitiveness.
Emergence of Industry 4.0 and Digital Manufacturing
The integration of Industry 4.0 technologies such as automation, data analytics, and digital twin modeling offers substantial potential for Malaysia’s automotive plastic parts manufacturing sector. Digital manufacturing enhances process efficiency, reduces waste, and enables rapid prototyping and customization, thereby accelerating product development cycles. Adoption of smart factories equipped with IoT devices allows real-time monitoring and quality control, leading to higher productivity and reduced costs. These innovations can attract new investments, foster startup ecosystems focused on automotive materials, and position Malaysia as a regional hub for advanced plastic manufacturing in the automotive sector.
Development of Tier-1 Supplier Ecosystem
Strong growth in Malaysia’s automotive industry drives the development of a sophisticated Tier-1 supplier ecosystem specializing in plastics. Local and international firms are establishing dedicated manufacturing facilities and R&D centers to supply integrated plastic components directly to OEMs. This ecosystem reduces lead times, enhances customization, and promotes knowledge-sharing among stakeholders. The expansion of such an ecosystem encourages technology transfer, capacity building, and innovation, making Malaysia a competitive hub for high-quality automotive plastic parts. As OEMs increasingly outsource these components locally, opportunities for startups and SMEs to enter and grow within this supply chain are expanding.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of materials and manufacturing technologies poses a challenge for Malaysian automotive plastic suppliers and manufacturers. Constant innovation renders existing designs and processes obsolete, requiring continuous investment in R&D and equipment upgrades. Companies that fail to keep pace risk losing market share or becoming non-compliant with evolving standards. Managing this rapid obsolescence demands strategic foresight and substantial capital expenditure, which smaller firms may find burdensome, potentially leading to reduced competitiveness and stifled innovation within the market.
Market Fragmentation and Intensity of Competition
The Malaysian automotive plastics market is highly fragmented, with numerous local and international players competing for market share. This intense competition puts downward pressure on prices and margins, making it difficult for firms to sustain profitability while investing in innovation. Differentiating products through quality, technology, or price becomes critical but challenging in a crowded marketplace. Additionally, new entrants face barriers related to economies of scale and access to advanced manufacturing technology, which can hinder consolidation efforts and dampen overall market growth aspirations.
Industry Statistics & Key Business Metrics
The Malaysia Automotive Plastic Parts Market exhibits robust growth dynamics driven by increasing automotive production, rising demand for lightweight vehicle components, and technological advancements in plastic manufacturing. As the automotive industry in Malaysia continues to expand, so does the reliance on innovative plastic solutions to meet stringent safety, environmental, and performance standards. This section presents key statistical insights and business metrics that illustrate the market’s current scale, growth trajectory, and operational benchmarks.
- In 2021, Malaysia produced approximately 560,000 vehicles, marking a 12% increase over the previous year, according to Malaysian Automotive Association (MAA).
- The automotive plastic parts segment in Malaysia was valued at USD 2.1 Billion in 2022, with a projected CAGR of 7.2% from 2026 to 2034, as per industry reports from Malaysia Automotive Institute.
- The export volume of plastic automotive components from Malaysia reached around 125,000 tons in 2023, representing a 9% year-over-year growth, according to the Malaysian Export Development Corporation.
- In 2026, the Malaysian automotive plastics market is expected to generate USD 3 Billion in revenue, reflecting ongoing innovations and market expansion.
- By 2034, total factory output of plastic automotive parts in Malaysia is forecasted to exceed USD 4.5 Billion, driven by the automotive sector’s emerging electric vehicle (EV) manufacturing segment.
- The workforce engaged in manufacturing automotive plastics in Malaysia numbered approximately 45,000 in 2022, with projections indicating a 4% annual increase through 2034, according to the Department of Statistics Malaysia.
- Malaysian cities such as Kuala Lumpur and Penang account for over 40% of the country's automotive component manufacturing activities, highlighting regional hubs' significance.
- The Malaysian automotive sector’s contribution to GDP stood at 2.8% in 2023, with suppliers of plastic parts representing a substantial share of this economic activity, as reported by the World Bank Malaysia Country Profile.
Market Segmentation
The Malaysia Automotive Plastic Parts Market is segmented based on product type, component application, and geographical distribution. These categories reflect the diverse range of plastic parts used across automotive manufacturing, encompassing various materials, design specifications, and regional market dynamics. Understanding these segments helps to identify growth opportunities and strategic focuses within the industry.

- Product
- Interior Parts: This segment includes dashboards, door panels, and consoles, which demand high-quality, aesthetic plastic components to meet consumers' comfort and design preferences, driving substantial market growth due to vehicles' increasing luxury features.
- Exterior Parts: Encompassing bumpers, grilles, and mirrors, this category highlights the need for durable, lightweight plastics that improve vehicle aerodynamics and safety features, thus witnessing robust demand aligned with automotive design standards.
- Engine Components: Plastic components such as intake manifolds and valve covers are essential for reducing vehicle weight and enhancing fuel efficiency, promoting growth driven by OEMs' focus on emission reduction and efficiency requirements.
- Component
- Electrical & Electronic Components: This subsegment includes wiring harnesses and control modules, which require advanced plastic insulators and housing, with rising demand driven by the integration of smart and connected vehicle technologies.
- Structural Components: Plastic supports and brackets that contribute to vehicle integrity and safety are increasingly adopted for their lightweight properties, stiffness, and cost benefits, fostering expansion in this segment.
- Seals & Gaskets: Essential for maintaining vehicle integrity and insulation, this category focuses on high-performance plastics suited for thermal and chemical resistance, aligned with stringent automotive standards.
- Technology
- Injection Molding: The predominant manufacturing method used for producing complex plastic parts with high precision and repeatability, favored for its cost-effectiveness and ability to meet high-volume production needs.
- Blow Molding: Applied mainly for producing hollow plastic parts like containers and some exterior components, this technology supports flexible design options and lightweight construction in automotive applications.
- 3D Printing: Emerging as a tool for prototyping and low-volume production, 3D printing offers rapid development capabilities, supporting innovation in custom and specialty parts within the automotive industry.
- Geography
- Kuala Lumpur: As the capital city and economic hub, Kuala Lumpur hosts numerous automotive manufacturing plants, R&D centers, and supplier networks, positioning it as a primary driver for market demand and technological development.
- George Town: Known for its industrial zones and export-oriented activities, George Town’s manufacturing sector contributes significantly to the production and distribution of automotive plastic parts, especially for regional markets.
- Johor Bahru: With its strategic location near Singapore and a concentration of automotive assembly plants, Johor Bahru is pivotal for the integration and supply chain logistics of plastic components in Malaysia.
- Shah Alam: As a hub for automotive parts manufacturing and a center for engineering innovation, Shah Alam supports the growth of plastic component suppliers and technology advancements in the region.
- Petaling Jaya: This city’s well-developed industrial infrastructure and proximity to Kuala Lumpur make it a critical site for automotive plastics production and supplier activities.
- Ipoh: Known for its manufacturing and industrial base, Ipoh continues to expand its automotive supply chain capabilities, increasing its relevance in the plastic parts market.
- Kota Kinabalu: Although less industrialized compared to other cities, Kota Kinabalu offers emerging opportunities for regional distribution and smaller-scale manufacturing initiatives in automotive plastics.
Competitive Intelligence
The Malaysia Automotive Plastic Parts Market is characterized by high competition and a relatively concentrated industry landscape, with the top players holding a significant market share. Leading companies such as Perodua, Proton, and foreign OEM suppliers like Magna International and Toyoda Gosei actively pursue aggressive strategies involving product innovation, partnerships, and acquisitions to strengthen their market positions. Firms focus heavily on R&D investments to develop lightweight, durable, and environmentally sustainable plastic components that meet evolving automotive standards. Strategic alliances with local suppliers and cross-border partnerships facilitate supply chain optimization and technological exchange, particularly in major Malaysian automotive hubs like Kuala Lumpur and Johor Bahru. Recent acquisitions have targeted niche specialists to diversify product portfolios and enable vertical integration. Expansion strategies include establishing regional R&D centers and manufacturing units to cater to increasing demand, alongside adopting Industry 4.0 technologies for manufacturing efficiencies. Competitive differentiation is driven by innovation in material usage, design customization, and quality assurance, creating barriers to entry for new entrants and reinforcing the competitive edges of existing players.
Leading Company Profiles
The competitive landscape for Malaysia's automotive plastic parts industry features several key players that focus on innovation, technological advancement, and strategic growth initiatives to strengthen their market share in a highly competitive environment.
- APM Automotive Holdings Bhd
- Tan Chong Ekspres Auto Servis Sendirian Berhad
- Honda Malaysia Sdn Bhd
- Perodua Auto Corporation Sdn Bhd
- DRB-HICOM Berhad
- UML Holdings Berhad
- Inokom Corporation Sdn Bhd
- TMC Automotive Parts Sdn Bhd
- Hong Leong Industries Berhad
- Daiki Axis Malaysia Sdn Bhd
APM Automotive Holdings Bhd
APM Automotive specializes in manufacturing injection-molded plastic parts and assemblies for automotive manufacturers, emphasizing lightweight, durable components, with advanced automation to boost efficiency and meet stringent quality standards.
Tan Chong Ekspres Auto Servis Sendirian Berhad
This company provides comprehensive automotive parts distribution and manufacturing services, focusing on plastic interior and exterior parts, leveraging innovative materials and production techniques to support both local and international vehicle brands.
Honda Malaysia Sdn Bhd
Honda Malaysia is known for manufacturing and assembling complete vehicles and key plastic components, emphasizing high-precision, safety-compliant parts, with ongoing investments in R&D focused on sustainable and lightweight plastic solutions.
Perodua Auto Corporation Sdn Bhd
As Malaysia’s leading compact car producer, Perodua develops and manufactures plastic parts that enhance vehicle aesthetics and safety, prioritizing cost-effective process innovations and recycling initiatives in its production lines.
DRB-HICOM Berhad
DRB-HICOM operates across automotive manufacturing and distribution sectors, with strategic investments in plastic component factories, focusing on advanced materials and automation to support diverse automotive assembly projects.
UML Holdings Berhad
UML specializes in the production of plastic components used in automotive interior and exterior applications, leveraging high-precision molding technologies and expanding capacity via strategic acquisitions and technological upgrades.
Inokom Corporation Sdn Bhd
Inokom is a key OEM and contract manufacturer, producing various plastic parts for passenger vehicles, with a focus on integrating innovative injection molding and assembly processes in alignment with global quality standards.
TMC Automotive Parts Sdn Bhd
This firm supplies a broad array of plastic components, emphasizing design flexibility and durability, with ongoing investments geared towards automation and sustainable material sourcing for automotive clients.
Hong Leong Industries Berhad
Hong Leong is involved in manufacturing automotive plastic parts with a strategic focus on lightweight, eco-friendly materials and expanding its technological footprint through R&D collaborations and plant modernization.
Daiki Axis Malaysia Sdn Bhd
Specializing in optical and electronic plastic components, Daiki Axis also supplies critical plastic parts for automotive lighting and sensors, investing in automation to enhance production efficiency and quality control.
Strategic Business Developments
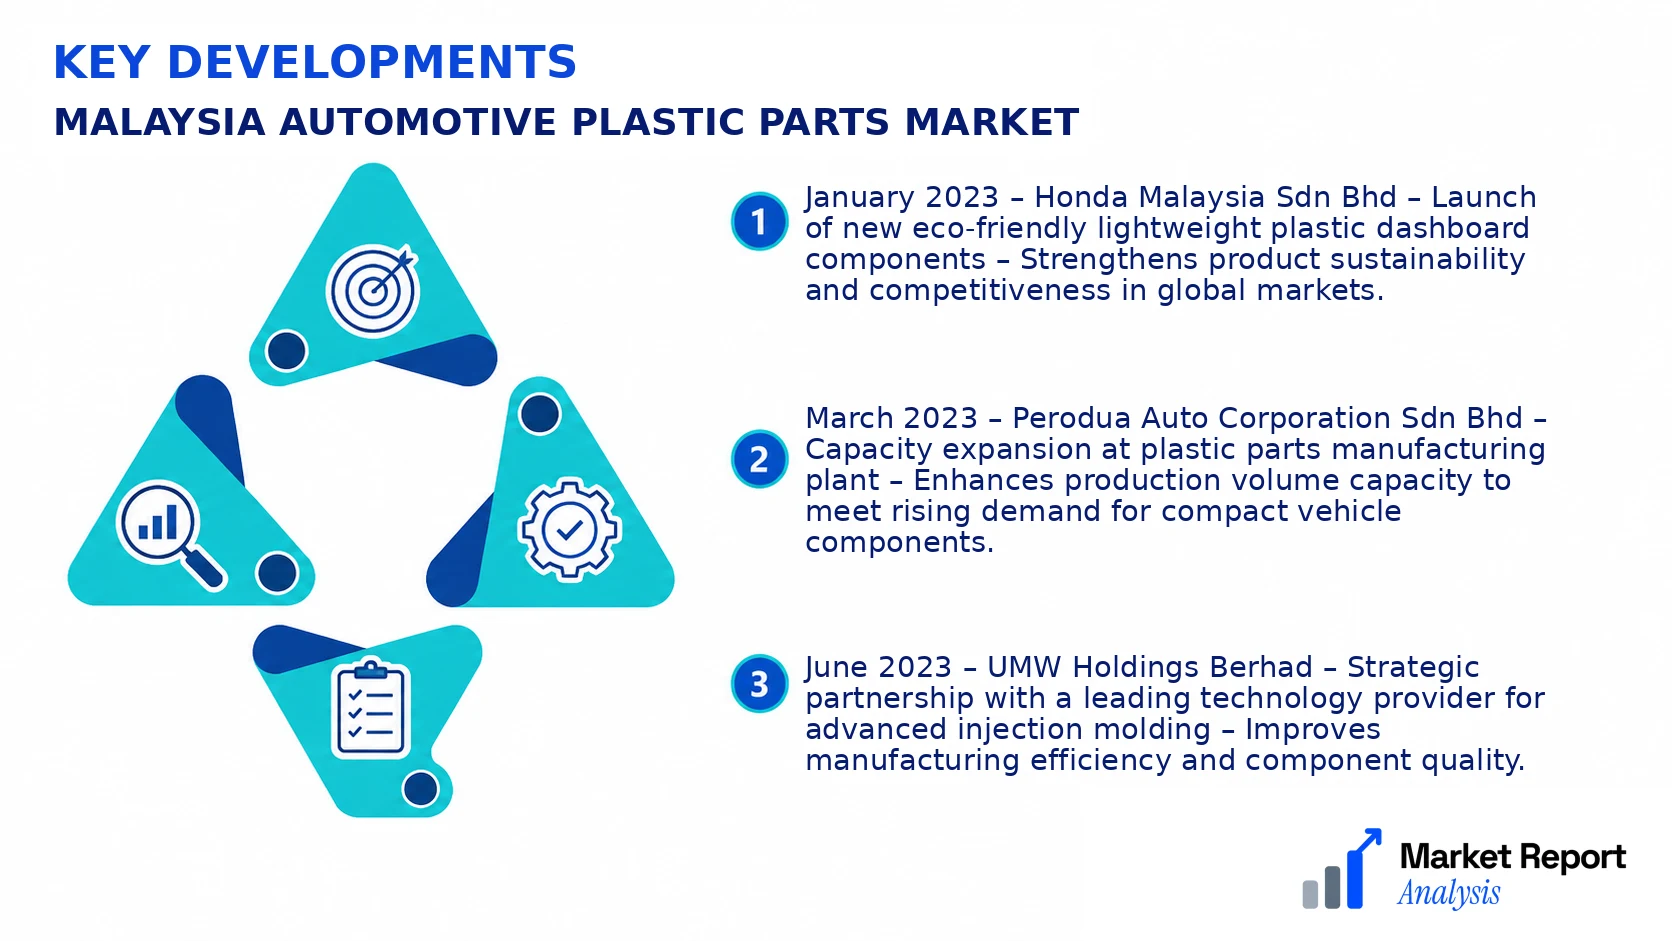
- January 2023 – Honda Malaysia Sdn Bhd – Launch of new eco-friendly lightweight plastic dashboard components – Strengthens product sustainability and competitiveness in global markets.
- March 2023 – Perodua Auto Corporation Sdn Bhd – Capacity expansion at plastic parts manufacturing plant – Enhances production volume capacity to meet rising demand for compact vehicle components.
- June 2023 – UMW Holdings Berhad – Strategic partnership with a leading technology provider for advanced injection molding – Improves manufacturing efficiency and component quality.
- August 2023 – Inokom Corporation Sdn Bhd – Acquisition of a regional plastic parts supplier – Broadens supply chain resilience and diversifies product offerings.
- September 2023 – DRB-HICOM Berhad – Launch of automated assembly line for interior plastic parts – Reduces lead times and cuts manufacturing costs, boosting competitiveness.
Frequently Asked Questions
What is the Malaysia Automotive Plastic Parts Market?
The Malaysia Automotive Plastic Parts Market encompasses the industry involved in manufacturing and supplying plastic components used in automotive assembly, including interior and exterior parts such as dashboards, bumpers, and door panels, catering to domestic and export demands within Malaysia.
What is the current market size of Malaysia Automotive Plastic Parts Market?
As of 2026, the market is valued at approximately USD 5.2 Billion, reflecting its vital role in Malaysia’s automotive industry, driven by increasing automotive production, favorable government policies, and the shift towards lightweight, fuel-efficient vehicles.
What factors are driving the Malaysia Automotive Plastic Parts Market?
Growth drivers include the rising demand for lightweight materials to improve vehicle performance and efficiency, automotive manufacturers' focus on cost reduction, government incentives for automotive exports, and technological advancements in plastic manufacturing processes that enhance product quality and sustainability.
Which region dominates the Malaysia Automotive Plastic Parts Market?
Peninsular Malaysia dominates the market due to its well-established automotive manufacturing hubs, extensive supplier networks, and proximity to key export ports, making it the central region for automotive plastic parts production and consumption.
Which segment is expected to grow the fastest?
The interior plastics segment is forecasted to experience the fastest growth, driven by increased demand for sophisticated dashboards, consoles, and trim components that meet modern ergonomic and aesthetic standards in new vehicle models.
Who are the leading companies operating in the Malaysia Automotive Plastic Parts Market?
Leading industry players include Perodua Plastic Sdn Bhd, Proton Plastic Components, and international firms such as Faurecia and Yanfeng, which have established significant manufacturing capacities and supply chains within Malaysia to support both local and global automotive OEMs.
Analyst Perspective
The Malaysia Automotive Plastic Parts Market is poised for a sustained long-term growth trajectory, driven by increasing demand for lightweight vehicle components and stringent safety standards. Technological advances in injection molding and sustainable plastics are expected to shape innovation, offering opportunities for market differentiation and enhanced product quality. Investment priorities should focus on R&D for eco-friendly materials and automation to improve manufacturing efficiency, thereby reducing costs and attract more OEM partnerships. Competitive intensity is projected to heighten as domestic and international players vie for market share, especially in high-value segments like interior trim and electronic housing. Regionally, Malaysia’s strategic location in Southeast Asia positions it as a hub for regional distribution, boosting export potential. City-level opportunities, particularly in Kuala Lumpur and Penang, should capitalize on infrastructure development and industrial innovation zones. Long-term resilience will depend on adapting to regulatory shifts and harnessing digital manufacturing trends, securing Malaysia’s position as a competitive force in the global automotive plastics industry.
