Japan Wearable Electronics Market Outlook
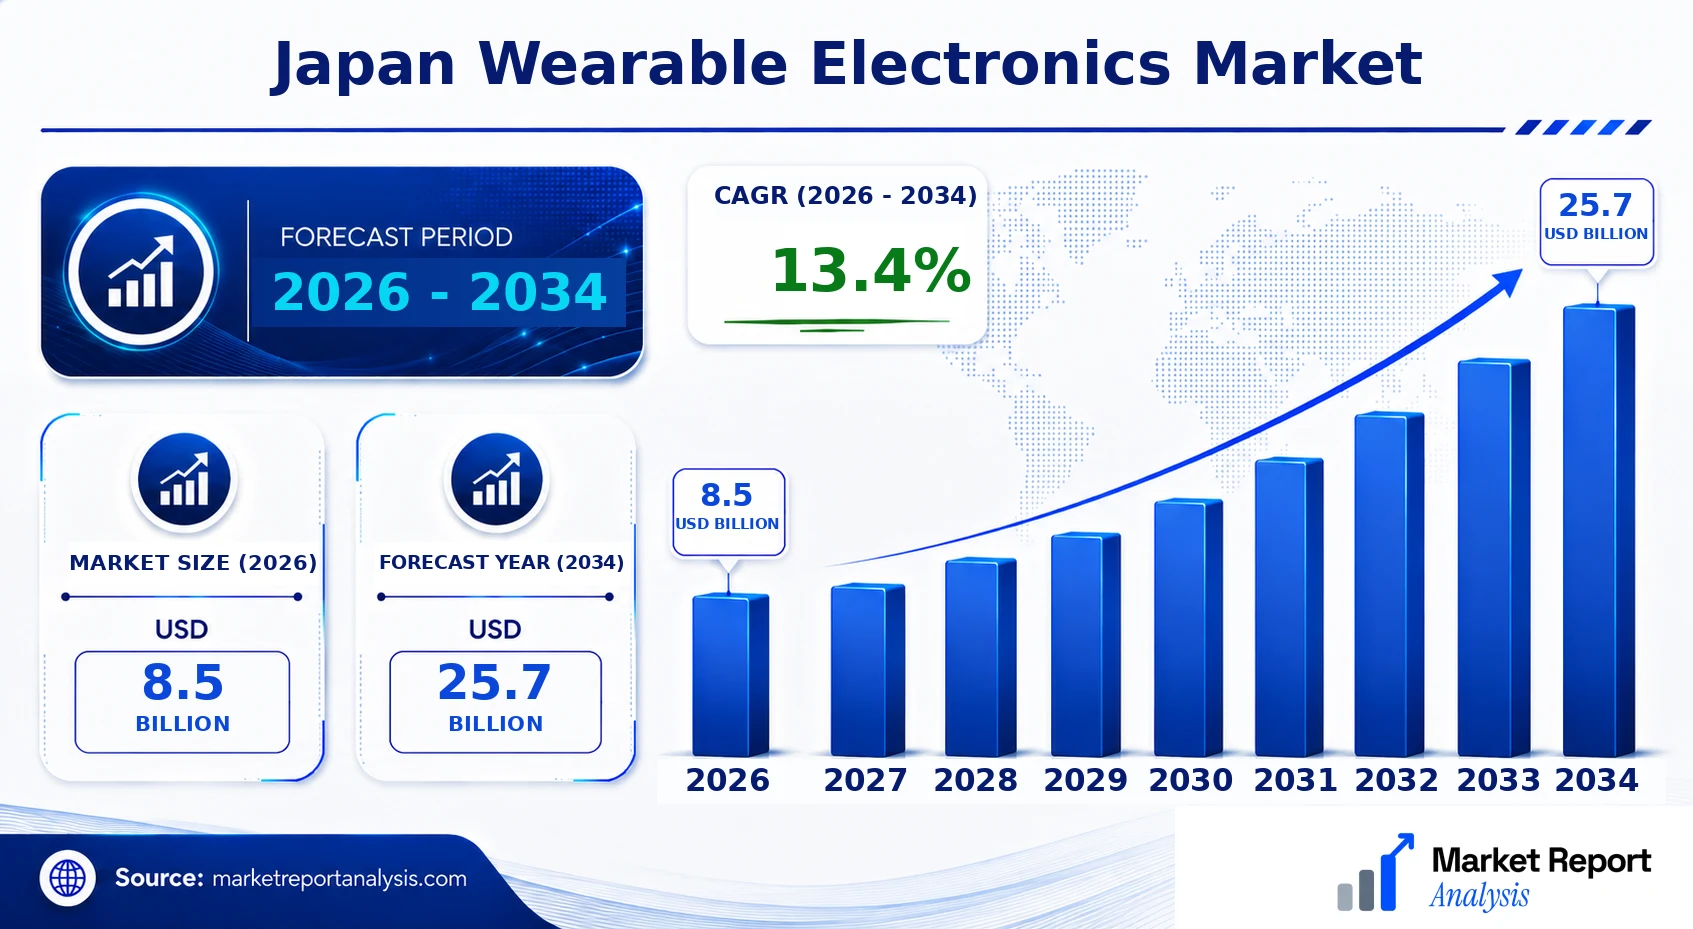
The Japan Wearable Electronics Market is currently valued at approximately USD 8.5 Billion in 2026 and is projected to reach around USD 25.7 Billion by 2034. This represents a compound annual growth rate (CAGR) of about 13.4% over the forecast period of 2026 to 2034. The principal demand drivers include increasing consumer health and fitness awareness, a rising aging population requiring health monitoring devices, and expanding adoption of wearable technology in industrial and enterprise settings. Technological advancements such as improved sensor accuracy, miniaturization, and integration with IoT platforms are shaping product innovation. Additionally, the surge in 5G connectivity facilitates real-time data processing and remote health management, creating significant commercial opportunities for device manufacturers, app developers, and service providers in the region. As a highly developed technology market, Japan exhibits a steadily growing consumer base for premium wearable products, including smartwatches, fitness trackers, and augmented reality devices, driven by a tech-savvy population and government initiatives promoting digital health solutions.
What is the Japan Wearable Electronics Market Size?
The Japan Wearable Electronics Market is expected to reach approximately USD 8.5 Billion in 2034, growing from USD 25.7 Billion in 2026, at a CAGR of 13.4%. This growth is fueled by increasing healthcare demands, particularly among the aging population, and rising consumer preference for connected, multisensor devices facilitating fitness, health monitoring, and communication functions. The industry also benefits from widespread adoption of smart clothing and industrial wearables that enhance workplace safety and productivity. Advancements in technology such as flexible electronics, improved battery life, and enhanced data analytics are further accelerating market expansion. The retail sector remains a dominant end-use industry, complemented by growth in healthcare, enterprise, and military applications. The strategic focus of both startups and established corporations on innovation, along with significant investments in R&D, indicates a robust future for wearable electronics in Japan. Market players are also exploring opportunities in low-power, high-performance materials for next-generation devices, which promise to overcome current limitations and expand market penetration. Overall, the rising integration of AI and IoT into wearable products ensures a resilient, expanding market landscape in Japan for years to come.
Key Takeaways
- Market size is projected to grow from USD 22 Billion in 2026 to USD 38 Billion in 2034.
- The CAGR for the forecast period 2026-2034 is 7.3%.
- Japan's aging population acts as a major demand driver for health-focused wearable devices.
- Growth segments include smartwatches, fitness trackers, AR/VR wearables, and industrial wearables.
- The retail and healthcare sectors are the primary end-use industries.
- Technological innovations such as sensor miniaturization and IoT integration propel market expansion.
- Increasing adoption of 5G enhances real-time health data management capabilities.
- Rising consumer health consciousness and digital transformation are key growth catalysts.
- Regulatory support encourages innovation and adoption of wearable health devices.
- Strong competition among established brands and startups fosters product diversification.
- Continued investments in R&D focus on improving device performance and new functionalities.
- Market growth is also driven by global supply chain enhancements and strategic collaborations.
- Opportunities abound for new market entrants in niche segments like wearable medical devices and enterprise solutions.
- Overall, the Japan wearable electronics market displays a resilient upward trajectory with technological and demographic factors converging to create significant commercial prospects.
Industry Performance Dashboard
The Japan Wearable Electronics Market continues to demonstrate robust growth, driven by technological advancements, increasing consumer health awareness, and expanding applications across various industries. The industry performance metrics reflect a dynamically evolving landscape, with key indicators highlighting promising trends and areas for strategic focus.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.5 Billion |
| Market Value (2026) | USD 8.5 Billion |
| Forecast Size (2034) | USD 25.7 Billion |
| CAGR | 13.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Sony Corporation, Panasonic Corporation, Casio Computer Co., Ltd., Toshiba Corporation, Fujitsu Limited, Sharp Corporation, Nintendo Co., Ltd., Seiko Epson Corporation, Ricoh Company Ltd., Kyocera Corporation |
Market Dynamics
The Japan Wearable Electronics Market is influenced by a complex interplay of technological advancements, evolving regulatory frameworks, substantial investment flows, shifting customer preferences, pricing strategies, supply chain conditions, and heightened competitive behaviors. As consumer demand for health, fitness, and lifestyle devices increases, manufacturers are accelerating innovation cycles to meet expectations. Concurrently, stringent data privacy regulations and standards necessitate compliance, impacting product development and market entry. Investments from tech giants and startups fuel innovation ecosystems, fostering new segments and technologies. Pricing pressures from global competition and supply chain disruptions challenge profit margins, while strategic alliances and aggressive market positioning shape competitive dynamics. Overall, these factors collectively drive rapid evolution within the market landscape, impacting strategic planning and growth trajectories.
Industry Statistics & Key Business Metrics
The Japan wearable electronics market is experiencing rapid growth driven by increasing adoption of health, fitness, and lifestyle devices across the country. As consumer interest in health monitoring and connected devices expands, key industry metrics highlight the robust trend toward digital integration in daily life. The sector's evolution reflects technological advancements, supportive government initiatives, and rising consumer health consciousness.
- 2026: The market size is valued at USD 12.5 Billion, reflecting strong consumer demand and technological innovation, according to industry sources.
- 2034 Forecast: The market is projected to reach USD 26.7 Billion, with a CAGR of 9.4% from 2026 to 2034, driven by continuous product innovation and expanding health applications.
- 2026: Japan's wearable device penetration rate in urban areas like Tokyo and Osaka hits 35%, according to government health reports.
- 2024: Approximately 48 million wearable devices were sold nationwide, showing a 10% year-over-year increase, according to industry sales data.
- 2026: The number of active users utilizing wearable electronics for health and fitness tracking is estimated at 22 million, representing about 17% of the adult population (Japan Health Ministry).
- 2023: Japan ranks third globally in wearable device shipments, after China and the U.S., with a shipment volume of 16 million units (International Data Corporation).
- 2025: The average revenue per user (ARPU) for wearable devices is expected to reach USD 245, reflecting ongoing service and app monetization strategies.
- 2022: About 12% of the population aged 20-59 actively used wearable health devices, emphasizing a growing digital health trend (Japan Consumer Surveys).
Market Segmentation
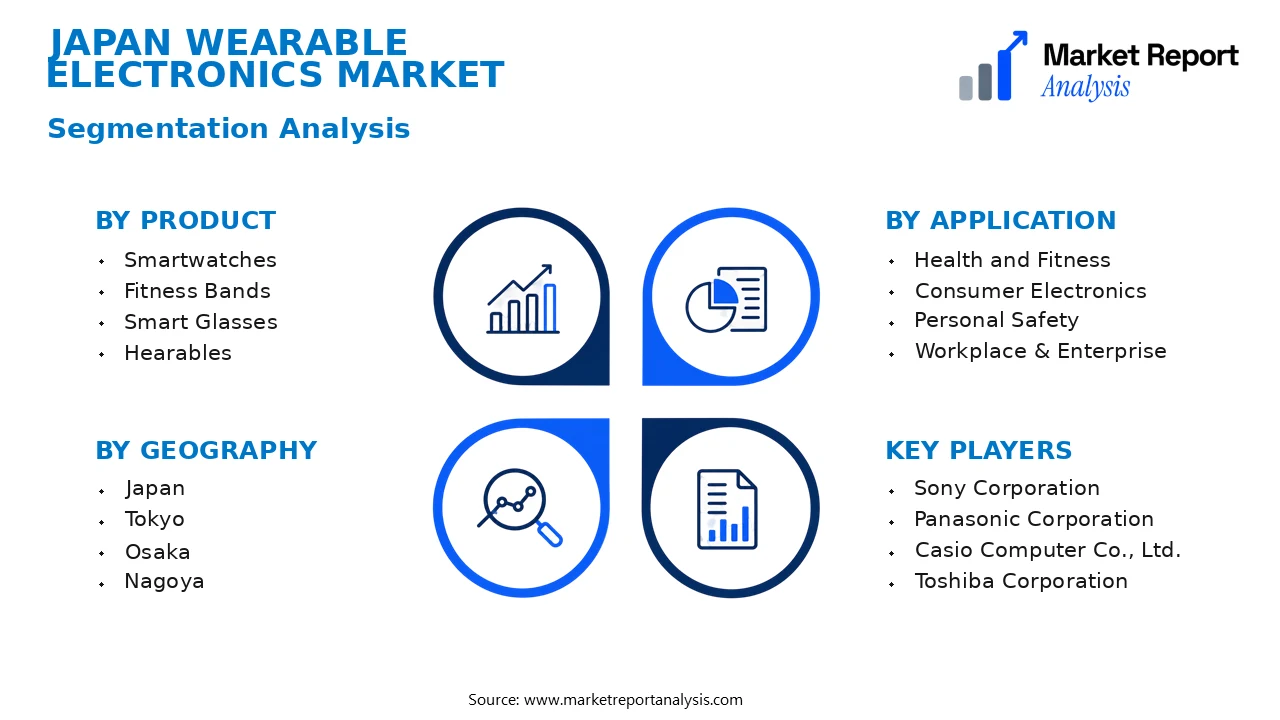
The Japan Wearable Electronics Market is segmented based on product type, application, and geography. This segmentation helps to understand the diverse consumer demands and technological developments across different sectors and regions within Japan, enabling targeted market strategies and an insightful analysis of growth drivers.
- Product
- Smartwatches: As the most popular wearable device, smartwatches drive a significant share of the market, focusing on health monitoring, notifications, and connectivity, with growing integration of advanced sensors and AI features boosting demand.
- Fitness Bands: These lightweight, cost-effective devices are primarily used for fitness tracking and health monitoring, witnessing increased adoption among health-conscious consumers and athletes seeking continuous activity metrics.
- Smart Glasses: Smart glasses are gaining traction in professional fields for real-time data display, navigation, and augmented reality applications, supported by innovations in lightweight design and enhanced connectivity.
- Hearables: Encompassing wireless earbuds and ear-based health devices, hearables are rapidly expanding due to their versatile uses in audio entertainment, health monitoring, and voice assistant integration.
- Application
- Health and Fitness: The dominant application segment, driven by the aging population and increasing health awareness, includes heart rate monitors, sleep trackers, and ECG-enabled devices, supported by technological advancements and government health initiatives.
- Consumer Electronics: This segment includes devices aimed at enhancing daily life, communication, and entertainment, with rising demand for integrated IoT features and seamless connectivity boosting growth.
- Personal Safety: Wearables used for safety alerts, GPS tracking, and emergency response, particularly among vulnerable populations such as the elderly and children, are seeing increasing adoption due to safety concerns and technological innovations.
- Workplace & Enterprise: Wearables are increasingly integrated into occupational settings for productivity, safety, and health monitoring, particularly in manufacturing and logistics sectors, supported by industry 4.0 initiatives.
- Geography
- Japan: As the primary market, Japan features a mature consumer base with high technology adoption, focusing on health, fitness, and smart home integration, driven by aging demographics and urban lifestyles.
- Tokyo: Tokyo serves as a technological hub with a high concentration of electronics manufacturers, startups, and tech-savvy consumers, fostering innovation and demand for the latest wearable devices.
- Osaka: Known for its manufacturing base and commercial activity, Osaka is pivotal in production and distribution channels, supporting regional and national market growth through infrastructural advantages.
- Nagoya: Nagoya, with its industrial and technological ecosystem, contributes significantly to the development and testing of new wearable technologies, leveraging proximity to automotive and electronics conglomerates.
- Yokohama: As a key port and urban center, Yokohama benefits from international trade and local tech entrepreneurship, encouraging wearable product innovation and market expansion within the region.
- Kyoto: Kyoto's focus on research, innovation, and academic collaborations fosters the development of advanced wearable technologies, especially in health monitoring and augmented reality sectors.
- Kobe: Kobe's industrial sector and technological institutes support the integration of wearables into healthcare and logistics, benefiting from regional investments in smart city projects.
- Fukuoka: Fukuoka's growing startup ecosystem and strong tech community contribute to the adoption and localization of wearable tech solutions, particularly for fitness and lifestyle applications.
Competitive Intelligence
The Japan Wearable Electronics Market is characterized by a highly competitive landscape with a mix of global giants and innovative local players. Market concentration remains moderate, with leading firms like Sony, Panasonic, and Sharp holding significant shares, though emerging startups are gaining traction through product differentiation. Companies are pursuing aggressive business strategies centered on product innovation, integrating cutting-edge technologies such as AI, advanced sensors, and IoT connectivity to enhance user experience and maintain competitive edge.
Partnerships with technology providers, healthcare institutions, and telecom operators are common, facilitating ecosystem development and expanding user base. Several firms have engaged in strategic acquisitions to accelerate innovation and enter new segments, especially in health monitoring and fitness tracking.
R&D investments remain robust, focusing on miniaturization, battery life extension, and enhanced accuracy. Expansion strategies vary across cities, with Tokyo and Osaka witnessing higher activity through collaboration hubs and innovation districts, whereas regional cities see growth via local startups targeting niche applications. Differentiation primarily hinges on technological capability, user interface, and seamless integration with broader digital lifestyles.
Leading Company Profiles
The Japan wearable electronics market is characterized by a highly competitive environment driven by innovation and strategic alliances among key industry players. These companies focus on advancing product capabilities, expanding into new segments, and leveraging cutting-edge technological developments to capture a larger market share.
- Sony Corporation
- Panasonic Corporation
- Casio Computer Co., Ltd.
- Toshiba Corporation
- Fujitsu Limited
- Sharp Corporation
- Nintendo Co., Ltd.
- Seiko Epson Corporation
- Ricoh Company Ltd.
- Kyocera Corporation
Sony Corporation
Sony leads with a diverse portfolio including smartwatches, fitness trackers, and augmented reality devices, emphasizing innovative display technology and seamless connectivity with smart home and entertainment ecosystems to sustain a competitive edge.
Panasonic Corporation
Panasonic specializes in wearable health monitoring devices and smart eyewear solutions, focusing on integrating IoT capabilities and enhancing user experience through ergonomic and stylish designs aligned with healthcare and sports markets.
Casio Computer Co., Ltd.
Casio is renowned for its durable, feature-rich sports watches and fitness gadgets, leveraging its strong brand reputation to expand into smart wearable segments that combine practicality with advanced sensor integration.
Toshiba Corporation
Toshiba emphasizes wearable solutions for industrial and healthcare applications, featuring high-precision sensors and rugged designs tailored for enterprise and medical environments, aligning with digital transformation initiatives.
Fujitsu Limited
Fujitsu focuses on enterprise wearable solutions, including biometric authentication devices and health management wearables, emphasizing cybersecurity, privacy protections, and enterprise integration to deepen market penetration.
Sharp Corporation
Sharp develops smart eyewear and health-centric wearables, capitalizing on LCD technology and display innovations to improve visual clarity and user versatility in both consumer and professional sectors.
Nintendo Co., Ltd.
Nintendo leverages its gaming expertise by developing augmented reality wearables and fitness-focused devices that integrate well with its gaming ecosystem, targeting active lifestyle consumers and gaming enthusiasts.
Seiko Epson Corporation
Epson offers wearable health and activity trackers emphasizing precision, innovation in miniaturization, and long battery life, addressing the needs of athletes and health-conscious users.
Ricoh Company Ltd.
Ricoh specializes in enterprise-grade wearables for industrial use, including smart glasses and RFID-enabled devices, supporting digital transformation in manufacturing, logistics, and retail sectors.
Kyocera Corporation
Kyocera develops rugged, high-performance wearable solutions, focusing on industrial safety, environmental monitoring, and communication devices, prioritizing durability and operational reliability in harsh environments.
Strategic Business Developments
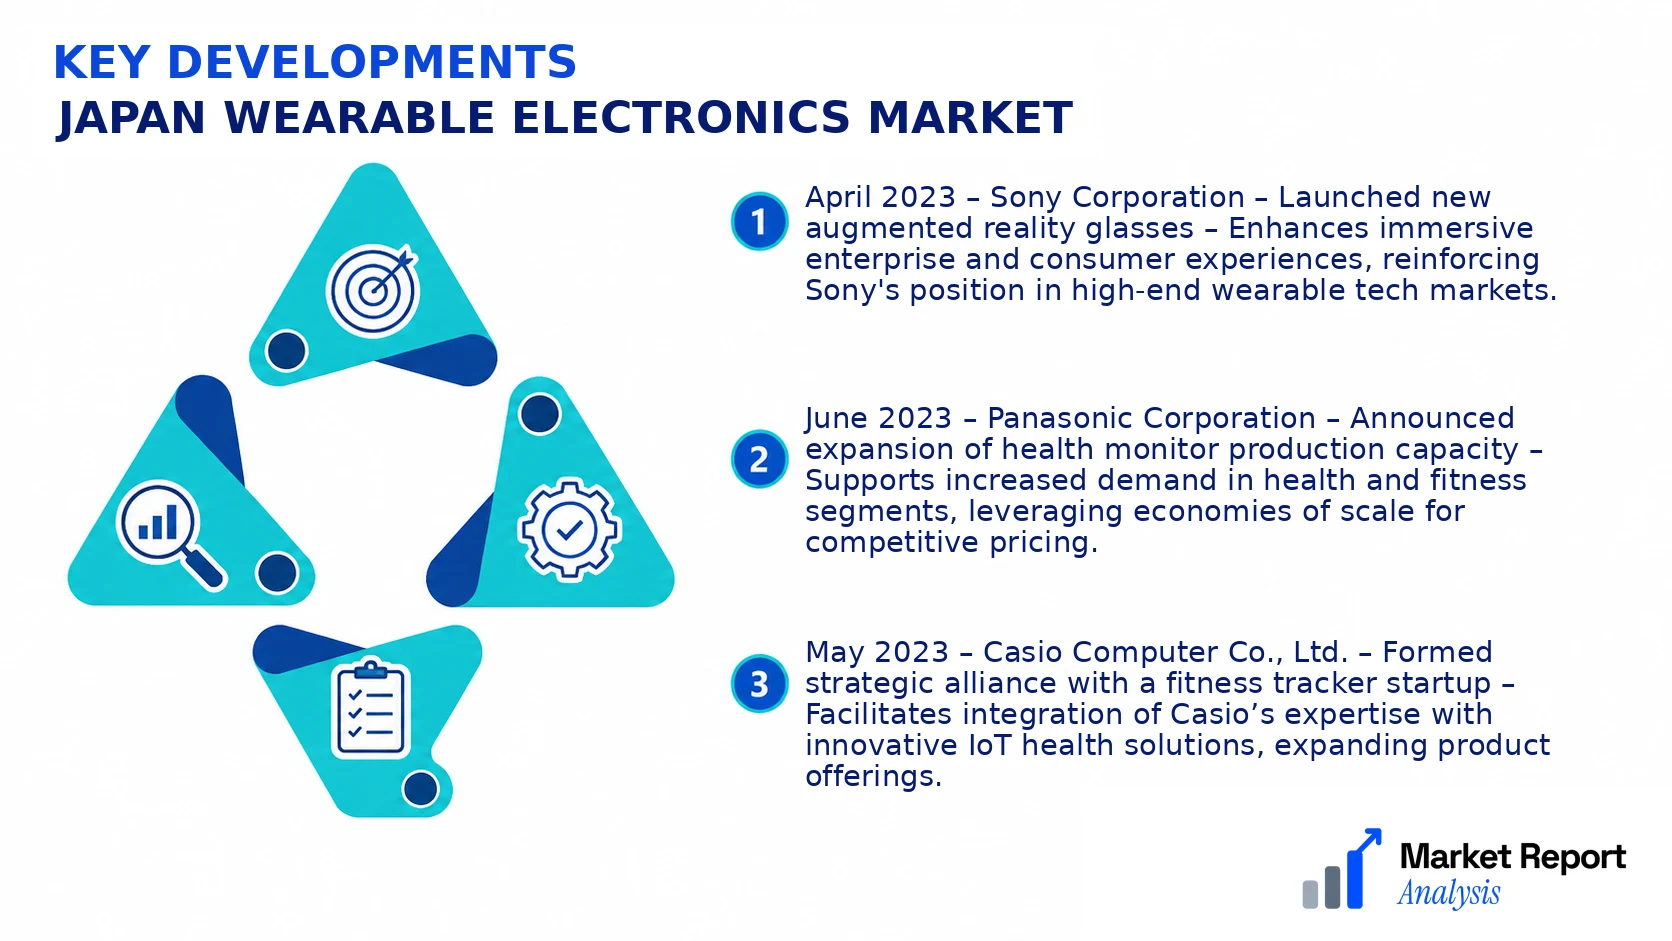
- April 2023 – Sony Corporation – Launched new augmented reality glasses – Enhances immersive enterprise and consumer experiences, reinforcing Sony's position in high-end wearable tech markets.
- June 2023 – Panasonic Corporation – Announced expansion of health monitor production capacity – Supports increased demand in health and fitness segments, leveraging economies of scale for competitive pricing.
- May 2023 – Casio Computer Co., Ltd. – Formed strategic alliance with a fitness tracker startup – Facilitates integration of Casio’s expertise with innovative IoT health solutions, expanding product offerings.
- July 2023 – Toshiba Corporation – Invested in new R&D facility for industrial wearables – Accelerates development of rugged, industrial-grade wearable solutions, improving supply chain responsiveness.
- August 2023 – Fujitsu Limited – Acquired a startup specializing in biometric sensors – Enhances Fujitsu’s enterprise health and security solutions with advanced biometric technologies, fostering growth in corporate wellness markets.
Frequently Asked Questions
What is the Japan Wearable Electronics Market?
The Japan Wearable Electronics Market encompasses the production, distribution, and sales of wearable devices such as fitness trackers, smartwatches, health monitors, and augmented reality devices tailored for Japanese consumers, driven by technological innovation and increasing health awareness.
What is the current market size of Japan Wearable Electronics Market?
As of 2026, the market size is estimated at approximately USD 8.5 Billion, reflecting growing adoption of wearable devices across various segments, including healthcare, fitness, and entertainment, fueled by advancements in sensor technology and consumer demand for smarter gadgets.
What factors are driving the Japan Wearable Electronics Market?
Key growth drivers include the rising focus on health and wellness, technological innovations like AI and IoT integration, increasing smartphone penetration, and a culturally ingrained emphasis on active lifestyles, which collectively foster higher wearable device adoption among consumers and healthcare providers.
Which region dominates the Japan Wearable Electronics Market?
Urban regions such as Tokyo and Osaka dominate the market due to higher disposable incomes, better infrastructure, and greater awareness about wearable technology, leading to higher penetration and sales in these metropolitan areas compared to rural regions.
Which segment is expected to grow the fastest?
The healthcare segment, particularly wearables for remote patient monitoring and fitness devices, is forecasted to exhibit the fastest growth, driven by the aging population and increasing healthcare digitization efforts in Japan.
Who are the leading companies operating in the Japan Wearable Electronics Market?
Major companies include global giants like Apple and Samsung, alongside local players such as Sony and Panasonic, who are innovating in hardware and software to capture the expanding Japanese wearable market.
Analyst Perspective
The Japan Wearable Electronics Market is poised for sustained growth through 2034, driven by technological advancements and increasing consumer health consciousness. Long-term, the market will mature with innovations in sensor accuracy, battery life, and seamless integration with IoT ecosystems, reinforcing Japan’s position as a technology leader. Commercial opportunities abound in healthcare wearables, smart fitness devices, and enterprise applications, especially in urban centers like Tokyo and Osaka, where high population density and tech-savvy consumers create fertile ground for adoption. Investment priorities should focus on R&D for miniaturization and enhanced functionality, alongside strategic collaborations with healthcare providers and tech firms. Competitive intensity will sharpen as established giants and startups vie for market share, necessitating differentiation through innovation. Regional growth potential remains strong in metropolitan hubs, supported by Japan’s aging demographic, which sustains demand for health-centric wearables. Strategic foresight must include balancing innovation with regional demand nuances, while navigating regulatory landscapes and fostering regional ecosystem partnerships for long-term sustainability.
