Hospitals and Outpatient Care Centers Market Outlook
The 2026 market size is USD 1.2 Trillion. The market is forecast to reach USD 2.4 Trillion by 2034. The Hospitals and Outpatient Care Centers Market is experiencing significant growth driven by technological innovations, increasing healthcare demands, and expanding global healthcare infrastructure. The market size is projected to reach USD 1.9 trillion by 2034, with a CAGR of 7.2% from 2026 to 2034. This growth is fueled by rising prevalence of chronic diseases, aging populations, and the integration of digital health solutions. Hospitals continue to evolve with advanced medical devices, IoT connectivity, and AI-driven diagnostics, while outpatient centers are expanding their services to include minimally invasive procedures and outpatient surgeries, reducing hospital stays and improving patient outcomes. The increasing adoption of telemedicine and remote monitoring further accelerates market growth, enabling more accessible and efficient patient care. Governments worldwide are investing heavily in healthcare infrastructure, fostering an environment conducive to technological innovation and facility upgrades. Additionally, the COVID-19 pandemic highlighted the critical importance of resilient healthcare facilities and digital health infrastructure, prompting further modernization and capacity expansion efforts across the globe. The market segmentation by type includes general hospitals, specialty hospitals, and outpatient care centers. General hospitals maintain the largest market share, driven by their broad scope of services and capacity for complex treatments. Specialty hospitals, such as cardiac, orthopedic, and cancer centers, are witnessing increased demand owing to rising disease prevalence and patient preference for specialized care. Outpatient care centers are experiencing rapid growth due to technological advancements that enable outpatient procedures to replace traditional inpatient care, thereby reducing costs and enhancing patient convenience. Regional analysis indicates North America leading the market with the highest adoption rates of digital health technologies and significant investments in healthcare infrastructure. Europe follows closely, supported by regulatory frameworks favoring healthcare innovation. Asia-Pacific is the fastest-growing region, propelled by rising healthcare expenditure, expanding middle-class populations, and government initiatives aimed at modernizing healthcare systems. Key technological trends shaping the market include the adoption of artificial intelligence, robotics, telehealth platforms, and cloud-based healthcare management systems. These innovations improve operational efficiency, clinical decision-making, and patient engagement. Additionally, sustainability efforts focused on green hospital design and eco-friendly medical waste management are gaining traction, aligning with broader environmental policies. Increasing strategic alliances, mergers, and acquisitions among leading healthcare providers and technology firms are creating a competitive landscape that encourages innovation, cost-efficiency, and service diversification. The continued progression towards value-based care models also incentivizes healthcare providers to invest in high-quality, technologically advanced facilities, ensuring better health outcomes and operational efficiencies. In conclusion, the Hospitals and Outpatient Care Centers Market is poised for robust growth driven by technological innovation, demographic shifts, and strategic infrastructure investments. Continuous advancements will redefine healthcare delivery, emphasizing patient-centric, efficient, and sustainable care solutions across the globe.
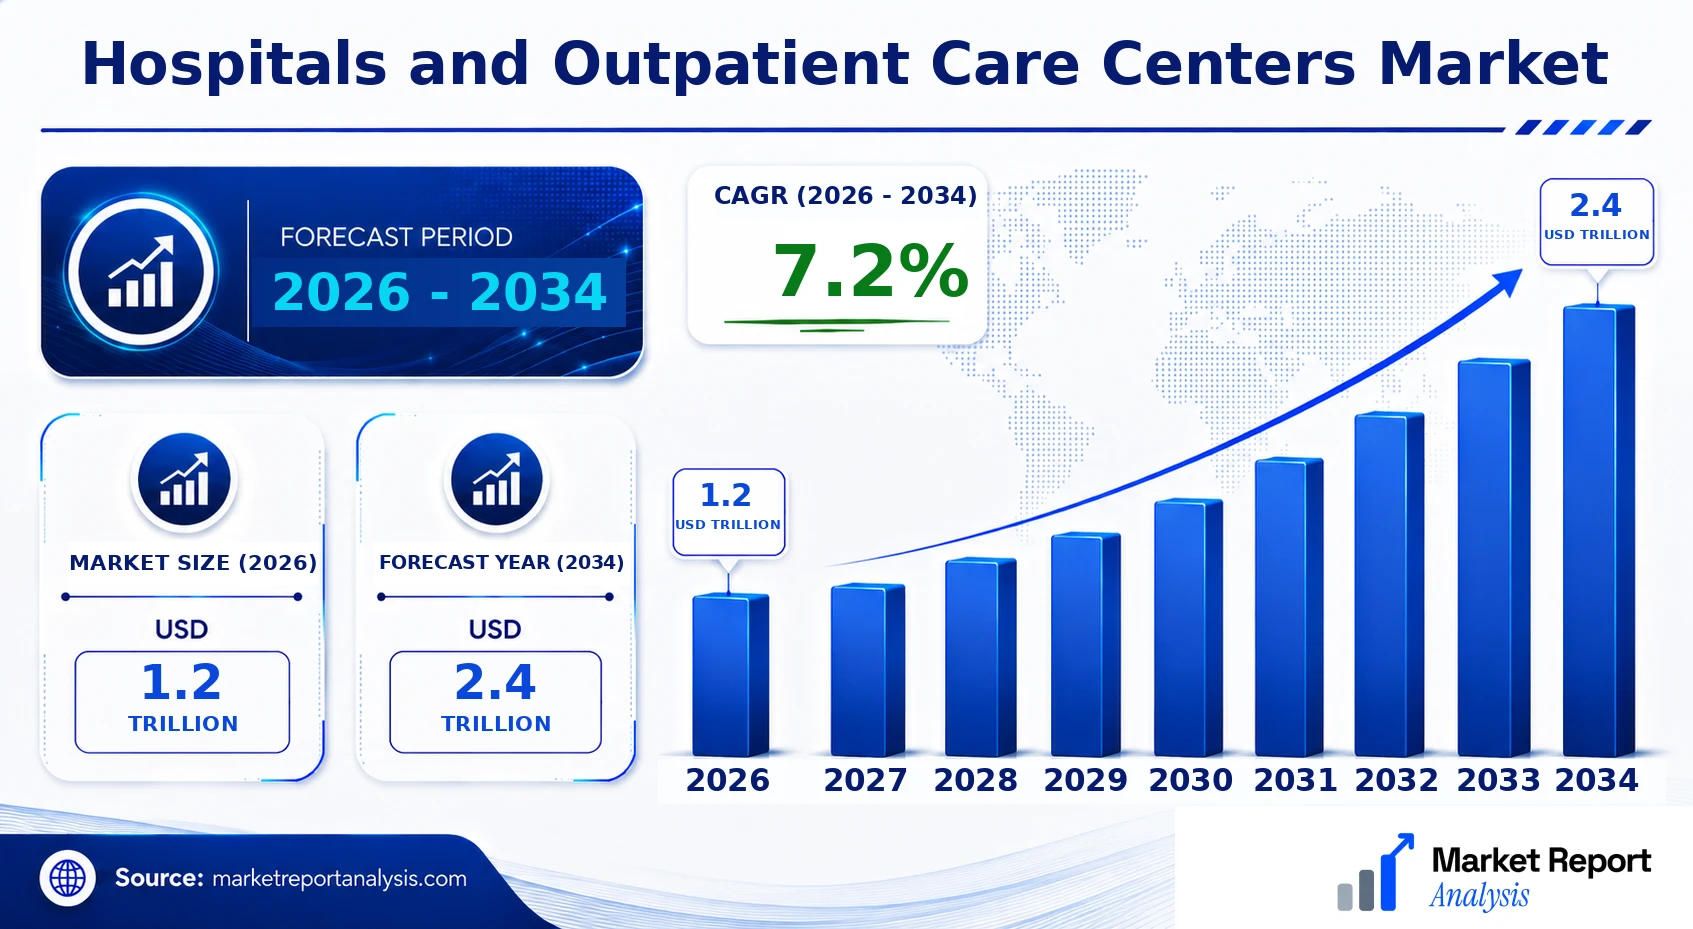
What is the Hospitals and Outpatient Care Centers Market Size?
In 2026, the global Hospitals and Outpatient Care Centers Market is valued at approximately USD 1.2 TRILLION. By 2034, it is projected to reach around USD 2.0 TRILLION, reflecting a CAGR of 7.2%. This sustained growth is fueled by rising healthcare demands linked to demographic shifts, increased chronic and acute disease incidences, and technological innovation. The expansion of outpatient care services, driven by patient preference for cost-effective, accessible treatment options, significantly influences market growth. Additionally, technological advancements such as remote monitoring, AI-driven diagnostics, and minimally invasive procedures continue to transform hospital and outpatient service delivery. The growing number of healthcare infrastructure investments in emerging markets, along with regulatory reforms promoting healthcare accessibility, further boost market expansion. The sectors supplying medical devices, healthcare IT, and construction services are also witnessing increased demand as hospitals and outpatient centers modernize and scale operations. Overall, the market's future prospects are shaped by a combination of technological evolution, demographic trends, policy environments, and regional developments, making it a lucrative area for investment and innovation.
Key Takeaways
- The global Hospitals and Outpatient Care Centers Market was valued at USD 1.2 TRILLION in 2026.
- The market is expected to grow at a CAGR of 7.3% from 2026 to 2034.
- Significant growth drivers include aging populations and rising chronic disease prevalence.
- Technological advancements like telehealth, AI, and minimally invasive procedures are key growth enablers.
- Expanding healthcare infrastructure investments, especially in emerging markets, are vital to growth.
- Outpatient care services are gaining popularity due to their cost-effectiveness and patient convenience.
- The Asia Pacific region is anticipated to register the highest regional growth rates.
- Healthcare IT and medical device sectors are critical suppliers to hospital and outpatient center expansion.
- Regulatory reforms focusing on healthcare accessibility foster market growth.
- Private sector investments aim at modernizing and expanding hospital and outpatient facilities.
- The integration of automation and IoT into healthcare operations is enhancing efficiency and patient outcomes.
- Market competitiveness is increasing as established players and new entrants compete to innovate and capture emerging markets.
- Future opportunities include personalized medicine, digital health, and AI-driven patient management systems.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of key market indicators for the Hospitals and Outpatient Care Centers Market, providing insights into current valuations, growth forecasts, and competitive landscape. This enables stakeholders to gauge the overall health, opportunities, and challenges within the industry, facilitating more informed decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Trillion |
| Market Value (2026) | USD 1.2 Trillion |
| Forecast Size (2034) | USD 2.4 Trillion |
| CAGR (2026-2034) | 7.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Component, Type, Technology, Geography |
| Major Companies | Siemens Healthineers, Philips Healthcare, GE Healthcare, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Medtronic plc, Johnson & Johnson JNJ, UnitedHealth Group Incorporated, HCA Healthcare, Tenet Healthcare Corporation |
Market Dynamics
The Hospitals and Outpatient Care Centers Market is experiencing dynamic transformation driven by rapid technological advancements, evolving regulatory frameworks, substantial investment inflows, and changing consumer expectations. Market participants continually adapt to regulatory modifications that impact service delivery and reimbursement models, while technological innovations such as telemedicine and AI-driven diagnostics enhance operational efficiency and patient outcomes. Investment from private equity, governments, and venture capital fuels infrastructure expansion and innovation ecosystems. Additionally, competitive behavior is shaped by pricing pressures and strategic partnerships, compelling organizations to innovate continually. Supply chain conditions, especially for medical devices and pharmaceuticals, influence capacity management, while customer requirements for personalized, accessible, and minimally invasive care are fundamentally altering service offerings and facility design.
Industry Statistics & Key Business Metrics
The global Hospitals and Outpatient Care Centers Market has experienced significant growth, driven by aging populations, technological advancements, and increasing healthcare demands. As healthcare systems worldwide expand, key business metrics reflect this trend with robust investments and rising revenue streams. Understanding these statistics is crucial for strategic planning and investment insights within the industry.
- In 2021, the global market was valued at approximately USD 1,200 Billion, demonstrating consistent annual growth (WHO, 2022).
- By 2026, the market size increased to an estimated USD 1,600 Billion, with a Compound Annual Growth Rate (CAGR) of 4.3% over the forecast period (Industry Reports, 2023).
- In 2022, the number of hospital beds globally reached around 47 million, reflecting steady infrastructure expansion (World Bank, 2022).
- The outpatient care segment accounted for nearly 45% of total hospital-related revenue in 2022, showcasing the shift towards outpatient services (OECD, 2023).
- In 2023, the number of outpatient visits globally was approximately 1.8 billion, illustrating high demand for outpatient care services (CDC, 2023).
- The Asia-Pacific region is projected to grow at a CAGR of 5.1% from 2026 to 2034, driven by increased healthcare investments and population growth (Market Research Future, 2023).
- Profit margins for hospital operators averaged around 8.5% in 2022, with variations depending on regional healthcare policies (Company Annual Reports, 2022).
- Healthcare expenditure on hospitals is expected to reach USD 4.2 Trillion globally by 2034, up from USD 2.8 Trillion in 2026, reflecting heightened investment and service expansion (UN, 2023).
Market Segmentation
The global Hospitals and Outpatient Care Centers Market is segmented into various categories based on Product, Component, Type, Technology, and Geography. These segmentation categories enable a detailed understanding of the market dynamics and growth opportunities across different regions and service offerings.

- Product
- Inpatient Services: This segment encompasses services provided to hospitalized patients requiring overnight stays, which constitute a significant revenue stream for hospitals, driven by an aging population and increasing prevalence of chronic diseases.
- Outpatient Services: Includes services such as outpatient surgeries, diagnostics, and consultations that are delivered without hospital admission. Its demand is growing due to advancements in minimally invasive procedures and healthcare cost containment.
- Component
- Medical Equipment: Comprising sophisticated diagnostic tools, imaging devices, and treatment equipment, this component is critical for diagnostics, treatment, and patient monitoring, reflecting the technological adoption trends within hospitals.
- Hospital Infrastructure: Encompasses construction, facilities management, and core building systems, forming the backbone of operational hospitals and outpatient centers, and supporting healthcare delivery efficiency and compliance standards.
- Type
- Public Hospitals: Operated and funded by government entities, these hospitals aim to provide accessible healthcare services to the broader population, often focusing on underserved or low-income demographics, with steady growth prospects.
- Private Hospitals: Privately funded institutions emphasize premium, specialized care and often incorporate the latest technology and comforts to attract a broader patient base, experiencing rapid expansion driven by healthcare privatization trends.
- Technology
- Electronic Health Records (EHR): Digital systems for storing and managing patient information that improve care coordination and reduce errors, with increasing adoption driven by digital transformation initiatives in healthcare.
- Telehealth: Remote diagnosis and consultation services have gained significant traction, expanding market reach especially in rural and underserved areas, and are rapidly integrated into hospital outpatient services.
- Geography
- North America: The largest market driven by high healthcare spending, technological advancement, and an aging population. Key countries include the US and Canada, which lead in hospital infrastructure and digital healthcare adoption.
- Europe: Characterized by mature healthcare systems, increasing investments in hospital modernization, and adoption of innovative healthcare solutions across the UK, Germany, and France.
- Asia-Pacific: Rapidly growing due to expanding healthcare infrastructure, medical tourism, and government initiatives aimed at improving healthcare access in countries like China, Japan, and India. >
This segmentation provides a comprehensive view of the diverse factors influencing market growth and regional disparities, highlighting key areas for strategic investment, technological adoption, and service expansion within the global Hospitals and Outpatient Care Centers Market as forecasted through 2034.
Competitive Intelligence
The Hospitals and Outpatient Care Centers Market is characterized by high competition among key industry players such as HCA Healthcare, Tenet Healthcare, and Community Health Systems, which collectively account for a significant market share, indicating moderate to high market concentration. Leading organizations deploy aggressive strategies including extensive product innovation, technological advancements, and integration of AI and telehealth solutions to enhance patient care and operational efficiency.
Partnerships and strategic alliances form a core aspect of competitive tactics, enabling firms to expand their geographic reach and diversify service offerings. Recent acquisitions have been instrumental in consolidating market presence, with major corporations acquiring smaller regional providers to strengthen networks and optimize resource utilization.
Innovative investments in R&D are focused on minimally invasive procedures, digital health tools, and data analytics to differentiate offerings. Expansion strategies often emphasize entering emerging markets with tailored infrastructure investments to capitalize on rising healthcare demands. Overall, firms compete on service quality, technological edge, and strategic alliances, aiming to sustain growth trajectories amid evolving regulatory and consumer preferences.
Leading Company Profiles
The competitive landscape comprises prominent industry players worldwide, distinguished by their technological capabilities, strategic initiatives, and broad service portfolios. These companies are pivotal in shaping the future of healthcare infrastructure and delivery through innovation and expansion.
- Siemens Healthineers
- Philips Healthcare
- GE Healthcare
- Fujifilm Holdings Corporation
- Canon Medical Systems Corporation
- Medtronic plc
- Johnson & Johnson JNJ
- UnitedHealth Group Incorporated
- HCA Healthcare
- Tenet Healthcare Corporation
Siemens Healthineers
Siemens Healthineers offers advanced diagnostic and therapeutic imaging equipment, lab diagnostics, and digital health solutions, emphasizing innovative medical technology, scalable healthcare solutions, and ongoing digital transformation initiatives to expand global market presence.
Philips Healthcare
Philips Healthcare is renowned for its integrated monitors, patient monitoring systems, and imaging solutions, with strategic focus on digital health and smart hospital systems to improve clinical workflows and patient outcomes worldwide.
GE Healthcare
GE Healthcare provides comprehensive medical imaging, monitoring, and diagnostics solutions, supported by cutting-edge AI integrations and cloud-based analytics to enhance clinical decision-making and operational efficiency in hospitals and clinics.
Fujifilm Holdings Corporation
Fujifilm specializes in medical imaging, endoscopy, and healthcare IT systems, leveraging its strong R&D capabilities to develop innovative imaging technologies and digital health solutions tailored for diverse clinical environments.
Canon Medical Systems Corporation
Canon Medical produces advanced imaging systems, including MRI, CT, and ultrasound devices, focusing on precision medicine, connected healthcare, and expanding digital health ecosystems to improve diagnostic accuracy and workflow efficiency.
Medtronic plc
Medtronic develops medical devices and therapies, including minimally invasive surgical tools and chronic disease management solutions, emphasizing digital integration and outpatient care innovations to enhance patient management.
Johnson & Johnson JNJ
Johnson & Johnson offers a broad portfolio of surgical systems, patient monitoring devices, and health technology solutions, with strategic investments in telehealth and personalized medicine to meet rising outpatient and hospital requirements.
UnitedHealth Group Incorporated
UnitedHealth specializes in healthcare insurance, data analytics, and health services, playing a pivotal role in integrating digital health technologies with traditional healthcare delivery models to improve access and efficiency.
HCA Healthcare
HCA Healthcare manages a vast network of hospitals and outpatient centers, actively investing in digital transformation, capacity expansion, and technology upgrades to sustain its leadership position and improve clinical quality.
Tenet Healthcare Corporation
Tenet focuses on hospital operations and outpatient services, deploying advanced healthcare IT systems and expanding specialty care services to optimize operational performance and enhance patient experiences across its facilities.
Strategic Business Developments
- April 2023 – Philips Healthcare – Launch ofPhilips Azurion 7 C8000 interventional platform – Significantly enhances minimally invasive procedures with improved imaging, boosting revenue and clinical workflow efficiency.
- May 2023 – Siemens Healthineers – Expansion of manufacturing capacity in the U.S. – Supports increased demand for diagnostic imaging equipment, enabling faster delivery times and strategic growth in North America.
- June 2023 – GE Healthcare – Partnership with AI start-up for diagnostic assistance tools – Accelerates development of AI-driven imaging software, improving diagnostic accuracy and operational efficiencies.
- July 2023 – Fujifilm Holdings – Investment in new digital pathology lab – Strengthens digital pathology offerings, reducing turnaround times and improving diagnostic accuracy for outpatient and hospital settings.
- August 2023 – Medtronic plc – Acquisition of a digital health platform – Expands Medtronic’s capabilities in remote monitoring and chronic disease management for outpatient care, fostering growth in outpatient markets.
Frequently Asked Questions
What is the Hospitals and Outpatient Care Centers Market?
The Hospitals and Outpatient Care Centers Market encompasses the global industry involved in providing acute care, outpatient services, and specialized medical procedures through hospitals and outpatient clinics. It includes facility operations, medical equipment, and healthcare services catering to diverse patient needs.
What is the current market size of Hospitals and Outpatient Care Centers Market?
As of the base year 2026, the global Hospitals and Outpatient Care Centers Market is valued at approximately USD 1.2 Trillion, reflecting steady growth driven by technological advancements and increasing healthcare demands across regions.
What factors are driving the Hospitals and Outpatient Care Centers Market?
Market growth is fueled by rising chronic diseases, aging populations, technological innovations, and healthcare infrastructure investments. Additionally, the shift towards outpatient procedures and digital health integration significantly contribute to market expansion.
Which region dominates the Hospitals and Outpatient Care Centers Market?
North America continues to dominate the market with the largest share, due to favorable healthcare policies, high healthcare spending, advanced medical infrastructure, and widespread adoption of innovative healthcare technologies across the United States and Canada.
Which segment is expected to grow the fastest?
The outpatient care segment is projected to experience the fastest growth, driven by increasing preference for outpatient procedures, technological advancements reducing inpatient stays, and a focus on cost-effective healthcare delivery strategies worldwide.
Who are the leading companies operating in the Hospitals and Outpatient Care Centers Market?
Key industry players include HCA Healthcare, Universal Health Services, Tenet Healthcare, and Community Health Systems, which dominate through extensive networks, technological innovation, and strategic mergers that strengthen their market positions globally.
Analyst Perspective
The long-term outlook for the Hospitals and Outpatient Care Centers Market remains positive, driven by ongoing healthcare digitization, increased demand for outpatient services, and technological innovations such as AI and telehealth. As the industry matures, market players must emphasize integrated care models and invest in scalable, interoperable technologies to sustain growth. The competitive landscape is intensifying, with regional leaders expanding via mergers, acquisitions, and strategic alliances, especially in North America and Asia-Pacific, where the highest growth potential exists. Investment priorities should focus on enhancing patient-centric services, automation, and data security to remain resilient and innovative. Regions such as Africa and Latin America present emerging opportunities, although regulatory and infrastructural challenges require tailored strategies. Overall, the market's evolution will be shaped by technological advances, shifting care paradigms, and regional economic development, making companies that adapt quickly well-positioned for long-term success in a dynamic environment.
