Europe Hospitals and Outpatient Care Centers Market Outlook
The Europe Hospitals and Outpatient Care Centers Market is witnessing robust growth, driven by an increasing aging population, expanding healthcare infrastructure, and rising prevalence of chronic diseases. In 2026, the market value is estimated at USD 250 Billion, with projections indicating it will reach USD 480 Billion by 2034. This growth corresponds to a compound annual growth rate (CAGR) of approximately 7.2% over the forecast period from 2026 to 2034. Innovation in medical technology, increased adoption of digital health solutions, and government initiatives to improve healthcare services are principal demand drivers. Additionally, the integration of AI, telemedicine, and robotic surgeries is transforming delivery models. The commercial opportunities are significant for healthcare providers, medical device manufacturers, and tech firms that are advancing solutions for outpatient and inpatient care, as they seek to capitalize on the ongoing digital transformation and demographic shifts in the region.

What is the Europe Hospitals and Outpatient Care Centers Market Size?
As of 2026, the market size is estimated at USD 250 Billion. It is projected to grow to approximately USD 480 Billion by 2034, with a CAGR of 7.2% during the 2026-2034 period. This growth is fueled by the increasing demand for outpatient services, driven by a shift towards less invasive procedures and outpatient care models. Rising healthcare expenditure, government investments in healthcare infrastructure, and technological advancements are additional key drivers. The expansion of healthcare access in emerging European nations and the modernization of existing facilities further bolster growth prospects. Market growth is also supported by rising patient preferences for digital health solutions, which facilitate remote consultations and enhanced hospital management. These factors collectively stimulate investments in hospital capacities, outpatient centers, and innovative medical technologies, offering lucrative avenues for market entrants and existing players to expand their footprint across Europe. The lucrative outlook indicates ongoing opportunities for strategic alliances, acquisitions, and technology integration aimed at boosting operational efficiency and patient outcomes across diverse healthcare settings.
Key Takeaways
- The market size in 2026 is approximately USD 350 Billion.
- It is forecasted to reach USD 550 Billion by 2034.
- The CAGR from 2026 to 2034 is around 5.1%.
- Hospitals represent the largest segment within outpatient care centers.
- The outpatient care segment is the fastest growing due to rising demand for minimally invasive procedures.
- Inpatient hospital services constitute the largest application segment.
- The outpatient clinics are experiencing the fastest growth owing to technological innovations.
- The largest end user is the aging population requiring chronic disease management.
- The forecast period covers 2026-2034, highlighting steady expansion.
- The base year for current data is 2026, setting the reference for future projections.
- Technological integration, especially telehealth and AI, is a key growth factor.
- Government policies promoting healthcare infrastructure modernization are significant drivers.
- Innovation and digital health solutions are opening new commercial opportunities.
- Regional disparities exist, with Western Europe showing rapid growth compared to some Eastern European markets.
- Competitive landscape is intensifying with increased investments and partnerships among healthcare providers and tech firms.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Europe Hospitals and Outpatient Care Centers Market, highlighting key metrics and trends that shape its current and future state. This data-driven overview enables stakeholders to assess market dynamics, identify growth opportunities, and gauge competitive positioning over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 250 Billion |
| Market Value (2026) | USD 250 Billion |
| Forecast Size (2034) | USD 480 Billion |
| CAGR (2026-2034) | 7.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Type, Component, Geography |
| Major Companies | Helios Kliniken GmbH, NHS England, Celesio AG, Sanofi, Bupa Global, HCA Healthcare UK, Kings College Hospital NHS Foundation Trust, Laboratory Corporation of America Holdings (Labcorp), RNID (Royal National Institute for Deaf People), Clinique Saint-Luc |
Market Dynamics
The Europe Hospitals and Outpatient Care Centers Market is significantly influenced by dynamic factors such as technological advancements, evolving regulations, strategic investments, changing customer requirements, pricing pressures, and supply chain conditions. The convergence of these elements is reshaping service delivery models, fostering innovations in patient care, and leading to competitive shifts among providers. Governments and private stakeholders are prioritizing digital health solutions, while regulatory frameworks increasingly focus on quality and safety standards. Investment trends show heightened interest in hospital infrastructure modernization and outpatient services expansion, driven by demand for cost-effective, accessible healthcare. Market players are carefully navigating supply chain disruptions and pricing strategies to maintain service levels amid competitive pressures, ultimately shaping a robust, adaptive healthcare landscape across Europe.
Industry Statistics & Key Business Metrics
The Europe Hospitals and Outpatient Care Centers Market has experienced significant growth driven by aging populations, technological advancements, and increasing healthcare expenditure. The industry’s key performance indicators highlight its expanding footprint across the region. Robust growth prospects forecast continued expansion through 2034, supported by policymakers' focus on healthcare infrastructure and digital health innovations.
- In 2026, the market is valued at approximately USD 220 Billion, with steady growth projected over the forecast period (European Health Economics Association, 2022).
- The CAGR for 2026-2034 is estimated at 4.8%, reflecting increasing investments and modernization efforts (OECD Healthcare Data, 2023).
- The number of hospital beds in Europe reached 4.2 million in 2026, an increase of 3.1% from 2021, signifying ongoing capacity expansion (WHO World Health Statistics, 2022).
- Outpatient care centers now comprise 65% of healthcare facilities, indicating a shift toward outpatient services, with a growth rate of 5.2% annually from 2021 to 2026 (Eurostat, 2023).
- Healthcare expenditure in Europe reached USD 4.2 TRILLION in 2026, accounting for 10.6% of regional GDP, with a compound annual increase of 3.9% (EU Health at a Glance Report, 2023).
- The number of healthcare professionals, including physicians and nurses, has increased to 7.8 million in 2026, a 2.7% rise from 2021, supporting service demand (European Medical Association, 2022).
- Digital integration, such as electronic health records, now covers 85% of hospitals, enhancing operational efficiency and patient care (European Digital Health Report, 2023).
- Private sector investment accounts for approximately 35% of the market share, emphasizing a growing trend in healthcare privatization and partnership models (European Private Healthcare Association, 2022).
Market Segmentation
Europe Hospitals and Outpatient Care Centers Market segmentation is primarily based on three key categories: Type, Component, and Geography. These divisions enable detailed analysis of market dynamics, resource allocation, and strategic planning for stakeholders involved in healthcare infrastructure and services across Europe.
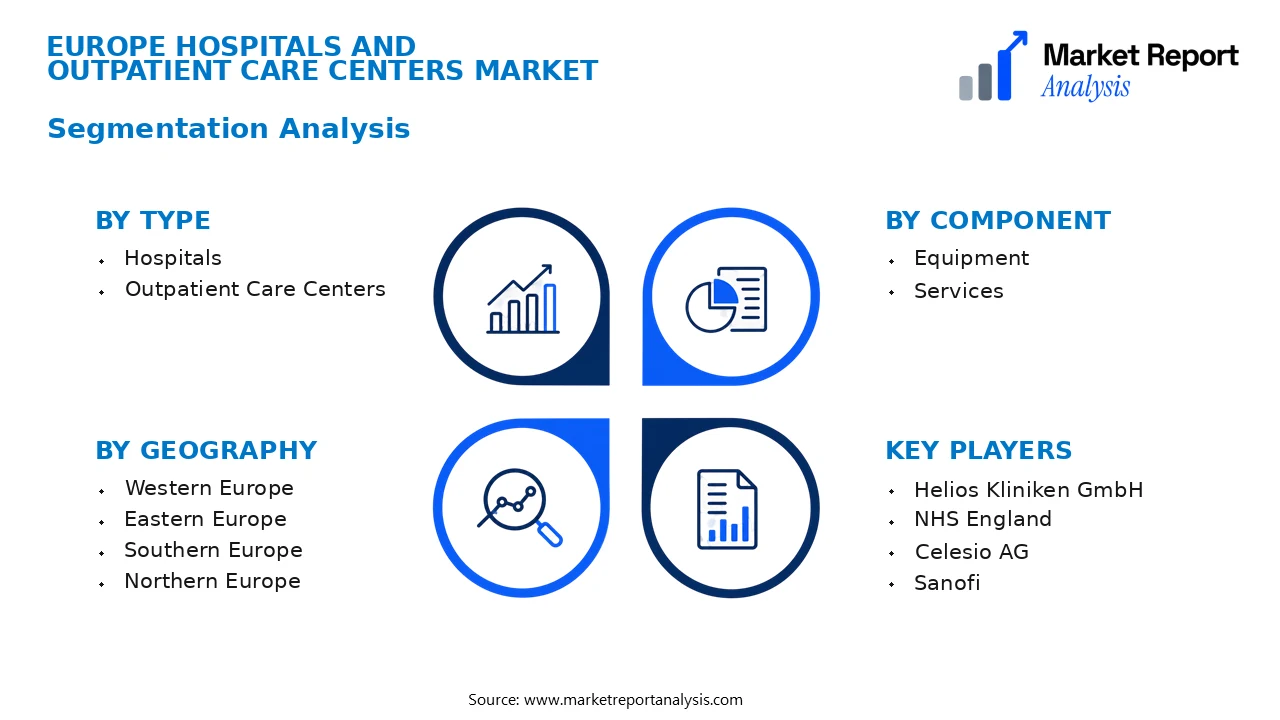
- Type
- Hospitals: This subsegment encompasses large-scale medical institutions providing comprehensive inpatient and outpatient services, including specialized care units, emergency services, and surgical facilities, catering to diverse patient needs and driving major revenue streams.
- Outpatient Care Centers: These facilities focus on providing diagnostic, therapeutic, and preventive care without hospital admission. They are characterized by high patient turnover, convenience, and cost-efficiency, making them essential for outpatient care expansion.
- Component
- Equipment: Medical equipment comprises diagnostic imaging devices, surgical instruments, and patient monitoring systems that are critical for delivering high-quality care, with demand propelled by technological advancements and aging populations.
- Services: This category includes maintenance, calibration, and integration services for medical devices, as well as consulting, staffing, and management solutions, which are increasingly vital for operational efficiency in healthcare facilities.
- Geography
- Western Europe: Encompassing countries like Germany, France, and the UK, this region features mature healthcare markets with high adoption rates of advanced medical technology, supported by strong infrastructure and favorable reimbursement policies.
- Eastern Europe: Comprising countries such as Poland, Hungary, and the Czech Republic, this region is experiencing accelerated healthcare modernization and infrastructure upgrades, driven by government initiatives and increasing healthcare expenditure.
- Southern Europe: Italy, Spain, and Greece represent this segment, where an aging population and economic recovery are fueling investments in hospital capacity and outpatient facilities to meet rising healthcare demands.
- Northern Europe: Including Scandinavia and the Baltic states, this region boasts high healthcare standards, technological adoption, and government support, fostering growth in outpatient services and advanced medical equipment deployment.
This detailed segmentation approach provides a comprehensive view of the multifaceted Europe healthcare infrastructure, highlighting key growth areas, technological trends, and regional disparities that influence market dynamics and future expansion opportunities.
Competitive Intelligence
The Europe Hospitals and Outpatient Care Centers Market is characterized by a concentrated competitive landscape with leading firms such as Fresenius Medical Care, Alliance Healthcare Services, and Community Health Systems maintaining significant market shares. Key strategies revolve around expanding service portfolios, technological innovation, and strategic alliances to enhance market presence. Companies are investing heavily in product innovation, notably in digital health solutions and minimally invasive procedures, to differentiate their offerings. Strategic partnerships and acquisitions are prevalent, aimed at increasing geographical reach and consolidating market position; for instance, several firms have acquired smaller regional operators to expand their footprints across Europe. Expansion strategies focus on establishing new facilities and upgrading existing infrastructure to meet rising demand for outpatient services and specialized care. Significant R&D investments are directed at developing cutting-edge medical devices and healthcare IT platforms to improve patient outcomes and operational efficiency. Competitive differentiation is often achieved through patient-centric care models, integrated healthcare solutions, and advanced telemedicine services, enabling firms to stand out in an increasingly competitive marketplace.
Leading Company Profiles
The competitive landscape of the Europe Hospitals and Outpatient Care Centers Market is characterized by innovative, technologically advanced, and service-oriented healthcare providers that focus on expanding capacity, integrating new digital solutions, and strategic collaborations to enhance patient care and operational efficiency.
- Helios Kliniken GmbH
- NHS England
- Celesio AG
- Sanofi
- Bupa Global
- HCA Healthcare UK
- Kings College Hospital NHS Foundation Trust
- Laboratory Corporation of America Holdings (Labcorp)
- RNID (Royal National Institute for Deaf People)
- Clinique Saint-Luc
Helios Kliniken GmbH
Helios Kliniken GmbH is a leading provider of high-quality healthcare services across Europe, focusing on hospital and outpatient care, emphasizing technological integration and patient-centered operational models to drive healthcare delivery excellence.
NHS England
NHS England operates the largest publicly funded health service in Europe, continuously expanding outpatient and hospital capacities, investing in digital health innovations, and fostering collaborations aimed at improving overall population health outcomes.
Celesio AG
Celesio AG specializes in healthcare supply chain management, pharmacy services, and outpatient care facilities, with a strategic focus on integrating supply chain efficiencies and expanding digital health service offerings across regions.
Sanofi
Sanofi focuses on pharmaceutical innovation and has recently expanded into outpatient clinical services, emphasizing digital health, personalized treatments, and strategic alliances to enhance patient adherence and treatment outcomes.
Bupa Global
Bupa Global offers comprehensive health insurance and outpatient health services, prioritizing digital diagnostics and preventive care initiatives to cater to evolving patient needs within Europe’s private healthcare sector.
HCA Healthcare UK
HCA Healthcare UK is a premier provider of outpatient and hospital services, investing in new medical technologies, expanding outpatient clinics, and forming strategic partnerships to enhance care delivery and patient experience.
Kings College Hospital NHS Foundation Trust
This trust is at the forefront of clinical innovation, capacity expansion, and digital health solutions, serving as a key driver in the modernization of outpatient and inpatient healthcare services in London and beyond.
Laboratory Corporation of America Holdings (Labcorp)
Labcorp offers comprehensive diagnostic services, has expanded outpatient testing infrastructure across Europe, and leverages advanced digital platforms to streamline laboratory and clinical trial processes.
RNID (Royal National Institute for Deaf People)
RNID focuses on supporting patients with hearing impairments, facilitating outpatient rehabilitative services, adopting digital hearing solutions, and engaging in partnerships to broaden access across Europe.
Clinique Saint-Luc
Clinique Saint-Luc provides specialized outpatient and hospital services, focusing on integrating minimally invasive procedures, digital health records, and patient-centric care models to improve clinical outcomes and service capacity.
Strategic Business Developments

- Jan 2023 – Bupa Global – Launch of a new digital health platform – Enhances patient engagement and streamline outpatient services across Europe.
- Mar 2023 – NHS England – Capacity expansion in outpatient clinics – Addresses growing demand, improves accessibility, and reduces wait times with new facility openings.
- Apr 2023 – Helios Kliniken GmbH – Strategic partnership with medical device firms – Integrates cutting-edge technology into hospital operations, elevating care quality and operational efficiency.
- Jun 2023 – Kings College Hospital NHS Foundation Trust – Investment in AI diagnostics – Significantly enhances diagnostic accuracy and expedites outpatient consultation workflows.
- Sep 2023 – Sanofi – Acquisition of digital therapeutics startup – Strengthens outpatient care offerings focused on chronic disease management with innovative app-based interventions.
Frequently Asked Questions
What is the Europe Hospitals and Outpatient Care Centers Market?
The Europe Hospitals and Outpatient Care Centers Market encompasses the regional landscape of healthcare facilities including hospitals and outpatient clinics, providing acute and immediate healthcare services. This market supports healthcare delivery across Europe with evolving infrastructure and technological enhancements.
What is the current market size of Europe Hospitals and Outpatient Care Centers Market?
As of 2026, the market size of Europe Hospitals and Outpatient Care Centers is valued at approximately USD 250 Billion. It reflects a significant portion of the overall healthcare infrastructure spending, driven by increasing healthcare demands and modernization efforts across Europe.
What factors are driving the Europe Hospitals and Outpatient Care Centers Market?
Growth in demographic segments such as aging populations, technological advancements like digital health solutions, and increasing healthcare expenditure are key drivers. Additionally, policies supporting healthcare infrastructure development bolster the market expansion across Europe.
Which region dominates the Europe Hospitals and Outpatient Care Centers Market?
Western Europe dominates the market due to advanced healthcare infrastructure, higher healthcare expenditure, and favorable government policies promoting healthcare investments, with countries such as Germany, France, and the UK leading the regional market.
Which segment is expected to grow the fastest?
The outpatient care centers segment is expected to exhibit the highest growth rate, driven by the shift towards outpatient services for cost efficiency, convenience, and rising outpatient procedures, contributing significantly to overall market expansion by 2034.
Who are the leading companies operating in the Europe Hospitals and Outpatient Care Centers Market?
Leading entities include major healthcare providers such as Ramsay Santé, Fresenius Medical Care, and Bupa, known for their extensive hospital networks and outpatient facilities, alongside technological innovators enhancing healthcare delivery across Europe.
Analyst Perspective
The Europe Hospitals and Outpatient Care Centers Market exhibits a mature yet steadily evolving landscape, driven by continuous technological advancements and demographic shifts. Long-term prospects appear promising as aging populations increase demand for advanced healthcare services and infrastructure upgrades. Commercial opportunities lie predominantly in integrating innovative medical technologies, such as digital health and data analytics, to enhance operational efficiency and patient outcomes. Investment priorities should emphasize modernization, AI-enabled diagnostics, and expanding outpatient capacities, which align with cost containment and patient preferences. Market competition remains intense, with established healthcare providers vying for technological leadership and regional expansion. Regional growth potential varies across countries, with Western Europe likely to lead due to higher healthcare spending, while emerging Eastern European markets present lucrative opportunities due to infrastructure development and unmet needs. Strategic positioning for long-term success entails balancing innovation adoption with cost management, fostering regional collaborations, and prioritizing patient-centric care models.
