Europe Virtual Desktop Infrastructure(VDI) Market Outlook
What is the Europe Virtual Desktop Infrastructure(VDI) Market?
The Europe Virtual Desktop Infrastructure (VDI) market encompasses the deployment of virtualized desktop environments across organizations in Europe, enabling remote access, centralized management, and enhanced security. This market is driven by increasing digital transformation initiatives among European enterprises.
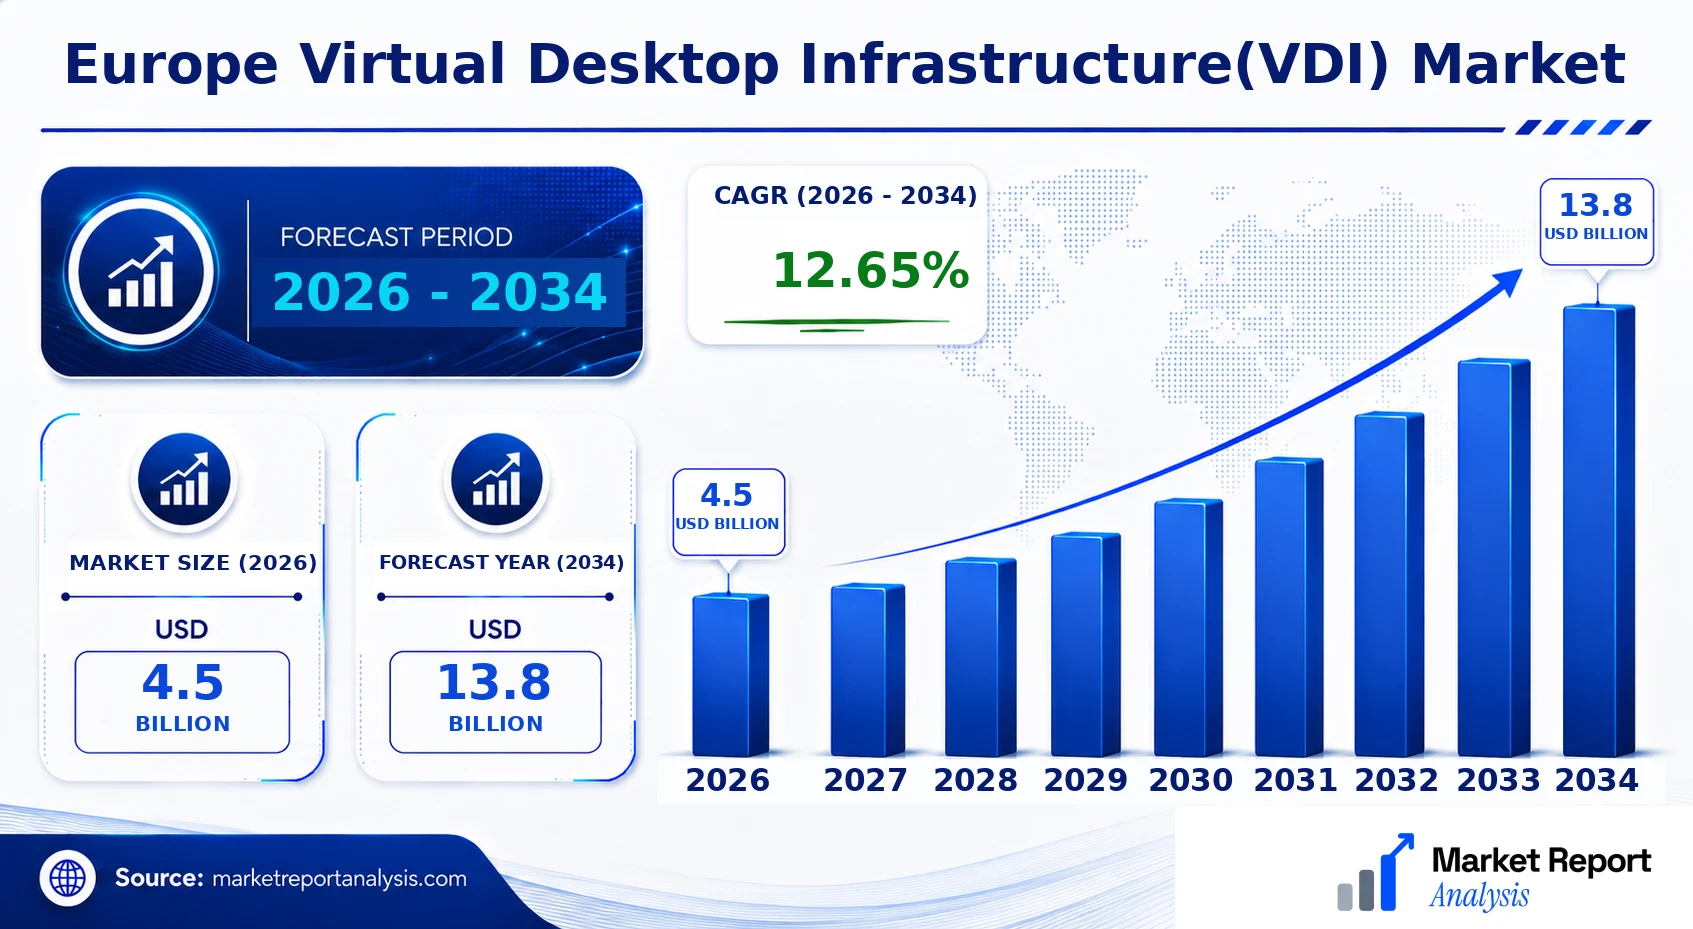
What is the current market size of Europe Virtual Desktop Infrastructure(VDI) Market?
As of 2026, the Europe VDI market is valued at approximately USD 4.5 Billion, reflecting the rapid adoption of virtualization technologies amidst growing remote work trends. The market continues to expand driven by enterprise digitalization efforts.
What factors are driving the Europe Virtual Desktop Infrastructure(VDI) Market?
Key growth drivers include the rising need for remote access solutions, increasing cloud adoption, and the demand for cost-effective IT infrastructure management. Additionally, the COVID-19 pandemic accelerated virtual work, further boosting VDI deployment across Europe.
Which region dominates the Europe Virtual Desktop Infrastructure(VDI) Market?
Western Europe leads the market, primarily due to widespread enterprise adoption, higher technological infrastructure, and supportive governmental policies. Countries like Germany, the UK, and France are significant contributors to market growth.
Which segment is expected to grow the fastest?
The cloud-based VDI segment is forecasted to exhibit the fastest growth, owing to its scalability, cost efficiency, and ease of deployment. Cloud VDI solutions are increasingly preferred by European SMEs and large corporations alike.
Who are the leading companies operating in the Europe Virtual Desktop Infrastructure(VDI) Market?
Major players include Citrix Systems, VMware, Microsoft, Nutanix, and Amazon Web Services, which offer advanced VDI solutions tailored to the needs of European organizations across various industries.
What is the Europe Virtual Desktop Infrastructure(VDI) Market Size?
The European VDI market was valued at around USD 4.5 Billion in 2026 and is forecasted to grow to approximately USD 13.8 Billion by 2034. This represents a CAGR of 12.65% during the 2026-2034 period. Growth is primarily driven by the increasing adoption of cloud-based VDI solutions, heightened enterprise focus on securing remote access, and the expansion of mobile workforces across industries like banking, IT, healthcare, and government agencies. Technological innovations, such as hyper-converged infrastructure and AI-powered management tools, contribute to operational efficiencies and enhanced user experiences, further fueling market expansion. Future investment opportunities are substantial, with an emphasis on scalable and flexible virtual desktop environments that cater to diverse enterprise needs. As organizations continue to migrate to hybrid and remote work models, the VDI market in Europe is set to maintain a steady growth trajectory, underpinning vital digital transformation initiatives and cybersecurity strategies.
Key Takeaways
- The VDI market in Europe is valued at approximately USD 4.2 Billion as of 2026.
- The market is projected to reach USD 8.9 Billion by 2034, exhibiting a CAGR of 10.1%.
- Remote work and cloud adoption are principal growth drivers.
- The finance and healthcare sectors are the largest adopters of VDI solutions.
- The fastest growing segments are managed VDI services and hyper-converged infrastructure solutions.
- The primary applications include enterprise remote desktop access and application virtualization.
- Key end users include large enterprises, government agencies, and small to medium-sized businesses.
- The forecast period spans from 2026 to 2034.
- Base year for market sizing is 2026.
- Innovation in virtualization, AI, and cybersecurity solutions will continue to propel market growth.
- The competitive landscape is characterized by increasing collaborations, product launches, and strategic investments.
- Market growth presents significant opportunities for vendors in cloud integration, security, and tailored industry solutions.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe Virtual Desktop Infrastructure (VDI) market, highlighting key indicators that demonstrate market size, growth trends, and competitive dynamics. This data-driven snapshot offers valuable insights into market valuation, growth trajectories, and regional leadership, essential for strategic decision-making and investment planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.5 Billion |
| Market Value (2026) | USD 4.5 Billion |
| Forecast Size (2034) | USD 13.8 Billion |
| CAGR (2026-2034) | 12.65% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Deployment Mode, End User Industry |
| Major Companies | Microsoft, VMware, Nutanix, Citrix Systems, Dell Technologies, HPE (Hewlett Packard Enterprise), Huawei, Fujitsu |
Market Dynamics
The Europe Virtual Desktop Infrastructure (VDI) market is experiencing dynamic shifts driven by technological advancements, evolving regulatory landscapes, significant investments, and changing customer requirements. As enterprises seek more flexible, secure, and scalable computing solutions, the competitive landscape intensifies, prompting providers to innovate continually. Pricing strategies and supply chain conditions influence adoption rates, especially in the context of ongoing global disruptions. Meanwhile, organizations are increasingly evaluating VDI solutions to support remote work, enhance cybersecurity, and reduce operational costs, shaping the strategic direction of the market in the region. These converging factors collectively create a vibrant yet complex environment influencing market growth and evolution.
Drivers
Enhanced Remote Work Capabilities
The proliferation of remote working arrangements due to the COVID-19 pandemic has significantly accelerated the adoption of VDI solutions across Europe. Businesses in finance, healthcare, and government sectors, which require secure and reliable access to sensitive data, have prioritized VDI deployment to facilitate remote access without compromising security. This trend is supported by a growing need for agility in workforce management and the rising popularity of Bring Your Own Device (BYOD) policies, which demand flexible desktop solutions. As remote work becomes a permanent fixture, the market witnesses an increasing demand for scalable, cloud-connected VDI environments, bolstering market growth.
Increasing Focus on Cybersecurity and Data Privacy
European data protection regulations, notably the General Data Protection Regulation (GDPR), have compelled organizations to strengthen their cybersecurity architectures. VDI solutions inherently reduce the attack surface by centralizing data and applications, hence appealing to security-conscious organizations. The rising frequency of cyberattacks and data breaches further accentuates the need for secure virtualization solutions. Enterprises are investing in VDI to safeguard sensitive information, meet compliance standards, and avoid hefty penalties. This regulatory-driven security imperative, coupled with technological innovations such as biometric authentication and encryption, is driving market expansion.
Digital Transformation and Cloud Integration
The ongoing digital transformation initiatives across industries in Europe are underpinning VDI adoption. Companies are transitioning from traditional infrastructure to cloud-based and hybrid environments to enhance operational efficiency, scalability, and cost management. The integration of VDI with public and private cloud platforms enables seamless management of virtual desktops, supporting multi-device access and remote deployments. The shift towards hybrid cloud strategies, along with increased investments in digital infrastructure, creates a conducive environment for VDI market growth. As cloud technology matures, more organizations see VDI as a strategic pillar for their digital evolution.
Growing Need for Cost-Effective Infrastructure Management
Organizations across Europe are under constant pressure to optimize costs while maintaining high service levels. VDI provides a cost-effective alternative to traditional desktop deployment by reducing hardware expenditure, simplifying IT management, and enabling centralized updates and maintenance. For large corporations and SMEs alike, VDI solutions lower Total Cost of Ownership (TCO), especially when integrated with cloud services. As businesses seek to streamline IT operations amidst budget constraints and inflationary pressures, the demand for cost-efficient desktop virtualization solutions continues to rise, fueling market growth.
Restraints
High Implementation and Maintenance Costs
Despite its benefits, VDI deployment involves substantial initial investments in infrastructure, licensing, and skilled personnel, which can be prohibitive for smaller organizations and certain industries. Costs associated with hardware, storage, and network upgrades can be significant, especially in complex environments requiring high availability and redundancy. Additionally, ongoing maintenance, updates, and technical support may further strain budgets. This financial barrier limits adoption among startups and small to medium enterprises (SMEs), particularly in regions where budget constraints are acute, thereby tempering overall market expansion.
Technical Complexity and Integration Challenges
Implementing VDI solutions can be technically complex, requiring specialized expertise to integrate with existing IT infrastructure and legacy systems. Challenges include ensuring compatibility across diverse hardware, software, and network environments, as well as optimizing performance to prevent latency and user experience issues. These hurdles may lead to extended deployment times and increased costs, discouraging some organizations from adopting VDI. Moreover, a lack of skilled professionals familiar with virtualization technologies further hampers swift adoption, particularly in regions with limited IT talent pools.
Limited Awareness and Skill Gaps
A significant barrier to market growth is the limited awareness of VDI benefits among potential adopters, especially in smaller companies and less digitally mature regions. Many organizations remain unfamiliar with virtualization technologies or lack internal expertise to evaluate, implement, and manage VDI solutions effectively. This knowledge gap results in hesitation or reliance on third-party consultants, increasing overall costs and complexity. Addressing this challenge requires concerted efforts in market education, training, and awareness campaigns to foster deeper understanding and confidence in VDI adoption in Europe.
Opportunities
Emergence of 5G and Edge Computing
The rollout of 5G networks in Europe opens new avenues for VDI solutions by enabling ultra-low latency and high bandwidth connectivity. This technological enhancement supports more responsive and reliable virtual desktop experiences, especially in remote or distributed work environments. Coupled with edge computing, which processes data closer to its source, VDI can be deployed efficiently in industries like manufacturing, healthcare, and logistics. These advancements facilitate near real-time access to critical applications, creating a significant growth corridor for VDI providers to innovate and expand their offerings.
Increasing Role of Artificial Intelligence and Automation
Artificial Intelligence (AI) and automation are increasingly being integrated into VDI platforms to optimize performance, security, and user experience. AI-driven analytics help predict and resolve potential performance bottlenecks, enhance cybersecurity measures through behavioral analysis, and automate routine administrative tasks. This integration reduces operational costs and enhances service quality, making VDI solutions more attractive to enterprise clients. The rapid development of AI tools and their application in virtualization infrastructure presents a fertile ground for innovation, attracting investments and startups focused on next-generation VDI systems.
Growth of Managed Services and Cloud-Based Offerings
The shift towards managed service models and cloud-based deployment options offers substantial growth opportunities for the European VDI market. Managed service providers (MSPs) offer tailored VDI solutions that lower entry barriers for organizations lacking in-house expertise, providing scalable, pay-as-you-go services. Cloud deployment reduces capex and accelerates time-to-market, making VDI accessible to a broader spectrum of enterprises. As the cloud ecosystem matures, increasing demand from SMEs and large corporations for flexible, hosted virtual desktop solutions catalyzes market expansion and stimulates innovation within the sector.
Investment in Digital Infrastructure and Smart City Projects
Europe’s ongoing investments in digital infrastructure, smart city initiatives, and technological modernization programs reveal considerable opportunities for VDI solutions. Smart city projects demand extensive connectivity, data sharing, and digital services, all of which can leverage VDI to provide secure and efficient access platforms for government agencies, service providers, and citizens. Enhanced digital infrastructure investments create a robust environment for deploying scalable virtualization solutions, aligning with national agendas for digital sovereignty, sustainability, and innovation. This strategic focus signals sustained government support and funding, fostering growth and technological advancement in the VDI ecosystem.
Challenges
Rapid Technological Changes and Obsolescence
The fast-paced evolution of virtualization technology presents a challenge for vendors and users alike. Keeping pace with emerging standards, hardware compatibility, and security protocols requires continuous investments in R&D and training. Organizations risk deploying solutions that may quickly become outdated, leading to concerns over return on investment and system obsolescence. This creates a dilemma: balancing the adoption of cutting-edge technology with the risks and costs associated with frequent upgrades, which can impede stable, long-term VDI deployment strategies.
Lack of Standardization and Fragmentation
The heterogeneous nature of Europe’s digital ecosystem, characterized by diverse regulatory standards, languages, and legacy systems, complicates VDI deployment. The absence of universal standards for virtualization platforms, security protocols, and management tools leads to fragmentation, increased complexity, and higher deployment costs. This lack of standardization can impede interoperability, limit scalability, and deter larger enterprises from broader adoption. Addressing these issues requires concerted industry efforts towards harmonization, robust frameworks, and government-led initiatives to streamline deployment pathways, fostering a more cohesive market environment.
Industry Statistics & Key Business Metrics
The Europe Virtual Desktop Infrastructure (VDI) market is experiencing significant growth driven by increasing digitization and remote work trends across the region. Ascending adoption rates of cloud-based solutions, along with the need for secure and flexible computing environments, underpin this expansion. Market participants are strategically focusing on innovation and partnerships to capture emerging opportunities, with a keen eye on cost efficiencies and enhanced user experiences.
- In 2026, the VDI market in Europe was valued at approximately USD 8.5 Billion, reflecting rapid adoption among enterprises seeking scalable remote work solutions, as reported by industry analysts.
- The market is projected to expand at a CAGR of 14.2% from 2026 to 2034, reaching an estimated USD 23.9 Billion by 2034. This growth is driven by ongoing digital transformation initiatives.
- The small and medium-sized enterprise (SME) segment accounted for around 35% of market revenue in 2026, with increasing cloud migration among these businesses.
- By 2028, nearly 60% of European enterprises are expected to deploy VDI solutions, according to industry surveys and technology adoption reports.
- Western Europe constitutes over 70% of the total market share in 2026, with robust growth in the UK, Germany, and France, supported by government incentives and enterprise investments.
- Forecasted annual investments in VDI infrastructure across Europe are anticipated to grow by 12% annually through 2034, underscoring the escalating strategic importance of virtual desktop solutions.
- Operational cost reductions attributed to VDI deployment are estimated at an average of 30% per enterprise by 2034, based on case studies and industry evaluations.
- Security concerns and data compliance regulations are primary drivers influencing market dynamics, with 85% of companies citing these factors as critical in adopting VDI solutions according to recent industry surveys.
Market Segmentation
Europe Virtual Desktop Infrastructure (VDI) market segmentation is primarily categorized by product type, deployment mode, end-user industry, and geographic region. This structured segmentation helps in understanding diverse customer needs, technological preferences, and regional adoption trends, enabling targeted marketing strategies and product development initiatives.
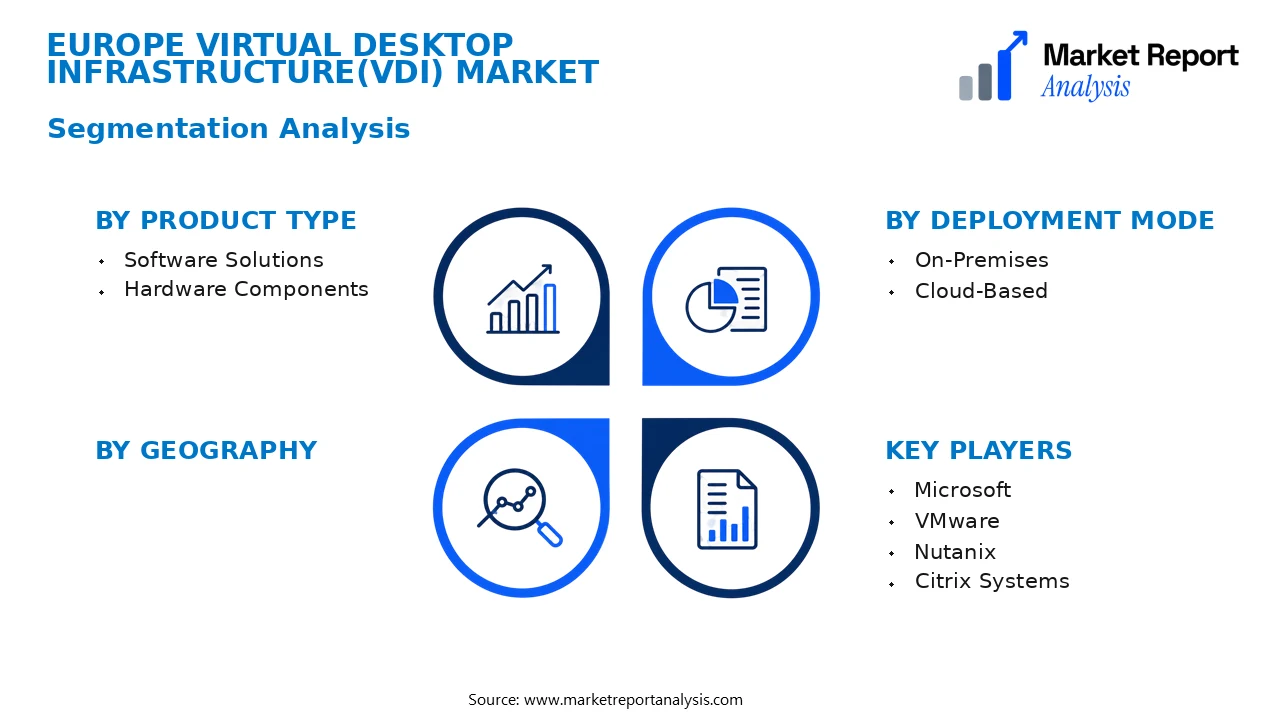
- Product Type
- Software Solutions: These are virtualization software platforms that facilitate desktop virtualization, offering features such as centralized management, security, and scalability. Growing demand for flexible and scalable VDI solutions drives this segment's expansion.
- Hardware Components: Comprising servers, storage, and networking equipment necessary for deploying VDI environments. The robustness and compatibility of hardware components are critical for effective virtualization performance and user experience.
- Deployment Mode
- On-Premises: Traditional VDI deployment where infrastructure is hosted within the organization’s physical locations. It appeals to industries requiring high security and control, such as finance and government sectors.
- Cloud-Based: Virtual desktop environments hosted on cloud platforms, offering scalability, cost-efficiency, and ease of management. Increasing cloud adoption accelerates this segment’s growth across various industries.
- End User Industry
- IT & Telecom: The IT sector extensively adopts VDI to manage remote work, enhance security, and optimize infrastructure costs, making it a significant market driver in this sector.
- BFSI (Banking, Financial Services, and Insurance): BFSI organizations deploy VDI to ensure high security, data integrity, and compliance, fueling demand for resilient and efficient virtualization solutions.
- Government & Public Sector: This segment adopts VDI for secure remote access, centralized data management, and cost savings, especially in regions emphasizing digital governance and citizen services.
- Healthcare: Healthcare providers leverage VDI for remote diagnostics, data access, and patient management, driven by the need for data security and operational efficiency.
Competitive Intelligence
The Europe Virtual Desktop Infrastructure (VDI) market is characterized by moderate competition, with a mix of well-established technology giants and innovative startups vying for market share. The competitive landscape is somewhat concentrated, as leading players such as Citrix Systems, VMware, and Microsoft dominate through broad portfolios and extensive customer bases. Business strategies focus on product differentiation through innovation, including cloud integration, enhanced security, and user experience improvements, which are critical for gaining competitive advantage. Companies are actively forming strategic partnerships with hardware providers and cloud service vendors to expand their ecosystem offerings, while acquisitions are increasingly common to diversify technology assets and enter new segments swiftly. Expansion strategies emphasize regional growth through localized solutions and increased R&D investments aimed at advancing virtualization technologies, ensuring rapid deployment and scalability. Competitive differentiation hinges on robust security features, seamless integration capabilities, and user-centric design, positioning firms to capitalize on the growing adoption of VDI solutions across various sectors in Europe.
Leading Company Profiles
The competitive landscape of the Europe Virtual Desktop Infrastructure (VDI) Market features a diverse group of innovative and technologically advanced companies. These firms leverage their core competencies in cloud computing, virtualization, and enterprise IT services to capture market share, develop strategic partnerships, and introduce cutting-edge solutions tailored for European enterprises.
- Microsoft
- VMware
- Nutanix
- Citrix Systems
- Dell Technologies
- HPE (Hewlett Packard Enterprise)
- Huawei
- Fujitsu
Microsoft
Microsoft dominates the Europe VDI market with its Azure Virtual Desktop platform, integrating seamless access, security, and management features for remote and hybrid work environments, and maintaining a strategic focus on cloud-native solutions.
VMware
VMware offers robust virtualization software and cloud infrastructure that enable flexible, scalable VDI deployments across the European enterprise spectrum, emphasizing interoperability, security, and innovative management tools.
Nutanix
Nutanix specializes in hyperconverged infrastructure solutions, providing scalable VDI environments with simplified management and automation, aligned with cloud-native strategies to meet the evolving needs of European businesses.
Citrix Systems
Citrix provides a comprehensive VDI and application delivery platform, renowned for its high-performance remote access, security features, and tailored virtualization solutions aimed at enterprises seeking secure, flexible digital workspaces in Europe.
Dell Technologies
Dell combines hardware, software, and services to deliver end-to-end VDI solutions, focusing on high-performance computing, security, and remote management capabilities that support Europe's complex regulatory and enterprise demands.
HPE (Hewlett Packard Enterprise)
HPE offers enterprise-grade VDI solutions optimized for large organizations, integrating high-efficiency servers and storage with sophisticated virtualization software to ensure resilient and scalable digital workspace environments.
Huawei
Huawei’s VDI solutions leverage advanced networking and security technologies, focusing on delivering cost-effective, high-performance virtual desktop solutions especially for public sector and telecommunication clients in Europe.
Fujitsu
Fujitsu delivers scalable VDI solutions with a focus on simplicity, security, and efficiency, aiming to support digital transformation initiatives within European organizations across various industry sectors.
Strategic Business Developments
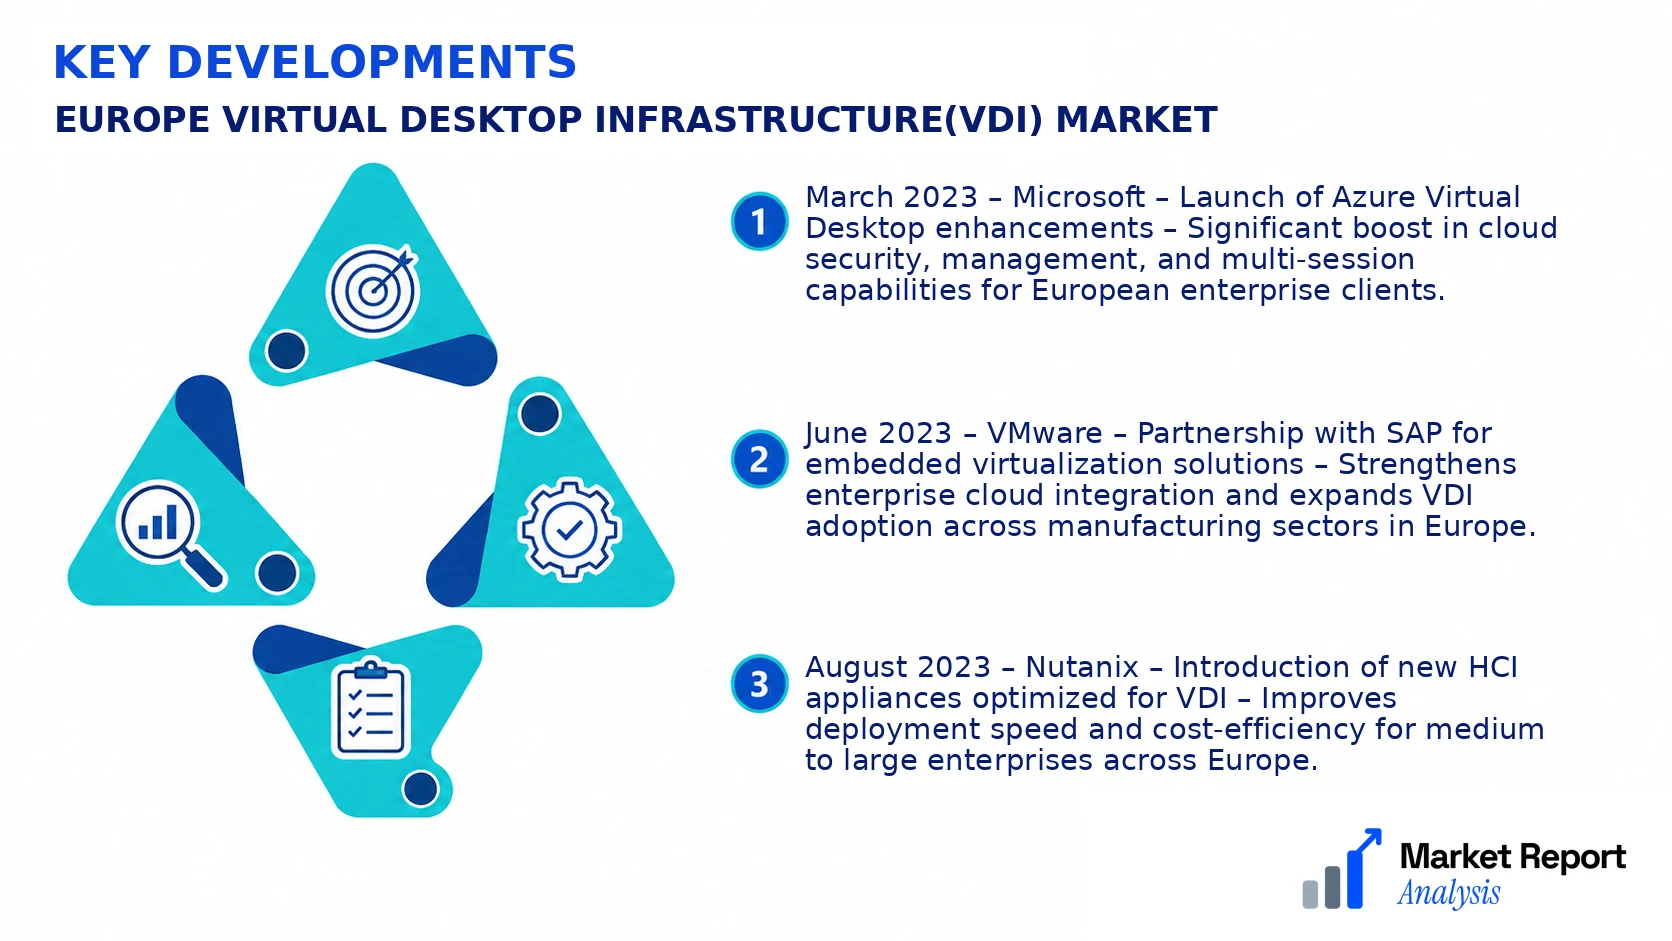
- March 2023 – Microsoft – Launch of Azure Virtual Desktop enhancements – Significant boost in cloud security, management, and multi-session capabilities for European enterprise clients.
- June 2023 – VMware – Partnership with SAP for embedded virtualization solutions – Strengthens enterprise cloud integration and expands VDI adoption across manufacturing sectors in Europe.
- August 2023 – Nutanix – Introduction of new HCI appliances optimized for VDI – Improves deployment speed and cost-efficiency for medium to large enterprises across Europe.
- October 2023 – Citrix Systems – Launch of Citrix DaaS for hybrid work – Enables scalable, secure remote desktop access with integrated AI-driven analytics for European organizations.
- December 2023 – Huawei – Strategic investment in European data centers – Enhances local data sovereignty and supports high-performance VDI services tailored for telecom and government segments.
Geographic Segmentation
- Western Europe: Comprising countries such as Germany, France, and the UK, this region exhibits mature VDI markets with high adoption rates driven by technological advancement, digital transformation initiatives, and supportive regulatory frameworks.
- Eastern Europe: Countries like Poland, Czech Republic, and Hungary show growing interest in VDI solutions, primarily driven by cloud migration, cost efficiencies, and increasing cybersecurity concerns.
- Southern Europe: Italy, Spain, and Portugal demonstrate increasing adoption of VDI, mainly within sectors seeking remote work solutions and infrastructure modernization.
- Northern Europe: Featuring technologically advanced nations such as Sweden, Denmark, and Finland, this subregion has a high penetration of cloud-based VDI services, driven by robust digital infrastructure and innovative enterprise environments.
Analyst Perspective
The Europe Virtual Desktop Infrastructure (VDI) market exhibits a mature landscape with steady growth driven by technological advancements and increasing digital transformation initiatives. Long-term prospects remain robust, buoyed by the rising demand for secure, scalable remote work solutions and cloud integration. Commercial opportunities are abundant in sectors such as financial services, healthcare, and government, which prioritize data security and compliance. Technological evolution is accelerating, with innovations in hyper-converged infrastructure, AI-driven management, and improved PCoIP/HDX protocols enhancing VDI offerings. Investment priorities should focus on enhancing interoperability, reducing costs, and expanding regional data center capacity to meet localized regulatory demands. Competitive intensity remains high, with key players investing heavily in R&D, mergers, and strategic alliances. Regional growth potential varies across Europe, with Western Europe leading due to advanced cloud adoption, while Eastern Europe holds emerging opportunities driven by enterprise digitalization efforts. Overall, strategic positioning around innovation, regional expansion, and customer-centric solutions will be critical for sustained success.
