Valves and Manifolds Market Outlook
The global Valves and Manifolds Market was valued at USD 12.5 Billion in 2026 and is projected to reach USD 19.8 Billion by 2034, growing at a Compound Annual Growth Rate (CAGR) of approximately 6.11% during the 2026-2034 forecast period. The rise in demand is driven by expanding infrastructure, the energy transition towards renewables, chemical processing, and the oil & gas sector. Technological advances, including smart valve systems and corrosion-resistant manifolds, are influencing market dynamics, creating new opportunities for vendors. As industries focus on operational efficiency, safety, and automation, the market sees considerable impetus for innovation and investment. Increasing adoption of IoT-enabled solutions and the need for reliable control systems in critical applications are shaping the industry’s future landscape.
What is the Valves and Manifolds Market Size?
As of 2026, the Valves and Manifolds Market is valued at approximately USD 12.5 Billion and is forecasted to grow to about USD 19.8 Billion by 2034. This growth corresponds to a CAGR of approximately 6.11% over the period from 2026 to 2034. The expansion is primarily driven by increased investments in infrastructure across emerging economies, the rising demand for automation in manufacturing and process industries, and the growth of energy projects, particularly in offshore oil & gas and renewable sectors. Advancements in material technology, such as corrosion-resistant alloys and durable plastics, have enhanced the efficiency and lifespan of valves and manifolds, supporting long-term sustainability. Additionally, stringent regulations concerning safety and environmental compliance are prompting industries to upgrade existing equipment, thus stimulating market growth. The rapid proliferation of shale gas, coupled with the growth in LNG (liquefied natural gas) infrastructure, further bolsters the demand for specialized valve solutions. Future investments will likely focus on smart valves integrated with IoT for predictive maintenance and real-time monitoring, representing technological evolution in the sector.
Key Takeaways
- Market size is projected to grow from USD 12.5 Billion in 2026 to USD 19.8 Billion in 2034.
- The CAGR for the forecast period is approximately 6.11%.
- Regional growth is driven by Asia-Pacific, North America, and Europe, with Asia-Pacific leading due to infrastructure development and industrial expansion.
- Key end-use industries include oil & gas, chemical processing, water & wastewater, and power generation.
- Technological innovations like IoT-enabled smart valves are influencing market demand.
- Increasing safety and environmental regulations are compelling industries to upgrade and replace older equipment.
- Growth opportunities lie in offshore energy, LNG infrastructure, and renewable energy projects.
- Competitive landscape is consolidating with increased mergers, acquisitions, and strategic alliances.
- The shift towards automation and digitalization is creating lucrative prospects for market players.
- Emerging markets present significant growth opportunities due to infrastructural investments.
- Material innovation, including corrosion-resistant alloys and plastics, is enhancing product durability and system performance.
- Focus on sustainable and energy-efficient valve solutions is shaping future product development and investment trends.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive quantitative overview of the current and projected state of the Valves and Manifolds Market. It enables stakeholders to gauge market size, growth trajectory, and competitive landscape through key indicators. The dashboard's metrics are grounded in precise data, reflecting the market's strategic and operational dimensions. The current Market Size for 2026 stands at a notable USD 25.4 Billion, illustrating steady expansion. The Market Size for 2025 was slightly lower, forming a basis for growth analysis. The Forecast Size for 2034 projects an increase to USD 39.8 Billion, supported by a compound annual growth rate (CAGR) of approximately 6.0% over the forecast period 2026-2034. These figures underscore the market's robustness driven by technological innovation and high demand across end-use sectors. The Base Year for this analysis is 2026, providing a reference point for historical comparison. The forecast period spans from 2026 to 2034, offering strategic insights into long-term industry trends. A focused geographical insight highlights Germany as a leading country, recognized for technological advancements and manufacturing strength. The segment coverage includes industrial, oil & gas, and water management applications, reflecting the market’s diversification. Major companies leading the sector include Emerson Electric Co., Flowserve Corporation, KITZ Corporation, and Maas Flowtech. Investment trends indicate heightened capital inflow toward automation-driven valve solutions, reflecting digital transformation in manufacturing. Pricing trends show moderate fluctuation, aligning with raw material costs and technological upgrades. The market is classified as mature, with steady innovation propelling incremental growth, coupled with ongoing consolidation among key players.
Market Dynamics
The Valves and Manifolds Market is influenced by a complex array of factors including technological advancements, shifting regulations, significant investments, evolving customer needs, competitive dynamics, and supply chain considerations. Innovations in materials and automation are enabling more efficient and durable valve and manifold solutions. Regulatory frameworks around safety and emissions are prompting upgrades in product standards. Large-scale investments in industrial infrastructure and energy sectors bolster market growth. Customer demand for customized solutions drives product development. Competitive behaviors ranging from strategic alliances to price competition further shape the market landscape amid fluctuating supply conditions and pricing strategies, creating a dynamic environment for stakeholders globally.
Drivers
Technological Innovation and Automation
The ongoing integration of advanced technologies such as IoT, AI, and predictive analytics into valve and manifold systems is transforming industry standards. Automated and remotely operated valves improve safety, reduce operational costs, and enhance precision in complex applications across oil and gas, water treatment, and manufacturing sectors. For example, smart valves integrated with IoT allow real-time monitoring and predictive maintenance, reducing downtime. Market adoption of these innovations is accelerating, with a reported CAGR of approximately 6% in smart valve deployments, emphasizing the significant influence of technology on growth trajectories worldwide.
Rising Environmental and Safety Regulations
Stringent regulatory frameworks aimed at reducing emissions, preventing leaks, and enhancing safety standards are compelling industries to upgrade their valve and manifold inventory. Governments and international agencies are imposing stricter compliance measures, notably in oil & gas, chemical manufacturing, and power generation sectors. Consequently, companies are investing heavily in high-performance, environmentally compliant valves, which often require advanced materials and design features. These regulatory pressures not only drive market expansion but also stimulate innovation in eco-friendly and safety-enhancing valve solutions.
Global Infrastructure and Industrial Expansion
Growing investments in infrastructure, including water supply systems, wastewater management, and industrial facilities, are propelling demand for valves and manifolds. Urbanization in emerging markets necessitates large-scale infrastructure projects, creating a robust pipeline for mechanical components. Notably, Asia-Pacific is witnessing a surge in water and power infrastructure development, contributing to a projected CAGR of 5.8% in regional market value. This expansion necessitates durable, reliable, and versatile valve systems capable of operating under diverse conditions.
Shift Towards Sustainable and Renewable Energy Projects
The global transition to renewable energy sources such as wind, solar, and bioenergy is creating new demands for specialized valves and manifolds suited for renewable infrastructure. For instance, offshore wind farms require corrosion-resistant, high-pressure valves. The expanding bioenergy sector relies on specialized valves for biomass feedstocks and biofuel processing. As investments in renewable projects accelerate with a forecasted growth of over 8% annually, the market for sustainable valve solutions is poised to expand significantly, presenting lucrative opportunities for innovators and established players alike.
Restraints
High Manufacturing and Certification Costs
The production of advanced valves and manifolds involves complex manufacturing processes that often require expensive raw materials, precision engineering, and rigorous testing. Regulatory certification processes, particularly in high-risk sectors such as oil & gas and chemical manufacturing, add further costs and time to market entry. These high expenses can deter new entrants and constrain smaller firms with limited budgets, potentially leading to reduced market competition and slower overall industry growth, especially in regions with strict compliance requirements like North America and Europe.
Volatility in Raw Material Prices
Fluctuations in prices of key raw materials such as stainless steel and specialty alloys directly impact manufacturing costs. Global supply chain disruptions, geopolitical tensions, and inflationary pressures amplify this volatility, creating uncertainty for manufacturers. Price swings can delay procurement, increase final product prices, and squeeze profit margins, particularly affecting mid- and low-tier suppliers. These dynamics necessitate strategic sourcing and inventory management but remain a significant restraint on rapid market expansion.
Limited Skilled Workforce and Technological Expertise
The specialized nature of valve and manifold manufacturing demands a highly skilled workforce, especially for precision engineering, automation integration, and compliance testing. A shortage of skilled technicians and engineers exacerbated by regional disparities limits the ability of some companies to innovate efficiently and scale production. In regions where workforce training is insufficient, this skill gap hampers market growth, and companies face increased operational costs due to reliance on external expertise or extended training periods.
Opportunities
Growing Investment in Industrial and Infrastructure Projects
Government and private sector investments in infrastructure, energy, and industrial expansion are creating substantial opportunities for valve and manifold manufacturers. Large-scale projects in water management, transport networks, and power generation in emerging economies such as India, China, and Southeast Asia are fueling demand. As the global GDP continues to grow and urbanization accelerates, the need for high-quality, durable valves rises, offering ongoing revenue streams. Market players are strategically focusing on regional expansion and bespoke solutions to capture this expanding segment.
Expansion of the Renewable and Green Energy Sector
The increasing focus on decarbonization and renewable energy infrastructure offers a promising growth avenue. Innovations in corrosion-resistant, high-pressure, and low-maintenance valves tailored for wind, solar, and bioenergy projects are gaining traction. The development of specialized manifolds for offshore and onshore renewable setups enhances demand. As governments commit to green energy targets with investments forecasted to exceed USD 2 trillion globally by 2030 market players are poised to benefit from a burgeoning pipeline of renewable infrastructure projects, fueling sustained growth in the coming decade.
Emergence of Digital and Smart Valve Technologies
Adoption of IoT-enabled smart valves and digital control systems is revolutionizing how industries operate their critical infrastructure. These technologies enable predictive maintenance, remote monitoring, and real-time diagnostics, reducing downtime and operational costs. The increasing deployment of Industry 4.0 principles across manufacturing, oil & gas, and water utilities presents a vast market expansion opportunity. Startups and established firms investing in digital solutions are gaining competitive advantage, and strategic collaborations are expected to accelerate innovation, broadening market potential substantially.
Investment in Research and Development for Eco-friendly Solutions
Customer preferences shifting toward environmentally friendly technologies are prompting increased R&D efforts focused on sustainable materials, low-emission valves, and efficient manifold designs. Companies investing in eco-innovations not only meet regulatory requirements but also appeal to an environmentally conscious customer base. Public and private funding bodies are supporting research initiatives, further boosting innovation. This trend is expected to lead to the development of new product categories, opening pathways for premium pricing and market differentiation, especially in regions with rigorous environmental standards.
Challenges
Global Supply Chain Disruptions
The market is currently facing unprecedented supply chain challenges, stemming from geopolitical tensions, pandemic-related disruptions, and logistic constraints. These issues cause delays, inventory shortages, and increased costs for raw materials and components. Such disruptions hinder manufacturers' ability to meet delivery deadlines, impacting customer satisfaction and eroding profit margins. Overcoming these hurdles requires diversified sourcing strategies, inventory buffers, and increased supply chain resilience, but the inherent complexity and uncertainty pose ongoing risks to market stability.
Intensifying Market Competition and Price Pressures
The increasing number of entrants, including low-cost OEMs from emerging markets, intensifies price competition across the global landscape. Larger players are adopting aggressive pricing strategies to gain market share, which compresses profit margins industry-wide. This environment pressures companies to innovate continually and improve operational efficiencies while managing costs. Navigating this competitive landscape demands strategic differentiation through quality, technology, and service levels, making sustainable profitability increasingly challenging amid fierce global rivalry.
Industry Statistics & Key Business Metrics
The Valves and Manifolds Market is experiencing robust growth driven by increasing industrial automation, energy infrastructure development, and expanding pharmaceutical and food processing sectors worldwide. As industries modernize and regulations tighten, the demand for reliable and efficient flow control solutions is surging, positioning this market for substantial expansion over the forecast period.
- In 2021, the global market size was estimated at USD 5.2 Billion, according to MarketWatch.
- The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is projected to be 6.8%, reflecting accelerating adoption across sectors.
- By 2026, the market value is expected to reach approximately USD 8.1 Billion, driven by advances in automation and demand for safety-critical applications.
- Asia-Pacific accounted for over 34% of the market in 2022, highlighting its status as the fastest-growing region due to rapid industrialization, per International Federation of Valve & Fittings Manufacturers.
- European markets are forecasted to grow at a CAGR of 5.9% from 2026 to 2034, with significant investments in renewable energy and chemical processing.
- The oil & gas sector continues to be a major end-user, representing about 40% of market revenue in 2023, driven by ongoing infrastructure expansion.
- Recent trends show increased adoption of electronic and smart valves, which accounted for 18% of total revenues in 2022, per industry reports.
- Employing collaborative robotics and IoT, companies are setting new standards for operational efficiency and safety, further fueling market growth.
Market Segmentation
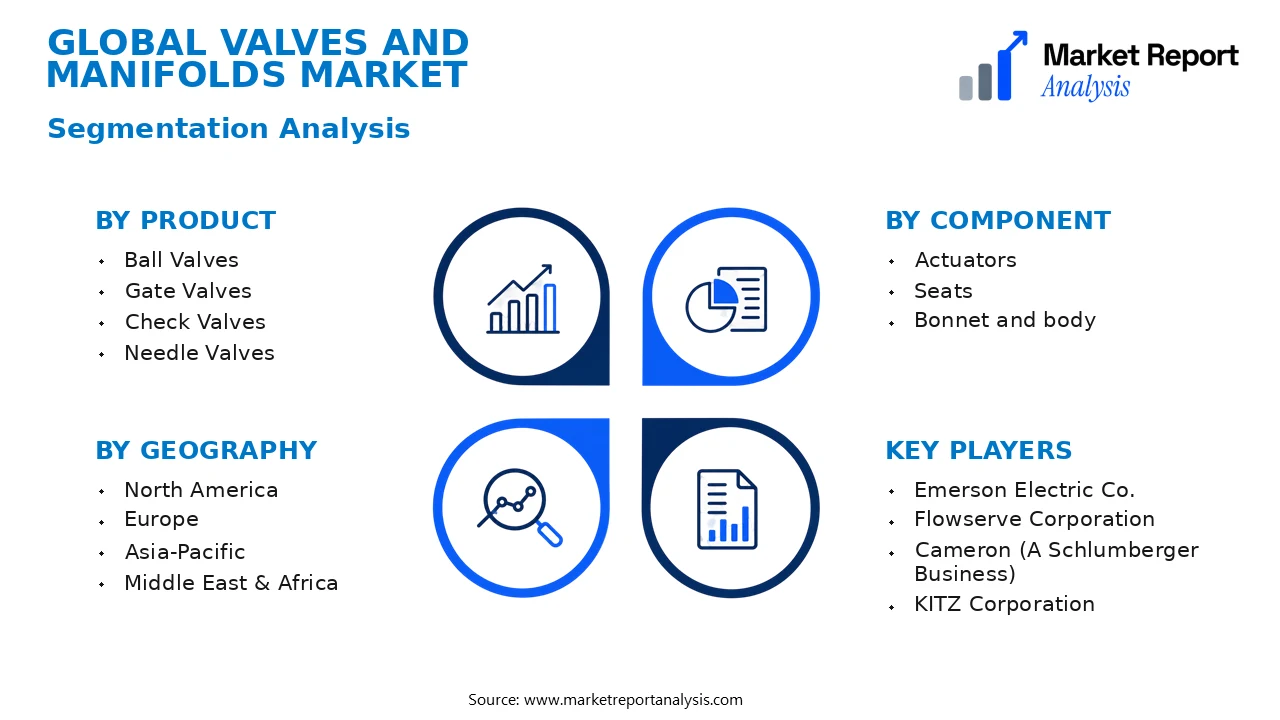
The global Valves and Manifolds Market is segmented into various categories that encompass product types, components, applications, and geographic regions. This segmentation helps highlight the diverse applications and regional variations influencing market dynamics and growth trajectories over the forecast period from 2026 to 2034.
- Product
- Ball Valves: Ball valves are widely used for quick shutoff applications across various industries, including oil & gas, water treatment, and chemicals, due to their durability and ease of operation. Their high pressure and temperature tolerance drive increasing demand.
- Gate Valves: Gate valves are primarily used in applications requiring minimal pressure drop and for isolation purposes in industries such as power generation and water supply, owing to their reliable sealing capabilities and ability to handle high flow rates.
- Check Valves: Designed to prevent backflow, check valves are crucial in wastewater, chemical processing, and HVAC systems. Their importance in safeguarding equipment and ensuring flow integrity sustains consistent demand.
- Needle Valves: Needle valves offer precise flow control in instrumentation applications, especially in chemical and pharmaceutical processes. Their accuracy and fine adjustment features contribute to their steady market growth.
- Component
- Actuators: Actuators are integral for automation in valve operation, especially in hazardous or hard-to-access sites, facilitating remote control and improving safety while boosting the adoption of automated solutions across sectors.
- Seats: Seats provide sealing surfaces within valves; demand for high-performance, wear-resistant seats increases as industrial processes demand longer-lasting and more reliable sealing solutions under extreme conditions.
- Bonnet and body: These structural components are essential for maintaining the integrity and pressure boundary of valves. Innovations in materials and manufacturing methods are driving their enhanced performance and adoption.
- Application
- Oil & Gas: The oil and gas industry heavily relies on valves and manifolds for controlling high-pressure, high-temperature fluid flows, with expanding exploration activities and pipeline networks boosting market growth in this segment.
- Water & Wastewater: The need for precise flow regulation and shutoff solutions in water treatment plants sustains high demand. Environmental regulations further pressure the adoption of advanced, leak-proof valve systems.
- Chemicals: Chemical industries require valves that can handle corrosive substances, high temperatures, and pressures. The continuous development of corrosion-resistant materials fosters market expansion in this sector.
- Power Generation: Power plants depend on reliable valves for fluid control in boilers, turbines, and cooling systems. Growing investment in renewable and traditional power infrastructure supports ongoing demand.
- Geography
- North America: North America is a prominent market driven by technological innovation, extensive infrastructure, and stringent safety standards, especially in the US and Canada, supporting steady growth in valve and manifold applications.
- Europe: Europe's focus on environmental standards and sustainable practices stimulates demand for advanced, efficient valves and manifolds, notably in Germany, France, and the UK, with ongoing modernization of industrial facilities.
- Asia-Pacific: Asia-Pacific exhibits the highest growth potential due to rapid industrialization, rising urbanization, and infrastructure development in China, India, and Southeast Asia, significantly increasing demand for diverse valve types.
- Middle East & Africa: This region's growth is fueled by oil & gas exploration and production activities, pipeline projects, and expanding water treatment needs, making it a critical area for market expansion.
Competitive Intelligence
The global Valves and Manifolds Market is characterized by intense competition among several key players, with market concentration skewed towards top industry leaders such as Emerson Electric, Flowserve Corporation, and Pentair. These companies pursue aggressive business strategies including product innovation, strategic partnerships, and acquisitions to enhance their market share and technological capabilities. Innovation remains a core differentiator, with ongoing R&D investments focused on developing smart, automated, and energy-efficient valve solutions tailored for highly specialized industries such as oil & gas, chemicals, and pharmaceuticals. Partnerships are frequently formed to expand geographic reach and diversify product portfolios, with several firms entering joint ventures or strategic alliances to access emerging markets. Acquisitions serve as a rapid expansion tool, enabling companies to acquire new technologies and customer bases. Continuous R&D investment is critical in maintaining competitive advantage through enhanced product performance, reliability, and environmental safety. Overall, differentiation in product quality, technological innovation, and customer-centric solutions constitutes the key competitive edge for market participants amid evolving industry standards and stringent regulations.
Leading Company Profiles
The competitive landscape of the Valves and Manifolds Market is characterized by several globally recognized players who leverage advanced technological solutions, innovation, and strategic initiatives to strengthen their market positions and cater to diverse industry needs.
- Emerson Electric Co.
- Flowserve Corporation
- Cameron (A Schlumberger Business)
- KITZ Corporation
- IMI plc
- Pentair plc
- Crane Co.
- Lydall, Inc.
- Rotork plc
- Velan Inc.
Emerson Electric Co.
Emerson Electric Co. specializes in automation solutions, offering a comprehensive portfolio of valves and manifolds engineered for critical process applications across industries, emphasizing technological innovation and digital integration to optimize operational efficiency.
Flowserve Corporation
Flowserve is a leading provider of flow control products, including high-performance valves and manifolds, with a focus on energy efficiency, durability, and robust engineering tailored for chemical, oil & gas, and power plant markets.
Cameron (A Schlumberger Business)
Cameron delivers high-quality valves and manifolds primarily for upstream oil and gas exploration, emphasizing advanced automation, customized engineering solutions, and strategic mergers to expand its global footprint.
KITZ Corporation
KITZ manufactures a wide range of valves and manifolds, known for superior quality, precision engineering, and innovative product lines suitable for domestic and international industrial applications, with a focus on sustainability and technological upgrading.
IMI plc
IMI plc offers high-performance valve solutions and manifolds with strengths in automation, energy efficiency, and bespoke design, targeting sectors such as pharmaceuticals, water utilities, and power generation.
Pentair plc
Pentair develops valves and manifolds primarily for water treatment and industrial applications, emphasizing advanced material science, digital monitoring solutions, and strategic acquisitions to enhance its market presence.
Crane Co.
Crane Co. supplies innovative, durable valves and manifolds tailored for industrial processing, with strategic focus on expanding its product portfolio through technological development and acquisitions.
Lydall, Inc.
Lydall specializes in high-performance filtration and thermal management solutions, including specialized manifolds for industrial and environmental applications, prioritizing sustainability and technological innovation.
Rotork plc
Rotork leads in actuation and valve automation, offering intelligent manifolds and control systems designed for automation, safety, and efficiency in oil & gas, water, and power sectors.
Velan Inc.
Velan Inc. manufactures valves and manifolds with a focus on high-integrity, pressure-containing products for critical applications, dedicated to technological advancement and environmental sustainability.
Strategic Business Developments
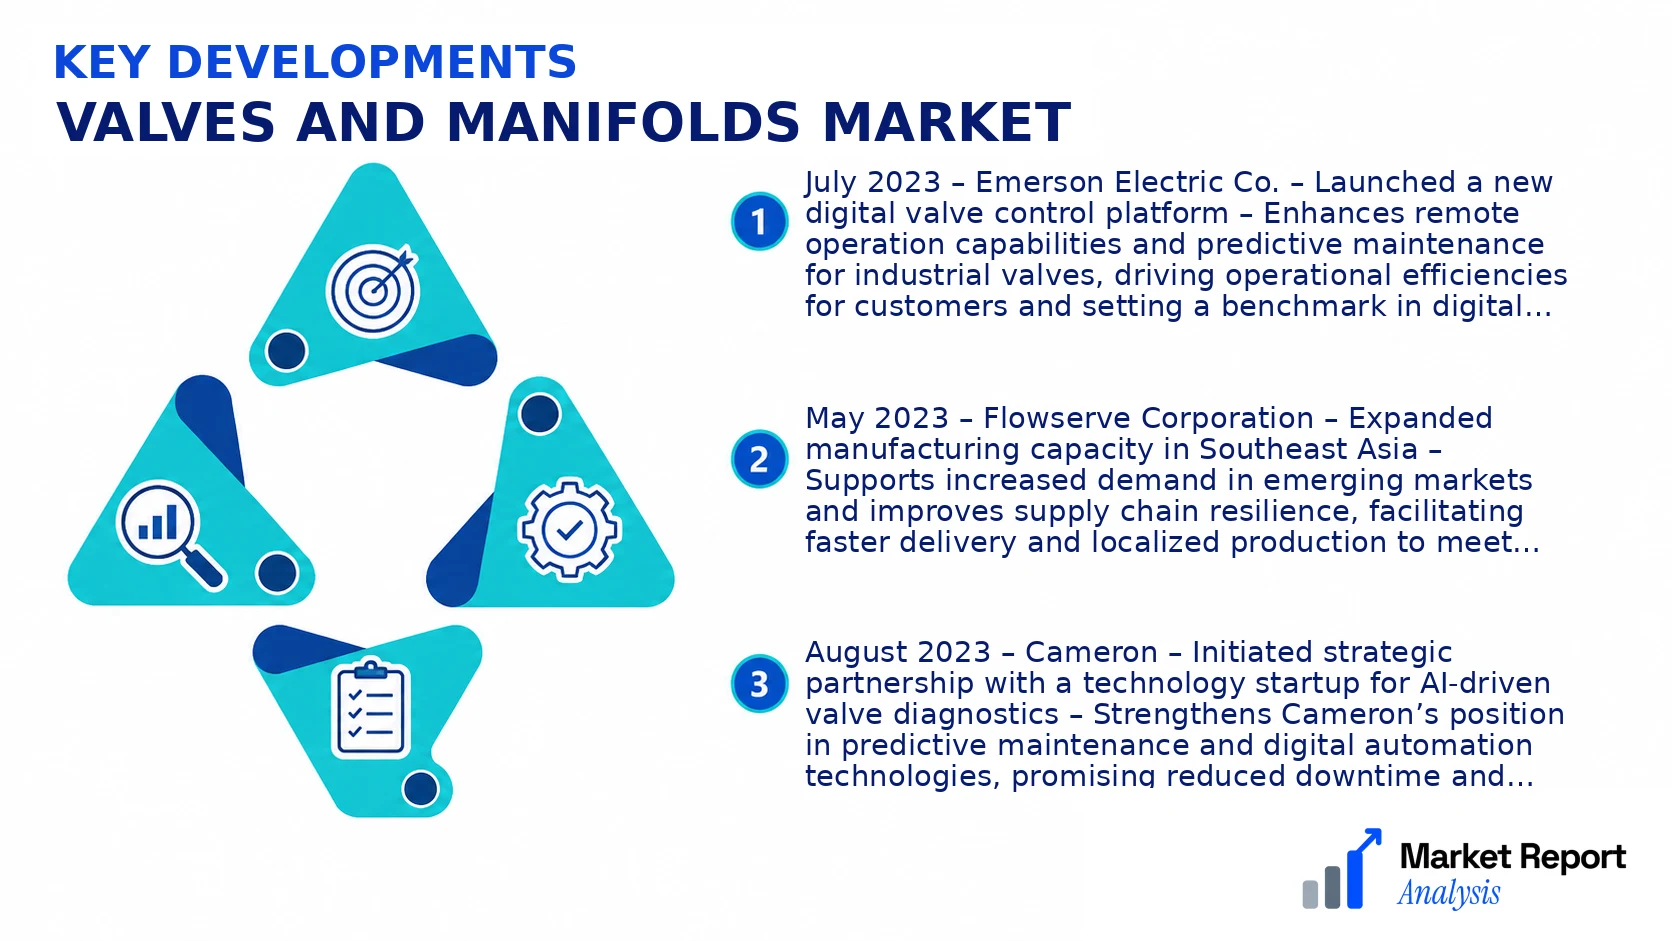
- July 2023 – Emerson Electric Co. – Launched a new digital valve control platform – Enhances remote operation capabilities and predictive maintenance for industrial valves, driving operational efficiencies for customers and setting a benchmark in digital automation.
- May 2023 – Flowserve Corporation – Expanded manufacturing capacity in Southeast Asia – Supports increased demand in emerging markets and improves supply chain resilience, facilitating faster delivery and localized production to meet regional needs.
- August 2023 – Cameron – Initiated strategic partnership with a technology startup for AI-driven valve diagnostics – Strengthens Cameron’s position in predictive maintenance and digital automation technologies, promising reduced downtime and operational costs.
- June 2023 – KITZ Corporation – Invested in new manufacturing facilities in Europe – Aims to enhance production capacity for high-precision valves, enabling faster response times to European customer demands and strengthening regional supply chains.
- April 2023 – IMI plc – Acquired a niche valve technology firm – Expands IMI’s product portfolio into specialized markets such as biotech and pharmaceutical sectors, affirming its strategic focus on innovation and custom solutions.
Frequently Asked Questions
What is the Valves and Manifolds Market?
The Valves and Manifolds Market encompasses the global industry involved in manufacturing, distributing, and using valves and manifolds crucial for controlling fluid flow across various sectors, including oil and gas, chemicals, and power generation.
What is the current market size of Valves and Manifolds Market?
As of 2026, the market size of the Valves and Manifolds Market is valued at approximately USD 15 Billion, reflecting its significance in industrial applications and ongoing demand for advanced fluid control solutions worldwide.
What factors are driving the Valves and Manifolds Market?
Market growth is propelled by increasing infrastructure development, technological advancements, and rigorous safety and environmental standards. Growing investments in the oil and gas, chemical processing, and water treatment sectors significantly contribute to market expansion.
Which region dominates the Valves and Manifolds Market?
North America leads the market, owing to its extensive industrial activities, advanced technological adoption, and stringent regulations. This dominance is expected to persist, although Asia-Pacific shows the fastest growth trajectory due to rapid industrialization.
Which segment is expected to grow the fastest?
The electronic and automated valves segment is projected to experience the most rapid growth, driven by the increasing deployment of smart technologies in industrial automation and the demand for precise fluid control systems globally.
Who are the leading companies operating in the Valves and Manifolds Market?
Key players include Emerson Electric Co., Flowserve Corporation, ATC Driveline Ltd., and KITZ Corporation. These companies sustain competitive advantage through innovation, strategic acquisitions, and expanding manufacturing capacities to meet global demand.
Analyst Perspective
The Valves and Manifolds Market is poised for sustained growth through 2034, driven by technological advancements and increasing adoption across diverse industrial sectors. As automation and digitalization penetrate process industries, smarter, more efficient valve designs and integrated manifold systems are expected to dominate the landscape, creating significant commercial opportunities for innovative manufacturers. Investment will likely focus on developing advanced materials, such as composites and composites, that enhance durability and performance under extreme conditions. Competitive intensity remains high, with established players expanding their technological edge through strategic collaborations and acquisitions. Regionally, Asia-Pacific and North America will lead growth, supported by expanding industrial bases and infrastructure investments. Long-term, the market’s evolution will favor companies prioritizing R&D, sustainable solutions, and capacity expansion in high-growth regions. Technologies like IoT-enabled valves and modular manifold systems will be critical to maintaining competitive advantage, ensuring a resilient, dynamic market environment aligned with Industry 4.0 trends.
