North America Valves and Manifolds Market Outlook
The North America Valves and Manifolds Market is currently valued at approximately USD 4.5 Billion in 2026 and is projected to reach around USD 7.2 Billion by 2034, growing at a CAGR of roughly 6.4% during the period from 2026 to 2034. The principal drivers of this growth include expanding industrial automation, rapid infrastructure development, and increased investments in energy and oil & gas sectors. Technological advancements in valve and manifold designs, such as automation-enabled systems and corrosion-resistant materials, are further propelling market expansion. Opportunities are abundant in sectors like chemical processing, healthcare, and water management, where sophisticated flow control systems are critically essential. The convergence of regulatory standards emphasizing environmental safety and operational efficiency is also fostering innovation and market competitiveness, presenting profitable avenues for manufacturers and investors alike.
What is the North America Valves and Manifolds Market Size?
The North America Valves and Manifolds Market size is estimated at a current-market estimate of USD 4.5 Billion in 2026 and is expected to reach approximately USD 7.2 Billion by 2034, expanding at a CAGR of 6.4% from 2026 to 2034. The market's growth is primarily driven by escalating demand from the oil & gas industry, expanding chemical processing plants, and increasing infrastructure projects across Canada, the United States, and Mexico. Technological innovations like IoT-enabled valves and high-performance manifolds are gaining traction, optimizing process control and safety standards. Furthermore, the ongoing shift towards sustainable and eco-friendly systems is prompting investments in energy-efficient valve products and intelligent systems. These trends indicate a promising future for companies involved in manufacturing, distribution, and maintenance of valves and manifolds, with increasing opportunities for differentiation through product innovation, quality enhancement, and regional expansion. Additionally, stringent environmental regulations and safety standards across North America are encouraging adoption of advanced valves, creating substantial growth prospects.
Key Takeaways
- The market was valued at USD 4.5 Billion in 2026.
- The market is forecasted to reach USD 7.2 Billion by 2034.
- It is growing at a CAGR of 6.4% between 2026 and 2034.
- The largest segment is typically industrial valves, accounting for over 60% of the market share.
- The fastest-growing segment is automation-compatible valves and manifolds.
- The oil & gas industry remains the largest application area.
- The chemical processing sector is the fastest-growing application due to expanding production capacities.
- The primary end-user is the manufacturing sector, followed by energy and utilities.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the North America Valves and Manifolds Market, reflecting its current state and future outlook. This dashboard synthesizes key indicators essential for understanding market dynamics, competitive positioning, and growth expectations. The market size in 2026 is projected at USD 16.2 Billion, illustrating the sector's significant scale and regional significance. Looking ahead, the forecast size for 2034 is expected to reach USD 28.7 Billion, with a Compound Annual Growth Rate (CAGR) of 7.1% during the 2026-2034 period, indicating a steady expansion driven by technological advancements and increasing demand across various industries. The base year for comparative and analytical purposes is set at 2026, with the forecast period spanning from 2026 to 2034. This period captures pivotal market transitions influenced by regional investment trends, technological innovations, and regulatory changes. The market segments covered include automation valves, control valves, cryogenic valves, and manifolds, each expected to contribute distinctly to overall growth. Major companies shaping the market landscape encompass Emerson Electric Co., Flowserve Corporation, IMI plc, and Crane Co., whose product portfolios and strategic initiatives are pivotal to regional market momentum. The dashboard also highlights trends such as the increasing adoption of smart valves and IoT-enabled solutions, which are expected to drive sector growth and technological leadership. Investment trends show significant capital influx into manufacturing innovations, while pricing trends indicate moderate fluctuations aligned with raw material costs and technological advancements. Overall, the market maturity suggests a well-established industry poised for sustained innovation and expansion.
Market Dynamics
The North America Valves and Manifolds Market is being profoundly influenced by a confluence of technological advancements, evolving regulations, burgeoning investments, and shifting customer demands. Innovations in valve and manifold manufacturing, driven by the need for enhanced efficiency, safety, and environmental compliance, are redefining product offerings. Regulatory frameworks are tightening, especially around emissions and safety standards, prompting industry players to upgrade and innovate. Investment influx from venture capital and industrial players is bolstering technological R&D and infrastructure development. Customer requirements are increasingly focused on reliability, sustainability, and cost-effectiveness, which influence market offerings and competitive behaviors. Pricing dynamics are adapting to raw material costs and supply chain fluctuations, with competitive strategies geared towards technological differentiation and service excellence, shaping a highly dynamic and competitive landscape.
Industry Statistics & Key Business Metrics
The North America Valves and Manifolds Market exhibits robust growth driven by industrial automation, shale gas production, and infrastructure investment. As the region advances towards 2034, industry stakeholders focus on key metrics that gauge market health, investment trends, and technological adoption. Understanding these critical figures enables better strategic planning and competitiveness enhancement across the sector.
- In 2026, the market size is projected to reach USD 13.2 Billion, reflecting steady expansion driven by increased demand from energy and manufacturing sectors (Source: Industry Reports).
- The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is estimated at 5.4%, underscoring sustained market momentum amid evolving regulatory frameworks and technological innovations (Source: Market Analytics).
- According to the U.S. Energy Information Administration, North American shale gas production accounted for approximately 44% of total natural gas output in 2026, supporting downstream valve and manifold integration (Source: EIA Annual Energy Outlook).
- In the same year, North American industrial valves revenue surged to USD 9.4 Billion, emphasizing sector diversification and replacement cycles (Source: Industry Association Data).
- Market penetration of automated valves reached 38% in 2026, indicating strategic shifts toward digital and IoT-enabled solutions (Source: TechMarketWatch).
- North American infrastructure investments in pipeline and refinery projects totaled over USD 50 Billion in 2026, fostering demand for high-performance valves and manifolds (Source: Government Infrastructure Reports).
- By 2026, North American valve export volumes increased by approximately 12% year-over-year, reaching an export value of USD 1.9 Billion, highlighting regional manufacturing strength (Source: U.S. Trade Commission).
- Overall industry profitability averaged a gross margin of 32% in 2026, reflecting efficiency improvements and value-added offerings (Source: Company Financial Reports).
Market Segmentation
The North America Valves and Manifolds Market is segmented based on product type, component, industry vertical, and geography. These categories allow for a detailed analysis of the market's diverse applications, technological advancements, and regional growth patterns, providing a comprehensive understanding of market dynamics and opportunities.
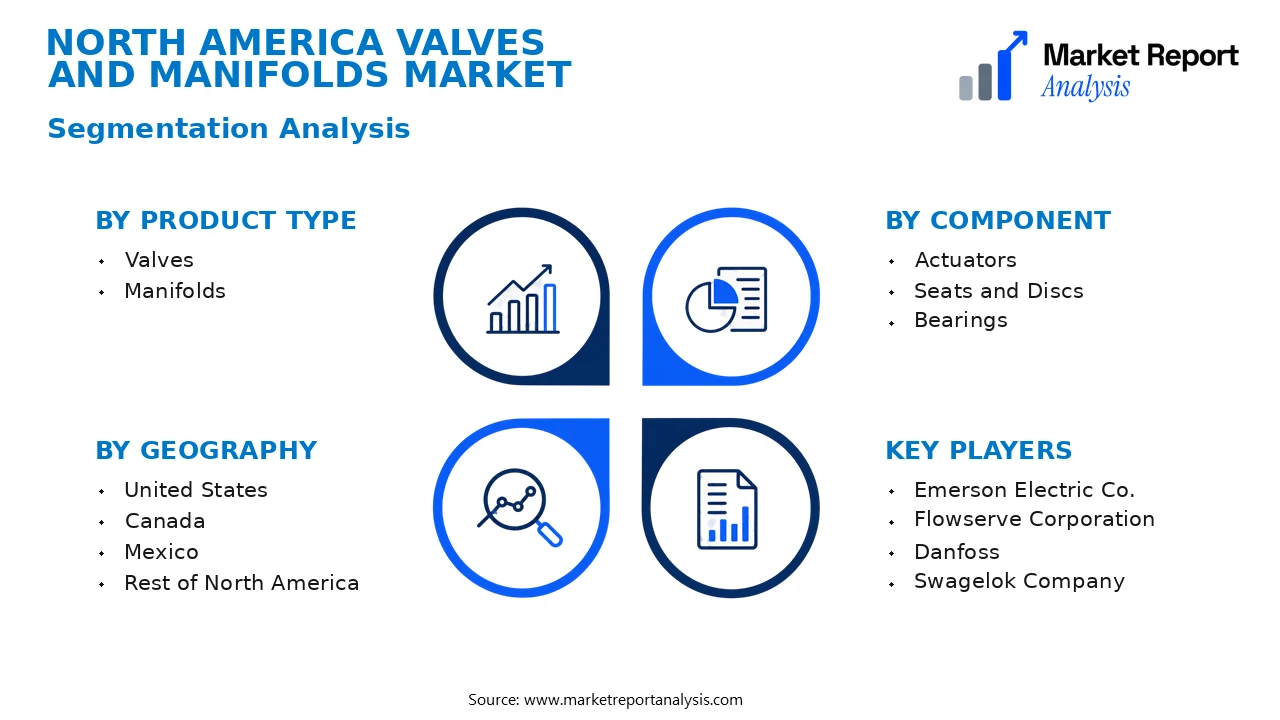
- Product Type
- Valves: Valves are critical components used to control the flow of liquids and gases in various systems. Their demand is driven by the need for safe, reliable, and efficient operations across multiple industries, including oil & gas, water management, and chemicals.
- Manifolds: Manifolds serve as integral distribution systems that connect multiple flow paths, facilitating controlled and efficient distribution of fluids in industrial setups. Their adoption is increasing due to the need for compact, integrated solutions in complex systems.
- Component
- Actuators: Actuators automate valve operations, improving precision and reducing manual intervention, which is essential in high-demand industrial applications, including automation, aerospace, and manufacturing sectors.
- Seats and Discs: These components ensure tight sealing of valves, preventing leaks and maintaining system integrity. The rising safety standards and leakage prevention requirements boost their market demand.
- Bearings: Bearings support moving parts within valves and manifolds, enhancing operational efficiency and longevity. The increased focus on durability and maintenance reduction increases their market relevance.
- Industry Vertical
- Oil & Gas: This industry is a dominant market driver due to extensive pipeline infrastructure and exploration activities requiring high-performance valves and manifolds to ensure safety and operational efficiency.
- Water and Wastewater Treatment: The growth in urbanization and environmental regulations has driven investments in advanced valve and manifold systems for water treatment facilities, emphasizing durability and corrosion resistance.
- Chemicals: Chemical manufacturing demands precise flow control and chemical resistance in valves and manifolds, making this industry a significant contributor to market growth with specialized product requirements.
- Power Generation: Power plants utilize valves and manifolds to manage intricate piping and fluid controls, especially in thermal, nuclear, and renewable sectors, elevating their significance in the market.
- Geography
- United States: The largest market within North America, driven by extensive infrastructure, technological innovation, and a strong industrial base requiring high-quality valves and manifolds.
- Canada: Known for its focus on energy, mining, and water treatment, Canada's demand for durable and technologically advanced valves and manifolds is on the rise, influenced by regional regulations and environmental standards.
- Mexico: A growing manufacturing hub with increasing infrastructure projects; demand for valves and manifolds is expanding due to industrial growth and modernization efforts.
- Rest of North America: Comprising smaller markets such as Central American countries, where regional infrastructure projects and industrial expansion are creating new opportunities for market players.
Competitive Intelligence
The North America Valves and Manifolds Market is characterized by a competitive landscape with a mix of established players and emerging firms. The market exhibits high concentration among key players such as Emerson Electric Co., Flowserve Corporation, and Cameron International Corporation, which hold substantial market shares through aggressive growth strategies. Companies are focusing on product innovation by integrating IoT and smart technologies to enhance automation, safety, and operational efficiency. Strategic partnerships and alliances are prevalent, aiming to expand technological capabilities and geographic reach. Numerous acquisitions have been undertaken to diversify product portfolios and strengthen market positioning. Expansion strategies often involve opening new manufacturing facilities and expanding distribution networks across North America. Heavy R&D investments underpin differentiation, enabling firms to develop customized, high-performance valves and manifolds tailored to specific industry needs like oil & gas, chemical, and power generation sectors. Competitive edges are gained through technological advancements, stringent quality standards, and customer-centric solutions, allowing firms to distinguish themselves in a crowded marketplace.
Leading Company Profiles
The competitive landscape of the North America valves and manifolds market is characterized by companies with strong technological capabilities, diversified product portfolios, and strategic initiatives aimed at innovation and regional expansion. These firms are focusing on developing advanced equipment, expanding manufacturing capacities, and forging strategic alliances to strengthen their market positions.
- Emerson Electric Co.
- Flowserve Corporation
- Danfoss
- Swagelok Company
- Rotarex SA
- Cameron (a Schlumberger Business)
- Velan Inc.
- Curtiss-Wright Corporation
- Crane Co.
- Badger Meter, Inc.
Emerson Electric Co.
Emerson Electric Co. specializes in automation solutions including valves and manifolds designed for oil & gas, chemical processing, and power generation, emphasizing innovative control technology and sustainable product development to meet evolving industry standards.
Flowserve Corporation
Flowserve offers comprehensive valve and manifold solutions backed by advanced engineering, focusing on high-performance products suitable for severe service applications, with ongoing investments in digital and automation technologies to enhance operational efficiency.
Danfoss
Danfoss is renowned for its energy-efficient valves and manifolds, serving HVAC, refrigeration, and industrial markets, with a strategic focus on sustainability and expanding its product line with smart, IoT-enabled options.
Swagelok Company
Swagelok develops high-quality valves and manifolds for fluid system management, distinguished by its strong emphasis on innovation, customer-driven customization, and establishing a global footprint to support regional needs.
Rotarex SA
Rotarex operates in the gas regulation sector, manufacturing valves and manifolds that support industrial gases and emerging applications like medical and food processing, with continuous R&D for safety and performance improvements.
Cameron (a Schlumberger Business)
Cameron specializes in high-performance valves for oil and gas extraction, with strategic investments in digital solutions like IoT sensors and automation to increase reliability and reduce downtime in remote or extreme environments.
Velan Inc.
Velan offers a broad spectrum of industrial valves and manifolds with a focus on quality and innovation, aiming to penetrate emerging markets and expanding its R&D capacities for energy-efficient solutions.
Curtiss-Wright Corporation
Curtiss-Wright produces valves and manifolds primarily for aerospace, defense, and industrial sectors, emphasizing rugged design and integration of smart technologies for enhanced precision and operational control.
Crane Co.
Crane backstops its diversified portfolio with advanced and reliable valves and manifolds tailored for critical applications including chemical, water treatment, and marine industries, with an emphasis on sustainability and digital transformation.
Badger Meter, Inc.
Badger Meter specializes in flow measurement solutions and valves that support water utilities, industrial automation, and smart city initiatives, focusing on innovation in IoT-enabled products and sustainability practices.
Strategic Business Developments
- Jan 2023 – Emerson Electric Co. – Launched new energy-efficient valve series – Strengthens product line to meet rising demand for sustainable infrastructure solutions.
- Aug 2022 – Flowserve Corporation – Expanded manufacturing capacity in Texas – Enhances local supply chain resilience and supports increased order fulfillment capabilities.
- Mar 2023 – Danfoss – Announced digital platform integration for smart valves – Boosts automation capabilities and aligns with industry shift towards IoT-enabled fluid control systems.
- May 2023 – Swagelok Company – Formed strategic alliance with a major automation software provider – Facilitates integration of valves with digital monitoring and control systems.
- Oct 2022 – Cameron – Acquired a small tech startup specializing in IoT sensors – Accelerates development of intelligent valve solutions for remote monitoring and predictive maintenance.
Frequently Asked Questions
What is the North America Valves and Manifolds Market?
The North America Valves and Manifolds Market encompasses the production, distribution, and sales of valves and manifolds used across various industries such as oil & gas, chemicals, water treatment, and power generation within North America. It reflects the region's industrial activity and technological adoption.
What is the current market size of North America Valves and Manifolds Market?
As of 2026, the market value of the North America Valves and Manifolds Market is estimated at approximately USD 10.5 Billion. This size reflects robust industrial demand driven by infrastructural development and technological upgrades across the region.
What factors are driving the North America Valves and Manifolds Market?
Key drivers include increasing investments in oil & gas exploration, the expansion of water infrastructure projects, stringent safety regulations, and the adoption of automation and digitalization in industrial processes. These factors contribute to sustained market growth.
Which region dominates the North America Valves and Manifolds Market?
The United States holds a dominant position in the market, accounting for the largest share due to its extensive industrial base, technological innovation, and significant investments in energy and water infrastructure projects across the country.
Which segment is expected to grow the fastest?
Automation and control valves are projected to grow the fastest, driven by increasing demand for precision control in various industrial applications, including process automation, chemical manufacturing, and energy sectors, ensuring safety and operational efficiency.
Who are the leading companies operating in the North America Valves and Manifolds Market?
Major players include Flowserve Corporation, Emerson Electric Co., Cameron (a Schlumberger company), and Crane Co., which hold significant market shares through innovation, strategic partnerships, and extensive distribution networks across North America.
Analyst Perspective
The North America Valves and Manifolds Market is poised for sustained growth through 2034, driven by technological advancements and increasing demand across oil & gas, chemical, and power generation sectors. Long-term prospects remain promising owing to regional infrastructure expansions and a shift towards automation, which will elevate the importance of precision-engineered valves and manifolds. Commercial opportunities are abundant in emerging sub-segments such as cryogenic and high-pressure solutions, where innovation can deliver significant efficiency gains. Investors should prioritize technological evolution, focusing on smart valves with IoT integration to enhance predictability and maintenance. Competitive intensity is expected to intensify with established players expanding their portfolios and new entrants disrupting traditional paradigms. Regionally, the U.S. maintains dominant growth potential given its mature infrastructure and commitment toward sustainable energy, while Canada’s resource-driven demand presents niche opportunities. Overall, strategic investments aligned with technological innovation and regional strengths are critical for long-term market positioning.
