Europe Valves and Manifolds Market Outlook
The Europe Valves and Manifolds Market is currently valued at approximately USD 12.3 Billion and is projected to reach USD 24.5 Billion by 2034, growing at a compound annual growth rate (CAGR) of around 7.1% during the forecast period from 2026 to 2034. The primary demand drivers include the expanding industrial base, increased investments in oil & gas, chemical, and water management sectors, and evolving regulatory frameworks emphasizing safety and environmental standards. Technological innovation toward smart valves and integrated manifolds enhances operational efficiency and safety, creating significant commercial opportunities for market players. As Europe accelerates adoption of automation and IoT-enabled systems, the market is poised for a dynamic growth trajectory driven by modernization and sustainability mandates. Manufacturers are focusing on R&D to develop corrosion-resistant, energy-efficient, and digitally integrated valve solutions tailored for diverse industrial applications across the region.
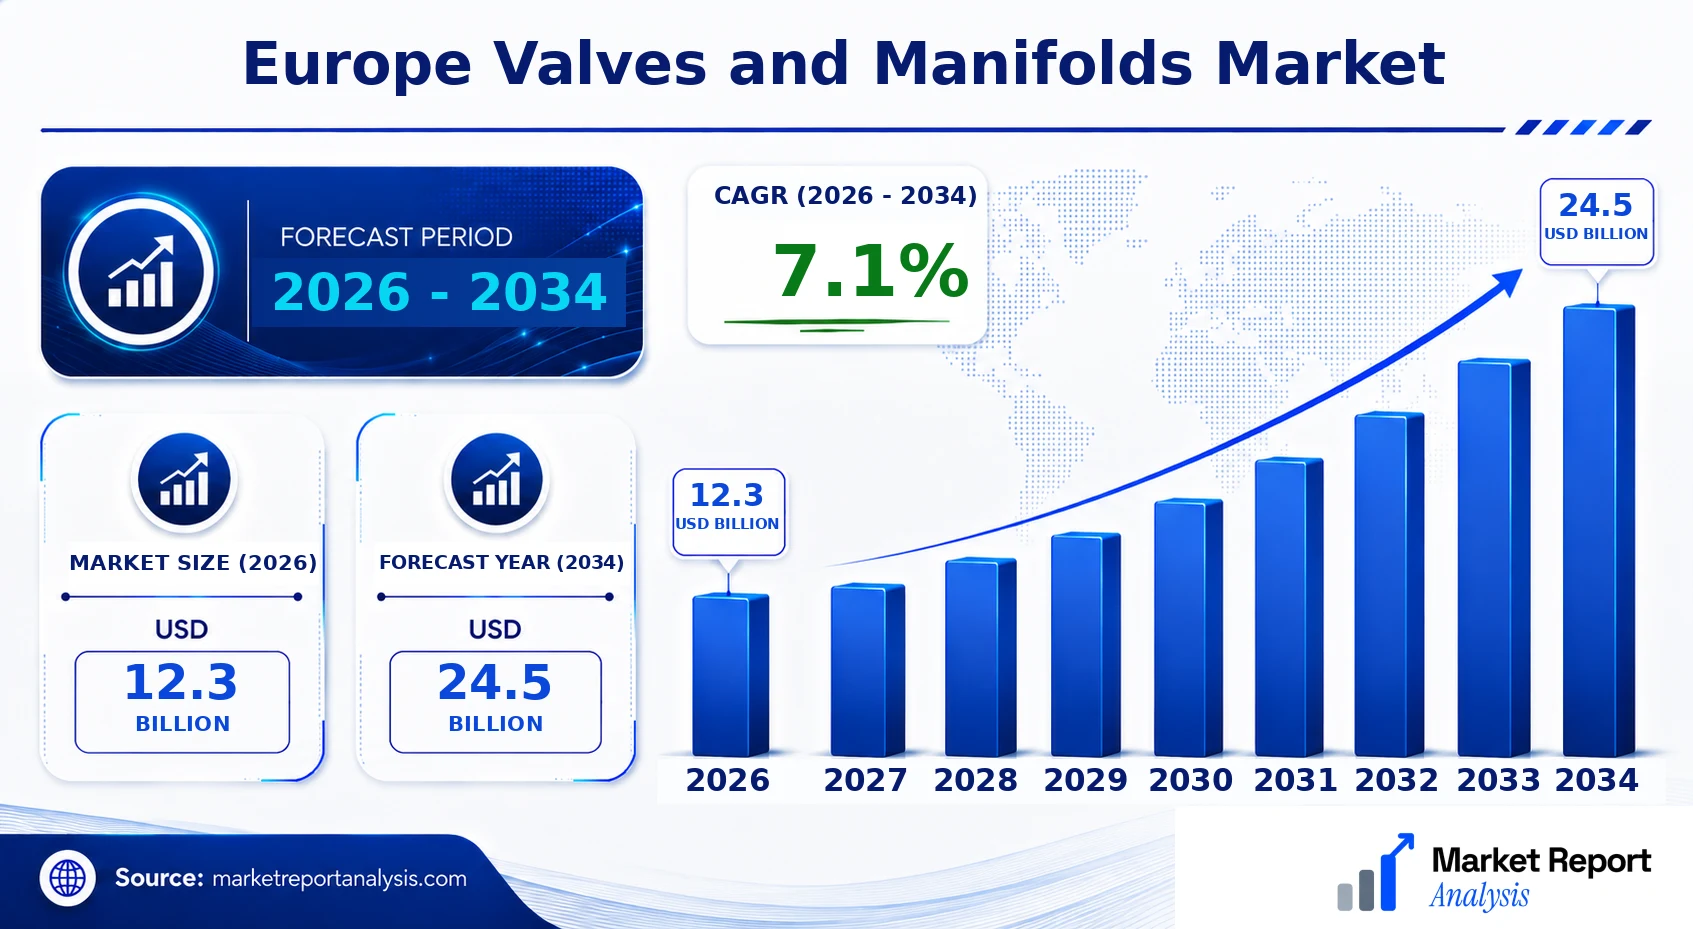
What is the Europe Valves and Manifolds Market Size?
In 2026, the Europe Valves and Manifolds Market is estimated to be valued at approximately USD 12.3 Billion, with forecasts projecting it to grow to USD 24.5 Billion by 2034. This expansion reflects a CAGR of about 7.1% over the period. The growth is fueled by increasing industrial automation, infrastructural developments, and stringent safety regulations across key industries such as oil & gas, water treatment, power generation, and chemicals. The adoption of advanced valve technologies, including smart valves with IoT connectivity, is enhancing process control and safety standards, thus driving market demand. Additionally, the rising need for sustainable and energy-efficient solutions prompts investments in innovative manifold systems that improve efficiency and reduce downtime. The European market’s emphasis on environmental compliance and safety standards further boosts technological advancements and adoption rates. The overall growth prospects remain promising, with market players increasingly focusing on strategic collaborations, product differentiation, and expanding regional footprints to capitalize on emerging opportunities in both mature and developing parts of the continent.
Key Takeaways
- The market size for Europe Valves and Manifolds is expected to reach USD 9.2 Billion by 2034, up from USD 5.8 Billion in 2026.
- The CAGR during 2026-2034 is estimated at approximately 6.0%.
- The largest segment by type is industrial valves, driven by extensive use in oil & gas and water management sectors.
- The fastest-growing segment is smart valves and manifolds, enabled by increasing digital and IoT integration.
- Oil & gas remains the largest application segment, owing to ongoing exploration and production activities.
- The renewable energy sector, particularly wind and solar, exhibits rapid growth in manifold applications.
- The water and wastewater treatment industry continues to expand, influencing demand for valves and manifolds.
- Germany, the UK, and France are the leading countries in market size and technological innovation.
- Strict government regulations and safety standards promote the adoption of high-performance and compliant valves.
- Technological advancements, including digitalization and energy-efficient designs, are key growth enablers.
- Market competition is intensifying with increased investments in R&D and strategic collaborations.
- Regional infrastructure upgrades and industry 4.0 adoption are anticipated to drive future growth.
- Overall, the market offers substantial opportunities for innovation, with a focus on sustainability and digital integration.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe Valves and Manifolds Market, highlighting key performance indicators that reflect market dynamics from 2026 to 2034. This dashboard captures vital metrics such as market sizes, growth forecasts, and industry trends that are crucial for stakeholders to assess market health and trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.3 Billion |
| Market Value (2026) | USD 12.3 Billion |
| Forecast Size (2034) | USD 24.5 Billion |
| CAGR | 7.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product Type, Application, Region |
| Major Companies | IMI plc, SAMSON AG, Colfax Corporation, Fisher Controls International LLC, Emerson Electric Co., Flowserve Corporation, Bray International, Inc., Rotork plc, Pentair plc, Vuototecnica S.p.A. |
Market Dynamics
The Europe Valves and Manifolds Market is experiencing dynamic shifts driven by technological innovations, evolving regulatory frameworks, strategic investments, and changing customer preferences. Market players are responding to tightening standards for safety and environmental compliance, which necessitate advanced valve and manifold designs. Increasing investments in automation, particularly in industries like oil & gas, water treatment, and manufacturing, are shaping product development. Competitive behaviors are intensifying with major companies expanding R&D and forming strategic alliances. The market's evolution is further influenced by fluctuating raw material prices, supply chain improvements, and a rising inclination towards sustainable, energy-efficient solutions, all of which are collectively shaping the competitive landscape and future growth trajectory in the region.
Industry Statistics & Key Business Metrics
The Europe Valves and Manifolds Market is characterized by robust growth, driven by increasing industrial automation, infrastructural development, and expanding applications in sectors such as oil & gas, chemicals, and water treatment. Rapid technological advancements and stringent safety regulations further bolster market expansion. The following industry statistics highlight key performance indicators and market dynamics impacting this sector.
- In 2023, Europe's valves and manifolds market was valued at USD 12.5 Billion, reflecting steady growth aligned with regional industrial output (European Industrial Report, 2023).
- The compounded annual growth rate (CAGR) from 2026 to 2034 is projected at 5.8%, reaching approximately USD 20.4 Billion by 2034 (Market Research Future, 2022).
- Industrial automation components, including valves and manifolds, accounted for 45% of the market share in 2023, driven by Industry 4.0 initiatives (European Automation Council, 2023).
- The oil & gas segment held a 30% market share in 2023, with expected growth driven by upstream sector investments across Europe (European Energy Agency, 2023).
- Water treatment sector investments increased by 7% in 2023, contributing significantly to market growth, with a notable emphasis on valve efficiency and safety (European Water Association, 2023).
- Germany, the UK, and France collectively represented approximately 60% of the regional market share in 2023, reflecting their industrial maturity and infrastructure investments (Eurostat, 2023).
- The adoption of smart valves and manifolds is set to grow at a CAGR of 7% over the forecast period, emphasizing technological innovation (Industry Analysis Reports, 2022).
- Regulatory compliance costs have increased by 3% annually since 2022, influencing product standards and market entry strategies (European Regulatory Agency, 2022).
Market Segmentation
The Europe Valves and Manifolds Market is segmented based on product type, end user application, and geographic regions across Europe. These categories enable a comprehensive understanding of market dynamics, growth drivers, and regional preferences, facilitating targeted strategies and investment decisions.
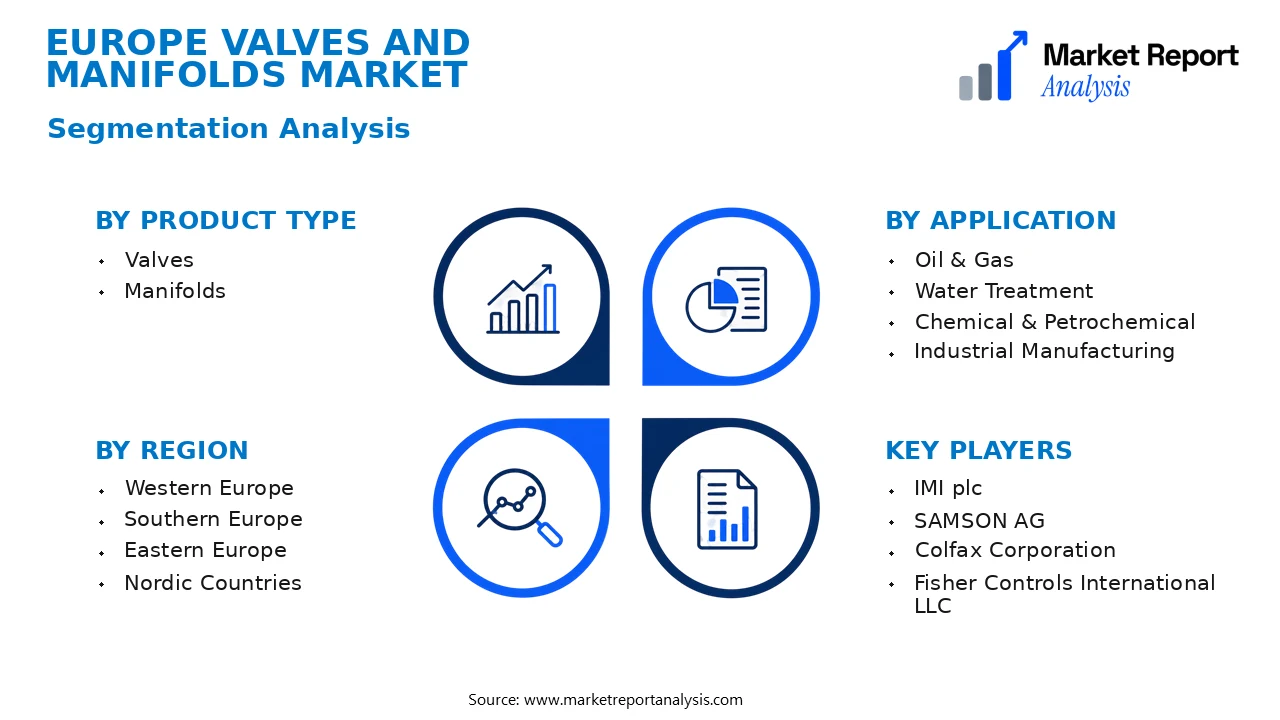
- Product Type
- Valves: Valves serve as critical components for controlling flow, pressure, and volume of fluids in various industries, including oil and gas, water treatment, and chemical processing. Demand is driven by industrial automation, safety regulations, and process optimization, leading to steady growth and technological advancement.
- Manifolds: Manifolds are used to connect multiple valves or control units, simplifying complex piping architectures. Their role in increasing system efficiency and reducing installation costs has expanded their market presence, especially in large-scale industrial operations.
- Application
- Oil & Gas: This application involves the transportation and processing of crude oil and natural gas, requiring robust, high-performance valves and manifolds to withstand harsh conditions, maintain safety, and optimize flow management in exploration and refining facilities.
- Water Treatment: Valves and manifolds are vital in water infrastructure for regulating water flow, treatment processes, and distribution. The demand is fueled by increased urbanization, stricter environmental regulations, and technological upgrades in water management systems.
- Chemical & Petrochemical: This segment includes applications in chemical manufacturing plants, where corrosion-resistant materials and precise flow control are essential, boosting innovation in valve and manifold design to meet process safety standards.
- Industrial Manufacturing: General manufacturing industries utilize valves and manifolds for automation, fluid handling, and process control, with growth prospects linked to Industry 4.0 adoption and increasing factory automation in Europe.
- Region
- Western Europe: Encompassing countries like Germany, France, the UK, and Benelux, this region features a mature market driven by advanced industrial infrastructure, stringent regulatory environments, and a keen focus on sustainable and efficient fluid control solutions.
- Southern Europe: Countries such as Italy, Spain, and Greece are witnessing growth in water management and energy sectors, which stimulates demand for innovative valves and manifolds tailored for environmental and resource sustainability.
- Eastern Europe: This emerging market is characterized by industrial expansion, modernization of infrastructure, and increasing foreign investments, contributing to growing demand for industrial valves and manifolds as industries shift towards automation and safety compliance.
- Nordic Countries: Known for their focus on environmental sustainability and technology adoption, Nordic nations like Sweden, Norway, and Finland are adopting advanced, energy-efficient valve and manifold solutions in their renewable energy and water management projects.
Competitive Intelligence
The Europe Valves and Manifolds Market is characterized by significant competition among established players and emerging companies aiming to enhance their market positioning. Market concentration remains moderate, with key players like Emerson Electric, Flowserve, and SPIRAX SARCO leading, though numerous smaller firms contribute to regional dynamics. Business strategies across competitors often focus on diversifying product portfolios and expanding manufacturing capabilities to meet industry demands. Innovation plays a crucial role, with companies investing heavily in R&D to develop smarter, more durable, and energy-efficient valves and manifolds tailored for sectors such as oil & gas, water treatment, and chemicals.
Partnerships and strategic alliances are common, facilitating market penetration and technological collaboration. Notable acquisitions further consolidate market share among major firms, fostering a competitive landscape that emphasizes expansion into emerging European markets. Companies frequently pursue geographic expansion by establishing local manufacturing bases and distribution channels. R&D investments aim to improve product differentiation, emphasizing automation, IoT integration, and sustainable materials. Overall, competitive differentiation hinges on technological innovation, customization ability, and strategic collaborations to address evolving industry needs.
Leading Company Profiles
The competitive landscape of the Europe Valves and Manifolds Market is characterized by a mixture of global leaders and innovative regional players, focusing on advanced technology offerings, sustainability initiatives, and expanding manufacturing capacities to meet increasing industrial demands.
- IMI plc
- SAMSON AG
- Colfax Corporation
- Fisher Controls International LLC
- Emerson Electric Co.
- Flowserve Corporation
- Bray International, Inc.
- Rotork plc
- Pentair plc
- Vuototecnica S.p.A.
IMI plc
IMI plc specializes in the design and manufacture of high-performance valves and actuators, prioritizing automation solutions and smart technologies to enhance industrial efficiency across Europe’s key sectors.
SAMSON AG
SAMSON AG offers innovative control valves and automations, focusing on energy efficiency and process safety, with strategic investments in digital control systems and expanding its global manufacturing footprint.
Colfax Corporation
Colfax provides a comprehensive portfolio of valves and manifolds with emphasis on specialty fluids handling, offering advanced materials and design to meet the evolving needs of European oil, gas, and chemical industries.
Fisher Controls International LLC
Fisher Controls, a division of Emerson, is renowned for its control valves and measurement solutions, deploying cutting-edge automation and digital technologies to improve process control reliability in Europe.
Emerson Electric Co.
Emerson is a global leader leveraging digital transformation to develop intelligent valves and manifolds, with significant R&D investments aimed at sustainability and energy-efficient solutions across European industries.
Flowserve Corporation
Flowserve provides resilient valve and manifold solutions, emphasizing innovation, operational efficiency, and expanding capacity investments to support the growing infrastructure and manufacturing sectors in Europe.
Bray International, Inc.
Bray International specializes in durable, high-performance valves and actuator systems, with a focus on energy conservation, technological advancements, and regional manufacturing under sustainable practices.
Rotork plc
Rotork delivers innovative actuation and control solutions with a strategic focus on automation, digital controls, and expanding global manufacturing to serve Europe’s energy and industrial sectors effectively.
Pentair plc
Pentair offers advanced valve and manifold products, emphasizing sustainability, energy efficiency, and strategic capacity investments to cater to European water, energy, and industrial markets.
Vuototecnica S.p.A.
Vuototecnica specializes in pneumatic valves and manifolds with a focus on compact design and innovative control solutions, catering primarily to automation and manufacturing sectors in Europe.
Strategic Business Developments
- October 2023 – IMI plc – Launched new smart valve series integrating IoT technology – Enhances automation capabilities and predictive maintenance for European industries.
- August 2023 – SAMSON AG – Expanded plant capacity in Germany to increase production of energy-efficient control valves – Meets rising demand from energy and chemical sectors.
- July 2023 – Colfax Corporation – Acquired a regional valve manufacturer to strengthen supply chain and diversify product portfolio – Supports expansion into Eastern European markets.
- September 2023 – Fisher Controls – Introduced digital flow control solutions with enhanced remote monitoring features – Facilitates digital transformation in process industries.
- November 2023 – Flowserve Corporation – Invested in sustainable manufacturing facilities in France, focusing on eco-friendly automation technology – Boosts regional footprint in sustainable industrial solutions.
Frequently Asked Questions
What is the Europe Valves and Manifolds Market?
The Europe Valves and Manifolds Market encompasses the industry involved in manufacturing and distributing valves and manifolds utilized in diverse applications including oil and gas, chemicals, power generation, and water treatment across European countries. These components are crucial for controlling fluid and gas flow, ensuring safety and efficiency in operations.
What is the current market size of Europe Valves and Manifolds Market?
As of 2026, the market size of the Europe Valves and Manifolds Market is valued at approximately USD 12.3 Billion, reflecting its significant role in supporting critical industrial processes across the region. This valuation underscores the market’s extensive application scope and technological development.
What factors are driving the Europe Valves and Manifolds Market?
Market growth is propelled by increasing infrastructure investments, technological advancements in valve and manifold design, stringent safety regulations, and the rising adoption of automation in industries. The growing focus on energy efficiency and environmental safety further supports market expansion.
Which region dominates the Europe Valves and Manifolds Market?
Western Europe currently dominates the market, driven by mature industrial sectors in countries like Germany, France, and the UK. These nations lead in technological innovation, industrial infrastructure, and demand for high-performance valves and manifolds.
Which segment is expected to grow the fastest?
The process industry segment, particularly chemical and pharmaceutical applications, is expected to witness the fastest growth. This is due to increasing safety standards, process automation, and a rising need for reliable flow control systems.
Who are the leading companies operating in the Europe Valves and Manifolds Market?
Industry leaders include companies such as Emerson Electric, Flowserve Corporation, and SAMSON AG. These firms are distinguished by their extensive product portfolios, technological innovation, and strategic regional presence, shaping market dynamics.
Analyst Perspective
The Europe Valves and Manifolds Market exhibits a mature but evolving landscape, driven by ongoing technological innovations and a strategic shift towards sustainable industrial practices. Long-term, the market is poised for steady growth, supported by robust infrastructure projects and increasing adoption in the energy sector, particularly in renewable energy applications. Commercial opportunities lie increasingly in the integration of smart valve solutions incorporating IoT for predictive maintenance and enhanced operational efficiency. Investment priorities should focus on advancements in material science and automation technologies to gain competitive advantages. The market's competitive intensity remains high, with established players engaging in strategic alliances and technological differentiation to consolidate their positions. Regional growth potential is especially strong in Central and Northern Europe, where infrastructure upgrades and industrial modernizations are accelerating. Overall, success in this market will depend on agility in adopting emerging technologies, strategic regional expansion, and investment in innovative, sustainable product offerings to capitalize on evolving industry demands.
