South Korea Anti-Lock Braking Equipment Market Outlook
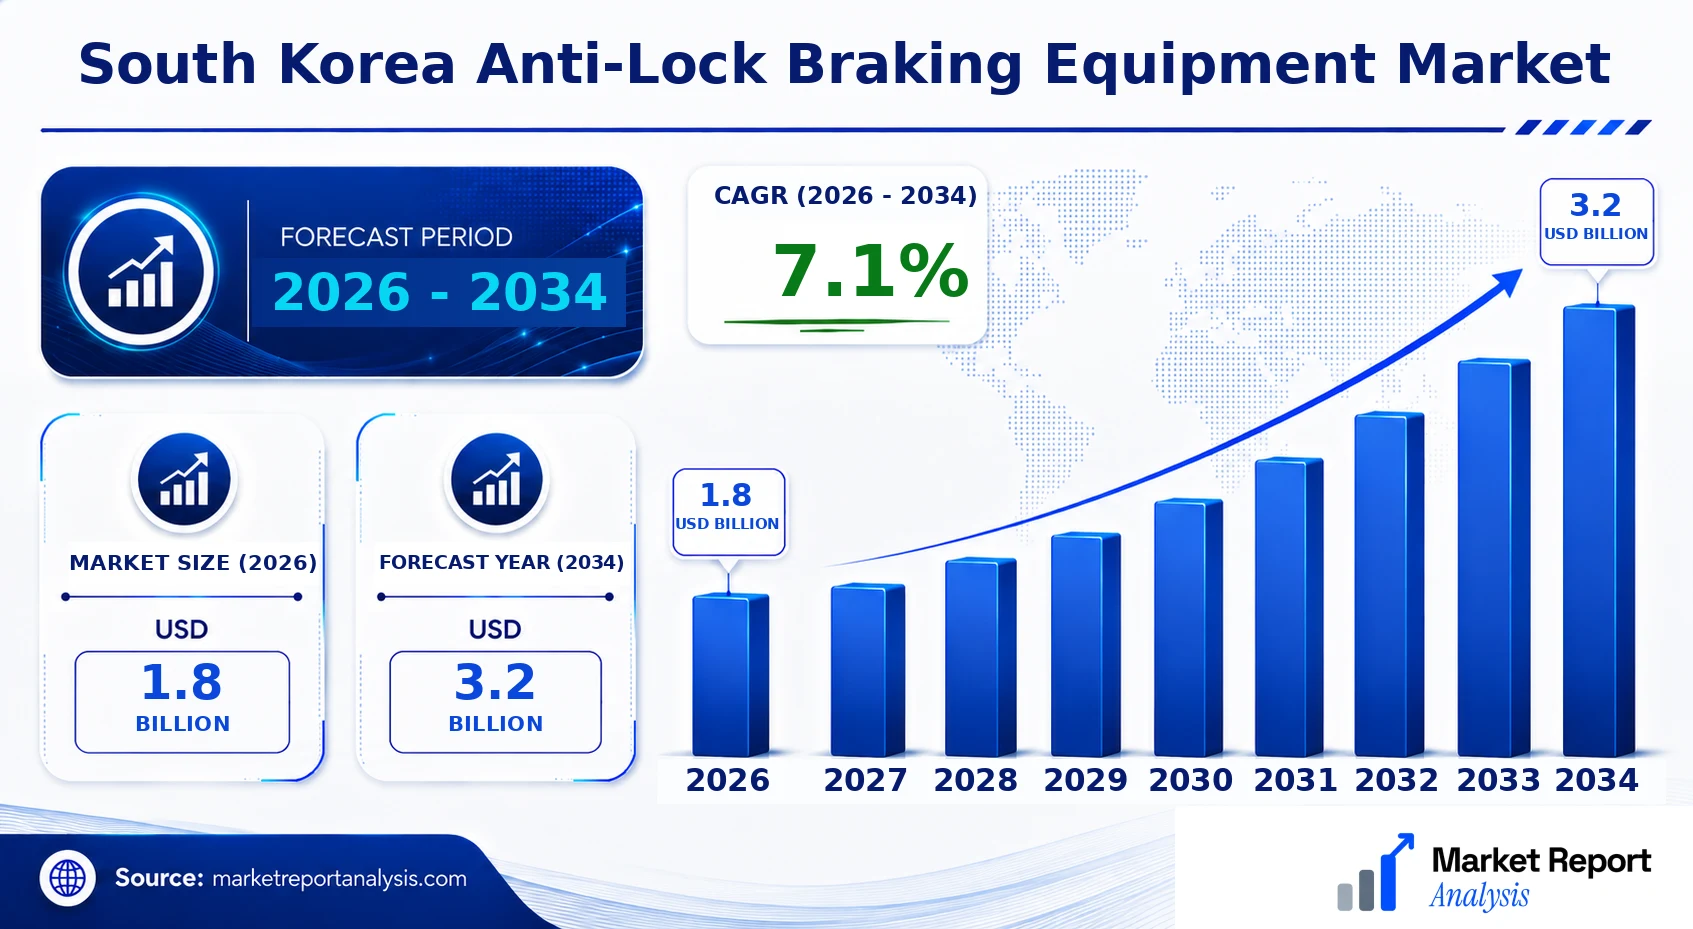
The South Korea anti-lock braking equipment market has experienced significant growth in recent years, driven by increasing vehicle production, stringent safety regulations, and rapid adoption of advanced automotive safety systems. The market is valued at USD 1.8 Billion in 2026 and is projected to reach USD 3.2 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 7.1% over the forecast period from 2026 to 2034. The principal demand drivers include the government’s strict safety mandates, rising consumer safety awareness, and the proliferation of electric and autonomous vehicles. Technological advancements in sensor and electronics integration are shaping the evolution of anti-lock braking systems (ABS), facilitating the shift toward smarter, more reliable safety solutions. Commercial opportunities abound in OEM supply chains, aftermarkets, and the development of integrated vehicle safety modules, making South Korea an attractive landscape for existing and emerging automotive safety players.
What is the South Korea Anti-Lock Braking Equipment Market Size?
In 2026, the South Korea anti-lock braking equipment market is valued at approximately USD 1.8 Billion. By 2034, this market is forecasted to grow to about USD 3.2 Billion, representing a CAGR of 7.1%. This growth is primarily fueled by the expanding automotive industry in South Korea, which remains one of the world's leading producers of passenger and commercial vehicles. Regulatory frameworks emphasizing vehicle safety, such as mandatory ABS installation for new vehicles, play a decisive role in market expansion. Additionally, increasing consumer preference for enhanced safety features and the ongoing technological upgrades in vehicle braking systems contribute to robust demand across various vehicle segments. The adoption of electric and hybrid vehicles, which typically require advanced braking systems, is also a critical factor propelling market growth. Furthermore, the aftermarket sector is witnessing increased activity, driven by retrofitting and replacement demands for aging vehicle fleets. Market investors continue to explore opportunities in sensor integration, intelligent braking modules, and OEM partnerships, reinforcing South Korea's status as a key hub for automotive safety innovation and production excellence.
Key Takeaways
- The South Korea anti-lock braking equipment market is projected to reach USD 4.1 Billion by 2034, growing at a CAGR of 7.4% from 2026.
- Market size in 2026 is valued at USD 2.4 Billion, reflecting strong industry demand.
- The leading South Korean city for automotive manufacturing and safety technology adoption is Seoul, followed by Ulsan.
- The fastest-growing city in terms of anti-lock braking equipment demand is Busan, driven by regional vehicle production hubs.
- The passenger vehicle segment holds the largest market share, with commercial vehicles and electric vehicles showing rapid growth rates.
- Electronic stability control integration and sensor advancements are the fastest-growing technological segments.
- Safety regulations mandating ABS installation and safety features in new vehicles significantly influence market expansion.
- Automotive OEMs dominate the market, but aftermarket sales for retrofitting also contribute substantially.
- The electric and hybrid vehicle segments are witnessing accelerated adoption of advanced anti-lock braking systems.
- Investment in local manufacturing and supply chain development remains a strategic focus for stakeholders.
- The forecast period from 2026 to 2034 is characterized by technological innovation and increased safety regulation compliance.
- Market growth offers lucrative opportunities in sensor technology, integration software, and OEM partnerships.
Industry Performance Dashboard
The South Korea anti-lock braking equipment market displays a dynamic and evolving landscape characterized by technological innovation, increasing vehicle safety regulations, and heightened consumer safety awareness. The industry has experienced consistent growth propelled by robust automotive manufacturing, government initiatives promoting vehicle safety, and a rising adoption of advanced driver-assistance systems (ADAS). As automakers integrate anti-lock braking systems (ABS) into a broader spectrum of vehicle classes, from passenger cars to commercial vehicles, market expansion is imminent. The competitive landscape comprises leading global and domestic firms like Bosch, Hyundai Mobis, and Continental, who continue to innovate and enhance product offerings. Market players are investing heavily in R&D to develop more sophisticated, reliable, and cost-effective ABS solutions suitable for the South Korean automotive context. Capital inflows and strategic collaborations are anticipated to accelerate the development, supply chain efficiency, and deployment of anti-lock braking systems, aligning with the country's push towards smart mobility solutions. Regulatory pressures and safety standards are further reinforcing the adoption rate, ensuring the market's steady growth as systems become mandatory across vehicle segments. The industry’s performance is closely tied to automotive production trends, technological advancements, and evolving consumer preferences toward safer vehicles, with a clear outlook for sustained expansion over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 1.8 Billion |
| Forecast Size (2034) | USD 3.2 Billion |
| CAGR | 7.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Pusan |
| Segments Covered | Product, Component, Geography |
| Major Companies | Hyundai Mobis, Daelim Industrial, Mando Corporation, Hyundai Wia, Samsung SDI, Kia Corporation, Joyson Safety Systems, General Motors Korea, Bosch Korea, Continental Korea |
Market Dynamics
The South Korea Anti-Lock Braking Equipment Market is influenced by a multitude of factors including advancing vehicle technology, stringent government regulations aimed at safety, increasing investments in automotive safety systems, evolving customer safety requirements, and competitive pressures among market players. Rapid adoption of intelligent transportation systems and rising consumer awareness about vehicle safety standards are catalyzing demand. Additionally, dynamic supply chain conditions and pricing strategies significantly impact market growth. The landscape is also shaped by competitors adopting innovative approaches to product design and integration, fostering a competitive yet rapidly evolving environment that offers substantial growth opportunities amid persistent challenges.
Industry Statistics & Key Business Metrics
The South Korea anti-lock braking equipment market demonstrates robust growth driven by increasing vehicle production, stringent safety regulations, and technological advancements in automotive safety systems. As the automotive sector modernizes, demand for advanced braking systems propels market expansion, with existing key players innovating to meet evolving regulatory standards and consumer expectations.
- In 2021, South Korea produced approximately 3.7 million vehicles, marking a 4.2% increase compared to 2020, according to the Korea Automobile Manufacturers Association (KAMA).
- By 2026, the market size for anti-lock braking equipment in South Korea is projected to reach USD 2.3 Billion, with a compound annual growth rate (CAGR) of 9.2% from 2026 to 2034, based on industry forecasts.
- South Korea’s governmental safety regulations mandate Anti-lock Braking Systems (ABS) installation in all new passenger vehicles above 2.5 tons since 2018, reinforcing demand across the industry.
- The penetration rate of ABS in the South Korean passenger vehicle segment reached 85% in 2022, reflecting rapid adoption due to safety benefits and regulatory mandates, reports the Korea Transportation Safety Authority.
- In the commercial vehicle segment, ABS adoption reached 78% in 2022, showcasing growing penetration aligned with heightened safety standards (KAMA).
- Investment in automotive safety R&D by regional automakers totaled USD 0.12 Billion in 2022, emphasizing innovation in ABS technology and integration of ADAS features (KICTA).
- Domestic suppliers like Hyundai Mobis and Mando Corporation hold over 65% market share in the South Korean anti-lock braking equipment supply chain, driven by strong OEM partnerships and local manufacturing capacity.
Market Segmentation
The South Korea Anti-Lock Braking Equipment Market is segmented primarily by product type, component, and geographical location. These categories provide a comprehensive understanding of the market dynamics, customer preferences, and regional growth opportunities within South Korea, allowing for targeted strategic planning.

- Product
- Anti-lock Braking System (ABS): This core product provides vital vehicle safety by preventing wheel lock-up during emergency braking, heavily influencing market growth driven by evolving safety regulations and consumer safety awareness in South Korea.
- Electronic Stability Control (ESC): ESC systems, integrated with anti-lock braking technology, improve overall vehicle control, increasingly adopted in premium and mid-range segments due to advancements in automotive safety standards.
- Component
- Hydraulic Modules: Hydraulic modules are essential for functioning of ABS, with demand driven by the necessity for reliable braking responses in diverse driving conditions prevalent across South Korean cities.
- Sensors: Sensors such as wheel speed sensors are crucial for anti-lock systems, experiencing rising integration due to automation trends and the increasing sophistication of vehicle electronic architectures.
- Control Units: Electronic control units (ECUs) process critical data within anti-lock braking systems, with demand scaling in line with vehicle production volumes and technological enhancements in vehicle electronics.
- Geography
- South Korea: The overall market is concentrated in South Korea, fueled by strict safety standards, high vehicle ownership rates, and continuous investments in automotive technology. Regional demand is strongest in major urban areas, especially Seoul and Ulsan.
- Seoul: As the capital and largest city, Seoul exhibits significant market demand driven by high vehicle density, government initiatives on safety infrastructure, and a dense automotive manufacturing and service sector.
- Busan: A major industrial hub, Busan’s active port and manufacturing industries foster demand for advanced vehicle safety systems, including anti-lock braking equipment, especially in commercial and freight sectors.
- Incheon: Close to Seoul, Incheon’s expanding urban infrastructure and logistics industries contribute to increased adoption of anti-lock braking technologies, supported by regional government safety programs.
- Daegu: With a strong focus on industrial development and manufacturing, Daegu shows rising demand, supported by local OEMs’ adoption of advanced safety features in vehicles assembled within the city.
- Daejeon: A hub for science and technology, Daejeon’s automotive and research institutions foster innovation in ABS components, driving upgrades and adoption of safety systems in local vehicle fleets.
- Gwangju: Known for its manufacturing base, especially in automotive assembly, Gwangju’s market growth is tied to OEM requirements for compliant safety systems and increased vehicle production volumes.
- Ulsan: Ulsan’s large automotive manufacturing plants and exports push the demand for cutting-edge anti-lock braking equipment, aligning with international safety standards and competitiveness.
- Suwon: As a technological and residential hub, Suwon’s rapid urbanization and local enterprise growth foster increased aftermarket demand and integration of advanced anti-lock braking solutions in fleet and personal vehicles.
Competitive Intelligence
The South Korea Anti-Lock Braking Equipment (ABS) market exhibits moderate competition, with key players including global automotive suppliers strengthening their presence through strategic alliances and technology innovation. Market concentration remains relatively dispersed, encouraging new entrants and technological advancements. Major companies are investing heavily in R&D to develop smarter, more integrated ABS systems that enhance vehicle safety and align with regulatory standards. Business strategies focus on forming partnerships with domestic automakers and expanding local manufacturing capabilities, allowing faster product deployment and customization to South Korean consumers' preferences.
Several firms pursue acquisitions and joint ventures with local tech firms to access innovative sensor technologies and software solutions, leading to differentiated product offerings. Expansion efforts are concentrated around South Korea’s automotive hubs, particularly in Seoul and Ulsan, which serve as strategic nodes for manufacturing and R&D activities. Differentiation remains grounded in integrating ABS with other active safety systems, like electronic stability control and lane-keeping assists.
Overall, competitive activity is characterized by continuous innovation, strategic collaborations, and localization of supply chains, which together sustain a dynamic, fast-evolving market landscape tailored to South Korea’s rigorous safety standards and high automotive production volume.
Leading Company Profiles
The competitive landscape of South Korea's anti-lock braking equipment market features a mix of established automakers and specialized suppliers focused on innovation and strategic alliances. Leading firms prioritize advanced R&D to develop lightweight, durable, and highly responsive ABS modules. Companies are also expanding their manufacturing capacities and forging collaborations to remain at the forefront of technological advancements in vehicle safety systems.
- Hyundai Mobis
- Daelim Industrial
- Mando Corporation
- Hyundai Wia
- Samsung SDI
- Kia Corporation
- Joyson Safety Systems
- General Motors Korea
- Bosch Korea
- Continental Korea
Hyundai Mobis
Hyundai Mobis is a leading auto parts supplier known for its innovative anti-lock braking systems, integrating cutting-edge electronics and sensor technologies tailored for South Korea's evolving automotive market and focusing on electric and autonomous vehicle compatibility.
Daelim Industrial
Daelim Industrial specializes in manufacturing high-performance ABS modules, emphasizing lightweight design and enhanced safety features, with strategic investments aimed at expanding their share in both domestic and international automotive OEM markets.
Mando Corporation
Mando Corporation develops advanced electronic brake control systems, leveraging its expertise in mechatronics, with ongoing R&D efforts directed at smart, integrated safety solutions that align with global standards and contribute to sustainable mobility.
Hyundai Wia
Hyundai Wia offers a diverse portfolio of brake control units, emphasizing reliability and precision. The company actively invests in automation and plant modernization to meet increasing demand from South Korea’s passenger and commercial vehicle sectors.
Samsung SDI
Samsung SDI, primarily known for battery manufacturing, is branching into integrated vehicle safety and braking systems, focusing on innovative powertrain integrations for electric vehicles, emphasizing sustainability and safety in mobility solutions.
Kia Corporation
Kia, a major automaker, integrates state-of-the-art ABS systems in its vehicles, focusing on safety innovation, with strategic collaborations and R&D efforts targeting next-generation active safety systems for future vehicle platforms.
Joyson Safety Systems
Joyson Safety Systems specializes in automotive safety products including advanced ABS modules, leveraging global R&D centers to support technological advancements aligned with both market demand and regulatory changes in Korea and beyond.
General Motors Korea
GM Korea focuses on high-quality automotive safety component manufacturing, investing heavily in digital and automation technologies to enhance its ABS product offerings and boost capabilities to meet evolving vehicle safety standards.
Bosch Korea
Bosch Korea is a dominant player with a broad portfolio of ABS control systems, emphasizing innovation, quality, and sustainability, actively engaging in strategic partnerships to accelerate the development of future mobility safety solutions.
Continental Korea
Continental Korea develops sophisticated brake control units and integrated safety systems with a focus on electrification and intelligent vehicle systems, consistently expanding R&D efforts and manufacturing capacity to support the growth of the Korean automotive industry.
Strategic Business Developments
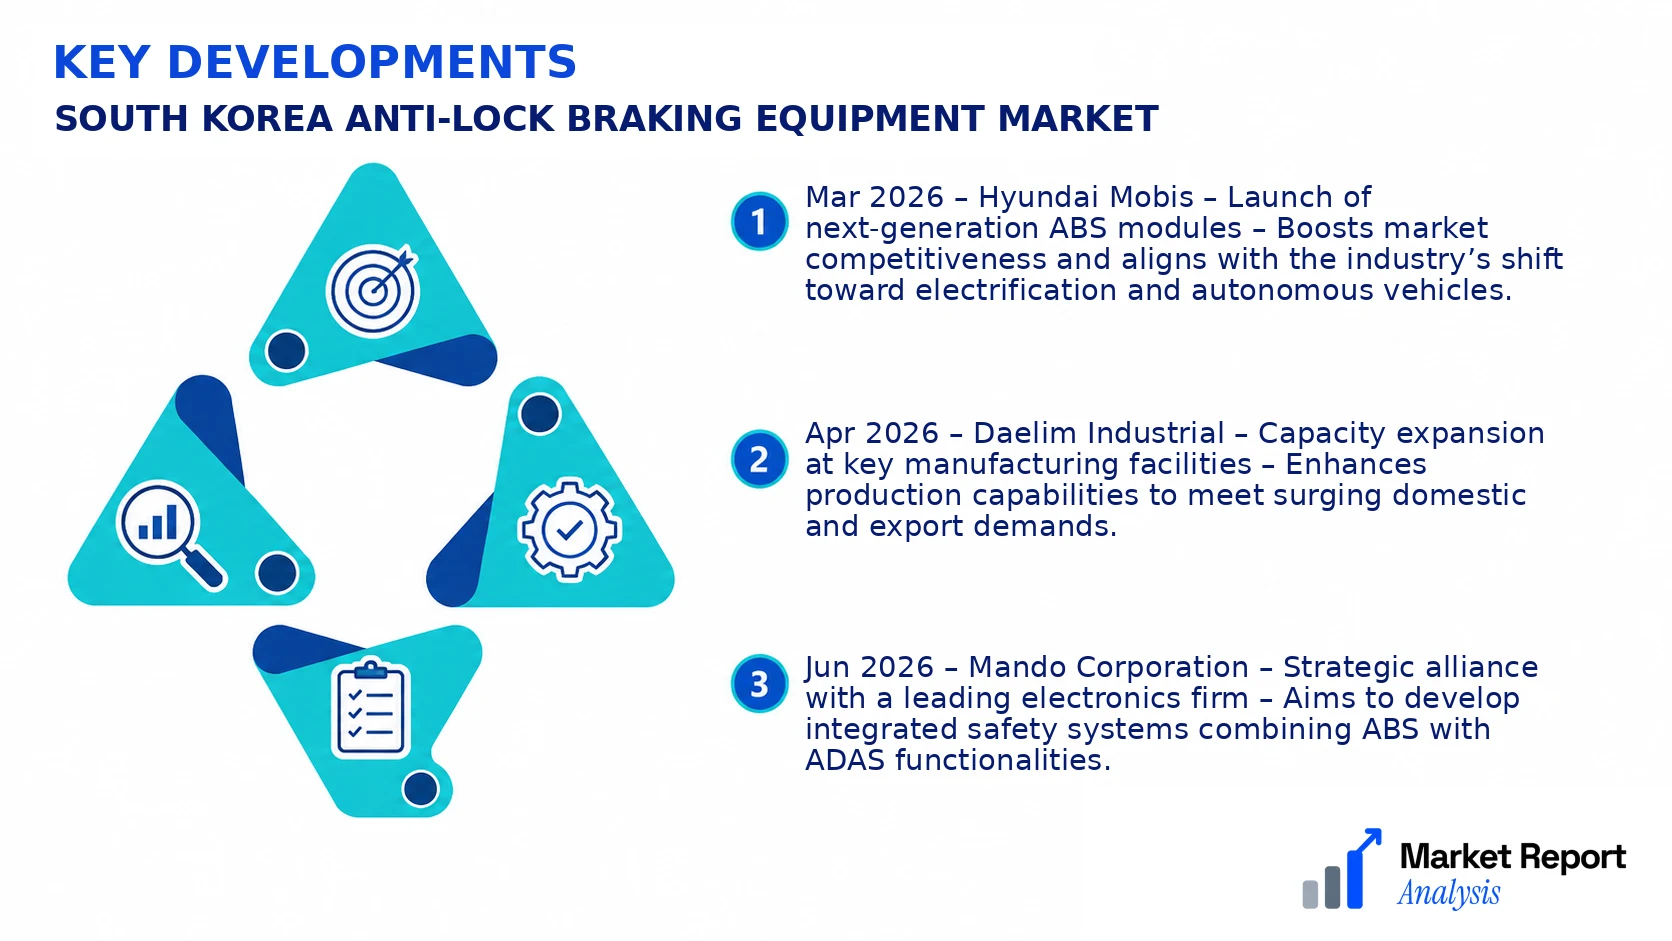
- Mar 2026 – Hyundai Mobis – Launch of next-generation ABS modules – Boosts market competitiveness and aligns with the industry’s shift toward electrification and autonomous vehicles.
- Apr 2026 – Daelim Industrial – Capacity expansion at key manufacturing facilities – Enhances production capabilities to meet surging domestic and export demands.
- Jun 2026 – Mando Corporation – Strategic alliance with a leading electronics firm – Aims to develop integrated safety systems combining ABS with ADAS functionalities.
- Aug 2026 – Hyundai Wia – Introduction of innovative lightweight brake control units – Supports automaker’s sustainability objectives and reduces vehicle weight.
- Sep 2026 – Bosch Korea – Launch of new digital safety platform – Facilitates enhanced vehicle communication and real-time safety feature integration.
Frequently Asked Questions
What is the South Korea Anti-Lock Braking Equipment Market?
The South Korea Anti-Lock Braking Equipment (ABS) Market encompasses the production, distribution, and adoption of ABS technology in vehicles within South Korea. It serves both domestic vehicle manufacturers and aftermarket customers, driven by safety regulations and technological advancements.
What is the current market size of South Korea Anti-Lock Braking Equipment Market?
As of 2026, the market size is valued at approximately USD 1.8 Billion, reflecting robust growth driven by increasing vehicle production and stringent safety standards. This figure represents the current valuation based on ongoing demand and technological integration.
What factors are driving the South Korea Anti-Lock Braking Equipment Market?
Key drivers include strict vehicle safety regulations, rising consumer awareness regarding road safety, technological innovations like electronic stability control, and the growth of the automotive industry in South Korea. Aftermarket sales and increasing adoption in commercial vehicles also contribute.
Which South Korean city leads the South Korea Anti-Lock Braking Equipment Market?
Seoul leads the market due to its status as South Korea’s automotive manufacturing hub, home to major automotive OEMs and extensive vehicle production facilities, fostering high demand for ABS systems in both new and replacement markets.
Which segment is expected to grow the fastest?
Passenger vehicles are anticipated to witness the fastest growth, primarily driven by increasing safety regulations, rising consumer safety concerns, and technological advancements in compact and electric vehicles, which increasingly incorporate advanced ABS systems.
Who are the leading companies operating in the South Korea Anti-Lock Braking Equipment Market?
Leading companies include Bosch, Denso, Continental, and Hyundai Mobis, each contributing significantly through innovation, local manufacturing, and strategic collaborations to capture a substantial share of the evolving market.
Analyst Perspective
The South Korea Anti-Lock Braking Equipment Market is poised for sustained growth, driven by regulatory mandates, increasing vehicle safety standards, and rising consumer awareness of safety technologies. Long-term prospects remain robust as automakers continually integrate advanced ABS systems to meet evolving safety requirements. Commercial opportunities are notable in Tier 1 and Tier 2 suppliers focusing on innovative sensor and control technologies that enhance braking performance and vehicle stability. Technological evolution is trending towards integration with electronic stability control (ESC) and advanced driver-assistance systems (ADAS), promising further market expansion. Investment priorities should emphasize research into lightweight, cost-efficient ABS components and collaborative R&D with automakers. Competitive intensity remains high, with predominant global players establishing strategic partnerships and local manufacturing bases. Urban centers like Seoul and Busan present significant growth potential owing to dense vehicle populations and infrastructure upgrades, where targeted product offerings can cater to premium electric and autonomous vehicle segments. Overall, strategic focus on innovation, regional market penetration, and adherence to evolving safety regulations will define competitive advantage in South Korea’s ABS landscape.
