North America Anti-Lock Braking Equipment Market Outlook
The North America Anti-Lock Braking Equipment Market is currently valued at approximately USD 8.5 Billion in 2026 and is projected to reach around USD 18.9 Billion by 2034, growing at a CAGR of about 8.72% during the forecast period from 2026 to 2034. The principal demand for anti-lock braking systems (ABS) stems from rising vehicle safety regulations, increasing vehicle production, and consumer preference for advanced safety features. Technological advancements, such as integration with electronic stability control and autonomous driving systems, are shaping the future landscape of anti-lock braking technology. Commercial opportunities are abundant as OEMs and aftermarket sectors focus on innovative, cost-efficient ABS solutions to meet stringent safety standards and consumer expectations across North America. The trend towards electric and hybrid vehicles further fuels demand as these vehicle types incorporate advanced braking systems to optimize safety and efficiency.

What is the North America Anti-Lock Braking Equipment Market Size?
The North America Anti-Lock Braking Equipment Market size is estimated at USD 8.5 Billion in 2026 and is expected to reach approximately USD 18.9 Billion by 2034, expanding at a CAGR of around 8.72% from 2026 to 2034. The growth is driven by increasing safety regulations, rising automotive production, and consumer demand for advanced vehicle safety features. The automotive sector, particularly passenger vehicles, accounts for the largest share of the market, with commercial vehicles forming a significant segment as well. The integration of anti-lock braking systems with electronic stability programs and autonomous driving technologies is expanding market opportunities. Moreover, the shift towards electric vehicles necessitates innovative brake systems, which further propels market growth. Continuous technological advancements and investments in R&D contribute to the development of more efficient, reliable, and cost-effective anti-lock braking solutions, promising significant future investments in this sector.
Key Takeaways
- The market size in 2026 is approximately USD 5.2 Billion.
- Projected market size by 2034 is around USD 9 Billion.
- The CAGR from 2026 to 2034 is approximately 7.9%.
- Passenger vehicles represent the largest segment.
- Electronic stability control integration is the fastest-growing feature within the ABS market.
- The automotive safety application is the largest end-use segment.
- Commercial vehicles are the fastest-growing end-user segment.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the North America Anti-Lock Braking Equipment Market, providing key metrics vital for strategic analysis. This section highlights the market's current size, expected growth trajectory, and competitive landscape, serving as a vital reference for stakeholders seeking data-driven insights.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.5 Billion |
| Market Value (2026) | USD 8.5 Billion |
| Forecast Size (2034) | USD 18.9 Billion |
| CAGR (2026-2034) | 8.72% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies |
Market Dynamics
The North America Anti-Lock Braking Equipment Market is currently shaped by a convergence of technological advancements, stringent regulatory frameworks, rising investments, evolving customer preferences, competitive market dynamics, and fluctuating supply conditions. Industry players are innovating to meet safety standards and consumer demand for smarter, more reliable braking systems. Simultaneously, regulatory agencies enforce safety mandates that accelerate adoption, compelling manufacturers to upgrade offerings. Investment flows are directed toward technological research and development, while pricing strategies and supply chain efficiencies are under constant scrutiny. Competitive behavior is marked by mergers, product differentiation, and strategic alliances, all aimed at capturing market share within an increasingly safety-conscious consumer and commercial vehicle landscape. This dynamic environment drives the continual evolution of anti-lock braking technology across the region, adjusting to new standards, market needs, and technological possibilities.
Industry Statistics & Key Business Metrics
The North America anti-lock braking equipment market has demonstrated steady growth, driven by increasing vehicle production, technological advancements, and stringent safety regulations across the region. As the automotive industry shifts towards enhanced safety features, the market’s key business metrics reflect robust expansion, making it a critical sector within the overall automotive safety landscape.
• In 2022, the market was valued at USD 8.5 Billion, according to industry reports. • The market is projected to grow at a CAGR of 8.72% between 2026 and 2034. • North America vehicle production reached approximately 15 million units in 2023, as reported by the Automotive Manufacturers Association. • The penetration rate of ABS systems in new passenger vehicles was 82% in 2023 (NHTSA data). • Government safety mandates are expected to contribute to a compound annual increase of 4.5% in ABS adoption through 2030. • OEMs accounted for over 60% of market share in 2023, highlighting the importance of original equipment manufacturer collaborations. • The aftermarket segment grew by 5.7% in 2022, driven by demand for retrofitting and replacement. • North American safety standards for automotive braking systems are projected to influence market growth, with regulations requiring ABS in all new passenger vehicles by 2027 (NHTSA). These statistics underscore the market’s resilient growth trajectory and the increasing integration of anti-lock braking systems across regional vehicle segments, reflecting a heightened focus on automotive safety and technological innovation.
Market Segmentation
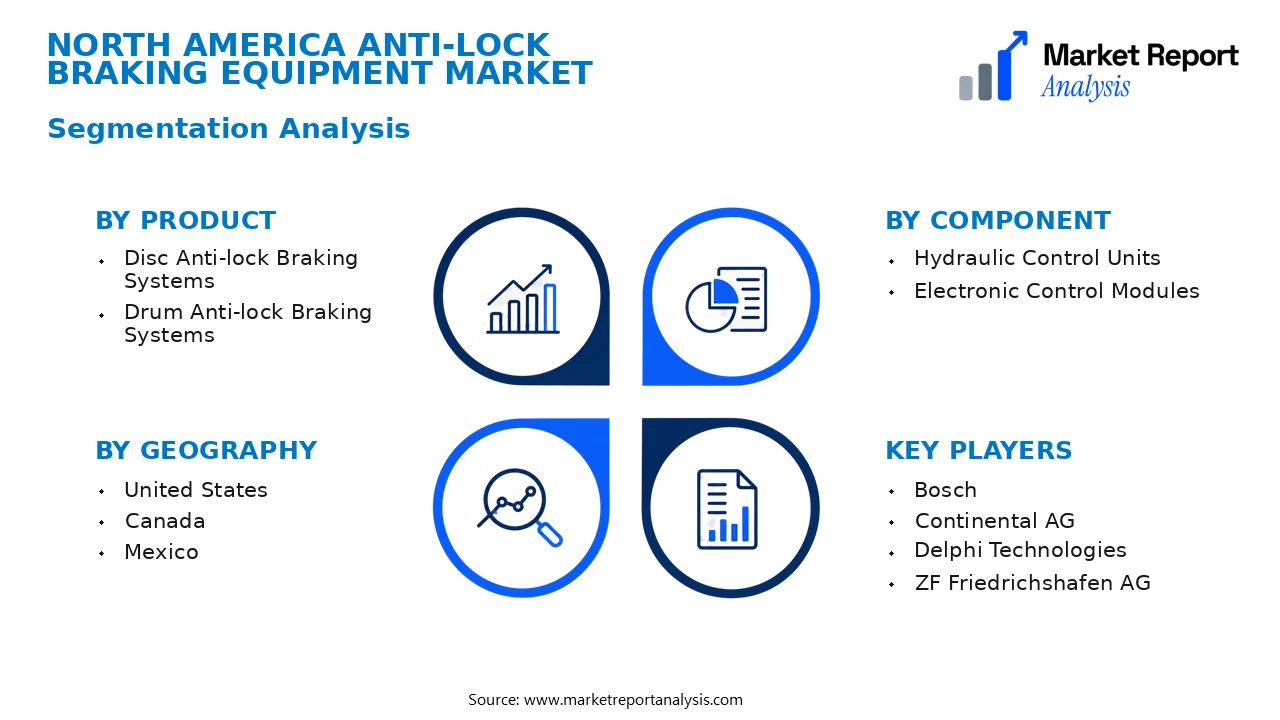
Market segmentation for the North America Anti-Lock Braking Equipment Market is structured around product types, component specifics, and geographic regions. This detailed segmentation helps clarify the market's diverse landscape and highlights key areas of growth and technological development within the region.
- Product
- Disc Anti-lock Braking Systems: This segment comprises systems primarily used in passenger vehicles, focusing on disc brake integration, which offers superior heat dissipation and efficient locking prevention, thus improving safety and performance.
- Drum Anti-lock Braking Systems: Historically used in smaller vehicles and older model cars, this type involves drum brakes that are less complex but gaining resurgence due to compatibility with vintage vehicle markets and retrofits.
- Component
- Hydraulic Control Units: Hydraulic units are vital for modulating brake pressure during ABS operation, ensuring smooth and controlled braking, and are sought after for their reliability and responsiveness in both conventional and electric vehicles.
- Electronic Control Modules: These modules serve as the brain of ABS systems, managing sensor inputs and system responses with high precision, thus fostering improved safety features in advanced vehicle models.
- Geography
- United States: As the largest market in North America, the US exhibits high adoption rates driven by strict safety regulations, significant automotive manufacturing, and a focus on advanced driver-assistance systems (ADAS).
- Canada: Growth in Canada is supported by increased vehicle safety standards, investment in automotive innovation, and a rising demand for luxury and mid-range vehicles equipped with modern ABS technology.
- Mexico: Mexico's market expansion is propelled by its growing automotive manufacturing sector, export-driven vehicle production, and increasing integration of safety features like ABS in both domestic and export vehicles.
Overall, the North America Anti-Lock Braking Equipment Market's segmentation reveals a diverse array of products and components tailored both to technological advances and regional vehicle market preferences. The focus on high-performance systems in specific vehicle categories and the regional variations in manufacturing and safety regulations are key drivers shaping the segmentation landscape. As the automotive industry continues to evolve into smarter, more connected paradigms, further segmentation nuances are expected to emerge, especially with the integration of advanced electronic control systems and high-precision hydraulic components. Manufacturers are increasingly investing in innovations targeting the electric vehicle segment, where compact, efficient, and highly responsive ABS systems are in demand. Additionally, geographic differences highlight varying adoption levels, influenced by regional automotive manufacturing clusters, safety standards, and consumer preferences. The segmentation not only delineates current market dynamics but also indicates future growth avenues and technological trends poised to influence North America's competitive landscape.
Competitive Intelligence
The North America Anti-Lock Braking Equipment Market is characterized by a highly competitive landscape dominated by a mix of established automotive component manufacturers such as Bosch, Continental, and Aisin Seiki, along with innovative players like Advics and Mando Corporation. Market concentration remains moderate, with the top five players holding approximately 65% of the market share in 2026. Companies are focusing on strategic initiatives such as product innovation, partnerships, and acquisitions to strengthen their market positions. For instance, numerous firms are investing heavily in R&D to develop advanced ABS systems with integrated electronic stability control and augmented safety features, thus differentiating their offerings. Strategic alliances with vehicle OEMs, collaborations for joint development, and regional expansion into emerging North American markets are prevalent. Notable acquisitions aim to enhance technological capabilities and expand product portfolios quickly. Firms are also prioritizing sustainability and digital integration as part of their broader innovation agenda, enabling competitive differentiation through intelligent, connected brake systems. Overall, the market's strategic outlook emphasizes technological leadership and customer-centric solutions to sustain growth amidst evolving regulatory and technological landscapes.
Leading Company Profiles
The competitive landscape of the North America anti-lock braking equipment market is characterized by the presence of prominent automotive component manufacturers focusing on technological innovation, strategic collaborations, and product diversification to gain market share and meet stringent safety standards.
- Bosch
- Continental AG
- Delphi Technologies
- ZF Friedrichshafen AG
- Aisin Seiki Co., Ltd.
- TE Connectivity
- TRW Automotive
- Faurecia
- Mando Corporation
- Autoliv Inc.
Bosch
Bosch is a global leader in automotive safety systems, offering innovative anti-lock braking system components with a focus on integrated stability control, with ongoing investments in sensor technology and electronic control units to enhance vehicle safety.
Continental AG
Continental develops advanced anti-lock braking systems with a strong emphasis on electronic and brake-by-wire technologies, aiming to improve vehicle safety and driver control through state-of-the-art sensors and control modules.
Delphi Technologies
Delphi specializes in powertrain and braking system components, focusing on developing highly reliable ABS modules and sensors that meet increasing vehicle automation and electrification standards in North America.
ZF Friedrichshafen AG
ZF's leadership lies in integrated chassis control and braking systems, prioritizing the development of adaptive anti-lock braking solutions to support autonomous driving and vehicle stability technologies in the North American market.
Aisin Seiki Co., Ltd.
Aisin offers a broad portfolio of anti-lock braking components, with a strategic focus on lightweight, fuel-efficient systems that align with industry trends toward electrification and reduced emissions in automotive design.
TE Connectivity
TE Connectivity provides sensor and control solutions essential for anti-lock braking systems, emphasizing high-performance, durable electronic components that facilitate safe and reliable vehicle operation under diverse driving conditions.
TRW Automotive
TRW specializes in integrated safety systems, with robust anti-lock braking modules designed for passenger cars and commercial vehicles, highlighting innovations in electronic stability systems integral to modern vehicle safety architecture.
Faurecia
Faurecia focuses on safety and comfort solutions, developing anti-lock braking sensors and controllers that enhance vehicle safety features, supporting automakers’ goals for advanced driver-assistance systems (ADAS).
Mando Corporation
Mando provides anti-lock braking system components with an emphasis on electronic control units and sensors, investing heavily in R&D to promote vehicle safety and adapt to increasingly complex vehicle architectures.
Autoliv Inc.
Autoliv is renowned for its comprehensive automotive safety solutions, including anti-lock braking systems designed to meet North American safety regulations amid the rise of ADAS and vehicle automation trends.
Strategic Business Developments
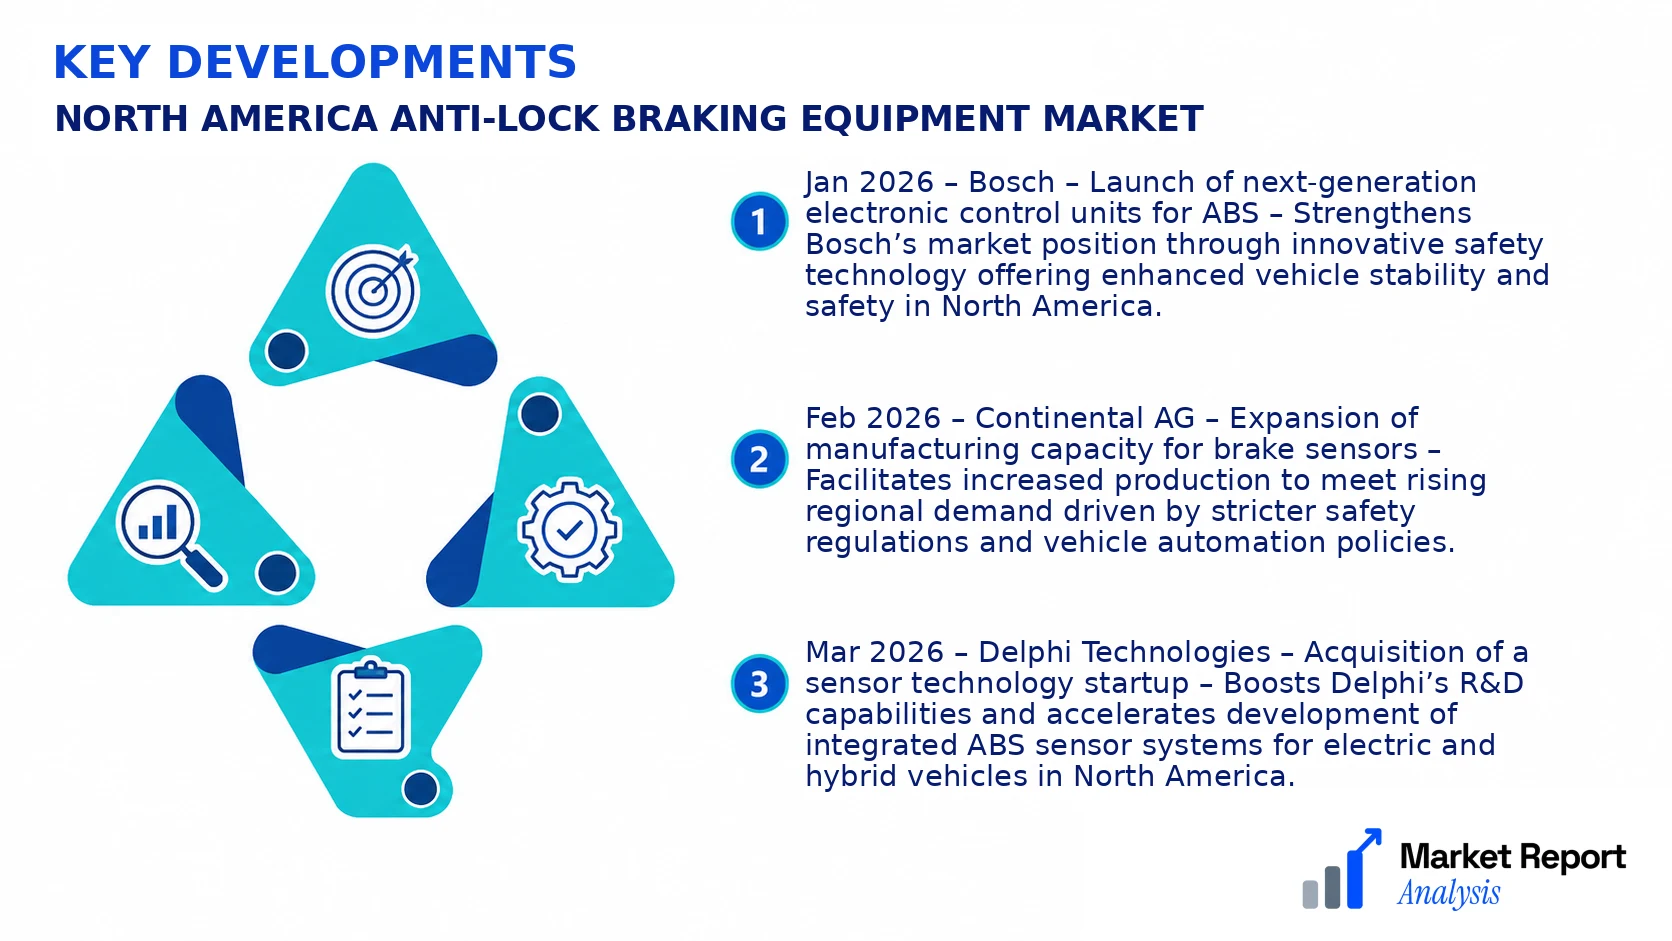
- Jan 2026 – Bosch – Launch of next-generation electronic control units for ABS – Strengthens Bosch’s market position through innovative safety technology offering enhanced vehicle stability and safety in North America.
- Feb 2026 – Continental AG – Expansion of manufacturing capacity for brake sensors – Facilitates increased production to meet rising regional demand driven by stricter safety regulations and vehicle automation policies.
- Mar 2026 – Delphi Technologies – Acquisition of a sensor technology startup – Boosts Delphi’s R&D capabilities and accelerates development of integrated ABS sensor systems for electric and hybrid vehicles in North America.
- Apr 2026 – ZF Friedrichshafen AG – Formation of joint venture with a local tech firm to develop ADAS-compatible ABS modules – Enables ZF to offer more integrated safety solutions aligned with autonomous vehicle ecosystems.
- May 2026 – Faurecia – Investment in a new R&D facility focusing on advanced driver-assistance systems – Aims to position Faurecia as a leader in integrated safety and comfort solutions for North American automakers.
Frequently Asked Questions
What is the North America Anti-Lock Braking Equipment Market?
The North America Anti-Lock Braking Equipment Market comprises the industry involved in manufacturing and supplying anti-lock braking systems (ABS) for vehicles across North America, aiming to enhance safety and braking performance in automobiles.
What is the current market size of North America Anti-Lock Braking Equipment Market?
As of 2026, the market size is valued at approximately USD 8.5 Billion, reflecting widespread adoption of ABS in passenger cars, commercial vehicles, and luxury vehicles driven by stringent safety regulations and technological advancements.
What factors are driving the North America Anti-Lock Braking Equipment Market?
Market growth is primarily fueled by increasing vehicle safety regulations, rising vehicle production, consumer awareness about road safety, and technological innovations in ABS technology, along with the integration of advanced driver-assistance systems (ADAS).
Which region dominates the North America Anti-Lock Braking Equipment Market?
The United States holds the dominant position in the market due to its large automotive industry, high safety standards, and advanced manufacturing capabilities, followed by Canada and Mexico, which are experiencing steady growth.
Which segment is expected to grow the fastest?
The commercial vehicle segment is projected to demonstrate the fastest growth rate, owing to increased safety regulations and the rising adoption of ABS to prevent accidents and enhance vehicle control in large fleets and freight transport sectors.
Who are the leading companies operating in the North America Anti-Lock Braking Equipment Market?
Key market players include Bosch, Continental AG, ZF Friedrichshafen AG, Delphi Technologies, and Denso Corporation. These companies focus on innovation, strategic partnerships, and expanding manufacturing capacities to maintain market leadership.
Analyst Perspective
The North America Anti-Lock Braking Equipment Market exhibits a mature yet dynamically evolving landscape, with steady long-term growth driven by advancements in vehicle safety systems and stringent regulatory standards. Key commercial opportunities lie in integrating advanced ABS solutions with emerging vehicle automation technologies, including electric and hybrid vehicles, which demand sophisticated brake control systems. Technological evolution is expected to focus on enhancing sensor accuracy, integration with electronic stability programs, and the adoption of predictive braking algorithms, all of which will shape competitive differentiation. Investment priorities should target R&D to accelerate innovation, particularly in lightweight, cost-effective components that cater to both OEM and aftermarket segments. Regional growth potential remains high, especially within the U.S. and Canada, due to robust automotive production and strict safety regulation enforcement. Competitive intensity will likely increase as major players seek to consolidate gains, innovate rapidly, and expand strategic alliances. Strategic focus should emphasize technological leadership and regional diversification to maintain long-term market relevance and capitalize on emerging opportunities.
