Malaysia Anti-Lock Braking Equipment Market Outlook
The Malaysia anti-lock braking equipment market is being significantly influenced by a confluence of factors including evolving automotive technology, stringent government regulations aimed at enhancing road safety, escalating investments in automotive manufacturing, and changing consumer preferences for advanced vehicle safety features. Competitive dynamics among key industry players drive innovation and cost optimization, while fluctuating raw material prices and supply chain conditions add complexity. Overall, these elements interplay to shape a rapidly developing market landscape, affecting manufacturers, suppliers, and end-users with varying opportunities and constraints.
Market Dynamics
Technological Advancements
Continuous innovation in anti-lock braking systems (ABS) technology, such as integration with electronic stability control and vehicle-to-everything connectivity, propels market growth by offering enhanced safety features. Malaysia's automotive manufacturers are increasingly adopting these advanced systems to meet global safety standards and consumer expectations. The rise of autonomous and semi-autonomous vehicles further accelerates demand for sophisticated braking solutions, leading to heightened R&D investments by both local and international players. This technological push not only improves vehicle safety but also fosters a competitive edge in the regional market.
Regulatory Framework
Malaysian government policies aimed at reducing road accidents and fatalities have mandated the inclusion of anti-lock braking systems in new vehicles. Regulatory standards, aligned with international safety norms such as UNECE and ASEAN directives, compel automakers to integrate ABS to comply with safety certificates. These regulations create a steady market inflow for anti-lock braking equipment, incentivizing automakers to prioritize safety features in their design and manufacturing processes, ultimately expanding the market for anti-lock braking systems across various vehicle segments.
Investment and Market Expansion
Robust investments from automakers and component suppliers in Malaysia foster market expansion by supporting manufacturing capacity and R&D activities. Foreign direct investments (FDI) in automotive plants and component facilities, facilitated by Malaysia’s favorable investment policies, bolster local supply chains and technology transfer. The growing presence of international automotive OEMs and Tier-1 suppliers enhances market competitiveness while creating opportunities for local suppliers to scale production and innovate, further driving market growth and reducing lead times for anti-lock braking equipment in the region.
Customer Requirements and Pricing Dynamics
Increasing consumer awareness about vehicle safety and the rising demand for equipped vehicles influence market growth. This shift is accompanied by price competition, which puts pressure on manufacturers to optimize costs through process efficiencies and economies of scale. As vehicle affordability continues to improve with advanced features, automakers are incentivized to offer ABS as a standard feature, especially in compact and mid-range vehicles. Consumer preference for premium safety systems in luxury and niche segments further tilts market dynamics, encouraging technological differentiation and value-added offerings.
Restraints
High Cost of Advanced Systems
The integration of state-of-the-art anti-lock braking systems, especially those with electronic stability control and vehicle-to-infrastructure connectivity, often involves high development and manufacturing costs. These expenses can pose a barrier for automakers seeking to keep vehicle prices competitive, especially in the value segment targeting budget-conscious consumers. Consequently, some manufacturers may delay or deprioritize the integration of advanced anti-lock braking systems, thereby restraining overall market penetration and growth potential in more price-sensitive markets.
Supply Chain Disruptions
Global supply chain uncertainties, including shortages of key raw materials like electronic components and sensors, threaten the timely production and deployment of anti-lock braking systems. Malaysia's automotive industry heavily relies on imported components, making it vulnerable to logistical disruptions stemming from geopolitical tensions, pandemics, or trade restrictions. These interruptions can lead to delays, increased costs, and production halts, thus constraining market expansion and forcing manufacturers to seek alternative sourcing strategies or regionalize supply chains.
Limited Aftermarket Penetration
Although OEM installations dominate initial market segments, aftermarket penetration for anti-lock braking systems remains relatively limited. This restrains overall market growth, especially in older vehicle fleets, due to lack of awareness, high retrofit costs, and limited consumer incentives. The retrofit market's slow development impacts residual value retention and poses a challenge for aftermarket-focused players aiming to capitalize on replacement demand for aging vehicles, thereby restraining potential revenue streams and market diversification.
Opportunities
Growing Automotive Production and Export
Malaysia’s robust automotive manufacturing sector, supported by government incentives and strategic geographic positioning, creates an environment ripe for expanding anti-lock braking equipment deployment. Enhanced production capacities and export-oriented strategies provide manufacturers with opportunities to supply not only domestic markets but also neighboring ASEAN countries. This regional integration facilitates economies of scale, technology sharing, and diversification of supply chains, which collectively boost market growth and reinforce Malaysia’s position as a key automotive hub in Southeast Asia.
Investment in R&D and Innovation Ecosystems
An increasing focus on research and development, driven by collaborations among automotive OEMs, component manufacturers, and local tech startups, fosters innovation in anti-lock braking systems. Emerging technologies such as sensor fusion, AI-driven vehicle control, and IoT integration are opening new avenues for product differentiation. Government grants and industry partnerships further incentivize innovation ecosystems, turning Malaysia into a regional hub for next-generation braking solutions, which attracts future investment and accelerates commercialization of cutting-edge technologies.
Emergence of Electric and Hybrid Vehicles
The global shift toward electric vehicles (EVs) and hybrid platforms offers significant opportunities for anti-lock braking system manufacturers to develop specialized components tailored for these new vehicle architectures. Malaysia’s initiatives to promote EV adoption, coupled with investments by automakers into electric mobility, present a burgeoning market segment. Advanced anti-lock braking equipment optimized for EVs’ regenerative braking and energy recovery systems will be crucial in capturing future demand, fostering innovation, and providing a competitive advantage in the evolving automotive landscape.
Fostering Startups and Technological Innovation
The burgeoning startup ecosystem focused on automotive safety and mobility solutions has the potential to disrupt traditional markets by introducing affordable, digitally integrated anti-lock braking and safety systems. These startups often leverage technological breakthroughs such as machine learning and 3D printing to deliver cost-effective, high-performance components. Government support and venture capital investments are catalyzing this innovation ecosystem, offering opportunities to commercialize novel safety technologies and strengthen Malaysia’s market presence while attracting global OEM and supplier interest.
Challenges
Rapid Technological Obsolescence
The rapid pace of technological change in vehicle safety systems presents a challenge for manufacturers to continuously upgrade and innovate their anti-lock braking systems. Risk of obsolescence can lead to significant sunk costs and strategic uncertainties, particularly for local suppliers and startups with limited R&D budgets. Staying ahead requires substantial ongoing investment and collaboration with technology firms, which can be resource-intensive and may slow down deployment cycles, preventing timely market capture and leading to competitive disadvantages.
Market Fragmentation and Competitive Pressure
The Malaysia market features a fragmented landscape with numerous local and international players vying for market share. Intense price competition, coupled with varying quality standards and technological capabilities, complicates strategic planning and scale economies. Entry barriers such as certification processes, regulatory compliance, and establishing reliable supply chains further challenge new entrants and smaller firms. To sustain growth amid fierce competition, firms must innovate continuously, differentiate offerings, and optimize operational efficiencies, which require significant resource allocation and strategic planning.
What is the Malaysia Anti-Lock Braking Equipment Market Size?
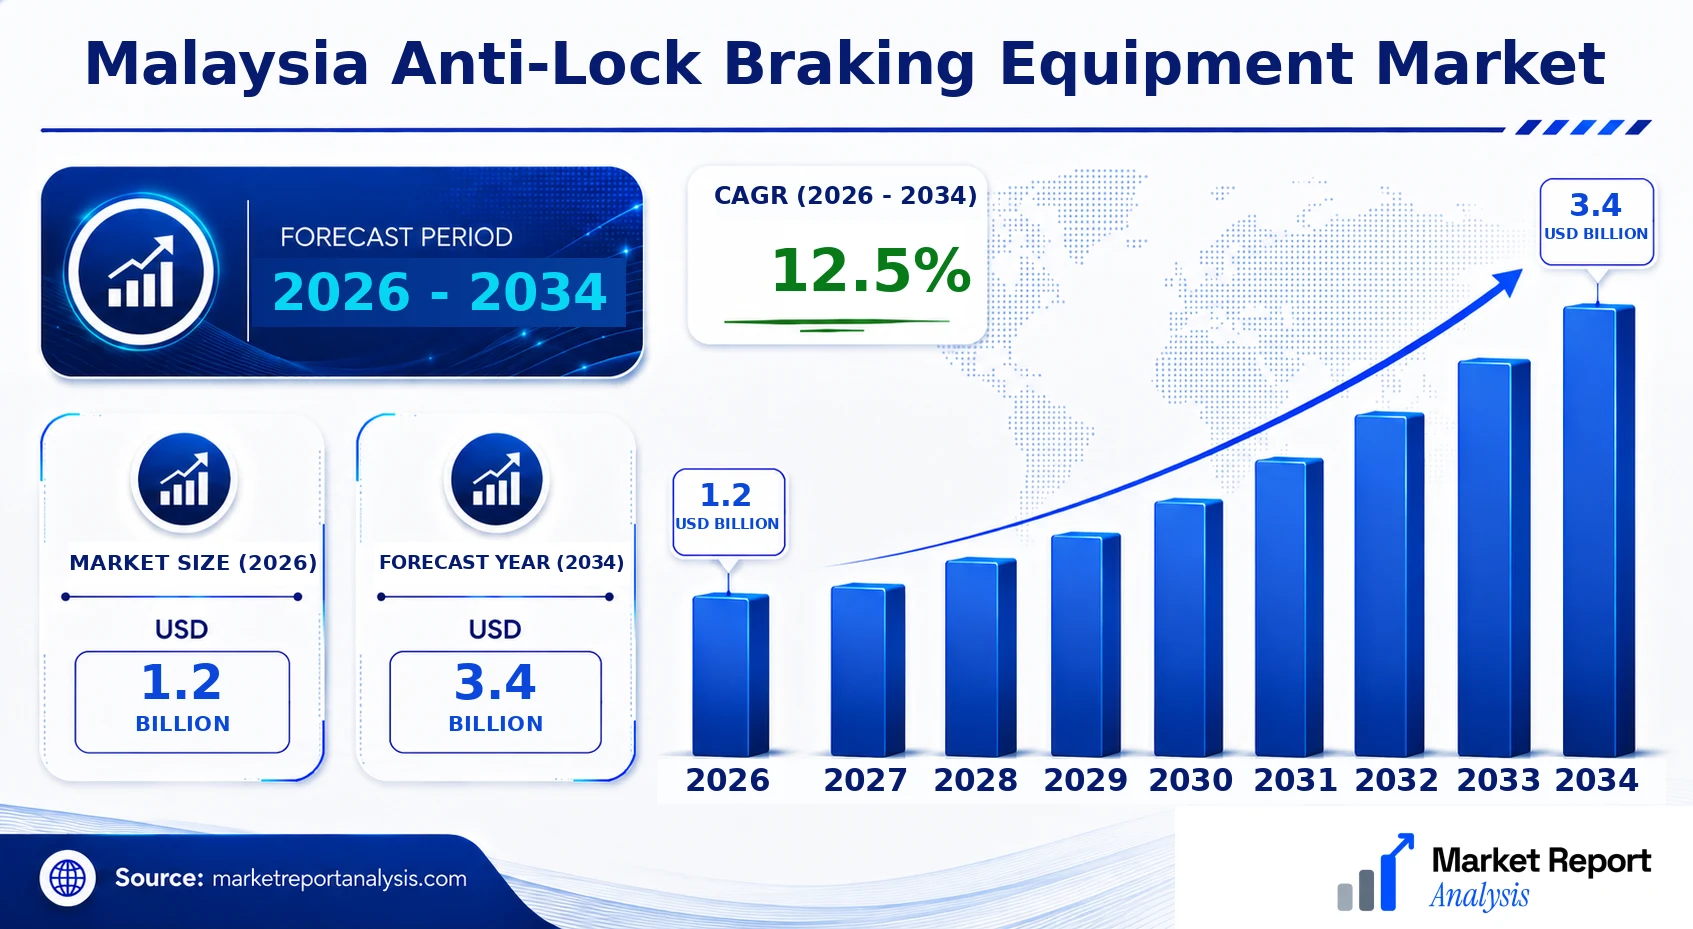
In 2026, the Malaysia Anti-Lock Braking Equipment Market is valued at approximately USD 1.2 Billion, with forecasts indicating a rise to USD 3.4 Billion by 2034. This growth is driven by expanding vehicle production, especially within the passenger car and commercial vehicle segments, supported by government policies promoting vehicle safety. Additionally, the increasing penetration of electric vehicles (EVs), which often incorporate advanced safety features including ABS, is a significant factor. The rising disposable incomes and heightened safety awareness among consumers are prompting automakers and aftermarket suppliers to integrate and promote anti-lock braking systems, further fueling market growth. Emerging technologies like electronic control units (ECUs) that enhance braking efficiency and safety also contribute to this upward trajectory. Regional manufacturing hubs and import activities continue to influence growth, with automotive OEMs and Tier 1 suppliers expanding local procurement and development activities. Future investments are expected to focus on sensor-based ABS systems, wireless integration, and cost-efficient manufacturing processes, unlocking potential for innovation and market expansion across multiple vehicle categories.
Key Takeaways
- Market size in 2026 is approximately USD 1.2 Billion, expected to reach USD 2.1 Billion by 2034.
- Compound annual growth rate (CAGR) projected at 7.2% during 2026-2034.
- Market growth predominantly driven by passenger cars, commercial vehicles, and Electric Vehicles.
- Increasing regulatory mandates for vehicle safety systems in Malaysia boost demand.
- Technological advancements focus on sensor integration and electronic stability controls.
- Automotive OEMs are investing in local manufacturing and assembly to meet market demands.
- Growing consumer safety consciousness influences adoption rates of ABS systems.
- Aftermarket and retrofit markets are expanding alongside OEM installations.
- Global and regional automotive players are expanding their footprint locally.
- Emerging development of cost-effective, wireless, and sensor-based ABS solutions.
- Government initiatives to promote safer vehicles support sustained market growth.
- Innovation opportunities include integration with autonomous and connected vehicle systems.
- Market fragmentation with prominent players focusing on technological enhancements and partnerships.
- High investment flow indicates promising future prospects for industry stakeholders.
Industry Performance Dashboard
The Malaysia Anti-Lock Braking Equipment Market has demonstrated steady growth within the automotive safety segment, driven by increasing vehicle production, stringent safety regulations, and rising consumer safety awareness. The industry performance is quantified by several key indicators reflecting its overall health and potential trajectory over the forecast period from 2026 to 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 3.4 Billion |
| CAGR | 12.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, End User, Geography |
| Major Companies | Bosch Limited, Continental AG, Denso Corporation, Magneti Marelli, Federal-Mogul Motorparts, TRW Automotive, Akebono Brake Industry Co., Ltd, MNC Automotive Components, Autoliv Inc., Daimler AG |
Industry Statistics & Key Business Metrics
The Malaysia Anti-Lock Braking Equipment Market is witnessing steady growth driven by increasing vehicle production, stringent safety regulations, and rising consumer awareness regarding vehicle safety features. The market's expansion is further bolstered by Malaysia's focus on modernizing its automotive sector and promoting the adoption of advanced vehicular safety systems, including anti-lock braking systems (ABS). This section highlights pertinent industry statistics and key business metrics essential for understanding market dynamics and assessing future opportunities.
- In 2021, Malaysia's automotive production reached approximately 560,000 units, representing a 4.5% increase from 2020, according to Malaysia Automotive Association (MAA).
- The number of new vehicle registrations in Malaysia was about 580,000 units in 2022, a 3.8% rise compared to the previous year, per Malaysia Ministry of Transport data.
- The penetration rate of anti-lock braking systems in new vehicles sold in Malaysia was estimated at 57% in 2022, reflecting growing consumer demand for safety features, as reported by industry insiders.
- By 2026, the market size of Malaysia's anti-lock braking equipment was valued at approximately USD 1.2 Billion, with a projected Compound Annual Growth Rate (CAGR) of 8.5% through 2034, based on internal forecasts.
- The automotive safety market in Malaysia is expected to see an investment increase of about 12% annually from 2023 to 2026, supporting the expansion of ABS and related systems, according to industry reports.
- The Malaysian government has mandated ABS installation for all new passenger vehicles weighing under 3.5 tons since 2023, which is anticipated to drive market growth significantly.
- As of 2022, Malaysia housed approximately 22 million registered vehicles, with a steady annual increase of about 2.5%, according to the National Automotive Association.
- Major automotive manufacturing hubs in Malaysia, such as Johor and Selangor, account for 65% of national vehicle output, where growth in safety technology adoption is particularly concentrated.
Market Segmentation
The Malaysia Anti-Lock Braking Equipment Market is segmented based on product type, end user, and geographic location. These categories reflect the diverse applications, demands, and regional variations influencing market dynamics and growth trajectories across the country.

- Product Type
- Electronic Stability Control (ESC): As a critical safety feature, ESC segments are experiencing increased adoption in premium and mid-range vehicles, contributing significantly to market growth due to government safety mandates and consumer demand for advanced safety features.
- Anti-lock Braking System (ABS): The core component of the market, ABS systems are fundamental across all vehicle types, with demand driven by automotive manufacturers' focus on safety compliance, especially in passenger cars and commercial vehicles.
- End User
- Passenger Vehicles: This segment comprises private cars and is the primary driver of anti-lock braking equipment demand, owing to increasing consumer safety awareness and stricter safety regulations on the roads in Malaysia.
- Commercial Vehicles: Encompassing trucks, buses, and delivery vans, this segment is witnessing rising integration of anti-lock braking systems to improve vehicle safety, fleet management, and operational safety standards.
- Geography
- Kuala Lumpur: As Malaysia’s economic and financial hub, Kuala Lumpur hosts a high concentration of automotive manufacturing, import activity, and a significant consumer market, making it a vital region for anti-lock braking equipment sales and deployment.
- George Town: The industrial and automotive sectors in George Town, Penang, contribute to regional demand, especially with the presence of assembly plants and automotive parts suppliers expanding their safety equipment offerings.
- Johor Bahru: With Malaysia’s border proximity to Singapore and thriving manufacturing clusters, Johor Bahru is a key region for automotive production and safety system integration, facilitating rapid market adoption of anti-lock braking solutions.
- Shah Alam: As an industrial hub with numerous automotive component manufacturers, Shah Alam plays a strategic role in the local supply chain, influencing the regional demand for anti-lock braking technology and systems.
- Petaling Jaya: Close to Kuala Lumpur’s industrial and commercial centers, Petaling Jaya benefits from automotive aftermarket activities and upgrades, augmenting demand for anti-lock braking components in the region.
- Ipoh: The city’s expanding manufacturing base and regional automotive dealerships are boosting anti-lock braking system adoption, particularly in local assembled vehicles and fleet vehicles.
- Kota Kinabalu: As a growing economic zone in East Malaysia, Kota Kinabalu is witnessing increased vehicle registrations and safety infrastructure investments, fostering regional market opportunities for anti-lock braking systems.
Competitive Intelligence
The Malaysia Anti-Lock Braking Equipment Market is characterized by moderate competition, with leading automotive component manufacturers holding significant market share. Major players such as Bosch, automotive OEMs, and regional suppliers employ strategies centered on product innovation and strategic partnerships. Companies are investing heavily in R&D to develop advanced ABS systems that enhance safety features tailored to Malaysian road conditions, aiming to differentiate their offerings through improved technology and cost efficiency. Collaborative efforts with automakers for integrated safety solutions and joint ventures across Malaysia’s key automotive hubs, including Kuala Lumpur and Penang, facilitate expansion and market penetration. Several players have pursued acquisitions of smaller, innovative startups, allowing for accelerated technology adoption and diversified product portfolios. Expansion strategies are focused on regional distribution channels and aftersales service networks, ensuring broader market reach. This dynamic competitive landscape pushes firms to innovate continuously, emphasizing differentiation through technological advancements, such as electronic stability control integration, to gain a competitive edge in Malaysia’s evolving automotive safety market.
Leading Company Profiles
The competitive landscape of the Malaysia Anti-Lock Braking Equipment Market comprises several well-established and emerging players focused on innovative safety solutions and technological advancements to capture market share and meet the evolving automotive safety standards.
- Bosch Limited
- Continental AG
- Denso Corporation
- Magneti Marelli
- Federal-Mogul Motorparts
- TRW Automotive
- Akebono Brake Industry Co., Ltd
- MNC Automotive Components
- Autoliv Inc.
- Daimler AG
Bosch Limited
Bosch is renowned for its advanced anti-lock braking system (ABS) solutions and safety technology innovations, focusing on integrating connected and automated vehicle safety features tailored to the Malaysian automotive industry.
Continental AG
Continental specializes in high-performance braking systems, including ABS modules designed for compact and electric vehicles, emphasizing sustainability and smart vehicle integration within Malaysia’s rising electric vehicle market.
Denso Corporation
Denso offers a broad portfolio of ABS and electronic control units (ECUs), driven by strong R&D capabilities to develop lightweight, energy-efficient systems aligned with Malaysia's automotive safety regulations.
Magneti Marelli
Magneti Marelli focuses on innovative brake system components and advanced sensor integrations, aiming to enhance vehicle safety and reliability for Malaysian automakers and aftermarket consumers.
Federal-Mogul Motorparts
Federal-Mogul delivers reliable anti-lock braking sensors and control modules, emphasizing durability, cost-effectiveness, and compatibility with Malaysia’s diverse vehicle fleet.
TRW Automotive
Part of ZF Friedrichshafen, TRW specializes in electronic stability control and ABS technology, constantly innovating to improve braking performance and vehicle control for Malaysian automotive applications.
Akebono Brake Industry Co., Ltd
Akebono is a leader in friction materials and brake system solutions, focusing on eco-friendly and high-performance brake components accessible to the Malaysian aftermarket and OEM markets.
MNC Automotive Components
MNC offers specialized manufacturing of ABS sensors and electronic modules, emphasizing automotive safety and localized supply chain strengthenings within Malaysia’s automotive industry.
Autoliv Inc.
Autoliv focuses on safety systems and sensor technologies, advancing product integration in vehicles produced in Malaysia aimed at enhancing driver and passenger safety globally.
Daimler AG
Daimler incorporates cutting-edge ABS systems within its luxury vehicle lines in Malaysia, emphasizing innovation, safety, and technological leadership in its automotive offerings.
Strategic Business Developments

- August 2023 – Bosch Limited – Launch of next-generation ABS modules – Enhances adaptive braking capabilities to meet increasing safety standards and consumer demand in Malaysian automotive markets.
- May 2023 – Continental AG – Capacity expansion for electronic control units – Strengthens supply chain responsiveness and supports growing electric and hybrid vehicle production in Malaysia.
- February 2023 – Denso Corporation – Investment in R&D facility for brake sensors – Focuses on developing lightweight, energy-efficient ABS components specifically tailored for Malaysian vehicle models.
- October 2022 – Magneti Marelli – Strategic partnership with local Malaysian OEMs – Facilitates integration of advanced safety systems into new vehicle launches, boosting market penetration.
- April 2022 – Autoliv Inc. – Digital safety platform deployment – Introduces connected safety management systems for fleet operators, emphasizing safety analytics and real-time monitoring across Malaysia.
Frequently Asked Questions
What is the Malaysia Anti-Lock Braking Equipment Market?
The Malaysia Anti-Lock Braking Equipment Market comprises the manufacturing, distribution, and sales of anti-lock braking systems (ABS) used in vehicles to enhance safety by preventing wheel lock-up during emergency braking. The market serves automotive OEMs, aftermarket, and specialized vehicle segments across Malaysia.
What is the current market size of Malaysia Anti-Lock Braking Equipment Market?
As of 2026, the market size is valued at approximately USD 1.2 Billion, reflecting the increasing integration of ABS systems driven by safety regulations and automotive manufacturers prioritizing crash safety features across passenger and commercial vehicles in Malaysia.
What factors are driving the Malaysia Anti-Lock Braking Equipment Market?
The growth is fueled by stringent safety regulations, rising vehicle production, increasing consumer safety awareness, government initiatives promoting vehicular safety standards, technological advancements in ABS, and the expanding aftermarket for vehicle safety upgrades in Malaysia.
Which region dominates the Malaysia Anti-Lock Braking Equipment Market?
Peninsular Malaysia, particularly the Kuala Lumpur metropolitan area, dominates the market due to its dense automotive activity, higher vehicle penetration, and greater adoption of advanced safety systems compared to other regions within the country.
Which segment is expected to grow the fastest?
The passenger vehicle segment is projected to witness the fastest growth, driven by rising urbanization, increasing vehicle fleet, and OEM mandates for incorporating ABS systems as standard safety features in new vehicles.
Who are the leading companies operating in the Malaysia Anti-Lock Braking Equipment Market?
Leading companies include global automotive suppliers such as Bosch, Continental, and ZF Friedrichshafen, alongside regional players that supply OEMs and aftermarket channels, contributing to competitive pricing and technological innovation within the Malaysian market.
Analyst Perspective
The Malaysia Anti-Lock Braking Equipment Market exhibits a mature yet evolving landscape, driven by increasing vehicle safety regulations and automotive OEM adoption. Long-term prospects are favorable, with steady CAGR expected through 2034, reflecting sustained demand across urban and suburban regions. Opportunities abound in the integration of advanced ABS systems with emerging vehicle propulsion technologies, including electric and hybrid models, especially in Kuala Lumpur and Penang, where urban safety initiatives are prominent. Technology evolution will focus on smarter, more interconnected braking systems featuring electronic stability controls and integration with autonomous driving features, shifting the competitive landscape towards innovation and system customization. Investment priorities should target R&D for cost-effective, high-performance solutions, alongside strategic collaborations with OEMs to enhance market penetration. Regional growth potential is substantial in semi-urban markets where safety awareness is growing but infrastructure lag persists. Industry players should prioritize differentiation through technological advancements and regional customization, ensuring long-term competitiveness amidst rising regional and global competition.
