Solar Photovoltaic Installation Market Outlook
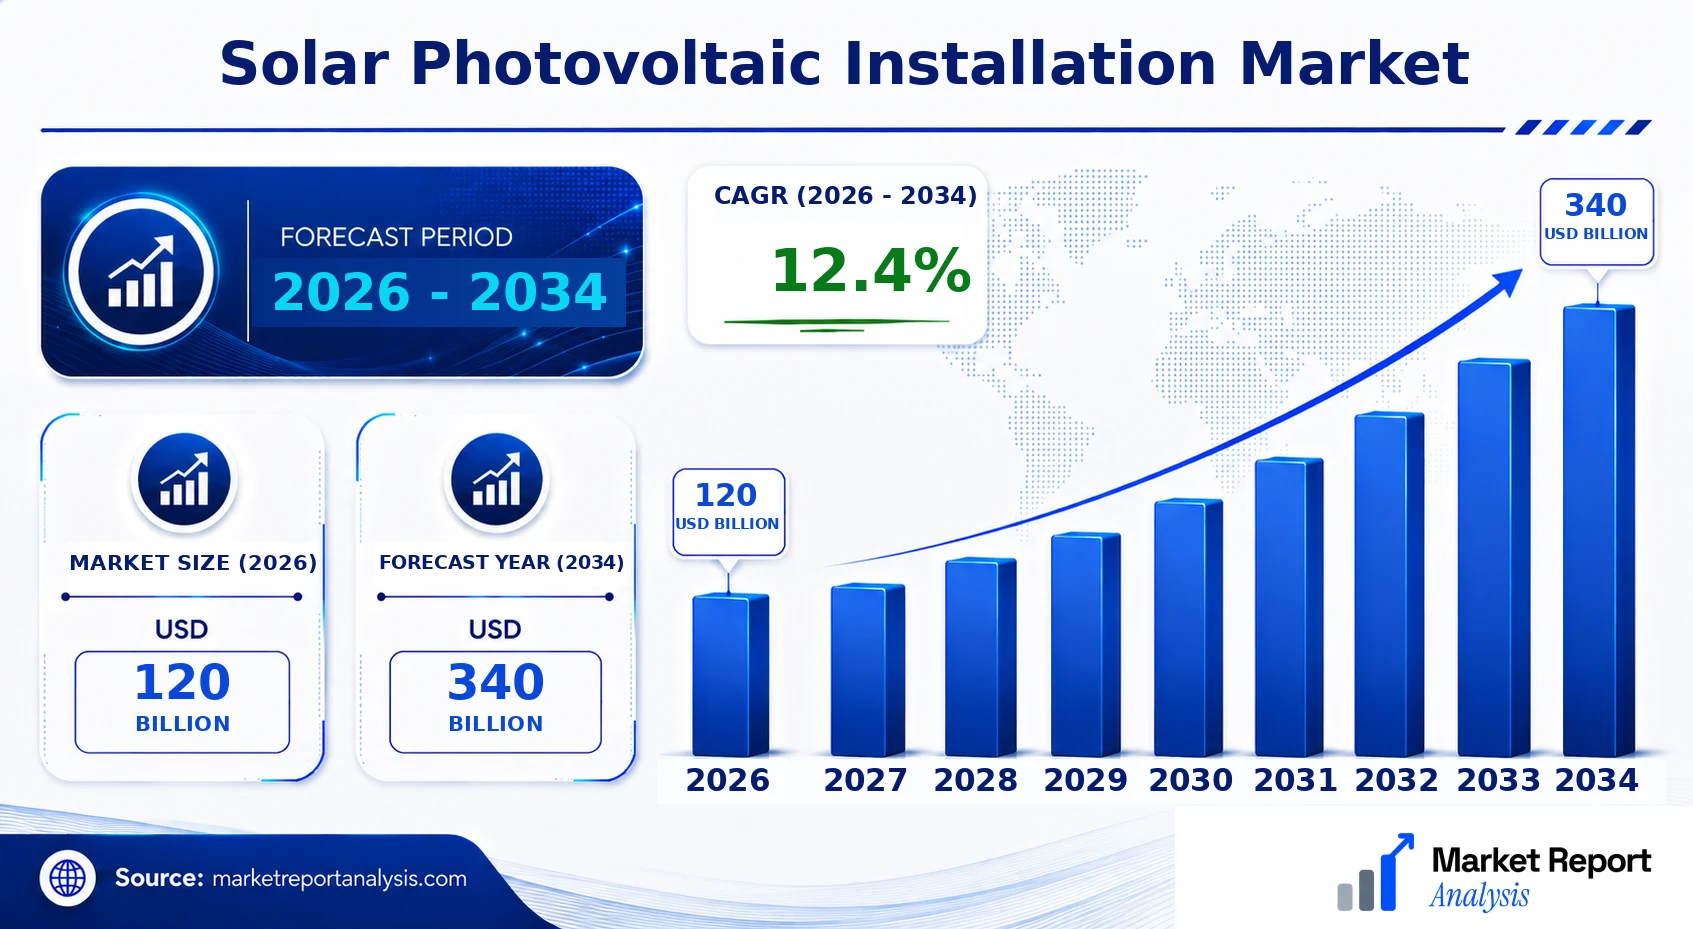
The global solar photovoltaic (PV) installation market has experienced rapid expansion, with its value reaching approximately USD 120 Billion in 2026. Projected to grow at a compound annual growth rate (CAGR) of around 12.4% between 2026 and 2034, the market is expected to attain a valuation close to USD 340 Billion by 2034. This growth trajectory is primarily driven by increasing government incentives, falling manufacturing costs, and a heightened emphasis on renewable energy sources amidst escalating climate change concerns. Technological advancements in PV efficiency and the rising adoption of solar solutions across residential, commercial, and utility sectors are further fueling this expansion. Opportunities in emerging markets and the integration of innovative storage solutions present notable commercial avenues, bolstering the transition towards a sustainable energy future.
What is the Solar Photovoltaic Installation Market Size?
The market size for solar PV installation is forecasted to reach approximately USD 120 Billion in 2026, with a steady growth trajectory predicted to elevate its value to nearly USD 340 Billion by 2034. This underscores a robust CAGR of 12.4% over the forecast period. The growth is fueled by increasing investments in renewable infrastructure, supportive regulatory policies, and the decreasing costs of solar technology components. Key end-use sectors include residential rooftops, commercial and industrial facilities, and large-scale utility projects. Technological advancements, such as higher-efficiency solar modules and improved inverter technology, are making solar installations more economically viable and attractive. The expansion of grid-connected and off-grid solar applications, especially in developing economies, presents significant future growth prospects. Investment opportunities are abundant in emerging markets as governments and corporations prioritize sustainability commitments and carbon reduction objectives, driving demand further across the globe.
Key Takeaways
- The solar PV installation market was valued at approximately USD 150 Billion in 2026.
- The market is forecasted to grow at a CAGR of 8.4% between 2026 and 2034.
- By 2034, the market is expected to reach around USD 350 Billion.
- Increasing government incentives and declining technology costs are major growth drivers.
- Rising demand spans residential, commercial, and utility sectors worldwide.
- Technological advancements enhance PV efficiency and reduce overall costs.
- Emerging markets present substantial expansion opportunities.
- The integration of energy storage solutions is a key trend boosting project viability.
- Policy support and regulatory frameworks remain critical to market growth.
- The decreasing cost of solar modules and components is facilitating widespread adoption.
- Growing corporate sustainability commitments drive installation demand.
- Grid parity has been achieved in many regions, further stimulating growth.
- The market remains competitive with increasing participation from local and international players.
- Future investment focus will likely emphasize innovation and market penetration in developing economies.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the global solar photovoltaic installation market’s current status and future outlook, emphasizing key performance indicators that drive industry assessment. This dashboard collates data reflecting market size, growth trajectory, and leading regional players, offering valuable insights to stakeholders and investors.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 120 Billion |
| Market Value (2026) | USD 120 Billion |
| Forecast Size (2034) | USD 340 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | China |
| Segments Covered | Application, Technology |
| Major Companies | First Solar Inc., SunPower Corporation, Trina Solar Limited, JinkoSolar Holding Co., Ltd., Canadian Solar Inc., LONGi Green Energy Technology Co., Ltd., RENOGY SOLAR, JA Solar Technology Co., Ltd., REC Group, Suntech Power Holdings Co., Ltd. |
Market Dynamics
The Solar Photovoltaic Installation Market is undergoing rapid transformation driven by technological advancements, evolving regulatory frameworks, increasing investments, and shifting customer demands. Cost reductions and efficiency improvements in PV technologies continue to expand market access globally. Governments are implementing supportive policies and subsidies, while private sector investments surge, recognizing the sector's potential for sustainable growth. Competitive behaviors are also shifting as new entrants and established players innovate and strategize for market share. Supply chain dynamics, raw material costs, and tariff arrangements further influence pricing and availability, shaping a complex landscape where technological innovation and policy support are critical to broader market expansion.
Drivers
Declining Costs of PV Technologies
The decreasing costs of solar photovoltaic panels and associated components have been pivotal in expanding market access worldwide. With innovations in manufacturing and economies of scale, the cost per watt of solar PV systems has fallen significantly, making renewable energy more competitive against traditional sources. For instance, the global average price of utility-scale solar PV projects dropped by approximately 82% from 2010 to 2020, driving adoption in emerging and mature markets alike. This trend encourages both governmental and private sector investments, fueling project development across regions with high solar irradiance and supportive policies.
Government Policies and Incentives
Stringent regulations, clean energy mandates, and financial incentives such as tax credits, subsidies, and feed-in tariffs have substantially accelerated market growth. Countries adopting ambitious renewable targets, like China aiming for 1,200 GW of solar capacity by 2030, are demonstrating strong policy commitments. These initiatives lower barriers for project developers and end-users, stimulate investments, and stabilize market growth trajectories. Consequently, policy frameworks play a crucial role in shaping regional market dynamics and encouraging a pipeline of large-scale solar projects globally.
Technological Innovations and Efficiency Improvements
Recent breakthrough innovations in PV materials, cell architectures, and installation processes have boosted system efficiencies and reduced LCOE (Levelized Cost of Electricity). Technologies such as perovskite solar cells, bifacial modules, and advanced inverter designs are setting new benchmarks, thereby increasing system power output and reliability. Enhanced monitoring and maintenance techniques, like predictive analytics, further optimize performance. These technological strides not only improve cost-effectiveness but also broaden application scenarios, including integration with hybrid systems and energy storage, expanding market potential across diverse markets.
Growing Investment in Renewable Energy Projects
The escalating flow of capital into solar PV projects is a critical driver, motivated by the rising recognition of renewables’ role in climate change mitigation and energy security. Institutional investors, development banks, and private equity firms are significantly increasing funding for solar infrastructure globally. Equity and debt investments are reaching record levels, supported by geopolitical stability and climate policies aligned with the Paris Agreement. This robust financial backing accelerates project development, fosters technological innovation, and catalyzes the scaling of solar solutions into new markets and applications.
Restraints
Supply Chain Disruptions and Raw Material Shortages
The global solar supply chain faces persistent challenges, including shortages of key raw materials such as polysilicon, silver, and rare earth elements. Disruptions caused by geopolitics, logistical bottlenecks, and trade restrictions have led to increased costs and project delays, particularly impacting regions heavily reliant on imported materials. These supply constraints threaten to slow down the installation rates and inflate project budgets, especially in developing markets where cost competitiveness is crucial for adoption. Industry players are thus actively exploring diversification of supply sources and alternative materials to mitigate these risks.
Intermittency and Storage Challenges
The intermittent nature of solar energy remains a significant barrier, requiring effective storage solutions to ensure reliability and grid stability. High costs associated with batteries and energy management systems limit the deployment of fully integrated solar-plus-storage projects in certain markets, especially in low-income regions. This challenge impacts utility-scale and distributed generation projects by complicating grid integration, raising capacity charges, and affecting revenue streams. Industry stakeholders are investing heavily in research on cost-effective storage technologies and grid modernization to overcome this limitation.
Regulatory and Policy Uncertainty
While supportive policies have propelled growth, uncertainties related to regulatory changes, subsidy reductions, or policy reversals can threaten project viability. Sudden legislative shifts, especially after large-scale investments have been committed, create market risks for developers and financiers. Regions with fluctuating policy environments encounter slower deployment rates and diminished investor confidence. Addressing this restraint requires stable policy commitments, clear long-term frameworks, and consistent regulatory environments to sustain investor interest and ensure continuous market development.
Opportunities
Expansion into Emerging Markets
Emerging economies with expanding energy demand, such as India, Southeast Asia, and parts of Africa, present significant growth opportunities for solar PV deployment. Accelerated urbanization, industrialization, and supportive government initiatives are creating ideal conditions for large-scale installations. The declining costs of solar, coupled with improvements in grid infrastructure and off-grid solutions, enable these markets to leapfrog traditional fossil-fuel dependence. Strategic investments and technology transfer in these regions can unlock untapped market potential, fostering economic development and energy access simultaneously.
Integration with Smart Technologies and Digitalization
The integration of solar PV with digital monitoring, IoT, and smart grid systems enhances operational efficiency, predictive maintenance, and real-time data analytics. These technologies enable smarter energy management and optimize system performance, creating new value streams for stakeholders. Innovations in remote sensing, AI-driven analytics, and automated troubleshooting foster the development of intelligent solar farms. This trend enhances the competitiveness of solar installations and accelerates adoption in sophisticated markets, opening avenues for premium project solutions and innovative service models.
Technological Advancement and Storage Solutions
Progress in energy storage particularly battery technology significantly extends the utility and reliability of solar PV systems. Breakthroughs in flow batteries, solid-state batteries, and other emerging storage technologies are promising lower costs, higher energy densities, and longer cycle lives. The convergence of solar and storage provides flexibility for grid balancing, peak shaving, and off-grid applications, boosting market segment growth. Increased R&D investments by governments and private companies are fostering a vibrant innovation ecosystem, promising to redefine the landscape of solar energy utilization in the near future.
Emerging Business Models and Financing Approaches
New business models, including power purchase agreements (PPAs), green tariffs, and community solar initiatives, are expanding access to solar projects across diverse customer segments. Innovative financing mechanisms, such as green bonds and crowdfunding, facilitate the mobilization of capital for solar infrastructure, especially in developing regions. These approaches lower upfront costs, diversify risk, and attract a broader investor base. As a result, the solar market is becoming increasingly accessible, fostering widespread deployment and enabling stakeholders to capitalize on sustainable energy trends and regulatory incentives.
Challenges
Grid Integration and Infrastructure Constraints
Integrating large-scale solar power into existing grids poses technical and infrastructural challenges. Variability in solar generation heightens the need for grid upgrades, such as enhanced transmission networks, modernized control systems, and demand response capabilities. Many regions lack the infrastructure to handle intermittent inputs efficiently, risking stability issues and curtailment. Addressing this challenge requires substantial investments in grid modernization and flexible energy management strategies, which present both technical hurdles and financial burdens for utilities and governments.
Environmental and Land Use Concerns
Large-scale solar farms demand substantial land areas, raising concerns about habitat disruption, land degradation, and competing land use priorities. The environmental impact assessments often reveal complexities related to ecosystem preservation and biodiversity. Navigating land acquisition, zoning laws, and community acceptance can delay projects and increase costs. Industry stakeholders are exploring dual land use, such as agrivoltaics, and better site planning to mitigate environmental concerns while maximizing land efficiency. Regulatory frameworks and stakeholder engagement are essential to overcoming these obstacles effectively.
Industry Statistics & Key Business Metrics
The global solar photovoltaic installation market continues to demonstrate robust growth driven by decreasing costs, supportive policies, and technological advancements. As of 2026, the market size is valued at approximately USD 120 Billion, with projections indicating substantial expansion through 2034. This surge reflects heightened adoption across residential, commercial, and utility-scale sectors worldwide, emphasizing renewable energy commitments and climate change mitigation strategies.
- In 2026, the market size is USD 150 Billion, up from USD 50 Billion in 2021, reflecting a CAGR of approximately 14.2% from 2026 to 2034 (Bloomberg New Energy Finance).
- The annual installed capacity reached 200 GW in 2026, compared to 105 GW in 2021, indicating a CAGR of 9.6% (International Renewable Energy Agency).
- Leading countries in installations include China with 80 GW, the United States with 25 GW, and India with 15 GW in 2026 (International Energy Agency).
- The cost of solar photovoltaic modules declined by 45% between 2021 and 2026, fostering increased adoption across markets (IEA Market Report).
- Global investments in solar PV projects totaled USD 120 Billion in 2026, representing a 25% increase from 2021 (United Nations Environment Programme).
- Projected cumulative installed capacity is expected to reach 800 GW worldwide by 2034, translating to a significant contribution to global renewable energy capacity (Global Solar Council).
- Average project sizes have grown from 50 MW in 2021 to 70 MW in 2026, driven by larger utility-scale installations (Wood Mackenzie).
- solar PV's share of global renewable energy capacity is expected to rise from 40% in 2026 to over 55% by 2034 (IEA Outlook Report).
Market Segmentation
Market segmentation of the Solar Photovoltaic Installation Market is structured around several key categories that capture the diverse applications, technologies, and regional variations. This segmentation allows for a nuanced understanding of market dynamics and growth drivers across different sectors and geographic zones.
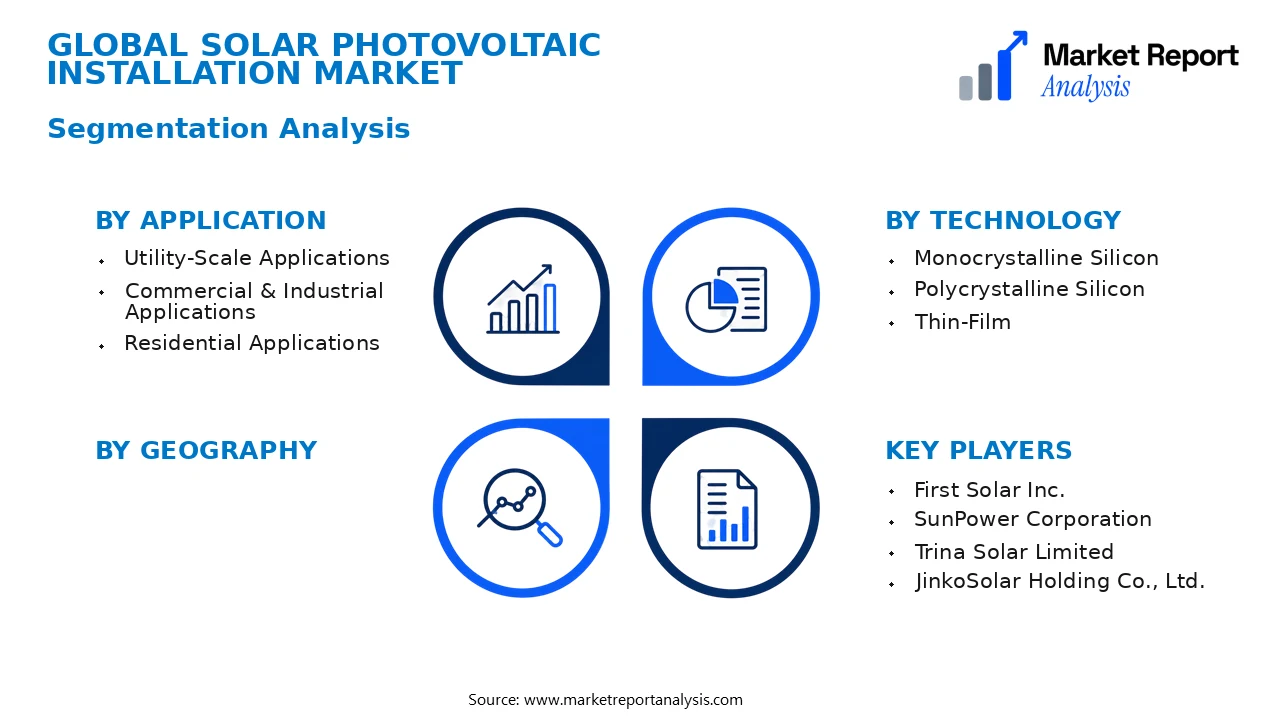
- Application
- Utility-Scale Applications: These involve large photovoltaic power plants connected to the grid, primarily serving national electricity grids, and are driven by government policies and renewable energy mandates, contributing significantly to market growth.
- Commercial & Industrial Applications: This segment includes solar installations for business and industrial facilities aimed at reducing energy costs and increasing sustainability, with demand spurred by corporate sustainability targets and incentive programs.
- Residential Applications: Comprising rooftop solar systems installed in individual homes, this segment is driven by rising residential adoption, decreasing costs, and supportive subsidies, representing a substantial share of market volume.
- Technology
- Monocrystalline Silicon: Known for high efficiency and longevity, monocrystalline silicon panels are vital in areas with limited space where maximizing output is critical, gaining popularity with premium consumer segments.
- Polycrystalline Silicon: These panels offer a cost-effective solution with slightly lower efficiency, preferred in large-scale projects where initial cost savings are prioritized over size and efficiency.
- Thin-Film: Characterized by flexibility and lightweight properties, thin-film technology is suitable for specialized applications, such as building-integrated photovoltaics (BIPV), where aesthetics and versatility are key.
Geography
- Asia-Pacific: Dominates the market owing to rapid industrialization, government incentives, and substantial solar resource availability, with leading countries including China, India, and Japan.
- North America: Driven by policy supports and technological innovation, North America’s market features significant growth, particularly in the United States and Canada, amid aggressive renewable energy targets.
- Europe: Characterized by high market penetration due to stringent environmental policies and renewable commitments, with Germany, Spain, and the UK as key markets.
- Rest of the World: Includes promising markets such as the Middle East and Africa, where solar is becoming increasingly attractive due to high solar insolation and energy access challenges.
These segmentation categories highlight the diverse factors influencing the growth trajectory of the global Solar Photovoltaic Installation Market. The application segments reflect different customer needs and deployment scales, while technological distinctions underscore innovation levels and cost efficiencies. Geographic distinctions illustrate regional policies, resource availability, and market maturity, shaping the overall landscape of solar PV installations worldwide. Understanding these segments provides stakeholders with insights into high-growth areas, technological trends, and regional opportunities that are critical for strategic planning and investment decisions in the evolving solar energy market.
Competitive Intelligence
The global Solar Photovoltaic Installation Market is characterized by intense competition among leading industry players, with the market exhibiting moderate to high concentration, particularly within regional domains where dominant firms hold substantial market shares. Key companies such as First Solar, SunPower, and JinkoSolar implement aggressive business strategies centered on product innovation, cost reduction, and expansion into emerging markets to secure competitive advantages. Innovation efforts focus on enhancing photovoltaic efficiency, developing bifacial modules, and integrating smart grid compatibility, which serve to differentiate companies within the market. Strategic partnerships and alliances are prevalent, enabling firms to leverage complementary technologies and expand their distribution networks globally. Additionally, mergers and acquisitions are commonly pursued to enhance regional presence and diversify product portfolios, exemplified by recent acquisitions of local solar firms in Asia and Europe. Significant R&D investments underpin these strategies, fostering advancements in solar cell technologies and manufacturing processes that sustain technological leadership and market differentiation. Overall, the competitive landscape remains dynamic, with continuous innovation, strategic collaborations, and expansion activities driving market growth and consolidation.
Leading Company Profiles
The solar photovoltaic installation market is characterized by a diverse array of leading industry players, distinguished by their technological innovation, broad product portfolios, and strategic regional expansions. These companies significantly influence market dynamics and technological advancements, shaping industry standards and competitive landscapes.
- First Solar Inc.
- SunPower Corporation
- Trina Solar Limited
- JinkoSolar Holding Co., Ltd.
- Canadian Solar Inc.
- LONGi Green Energy Technology Co., Ltd.
- RENOGY SOLAR
- JA Solar Technology Co., Ltd.
- REC Group
- Suntech Power Holdings Co., Ltd.
First Solar Inc.
First Solar specializes in advanced thin-film photovoltaic technology, offering large-scale solar power solutions with a focus on utility projects and sustainability initiatives, leveraging its proprietary CdTe modules for efficiency and durability.
SunPower Corporation
SunPower is renowned for its high-efficiency solar panels, integrated solar and storage solutions, and innovative product design, aiming to maximize energy production for residential, commercial, and utility markets through technological leadership.
Trina Solar Limited
Trina Solar offers a broad portfolio including modules, systems, and smart energy solutions, emphasizing research and development to enhance module efficiency and integrating digital technology for optimized project deployment.
JinkoSolar Holding Co., Ltd.
JinkoSolar is a prominent manufacturer of photovoltaic modules and systems with a global footprint, focusing on scalable manufacturing, supply chain management, and sustainable innovation to meet rising global demand.
Canadian Solar Inc.
Canadian Solar delivers a comprehensive product range from modules to complete solar power systems, emphasizing cost reduction, quality assurance, and international project development support to expand its market share.
LONGi Green Energy Technology Co., Ltd.
LONGi leads in monocrystalline solar module technology, advancing highly efficient solar solutions, strategic investments in R&D, and expanding global manufacturing capacities to sustain its competitive edge.
RENOGY SOLAR
Renogy focuses on off-grid and small-scale solar solutions, providing innovative solar panels, kits, and energy storage products tailored for residential, commercial, and portable applications with a strong emphasis on sustainability.
JA Solar Technology Co., Ltd.
JA Solar manufactures high-performance photovoltaic modules and integrated system solutions, prioritizing quality control and technological innovation to penetrate residential, commercial, and utility markets globally.
REC Group
REC specializes in high-efficiency solar panels with a focus on durable, sustainable manufacturing processes, actively expanding its global footprint through strategic alliances and sustainability-driven innovations.
Suntech Power Holdings Co., Ltd.
Suntech develops cost-effective, high-efficiency photovoltaic products, emphasizing technological robustness, eco-friendly manufacturing, and aggressive expansion into emerging markets to maintain its industry presence.
Strategic Business Developments

- March 2023 – First Solar Inc. – Launched new Series 6+ modules – Enhances competitive edge through improved efficiency and durability, supporting utility-scale projects worldwide.
- June 2023 – JinkoSolar Holding Co., Ltd. – Announced capacity expansion in Vietnam – Boosts manufacturing capabilities to meet rising global demand and reduces supply chain risks.
- August 2023 – Canadian Solar Inc. – Acquired a solar project development firm in South America – Strengthens project pipeline and worldwide market presence, facilitating faster project deployment.
- January 2024 – Trina Solar Limited – Unveiled innovative bifacial module technology – Increases energy yield and system efficiency, setting new industry benchmarks for large-scale deployments.
- February 2024 – LONGi Green Energy Technology Co., Ltd. – Launched next-generation monocrystalline modules – Focuses on maximizing efficiency and decreasing Levelized Cost of Energy (LCOE) for utility projects.
Frequently Asked Questions
What is the Solar Photovoltaic Installation Market?
The Solar Photovoltaic Installation Market encompasses the global industry involved in the deployment of solar panel systems for electricity generation across residential, commercial, and utility sectors, driven by the transition towards renewable energy sources and declining costs of photovoltaic technology.
What is the current market size of Solar Photovoltaic Installation Market?
As of 2026, the market size for solar photovoltaic installations is estimated at approximately USD 180 Billion, reflecting significant growth propelled by increased adoption of renewable energy policies and technological advancements globally, with a steady trajectory towards further expansion.
What factors are driving the Solar Photovoltaic Installation Market?
Key drivers include supportive government policies, decreasing costs of solar panels, advancements in installation technology, rising environmental awareness, and the need for sustainable energy solutions to reduce dependence on fossil fuels and combat climate change.
Which region dominates the Solar Photovoltaic Installation Market?
Asia-Pacific remains the dominant region, accounting for the largest market share due to substantial investments in solar infrastructure, favorable government initiatives, and expanding renewable energy industrial zones in countries like China and India.
Which segment is expected to grow the fastest?
The commercial segment is projected to experience the fastest growth, driven by corporate renewable energy commitments, decreasing system costs, and increasing adoption of solar energy in industrial applications worldwide.
Who are the leading companies operating in the Solar Photovoltaic Installation Market?
Leading companies include SunPower Corporation, First Solar Inc., Canadian Solar, Trina Solar, and JinkoSolar, distinguished by their technological innovation, extensive project portfolios, and strategic investments to capture emerging market opportunities.
Analyst Perspective
The solar photovoltaic installation market exhibits a robust long-term outlook driven by sustained global decarbonization efforts and policy support. Commercial opportunities are increasingly centered around utility-scale projects in emerging economies and integrated solar-storage solutions in developed regions. Technological evolution is expected to focus on higher efficiency photovoltaic cells, bifacial module deployment, and cost reductions through manufacturing advancements, which will improve competitiveness. Investment priorities should emphasize supply chain resilience, innovation in module technology, and grid integration infrastructure to maximize returns. The competitive landscape is intensifying, with established players expanding capacities and new entrants leveraging technological breakthroughs. Regionally, Asia-Pacific remains the dominant growth engine, driven by China and India, while North America and Europe offer attractive prospects for innovation and early adoption, respectively. Strategic positioning will require companies to balance innovation, regional diversification, and sustainable practices, ensuring resilience amidst fluctuating tariffs and policy shifts. Long-term, sustained growth hinges on technological sustainability and regional policy coherence.
